
 Africa Tobacco Products Market | 2026-2036
Africa Tobacco Products Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Tobacco Products Market Intelligence
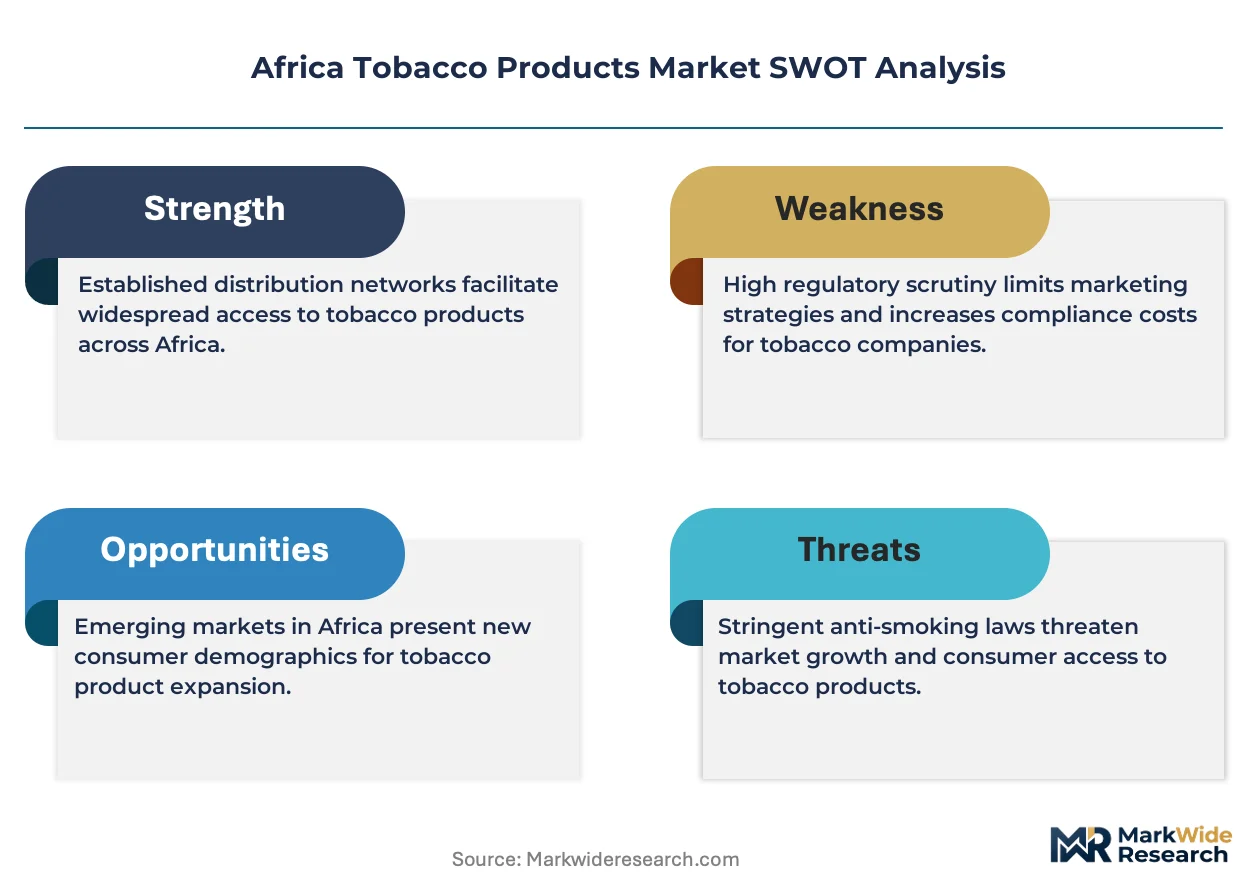
Egypt is narrowing its import dependency through expanded local cigarette manufacturing capacity. British American Tobacco leverages integrated leaf-processing operations across multiple African markets to sustain cost advantages. Philip Morris International anchors its regional presence through heated-tobacco product diversification. Imperial Brands competes aggressively in value-tier cigarette positioning.
Africa tobacco products encompass nicotine-delivery goods manufactured from cured leaf, including combustible cigarettes containing typically 8-20 mg tar and 0.5-1.5 mg nicotine per unit, plus non-combustible alternatives, serving recreational consumption and habitual use across retail and institutional channels. Cigarettes dominate volume throughput given entrenched consumer habits and accessible price points, while smokeless tobacco captures faster growth in select East African markets where oral traditions persist. Distribution through convenience stores and informal kiosks commands the deepest rural penetration, though online retail is gaining traction among urban demographics seeking discretion.
South Africa's National Treasury enforces escalating excise duties under tobacco control legislation, while Egypt's Ministry of Finance administers stamp-tax verification systems to combat illicit trade. Nigeria's National Agency for Food and Drug Administration and Control regulates product standards and advertising restrictions. Stakeholders must monitor evolving tax enforcement mechanisms and illicit supply interdiction efforts to calibrate pricing and channel strategies.
Market Dynamics
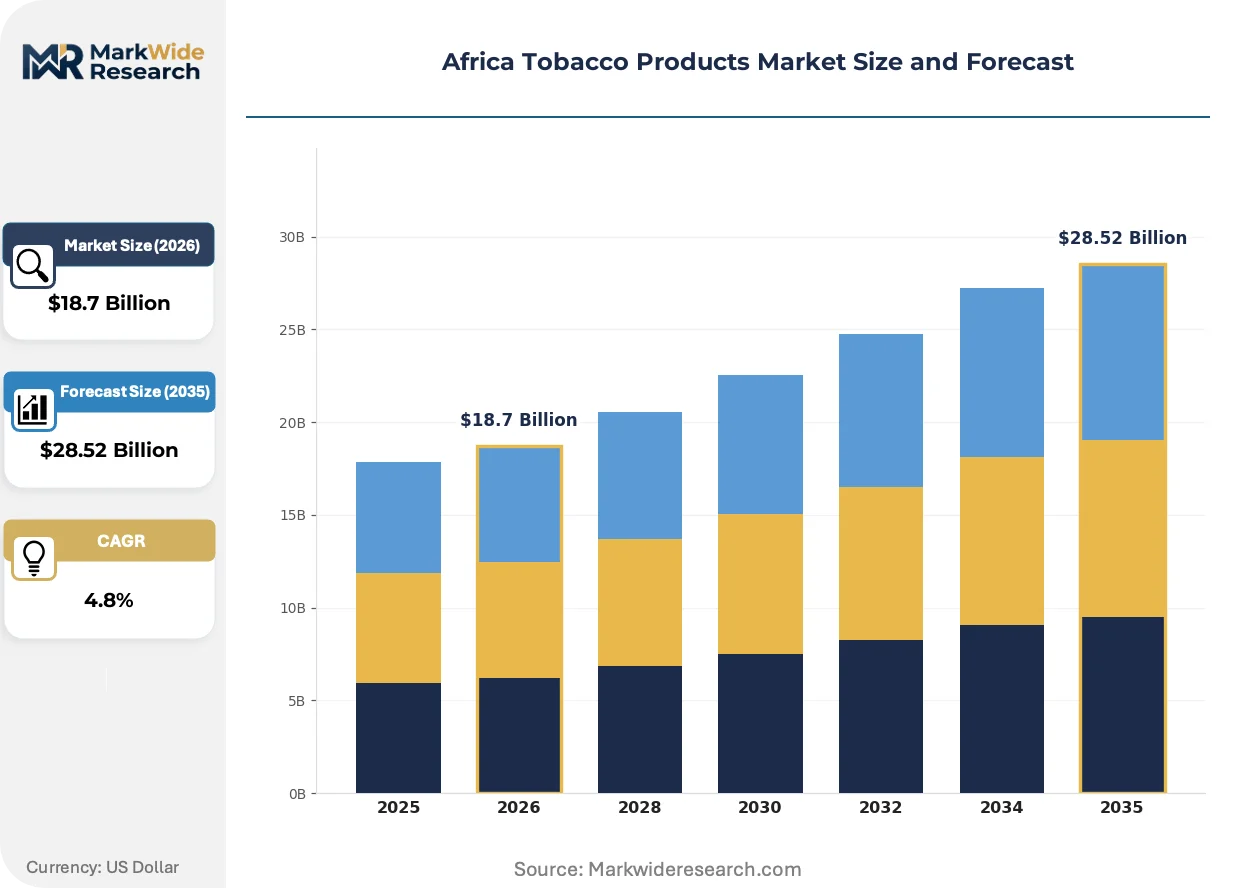
Escalating excise tax enforcement across Nigeria, Egypt, and South Africa is compressing legitimate volume while redirecting demand toward illicit channels, forcing manufacturers to recalibrate pricing architecture and distribution depth.
Growth Catalysts
- Urban young adult cohorts:Concentrated demand in Lagos, Cairo, and Johannesburg sustains volume throughput as disposable income rises among 18-35 year-old consumers.
- Oral tradition markets:Smokeless tobacco formats gain traction in Ethiopia, Kenya, and Uganda where chewing practices predate manufactured cigarette adoption.
- WHO FCTC implementation gaps:Inconsistent enforcement across member states creates regulatory arbitrage opportunities for compliant operators to expand market presence.
Market Restraints
- Leaf input cost volatility:Weather-driven fluctuations in Zimbabwe and Malawi tobacco harvests compress processor margins and destabilize supply commitments.
- Illicit trade penetration:Unstamped products from neighboring states undercut excise-compliant pricing in Egypt's Delta region and Nigeria's northern border zones.
- Advertising prohibition scope:South Africa's Tobacco Products Control Act bans point-of-sale display, eliminating traditional brand-building channels.
Strategic Opportunities
- Heated-tobacco product expansion:Reduced-risk device categories face lighter regulatory burden in Morocco and Algeria relative to combustible restrictions.
- Informal kiosk digitization:Mobile payment integration and inventory tracking systems upgrade traditional trade channel efficiency in Nigerian urban peripheries.
- Local manufacturing incentives:Egypt's industrial zone tax holidays reward domestic production capacity that substitutes previously imported finished goods.
Industry Challenges
- Excise stamp authentication:Nigeria's NAFDAC verification system demands serialization infrastructure investment that strains smaller distributor networks.
- Cross-border smuggling interdiction:Coordination failures between South African Revenue Service and neighboring customs authorities enable duty-evasion arbitrage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Tobacco Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cigarettes, Cigars, Roll-Your-Own, Smokeless Tobacco Customer Type: Retail Consumers, Wholesalers, Distributors, Duty-Free Shops Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Packaging Type: Cartons, Packs, Soft Packs, Tins |
| Companies Covered | Korea Tobacco & Ginseng Corporation, Imperial Brands, Philip Morris International, Scandinavian Tobacco Group, Swedish Match, British American Tobacco, ITC Limited, Eastern Company, Japan Tobacco, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Tobacco Products Market Strategic Shifts & Innovations
Product format diversification and channel digitization are restructuring how nicotine products reach African consumers, with regulatory technology and alternative delivery systems emerging as decisive competitive variables.
Heated-tobacco technology is hybridizing combustible and electronic nicotine delivery into single-device platforms that reduce tar exposure while maintaining ritual satisfaction. Urban professional segments in Cairo and Johannesburg are adopting these systems faster than rural smokers. This convergence is compressing the traditional cigarette value chain by merging manufacturing competencies previously separated between leaf processors and electronics assemblers.
South Africa's National Treasury escalates specific excise duties annually under tobacco control legislation, compressing manufacturer margins unless absorbed or passed through. The industrial consequence is accelerated trading down to value-tier brands and expanded informal channel penetration. Premium cigarette positioning faces the steepest volume erosion as price-sensitive consumers migrate to lower-duty alternatives.
Urban buyer segments are gravitating toward discreet purchase channels that minimize social visibility of tobacco transactions. E-commerce platforms and delivery applications in Lagos and Nairobi are displacing conventional retail for affluent demographics. Kenya's central business district exhibits the fastest channel shift, where smartphone penetration enables app-based ordering that circumvents physical retail exposure.
Africa Tobacco Products Market Segmentation
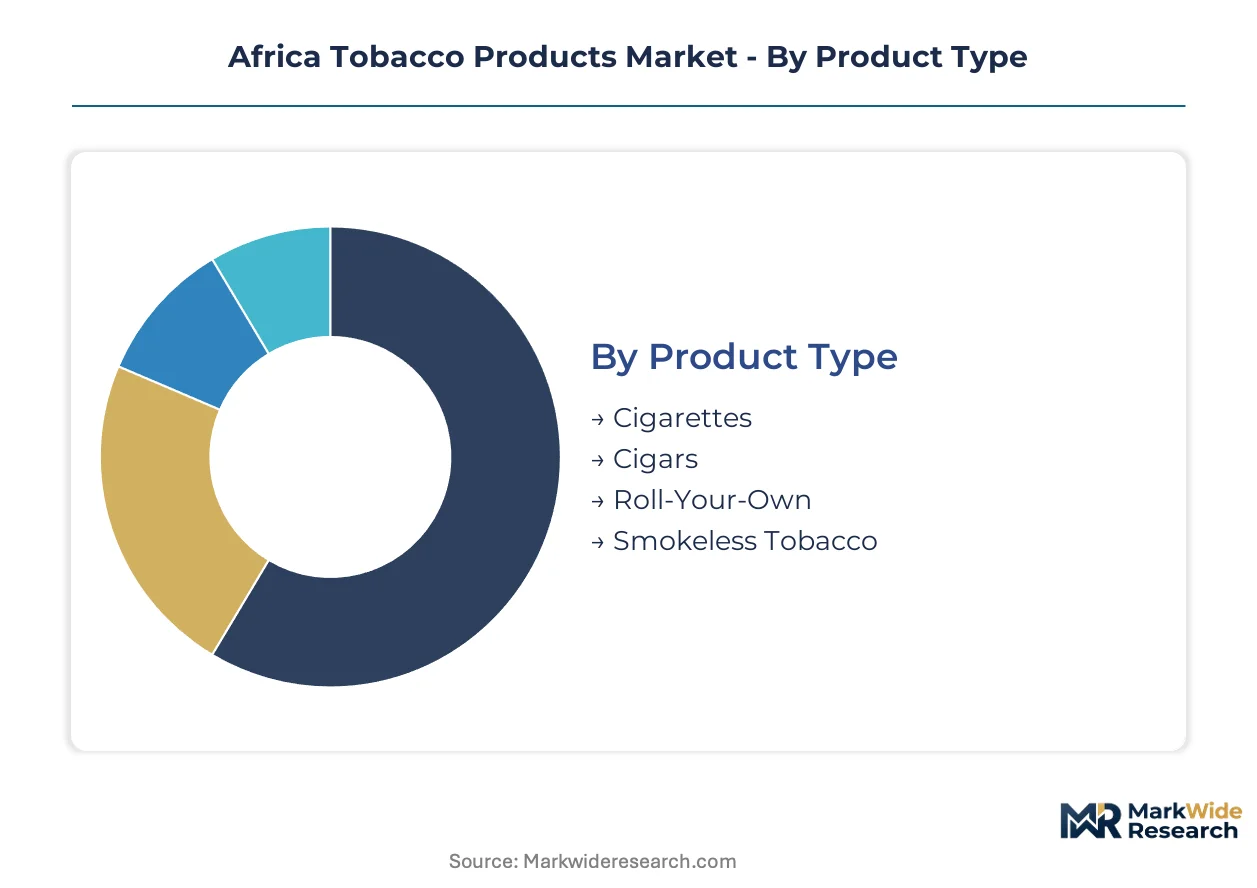
Segmentation reveals how nicotine delivery formats, procurement pathways, and retail formats split across divergent consumer rituals and regulatory exposure. Manufacturers calibrate portfolio depth and channel investment against these fracture lines.
Product Type:
After-sales intensity varies sharply across formats, with reduced-risk devices demanding technical support infrastructure absent from combustible categories.
- Cigarettes:Manufactured combustible sticks containing cured leaf blends with standardized tar and nicotine delivery profiles. Volume concentrates in Nigeria, Egypt, and South Africa where urban young adult cohorts sustain habitual consumption despite excise escalation.
- Smokeless Tobacco:Oral and nasal formats including snuff and chewing variants that bypass combustion. Kenya, Ethiopia, and Uganda exhibit concentrated demand where pre-industrial chewing traditions persist and indoor smoking restrictions bite hardest.
- Cigars:Premium hand-rolled and machine-made formats targeting ceremonial and affluent recreational use. South Africa's metropolitan elite and Egyptian leisure venues anchor demand.
- Roll-Your-Own:Loose leaf with paper and filter components for self-assembly. Price-sensitive consumers in Nigeria's northern states and South African townlands adopt this format to evade branded-pack excise incidence.
Cigarettes hold the largest share; momentum sits with smokeless tobacco as oral tradition markets expand manufacturing capacity.
Customer Type:
Cost tier stratification separates high-volume institutional buyers from fragmented retail procurement with divergent payment terms and compliance burdens.
- Retail Consumers:Individual end-users purchasing single units or small quantities through licensed and informal channels. Lagos, Cairo, and Johannesburg concentrate discretionary spending power among 18-35 year-old demographics.
- Wholesalers:Volume aggregators supplying downstream distributors with cartons and bulk formats. Nigeria's northern border zones and Egypt's Delta region exhibit highest wholesaler density amid illicit trade penetration.
- Distributors:Licensed operators managing excise-stamp verification and last-mile logistics to licensed retailers. South Africa's Revenue Service registration requirements strain smaller distributor networks.
- Duty-Free Shops:Airport and border retail exempt from domestic excise, targeting transient international travelers. Morocco and Algeria maintain highest duty-free throughput on trans-Mediterranean routes.
Retail consumers hold the largest share; momentum sits with distributors as NAFDAC and SARS serialization mandates professionalize logistics infrastructure.
Distribution Channel:
Geographic penetration depth separates urban-consolidated modern trade from rural-ubiquitous traditional formats with opposing capital intensity profiles.
- Convenience Stores:Small-format licensed retailers with extended hours serving neighborhood foot traffic. Nigeria's urban peripheries and South African townships depend on this channel for accessible price points.
- Supermarkets:Organized retail with standardized shelving and point-of-sale display restrictions. South Africa's Tobacco Products Control Act display bans compress brand visibility in this channel.
- Online Retail:E-commerce platforms and delivery applications enabling discreet transaction completion. Nairobi and Lagos exhibit steepest channel shift among affluent smartphone-enabled demographics.
- Specialty Shops:Dedicated tobacco retailers with premium assortment and consultation services. Cairo and Johannesburg concentrate this format for heated-tobacco and cigar categories.
Convenience stores hold the largest share; momentum sits with online retail as urban professionals prioritize transaction privacy.
Packaging Type:
Margin structure diverges between high-volume carton formats and premium unitary packaging with differentiated materials cost and branding surface area.
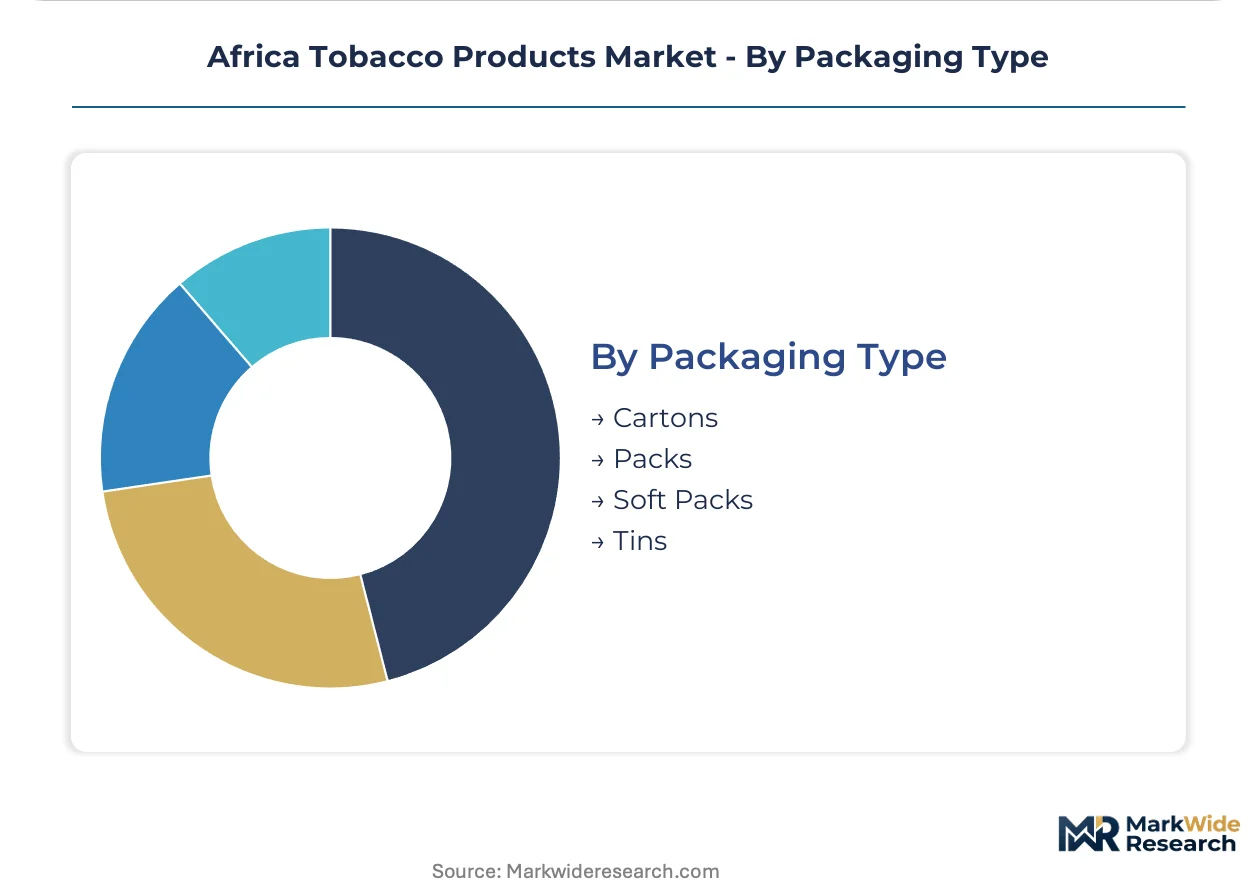
- Packs:Standard 20-unit rigid boxes with mandated health warnings and excise stamps. Universal adoption across all markets as the baseline transaction unit.
- Cartons:Aggregated 10-pack containers for volume purchasers and wholesale transfer. Preferred by Nigerian wholesalers and South African distributor networks for logistics efficiency.
- Soft Packs:Flexible paper-based packaging with lower materials cost and compressed shelf presence. Value-tier positioning in price-sensitive segments.
- Tins:Metal containers for smokeless tobacco and premium cigar preservation. Kenya and Uganda chewing-tobacco markets sustain tin demand for moisture retention.
Packs hold the largest share; momentum sits with cartons as distributor consolidation and excise-stamp batch verification favor aggregated formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
WHO FCTC implementation across Africa Tobacco Products Market member states varies sharply, with Nigeria's National Agency for Food and Drug Administration and Control, South Africa's National Treasury, and Egypt's Ministry of Finance anchoring divergent regulatory enforcement trajectories that reshape competitive positioning across sub-Saharan and North African consumption clusters.
Nigeria
Lagos and Abuja concentrate young adult demand among 18-35 year-old consumers with rising disposable income. NAFDAC enforces excise stamp verification systems that demand serialization infrastructure from distributor networks. Northern border zones exhibit elevated wholesaler density amid persistent illicit trade penetration from neighboring states.
South Africa
Johannesburg and Cape Town metropolitan areas sustain habitual consumption despite aggressive price escalation. The National Treasury escalates specific excise duties annually under tobacco control legislation, compressing manufacturer margins. Township convenience stores and informal kiosks command deepest rural penetration for accessible price points.
Egypt
Cairo anchors regional demand with concentrated urban professional adoption of heated-tobacco devices. The Ministry of Finance administers stamp-tax verification systems targeting Delta region illicit supply. Expanded local cigarette manufacturing capacity in industrial zones benefits from tax holidays that previously substituted imported finished goods.
Kenya
Nairobi exhibits the fastest channel shift toward e-commerce platforms among affluent smartphone-enabled demographics. Oral chewing traditions in rural regions sustain smokeless tobacco manufacturing expansion. The central business district concentrates app-based ordering that circumvents physical retail exposure.
Ethiopia
Addis Ababa and regional urban centers display concentrated demand for smokeless formats where pre-industrial chewing practices persist. Indoor smoking restrictions bite hardest in formal employment zones, redirecting consumption toward oral alternatives. Manufacturing capacity expansion targets East African regional supply integration.
Africa Tobacco Products Market Key Industry Players
Capability concentration sits with integrated multinationals commanding leaf-processing infrastructure; scale advantage sits with regional specialists exploiting regulatory arbitrage. The market structure consolidates around three tiers: global majors with captive supply chains, emerging-market champions with government partnerships, and local specialists with informal channel depth. Dominant competitive moves include portfolio diversification into reduced-risk devices and strategic partnerships with state-owned distribution networks.
Within the integrated multinational tier, British American Tobacco and Philip Morris International exemplify archetypes leveraging backward integration into leaf processing across multiple African markets. Imperial Brands occupies a position within the value-tier cigarette positioning archetype, while Japan Tobacco represents the geographic diversification specialist model. Korea Tobacco & Ginseng Corporation anchors the Asia-origin multinational seeking African market presence. These entities sit within a competitive matrix where regulatory compliance capability separates sustainable operators from those dependent on enforcement gaps.
| Leading Market Players |
|---|
| Korea Tobacco & Ginseng Corporation |
| Imperial Brands |
| Philip Morris International |
| Scandinavian Tobacco Group |
| Swedish Match |
| British American Tobacco |
| ITC Limited |
| Eastern Company |
| Japan Tobacco |
| Others |
Cost & Logistics Intelligence
The Beira Corridor freight route from Zimbabwe to Mozambique ports governs leaf export cost dynamics, concentrating supply power among processors with captive warehousing near Harare and Mutare while forcing downstream price stratification between excise-compliant and illicit channels.
Pricing Analysis
Price spreads between Lagos convenience stores and Cairo specialty retailers exceed threefold for equivalent cigarette formats, reflecting divergent excise incidence and distribution depth. Three-tier pricing structure across premium, standard, and economy levels separates British American Tobacco's aspirational positioning from Imperial Brands' value-tier penetration and local manufacturers' unbranded loose-leaf alternatives. Pricing pressure stems from South Africa's annual excise escalation under National Treasury mandates, compressing margins unless absorbed or passed through. Price-sensitive consumers in Nigerian northern states and South African townlands migrate toward roll-your-own formats and unstamped products, while affluent Cairo professionals absorb premium heated-tobacco device costs.
Supply Chain Analysis
Contract manufacturing concentration sits with British American Tobacco's integrated leaf-processing facilities across Nigeria, Kenya, and South Africa, supplemented by Philip Morris International's heated-tobacco assembly partnerships in Egypt's industrial zones. Geographic supply concentrates in Zimbabwe and Malawi for flue-cured Virginia leaf, with secondary sourcing from Tanzania and Zambia for burley varieties. Raw material dependencies rest on weather-driven harvest volumes, fertilizer input costs, and curing fuel availability. Supply chain risk centers on single-source vulnerability from Zimbabwe's concentrated flue-cured production, where drought cycles destabilize processor commitments. Distribution runs through NAFDAC-verified distributor networks in Nigeria, SARS-registered wholesalers in South Africa, and informal kiosk channels penetrating rural peripheries across all markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory enforcement intensity, channel digitization readiness, and oral tradition prevalence creates niche expansion opportunities for operators with targeted capability investments.
For Market Incumbents: Insulate excise-compliant volume by deepening backward integration into Zimbabwean leaf processing to offset harvest volatility, while deploying serialization infrastructure ahead of NAFDAC and SARS mandate expansion. Channel control through informal kiosk digitization in Nigerian urban peripheries defends against illicit trade erosion. Certification investment in WHO FCTC compliance protocols separates sustainable operators from enforcement-gap dependents.
For New Entrants and Emerging Players: Establish a beachhead in Kenya's smokeless tobacco manufacturing expansion, where oral chewing traditions sustain demand insulated from indoor smoking restrictions. The most penetrable segment sits in Ethiopia's regional supply integration for East African markets, with app-based distribution partnerships in Nairobi's central business district offering the sharpest go-to-market angle for affluent smartphone-enabled demographics.
For Investors and Strategic Acquirers: Regional specialists with government distribution partnerships and informal channel depth represent the priority acquisition archetype, given their regulatory arbitrage exploitation and last-mile penetration. Long-term viability hinges on reduced-risk device portfolio diversification and heated-tobacco technology licensing. The signal to watch is SARS-NAFDAC coordination on cross-border stamp verification, which would compress enforcement-gap dependent operators and consolidate volume toward compliant infrastructure holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Heated-Tobacco Product Expansion | Philip Morris International's device diversification in Cairo and Johannesburg captures urban professional adoption ahead of combustible restrictions. |
| Informal Kiosk Digitization | Mobile payment integration in Nigerian urban peripheries upgrades traditional trade efficiency against illicit channel competition. |
| Local Manufacturing Incentives | Egypt's industrial zone tax holidays reward domestic capacity that substitutes previously imported finished goods. |
| Excise Stamp Authentication Infrastructure | NAFDAC serialization mandates professionalize distributor networks and strain smaller non-compliant operators. |
| Smokeless Tobacco Capacity Buildout | Kenya and Ethiopia manufacturing expansion targets East African regional supply integration for oral tradition markets. |
Research Approach
A standing panel of brand managers at multinational tobacco processors, NAFDAC regulatory affairs officers, SARS excise enforcement leads, and convenience store chain procurement heads provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from WHO FCTC implementation reports, national customs and excise data, and SEC filings of listed tobacco multinationals. Bottom-up volume triangulation across product formats, customer types, and distribution channels converged with top-down macroeconomic anchoring.
Scenario-bracketing framed low, base, and high cases across excise enforcement intensity, illicit trade interdiction effectiveness, and heated-tobacco adoption velocity throughout the projection horizon. Segmentation dimensions modeled include product type, customer tier, distribution channel depth, and packaging format, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from trend extrapolation moderated by saturation thresholds and policy inflection points, with leaf input cost volatility and urban young adult income growth treated as key forecast inputs.
Stress conditions across Zimbabwean harvest failure, Nigeria-NAFDAC verification system rollout delays, and South African excise escalation beyond historical trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and consumer ritual persistence. Quarterly review of excise revenue collection data, illicit trade seizure reports, and heated-tobacco device import registrations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Homemade Cigars Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
North America E-Cigarette Market