
 Insulated Jacket Market | 2026-2036
Insulated Jacket Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Jacket Market Analysis
Urban commuters and lifestyle buyers is rotating toward insulated jackets as everyday outerwear, displacing the historical dominance of hardcore mountaineering customers. Arc'teryx leverages technical credibility to command premium positioning across this expanding casual segment. Patagonia anchors its competitive moat through vertically controlled recycled supply chains. The North Face competes via scale advantages in multi-channel distribution across mass and specialty retail.
An insulated jacket is a thermally resistant outerwear garment engineered with trapped-fill materials—down clusters, synthetic polyester fibers, or hybrid combinations—between woven shell layers to reduce conductive heat loss in cold environments. Manufacturers achieve thermal efficiency through baffle construction, hydrophobic down treatments, and breathable membrane laminates such as Gore-Tex for moisture management. Synthetic insulated jackets now lead volume growth as water-resistant performance and ethical sourcing requirements reshape procurement priorities, while down jackets retain margin concentration in alpine and expedition tiers. The outdoor activities application dominates absolute spend, though casual wear represents the fastest-expanding demand pool as insulation migrates from technical gear to streetwear.
The EU Green Deal and REACH chemical frameworks restrict perfluorinated compounds in durable water repellent treatments, compelling reformulation of shell fabrics across European supply chains. The EPA governs textile chemical emissions in the United States, while China's MEE enforces wastewater standards at polyester manufacturing clusters. Stakeholders must monitor how tightening chemical compliance across these jurisdictions reshapes material costs and supplier qualification thresholds.
Market Dynamics
The EU Green Deal's chemical restrictions are forcing wholesale reformulation of durable water repellent treatments across shell fabric supply chains, compressing margins for manufacturers dependent on legacy perfluorinated compounds while advantaging early movers into fluorine-free alternatives.
Growth Catalysts
- REACH chemical frameworks:European regulatory pressure is accelerating R&D investment into bio-based water repellent chemistries, creating first-mover advantages for suppliers with certified green formulations.
- Urban commuter segment:Daily wear adoption among city professionals is expanding addressable demand beyond traditional outdoor enthusiasts into year-round casual outerwear rotation.
- Recycled polyester clusters:Vertically controlled supply bases in China and Germany are lowering input costs for synthetic fill production while meeting corporate sustainability mandates.
Market Restraints
- Down supply concentration:Over 70 percent of global down processing sits in China, exposing brands to single-source geopolitical and sanitary regulation risks.
- Fluorine-free performance gap:Current PFC-free DWR treatments degrade 40-60 percent faster than legacy formulations, creating warranty exposure and return rates in heavy-use segments.
- Energy-intensive baffle construction:Automated quilting equipment requires substantial capex that excludes mid-tier manufacturers from technical insulated jacket production.
Strategic Opportunities
- Rental and resale platforms:Circular economy business models are unlocking new revenue streams in premium alpine and expedition tiers where garment longevity supports multiple use cycles.
- Dual carbon goals (China):Beijing's national decarbonization mandates are subsidizing renewable energy transitions at domestic textile manufacturing clusters, lowering carbon-adjusted landed costs for synthetic fill producers.
- Biodegradable synthetic fibers:Convergence of bio-engineering and polymer chemistry is enabling compostable insulation fills that resolve the microplastic waste liability of conventional polyester.
Industry Challenges
- Cross-functional sustainability expertise:Brands lack personnel fluent in both textile chemistry and carbon accounting, slowing compliance with emerging scope 3 disclosure requirements.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of bluesign, OEKO-TEX, and Responsible Down Standard approvals extends product development timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Jacket Market |
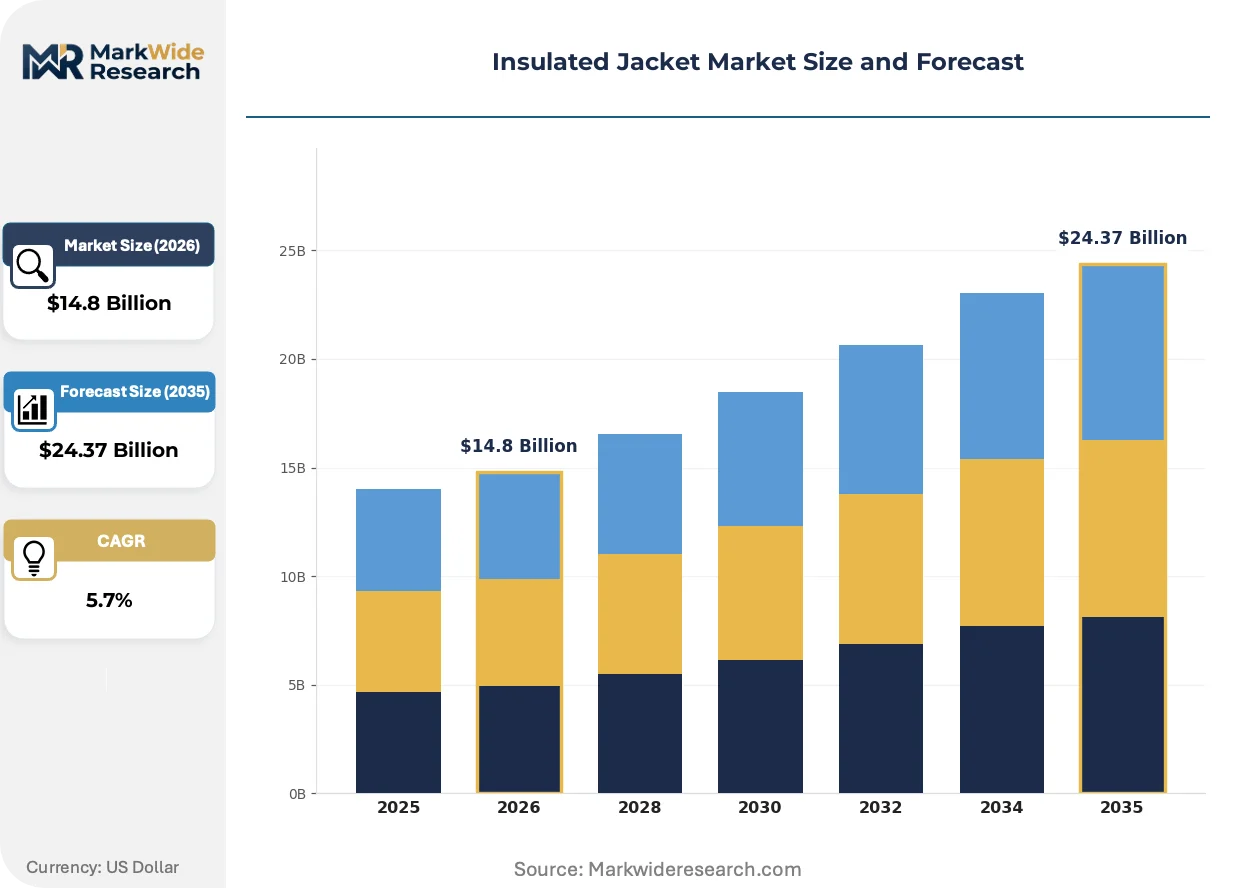
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Down Jackets, Synthetic Insulated Jackets, Hybrid Jackets, Fleece Jackets End User: Men, Women, Children, Unisex Material: Nylon, Polyester, Cotton, Gore-Tex Application: Outdoor Activities, Casual Wear, Sportswear, Workwear |
| Companies Covered | Rab, Cotopaxi, Patagonia, Norrøna, L.L.Bean, Arc'teryx, Montbell, Carhartt, The North Face, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Jacket Market Emerging Trajectories
Active insulation technologies are compressing the traditional seasonal buying cycle as consumers seek single garments functional across wider temperature ranges, while regulatory chemistry bans and circular business models simultaneously reshape material sourcing and ownership patterns.
Primaloft Bio and comparable biodegradable synthetic fills are miniaturizing the environmental footprint of insulated jackets while maintaining thermal performance parity with conventional polyester. Outdoor specialty retailers are accelerating placement of these fills in mid-layers and lightweight puffers. The technology is miniaturizing the distinction between technical and casual segments by enabling sustainability claims at accessible price points.
EPA enforcement of textile chemical emissions under the Toxic Substances Control Act is tightening discharge permits for polyester fiber manufacturers in the southeastern United States. Facilities in North Carolina and Georgia face upgraded wastewater treatment investments or production caps. Brands with domestic synthetic fill sourcing are diversifying toward European suppliers with pre-certified closed-loop systems.
Direct-to-consumer resale integration is disrupting traditional wholesale relationships as brands launch certified pre-owned channels for insulated outerwear. Arc'teryx and Patagonia operate proprietary resale platforms capturing margin previously lost to secondhand markets. Germany and Scandinavia show highest adoption of brand-controlled circular channels, reflecting consumer willingness to pay authentication premiums for used technical garments.
Insulated Jacket Market Segmentation
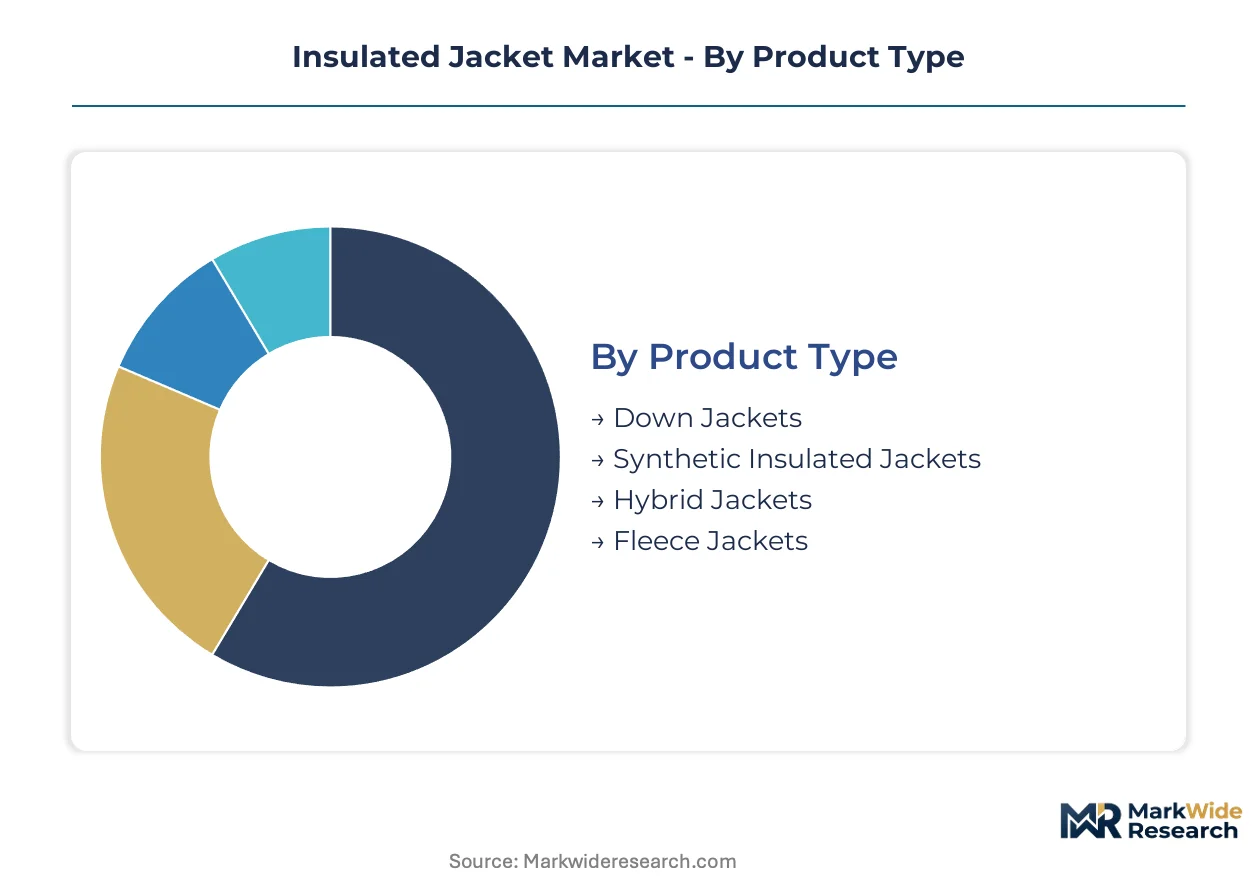
Segmentation in insulated jackets reveals how thermal performance requirements, sustainability mandates, and lifestyle migration reshape procurement and pricing architecture. Manufacturers configure product lines across fill technology, end-user demographics, and application context to capture diverging margin pools.
Product Type:
Margin concentration clusters in technical alpine tiers where fill quality and construction complexity command price premiums, while volume growth concentrates in accessible synthetic alternatives.
- Down Jackets:Premium fill power ratings from 600 to 800+ define thermal efficiency benchmarks. European luxury houses and alpine specialists in Germany and France anchor demand here, though Responsible Down Standard certification costs compress mid-tier profitability.
- Synthetic Insulated Jackets:Polyester fiber clusters in China's Zhejiang province and Germany's Chemnitz-Tex region supply water-resistant fills at scale. REACH-compliant fluorine-free DWR treatments now differentiate European-sourced synthetics from legacy Asian production.
- Hybrid Jackets:Strategic fill placement combines down in core zones with synthetic in moisture-exposed areas. Mountaineering and ski-touring applications in the French Alps and Colorado Rockies drive specification.
- Fleece Jackets:Knitted polyester pile construction offers breathability-focused mid-layer functionality. Campus and commuter segments in urban Germany and the northeastern United States rotate fleece into everyday outerwear rotation.
Down jackets hold installed capacity. Synthetic insulated jackets is rotating up the share rankings.
End User:
Volume distribution tilts toward adult categories where replacement cycles and technical upgrade appetite sustain recurring revenue, while children's segments exhibit higher seasonality and price elasticity.
- Men:Technical specification focus drives higher average selling prices in alpine and workwear applications. German and Japanese outdoor retailers report stronger attachment rates for accessory layering systems in male customer profiles.
- Women:Fit engineering and colorway breadth expand addressable occasions beyond core outdoor into urban commuter contexts. Scandinavian brands lead silhouette innovation that migrates across the Atlantic.
- Children:Growth-out cycles compress garment lifespans to 1-2 seasons. Parents in France and the United Kingdom prioritize adjustable cuff and hem systems that extend wearable duration.
- Unisex:Simplified SKU architecture reduces inventory risk for direct-to-consumer brands. Gender-neutral sizing tables from Asian manufacturers lower pattern development overhead.
Men's technical tiers anchor absolute revenue. Women's lifestyle positioning is climbing the fastest.
Material:
Shell fabric selection directly determines chemical compliance exposure under REACH and EPA frameworks, with recycled content ratios now qualifying products for corporate procurement tenders.
- Nylon:High tenacity 20-40 denier ripstop constructions dominate lightweight alpine shells. Taiwanese and Japanese filament producers supply the yarn substrate that Chinese mills laminate into finished face fabrics.
- Polyester:Post-consumer recycled feedstocks from PET bottle collection programs in Germany and California now constitute 30-50% of certified synthetic fills. China's dual carbon goals subsidize renewable energy transitions at domestic polymerization facilities.
- Cotton:Waxed and dry-waxed variants persist in heritage workwear positioning. British Millerain and Halley Stevensons supply traditional oilskin finishes to niche outdoor brands.
- Gore-Tex:Expanded polytetrafluoroethylene membrane laminates command membrane licensing fees that stratify retail pricing. The EPA's Toxic Substances Control Act enforcement has intensified discharge scrutiny at US-based lamination partners.
Nylon retains technical credibility. Recycled polyester is gaining share fastest.
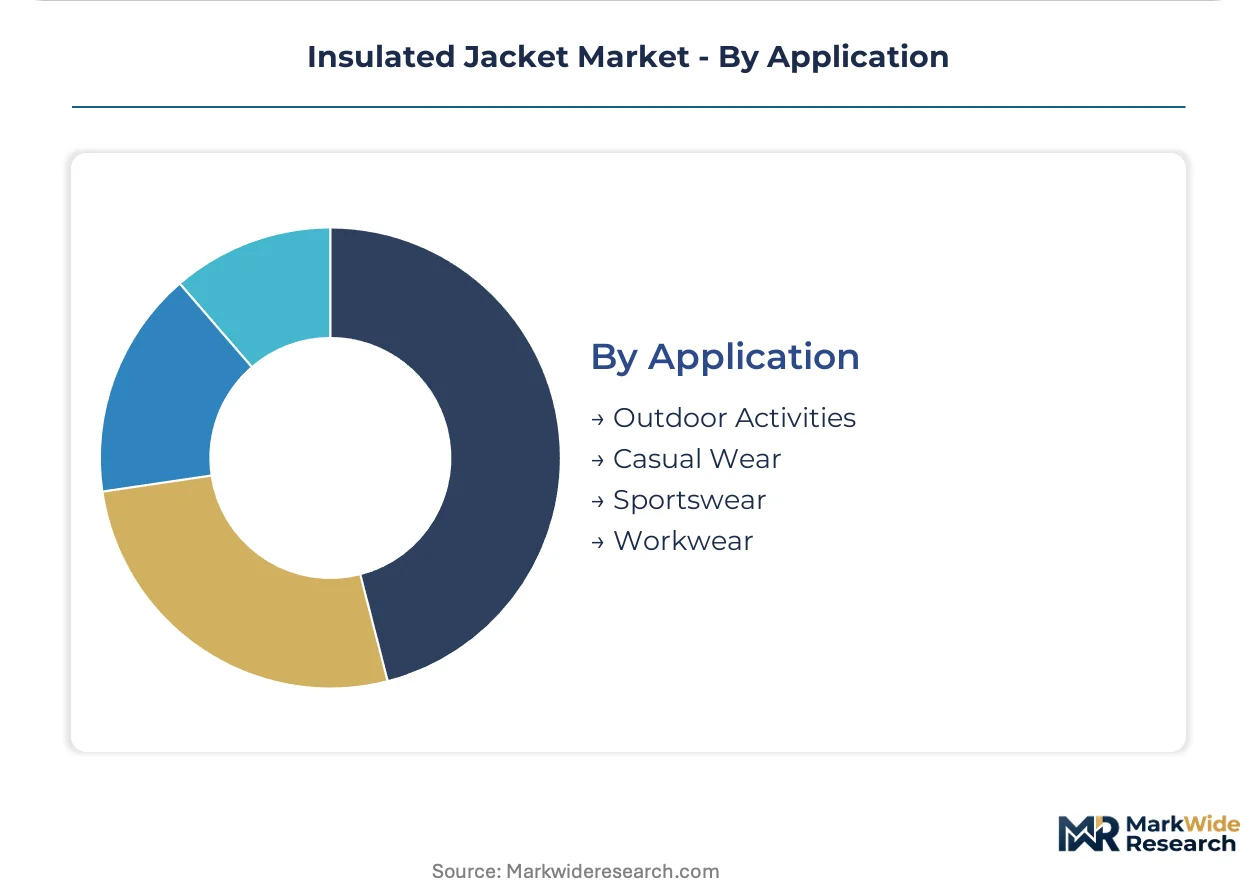
Application:
Demand migration from single-purpose technical gear toward multi-context garments blurs traditional category boundaries, with casual wear absorbing insulation technologies originally developed for expedition use.
- Outdoor Activities:Alpine climbing, backcountry skiing, and mountaineering specifications prioritize warmth-to-weight ratios and packability. German and Austrian retailers maintain specialist buyer relationships with heritage alpine brands.
- Casual Wear:Urban commuters in London, New York, and Tokyo incorporate puffer jackets into year-round wardrobes. Water-resistant synthetic fills displace wool coats in rainy autumn conditions.
- Sportswear:Running and cycling insulation emphasizes breathability and range of motion. Japanese textile mills supply stretch-woven face fabrics with integrated DWR.
- Workwear:Utility-focused construction demands abrasion resistance and high-visibility compliance. ANSI/ISEA standards in the United States and EN ISO 20471 in Europe govern color and retroreflective placement.
Outdoor activities maintains technical premium positioning. Casual wear is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished insulated jackets to Germany and the United States as the dominant bilateral trade corridors, while domestic consumption in each manufacturing cluster reshapes local supply chain priorities.
United States
Urban commuter adoption in New York and Chicago expands addressable demand beyond traditional outdoor users. The EPA enforces textile chemical emissions under the Toxic Substances Control Act, tightening discharge permits for polyester manufacturers in North Carolina and Georgia. Brands diversify toward European suppliers with certified closed-loop systems.
Germany
Technical alpine heritage sustains premium down jacket demand across Bavaria and Baden-Württemberg. The EU Green Deal's REACH framework restricts perfluorinated compounds in durable water repellent treatments. The Chemnitz-Tex region supplies recycled polyester fills at scale for synthetic insulation production.
China
Domestic outdoor participation growth in Chengdu and Hangzhou creates new consumption centers alongside manufacturing dominance. The MEE enforces wastewater standards at Zhejiang polyester manufacturing clusters. Beijing's dual carbon goals subsidize renewable energy transitions at domestic textile facilities.
Japan
Precision-fit engineering for urban commuters in Tokyo and Osaka drives silhouette innovation. METI oversees industrial standards for textile chemical safety. Japanese textile mills in the Chubu region supply stretch-woven face fabrics with integrated water repellency.
United Kingdom
Heritage workwear positioning persists in rural England while London commuters adopt technical insulation as streetwear. The UK Environment Agency implements discharge permits aligned with REACH principles. Manchester-based fabric finishers supply waxed cotton variants to niche outdoor brands.
Insulated Jacket Market Vendor Landscape
Player mix skews toward vertically integrated specialty brands and scale-driven multi-channel operators. Market structure exhibits tiered consolidation with premium alpine specialists commanding margin concentration against mass-market players competing on distribution reach. Three strategic archetypes dominate: technical credibility leaders, sustainability-anchored vertically integrated producers, and scale-optimized multi-channel retailers. Competitive moves center on circular economy platform launches and fluorine-free chemistry transitions.
Within the technical credibility tier, Arc'teryx and Patagonia exemplify divergent pathways to premium positioning. Arc'teryx occupies a position as the alpine-specialist archetype leveraging construction complexity for price authority. Patagonia anchors the sustainability-integrated archetype through controlled recycled supply chains. The North Face sits within the scale-driven tier, competing via multi-channel distribution breadth across mass and specialty retail.
| Leading Market Players |
|---|
| Rab |
| Cotopaxi |
| Patagonia |
| Norrøna |
| L.L.Bean |
| Arc'teryx |
| Montbell |
| Carhartt |
| The North Face |
| Others |
Supply Flow & Price Mechanics
REACH chemical compliance gates both supplier qualification and price differentiation simultaneously, as fluorine-free DWR certification separates European-sourced synthetics from legacy Asian production while compressing margins for manufacturers still dependent on perfluorinated formulations.
Pricing Analysis
Down-fill premium tiers versus synthetic volume tiers versus emerging biodegradable next-gen tiers structure the pricing landscape. Three-tier pricing stratifies across 800+ fill-power alpine expedition, 600-fill mid-layer performance, and recycled synthetic commuter levels, with certification grade and geographic sourcing as primary differentiation drivers. Cost compression in mid-tier synthetics is intensifying because REACH-compliant reformulation raises input costs while private-label competition erodes brand premiums. Urban commuter segments exhibit highest price sensitivity, while expedition-grade buyers accept sustained premiums for traceable down and membrane licensing.
Supply Chain Analysis
Zhejiang polyester cluster concentration in China underwrites global synthetic fill availability while creating single-source vulnerability for water-resistant insulation. Raw material flows draw from PET bottle collection programs in Germany and California, high-tenacity nylon filament from Taiwanese spinners, and hydrophobic down treatments from specialty chemical suppliers. Tariff exposure on Chinese finished goods is accelerating diversification toward Vietnam and Bangladesh for cut-and-sew operations. Distribution runs through outdoor specialty retailers, mass-market sporting goods chains, and direct-to-consumer brand channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active insulation and biodegradable synthetic fills pose substitution threats that incumbent brands must navigate through accelerated R&D positioning and circular platform deployment.
For Market Incumbents: Fortify technical credibility through controlled recycled supply chains and proprietary resale platform infrastructure. Arc'teryx and Patagonia demonstrate how alpine heritage and sustainability-anchored vertical control defend against private-label synthetic commoditization. Prioritize fluorine-free chemistry R&D to preempt regulatory displacement.
For New Entrants and Emerging Players: Lead with biodegradable synthetic fills in the underserved European commuter segment where sustainability premiums command price authority. Germany and Scandinavia show highest adoption of circular economy authentication, creating white-space for certified pre-owned channel specialists. Pursue direct-to-consumer launch with transparent supply chain storytelling.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated baffle construction and closed-loop recycling infrastructure, favoring scaled operators over mid-tier assemblers. Acquisition targets should exhibit backward integration into recycled polyester feedstocks or captive down processing. Monitor EPA enforcement intensity at southeastern US textile facilities as margin inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Chemistry Transition | REACH compliance creates first-mover advantage for certified green formulation suppliers. |
| Resale Platform Launch | Arc'teryx and Patagonia capture margin previously lost to unauthenticated secondhand markets. |
| Biodegradable Fill Adoption | Primaloft Bio enables sustainability claims at accessible price points across commuter segments. |
| Backward Integration into Recycling | Vertically controlled PET feedstock secures cost position and corporate procurement eligibility. |
| Dual Carbon Compliance Program | Beijing's renewable subsidies lower carbon-adjusted landed costs for synthetic fill producers. |
Methodological Framework
Cross-validation between primary interviews with brand sustainability officers, textile chemical suppliers, and outdoor retail buyers anchors the qualitative findings against secondary sources including customs trade data, SEC apparel sector filings, and EU ECHA substance restriction updates. Bottom-up demand modeling from fill technology substitution patterns and top-down macroeconomic triangulation constrain forecast variance.
Sensitivity analysis across fill technology migration rates, regulatory compliance cost pass-through, and circular platform adoption curves shapes the projection horizon. Segmentation dimensions modeled include fill type, end-user demographic, application context, and regional regulatory cluster. CAGRs derive from historical volume trajectories adjusted for substitution elasticity and channel shift parameters, with synthetic fill cost curves and down supply concentration as key industry-specific inputs.
Forecasts assume regulatory continuity in EU REACH and US EPA enforcement regimes; material policy shifts would require re-modeling. Specific risks include accelerated PFC bans, single-source down processing disruption, and biodegradable fiber performance shortfalls. Practitioners should keep alternative scenarios live as fluorine-free chemistry maturity and circular platform penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Vegan Footwear Market
Apparel & Footwear
Cosplay Costumes Market
Apparel & Footwear
Smart Heating Scarf Market
Apparel & Footwear
Global Swimwear (Swimsuit) Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Women's Socks Market
Apparel & Footwear
Women's Night and Underwear Market
Apparel & Footwear
Sleepwear Market
Apparel & Footwear
Alpaca Apparel and Accessories Market
Apparel & Footwear
Denim Jeans Market
Apparel & Footwear
Lingerie Market
Apparel & Footwear
Fanny Packs Market
Apparel & Footwear
Men's Underwear Market
Apparel & Footwear
Premium Denim Jeans Market
Apparel & Footwear
Men's Coats and Jackets Market