
 Liquor Flavored Cigars Market | 2026-2036
Liquor Flavored Cigars Market Size, Share, and Industry Trends Forecast 2026-2036
Liquor Flavored Cigars Market Foresight
Multi-source flavor ingredient procurement is shifting toward captive supply arrangements as manufacturers seek batch consistency and regulatory traceability. Davidoff of Geneva USA leverages its Swiss parent company's vertical infrastructure to secure aged barrel extracts for limited releases. General Cigar Company anchors North American distribution through controlled wholesale partnerships with licensed tobacco retailers. Scandinavian Tobacco Group competes across price tiers by operating parallel machine-made and hand-rolled production lines.
Liquor flavored cigars comprise tobacco leaf cores infused or cased with distilled spirit extracts—typically rum, whiskey, or cognac—then bound and wrapped in fermented leaf for combustion and aromatic delivery. The infusion process demands precise alcohol concentration control to prevent wrapper degradation while preserving volatile flavor compounds through the burn. Within flavor profiles, whiskey variants command the deepest consumer loyalty and highest repeat purchase rates, whereas rum expressions attract entry-level smokers through sweeter, more accessible palates. The cigar type dimension reveals a structural split: premium hand-rolled formats capture concentrated margin pools in specialty stores, while machine-made variants sustain volume throughput through convenience and supermarket channels.
The FDA Center for Tobacco Products enforces premarket authorization requirements under the deeming rule that classifies flavored cigars as regulated tobacco products subject to ingredient disclosure and marketing restrictions. State-level excise tax regimes in California and New York further compress retail pricing flexibility and shape regional demand patterns. The EU Tobacco Products Directive imposes combined health warning obligations and flavor descriptor limitations that constrain cross-border branding strategies. Stakeholders must monitor pending state legislation on flavored tobacco bans and calibrate portfolio exposure between premium artisan lines and mass-market formats accordingly.
Market Dynamics
The FDA's deeming rule over flavored tobacco products is compressing marketing pathways and forcing manufacturers to restructure product registration workflows around premarket authorization requirements. This regulatory pressure is concentrating competitive advantage among firms with established compliance infrastructure and captive supply networks.
Growth Catalysts
- Experiential retail expansion:Premium lounges in Miami, Las Vegas, and Nashville are driving curated tasting formats that command higher margins per unit than conventional retail channels.
- REACH compliance infrastructure:European manufacturers who invested early in ingredient traceability systems now face lower barrier costs for cross-border distribution under the EU Tobacco Products Directive.
- Barrel-aging extract technology:Controlled alcohol infusion processes that preserve volatile compounds through combustion are extending product shelf stability and reducing batch rejection rates.
Market Restraints
- Input cost volatility:Aged tobacco leaf prices fluctuate with weather patterns in the Dominican Republic and Nicaragua, squeezing margin predictability for hand-rolled formats.
- FDA premarket authorization timelines:The Center for Tobacco Products review backlog extends product launch windows by 18-24 months, freezing portfolio refresh cycles.
- Substitution by non-tobacco alternatives:Nicotine pouches and heated tobacco products are capturing trial smokers who previously entered through flavored cigar entry points.
Strategic Opportunities
- Underpenetrated German market:Cigar lounge culture remains concentrated in Hamburg and Berlin, leaving secondary cities like Munich and Cologne open for format experimentation.
- Direct-to-consumer subscription channels:Monthly curated deliveries bypass wholesale margin stacking and capture full retail-equivalent pricing from repeat buyers.
- CSRD-aligned sustainability reporting:Early adoption of supply chain carbon disclosure creates differentiation among ESG-mandated institutional buyers in Nordic markets.
Industry Challenges
- Master blender talent scarcity:The specialized skill of balancing spirit extracts with tobacco leaf aging profiles commands premium compensation and limits production scaling.
- Compliance documentation systems:FDA ingredient disclosure requirements demand reconfiguration of legacy batch tracking software that predates the deeming rule.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquor Flavored Cigars Market |
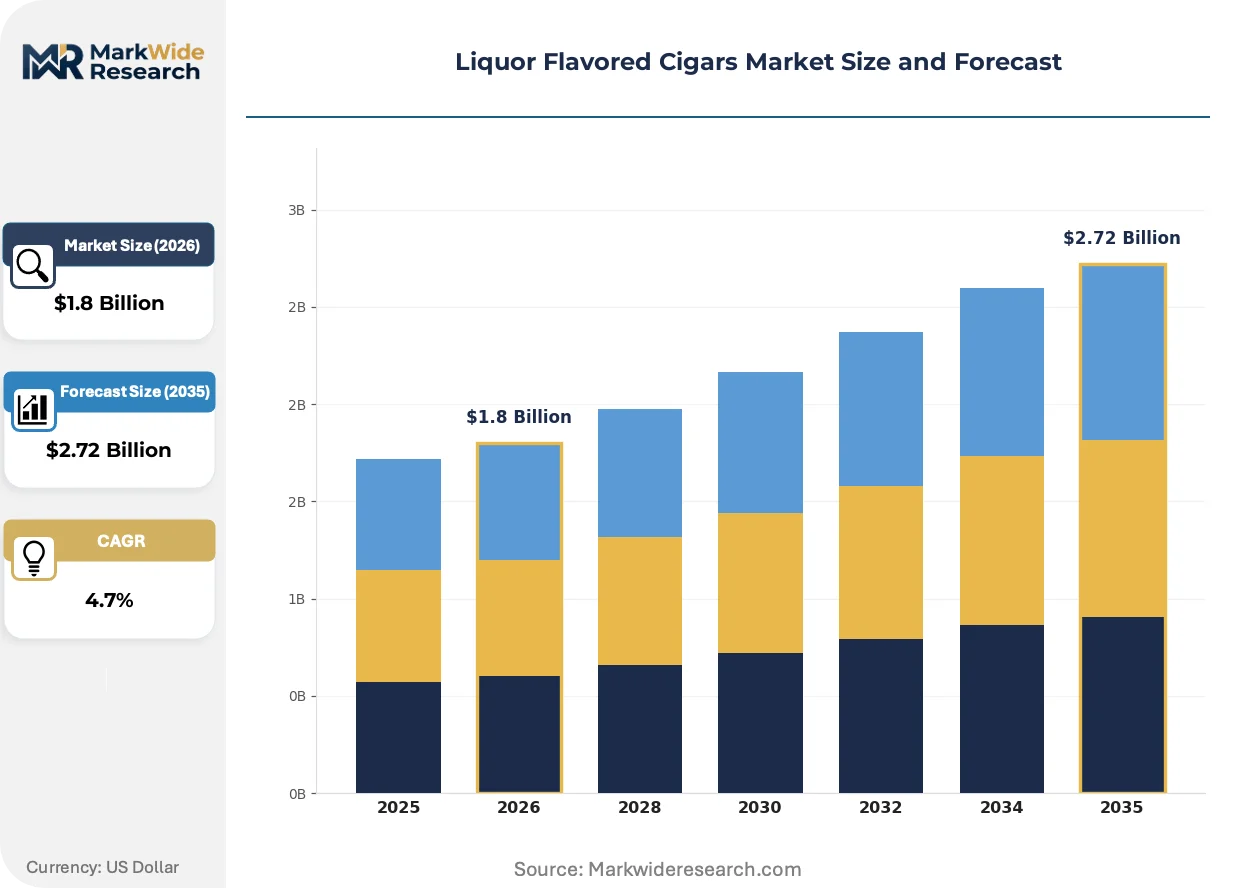
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Profile: Rum, Whiskey, Cognac, Vodka Cigar Type: Premium, Machine-Made, Hand-Rolled, Flavored Packaging Type: Boxes, Tins, Bundle Packs, Pouches Distribution Channel: Online, Supermarkets, Specialty Stores, Tobacco Shops |
| Companies Covered | Davidoff of Geneva USA, General Cigar Company, Altadis USA, Swisher International, Imperial Brands, Oettinger Davidoff AG, Rocky Patel Premium Cigars, Scandinavian Tobacco Group, Drew Estate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquor Flavored Cigars Market Shifts & Advancements
Flavor preservation technology and regulatory compliance automation are reshaping production economics. Manufacturers are reallocating capital toward controlled-environment aging facilities and traceability infrastructure.
Precision humidity-controlled infusion chambers are automating the casing process for spirit extract application. Premium hand-rolled manufacturers in the Dominican Republic are adopting these systems to reduce wrapper degradation rates. The technology is automating quality consistency that previously required manual intervention by master blenders.
The EU Tobacco Products Directive's combined health warning and flavor descriptor limitations are constraining cross-border branding strategies. Manufacturers must maintain parallel packaging inventories for member states with divergent enforcement interpretations. Small-batch artisan producers face disproportionate compliance cost burdens relative to volume scale.
Buyer concentration among experiential retail venues is shifting procurement toward exclusive allocation agreements. Specialty lounges in Texas and Florida are negotiating direct relationships with specific aging facilities, bypassing traditional wholesale distributors. This channel compression is most visible in metropolitan markets with established craft spirits crossover demographics.
Liquor Flavored Cigars Market Segmentation
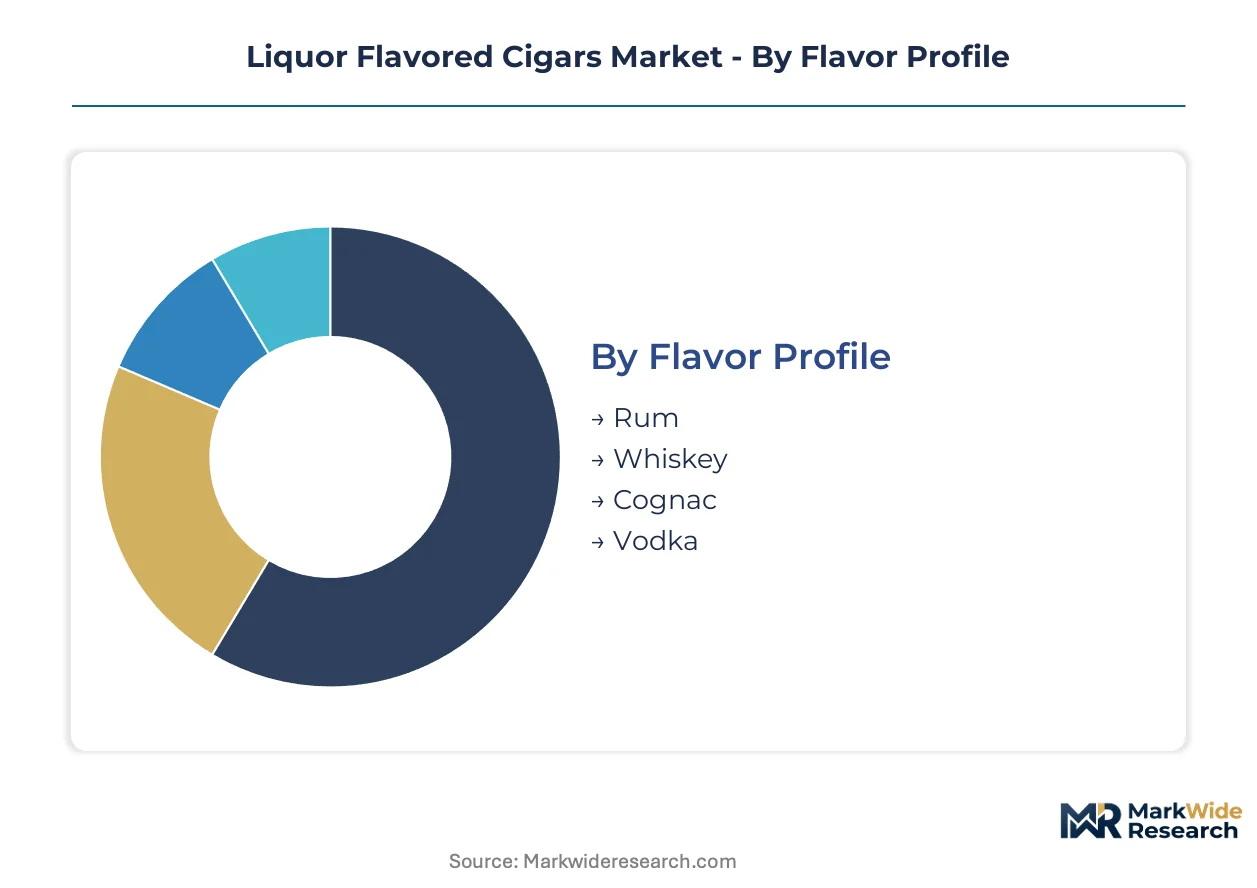
Segmentation in the liquor flavored cigars market reveals how consumer preferences, retail formats, and regulatory exposure create distinct commercial battlegrounds. Manufacturers must align production scale and compliance investment with the specific requirements of each segment cluster.
Flavor Profile:
Buyer differentiation in this category stems from palate sophistication and repeat purchase intensity rather than demographic splits.
- Whiskey:Aged barrel extracts from bourbon and scotch sources deliver the most complex volatile compound profiles. Demand concentrates in Texas, Tennessee, and Kentucky where craft spirits culture overlaps with premium cigar consumption; repeat purchase rates exceed other flavor categories due to perceived authenticity.
- Rum:Sweeter molasses-based extracts attract entry-level smokers through accessible palatability. Florida and Caribbean-influenced coastal markets drive volume; the segment faces substitution pressure from younger consumers migrating to nicotine pouches.
- Cognac:Grape-derived spirit infusions command boutique positioning in urban specialty stores. Limited production runs target collectors in New York and California.
- Vodka:Neutral spirit bases allow flavor-forward casing without competing aromatic signatures. Convenience channel placements in Midwestern states sustain modest throughput.
Whiskey leads volumes today; rum is gaining share fastest among first-time buyers.
Cigar Type:
Cost tier separation determines manufacturing location, labor intensity, and margin structure across this dimension.
- Premium:Hand-rolled formats using long-filler tobacco and extended barrel-aging protocols. Miami, Las Vegas, and Nashville lounges drive allocation scarcity; FDA premarket authorization costs per SKU favor producers with compliance infrastructure.
- Machine-Made:High-throughput production using homogenized tobacco leaf and automated casing application. Supermarket and convenience channels in Florida and Texas sustain volume; excise tax compression in California and New York squeezes pricing flexibility.
- Hand-Rolled:Artisan production in Dominican Republic and Nicaraguan facilities with master blender oversight. Specialty store distribution commands wholesale premiums.
- Flavored:Category descriptor for regulatory classification rather than distinct production method. Cross-segment labeling requirements under FDA deeming rule impose documentation burdens.
Machine-made formats dominate unit volumes; premium hand-rolled segments exhibit the steepest expansion trajectory in revenue terms.
Packaging Type:
Volume scale and retail channel destination dictate material selection and unit economics in this category.
- Boxes:Rigid paperboard constructions with humidity control inserts for premium preservation. Specialty lounges in Texas and Florida negotiate exclusive allocation agreements using box-format presentation.
- Tins:Metal containers with gasket seals extending shelf stability in variable climates. Convenience channel placement in Gulf Coast states favors this format.
- Bundle Packs:Cellophane-wrapped collections reducing per-unit packaging cost for price-sensitive segments. Machine-made product lines utilize this format for supermarket distribution.
- Pouches:Flexible laminate structures for single-serve or trial-size offerings. Online subscription channels adopt pouches for shipping efficiency.
Boxes lead revenue contribution today; pouches are climbing the fastest through direct-to-consumer channels.
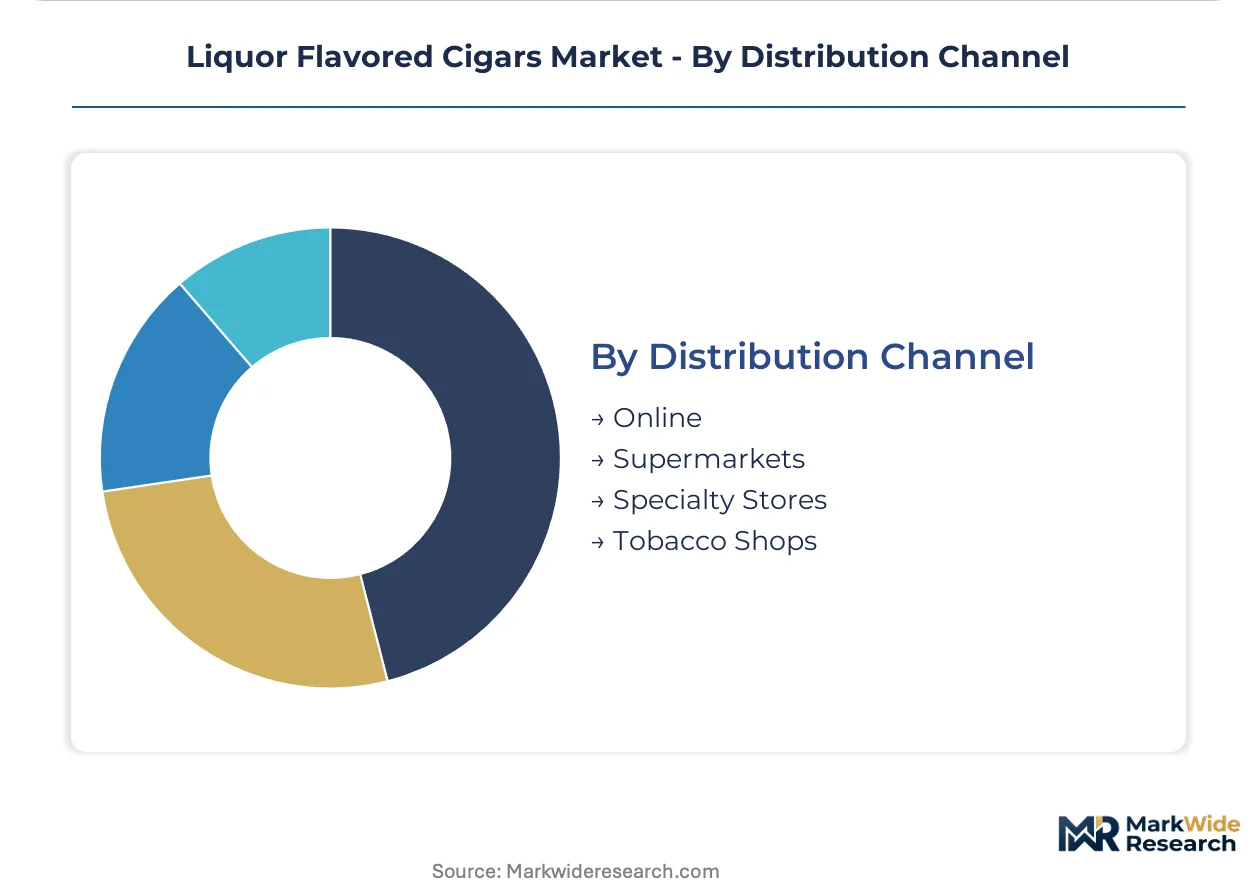
Distribution Channel:
Customer acquisition cost and regulatory exposure vary sharply across procurement pathways in this dimension.
- Specialty Stores:Licensed tobacco retailers with humidor infrastructure and staff expertise. Curated tasting experiences in Nashville and Miami command full retail-equivalent pricing without wholesale margin stacking.
- Online:Direct-to-consumer platforms bypassing geographic restrictions on flavored tobacco retail. Subscription models capture repeat buyer data for allocation forecasting.
- Tobacco Shops:Traditional outlets with established regulatory compliance and age verification systems. State-level licensing requirements create barrier advantages for incumbent operators.
- Supermarkets:Mass-market placement for machine-made variants with high inventory turnover. California and New York excise tax regimes compress profitability in this channel.
Specialty stores lead margin generation today; online channels are expanding most quickly as lounge culture digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the deepest craft spirits crossover culture and premium lounge infrastructure. Regulatory divergence across state and federal jurisdictions is fragmenting distribution economics and forcing manufacturers to maintain parallel compliance systems.
United States
Texas and Florida drive volume through experiential retail venues in Dallas, Houston, and Miami. The FDA Center for Tobacco Products enforces premarket authorization requirements that extend product launch windows. Nashville's emerging lounge cluster commands allocation scarcity for barrel-aged whiskey variants.
Germany
Hamburg and Berlin anchor cigar lounge culture while Munich and Cologne remain underpenetrated for format experimentation. REACH compliance infrastructure reduces barrier costs for cross-border distribution under the EU Tobacco Products Directive. Bavarian specialty retailers are negotiating direct allocation agreements with Dominican aging facilities.
Dominican Republic
Santiago and La Romana host the primary hand-rolled production infrastructure for premium formats. Master blender talent scarcity limits production scaling despite sustained demand from US and European buyers. Precision humidity-controlled infusion chambers are automating casing processes in aging facilities.
United Kingdom
London's specialty retailers command wholesale premiums for cognac-infused boutique lines. The UK tobacco excise regime compresses pricing flexibility for machine-made variants. Scottish urban markets show emerging crossover potential with whiskey culture.
Switzerland
Geneva-based vertical infrastructure secures aged barrel extracts for limited releases distributed across European markets. Swissmedic oversight applies to nicotine-containing products, creating regulatory clarity for adjacent categories. Basel's logistics cluster supports cross-border distribution to German and French markets.
Liquor Flavored Cigars Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription channels and experiential retail partnerships. The competitive terrain separates into compliance-heavy premium hand-rolled specialists and volume-focused machine-made operators with supermarket penetration. Three archetypes dominate: vertically integrated Swiss-parented operations with captive supply networks, North American distributors controlling wholesale partnerships with licensed retailers, and Scandinavian groups operating parallel production lines across price tiers. Dominant competitive moves include backward integration into barrel-aging extract technology and geographic expansion into underpenetrated German secondary cities.
Within the premium-tier vector, Davidoff of Geneva USA exemplifies Swiss-parented vertical integration, while General Cigar Company anchors North American distribution architecture. Scandinavian Tobacco Group occupies a position spanning machine-made volume and hand-rolled margin pools. Rocky Patel Premium Cigars and Drew Estate represent boutique specialists competing on master blender reputation and limited-release scarcity. Altadis USA and Swisher International sit within the mass-market machine-made tier with convenience channel dominance. Imperial Brands and Oettinger Davidoff AG exemplify diversified tobacco conglomerates with multi-category portfolio exposure.
| Leading Market Players |
|---|
| Davidoff of Geneva USA |
| General Cigar Company |
| Altadis USA |
| Swisher International |
| Imperial Brands |
| Oettinger Davidoff AG |
| Rocky Patel Premium Cigars |
| Scandinavian Tobacco Group |
| Drew Estate |
| Others |
Supply & Pricing Matrix
Swiss-parented conglomerates with captive barrel-aging infrastructure command asymmetric pricing power through in-house extract production, insulating premium tiers from commodity leaf volatility while machine-made operators absorb excise tax compression through volume throughput. This ownership pattern concentrates margin capture in vertically integrated hands and forces independent producers toward defensive wholesale partnerships.
Pricing Analysis
Input-cost pass-through from aged Dominican and Nicaraguan tobacco leaf flows unevenly across product tiers, with premium hand-rolled formats absorbing volatility through scarcity pricing while machine-made variants face compression from California and New York excise regimes. Three-tier pricing structure across premium, standard, and economy levels separates lounge-exclusive allocations from supermarket convenience placements. Pricing pressure stems from FDA premarket authorization cost burdens that freeze SKU refresh cycles. Boutique collectors exhibit lowest price sensitivity; entry-level rum segment buyers show highest elasticity to per-unit increases.
Supply Chain Analysis
Direct-to-lounge channels in Miami, Las Vegas, and Nashville handle hyperscale experiential demand through exclusive allocation agreements that bypass traditional wholesale margin stacking. Geographic concentration centers on Dominican Republic and Nicaragua for hand-rolled production, Switzerland for extract infrastructure, and United States for consumption gravity. Raw material dependencies include aged tobacco leaf, distilled spirit extracts, and fermentation-grade wrapper varieties. Single-source vulnerability in master blender talent constrains production scaling. Distribution runs through controlled wholesale partnerships with licensed retailers for mass-market tiers and direct relationships for premium allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquor flavored cigars market functions as a stable compounder where experiential retail expansion and spirits crossover branding generate durable repeat purchase economics resistant to cyclical compression.
For Market Incumbents: Lock in master blender talent through equity-linked compensation structures and captive aging facility partnerships before scarcity intensifies. Secure FDA compliance infrastructure investments now to maintain launch velocity against review backlog delays. Prioritize backward integration into barrel-aging extract technology to preserve margin pools from commodity volatility. For New Entrants and Emerging Players: Capture underpenetrated German secondary cities through Munich and Cologne lounge format experimentation before incumbent allocation agreements solidify. Target direct-to-consumer subscription channels with curated monthly deliveries that capture full retail-equivalent pricing and bypass wholesale margin extraction. Lead with whiskey variants in Texas and Tennessee where craft spirits culture overlaps with premium cigar consumption. For Investors and Strategic Acquirers: Valuations sit cheapest among machine-made operators with convenience channel dominance facing substitution pressure from nicotine pouches. Long-term viability favors premium hand-rolled specialists with compliance infrastructure and experiential retail relationships over five-to-ten year holding periods. Watch pending state-level flavored tobacco ban legislation as the critical inflection signal for portfolio reallocation between mass-market and artisan exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrel-Aging Extract Technology | In-house spirit extract production secures batch consistency and reduces regulatory traceability costs under FDA deeming rule. |
| Experiential Retail Partnership Expansion | Lounge-exclusive allocation agreements in Miami and Nashville command scarcity premiums above conventional wholesale channels. |
| Direct-to-Consumer Subscription Launch | Monthly curated deliveries bypass geographic retail restrictions and capture repeat buyer data for forecasting. |
| REACH Compliance Infrastructure Investment | Early ingredient traceability systems reduce barrier costs for cross-border distribution under EU Tobacco Products Directive. |
| Master Blender Talent Acquisition | Specialized aging profile expertise commands premium compensation and limits competitive production scaling. |
Research Methodology
Direct dialogue with master blenders, licensed tobacco retail operators, FDA regulatory consultants, and spirits industry brand managers grounded qualitative findings in operational reality. Secondary validation drew from FDA Center for Tobacco Products filings, EU Tobacco Products Directive implementation guidance, state excise tax databases, and customs trade records. Bottom-up and top-down triangulation cross-checked facility capacity estimates against consumption channel throughput data.
Bottom-up volume modeling aggregated production capacity across Dominican and Nicaraguan aging facilities with machine-made throughput assumptions, while top-down demand calibration referenced specialty lounge expansion rates and subscription channel growth patterns. Segmentation dimensions included flavor profile, cigar type, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs were derived from trend extrapolation moderated by premarket authorization timeline constraints and substitution elasticity estimates from adjacent nicotine product categories.
FDA deeming rule enforcement shifts, state-level flavored tobacco ban passages, and master blender talent migration are the dominant revision risks that could compress or extend growth trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Africa Tobacco Products Market
Tobacco Products
Global Flavor Capsule Cigarette Market
Tobacco Products
GCC Cigarette Lighter Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Europe Cigarette Market