
 Cigarette Lighter Market | 2026-2036
Cigarette Lighter Market Size, Share, and Industry Trends Forecast 2026-2036
Cigarette Lighter Market Intelligence
China is reshaping supply dynamics through expanded lighter production capacity in Zhejiang and Guangdong provinces. BIC Corporation leverages massive manufacturing scale to dominate disposable lighter volumes across multiple continents. Tokai Co., Ltd. anchors premium refillable lighter technology through sustained precision engineering investments. Ningbo Xinhai Electric Co., Ltd. competes aggressively on cost while extending distribution reach into European retail channels.
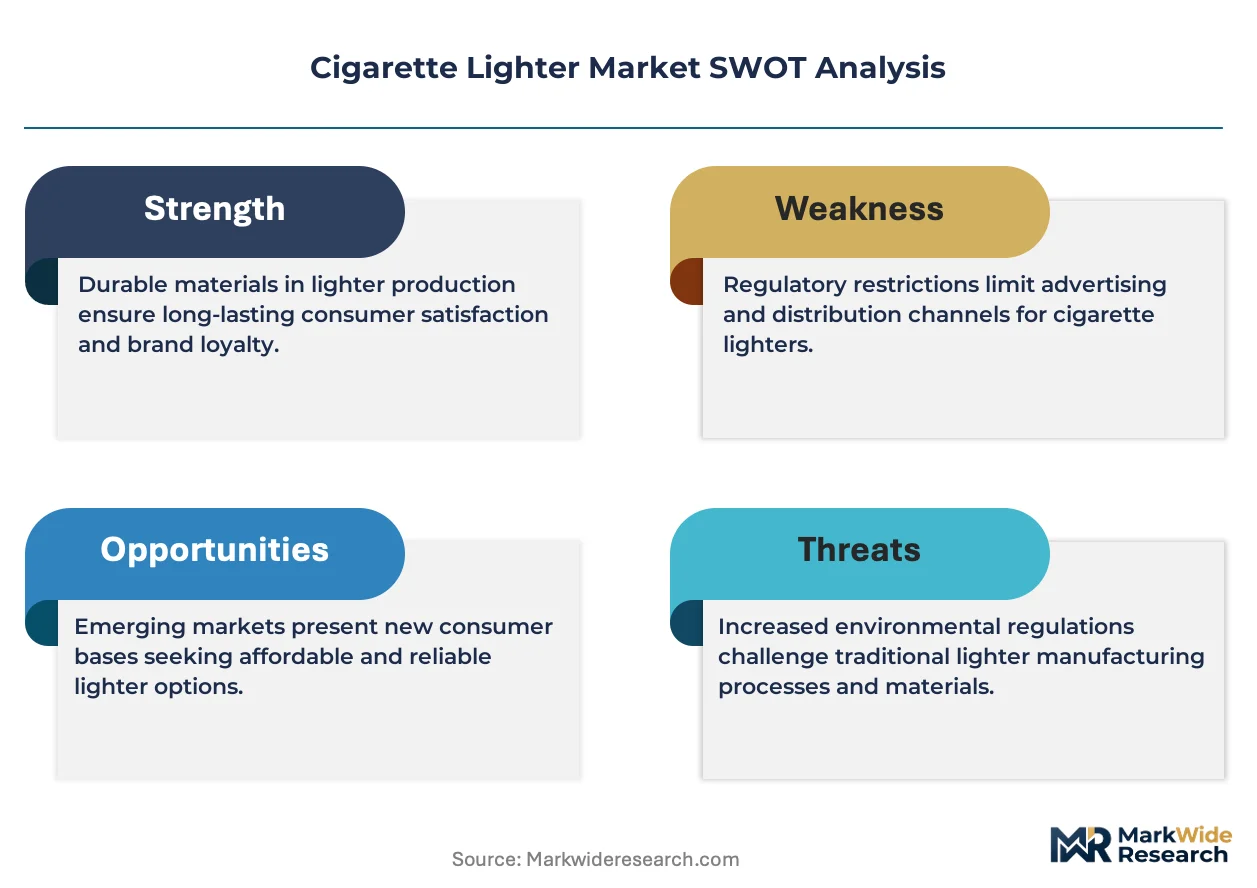
A cigarette lighter is a portable ignition device typically employing piezoelectric mechanisms or flint-and-steel systems to generate flame, with butane fuel capacity ranging from 3 to 15 grams depending on form factor, designed for consumer ignition of tobacco products, candles, and outdoor equipment. Disposable lighters occupy the highest volume tier due to impulse-purchase pricing and convenience-store ubiquity, though margin pools concentrate in refillable metal-body variants where zinc alloy construction commands durable goods positioning. Electronic lighters are gaining structural share through USB-rechargeable architectures that eliminate fuel logistics, while windproof designs sustain premium pricing in outdoor specialty channels.
China's SAMR enforces GB standards mandating child-resistant mechanisms and flame-height limits on all domestic lighter production. The EU REACH regulation restricts certain plasticizers and heavy metals in lighter components, forcing material substitutions across export-bound manufacturing. The US CPSC maintains mandatory child-safety testing protocols under federal flammable products authority. Stakeholders must monitor evolving battery-safety standards for electronic lighter architectures as lithium-ion cell integration accelerates across product lines.
Market Dynamics
China's GB standards for child-resistance mechanisms are compressing margins across disposable lighter manufacturing while simultaneously accelerating electronic lighter R&D investment.
Growth Catalysts
- REACH Regulation Compliance:EU REACH restrictions on plasticizers and heavy metals are forcing material substitutions that favor premium zinc-alloy refillable designs over disposable plastic variants.
- Outdoor Recreation Retail:Camping and outdoor equipment retailers are expanding lighter SKUs as fire-starting tools gain positioning alongside stoves and lanterns.
- USB-Rechargeable Architectures:Lithium-ion cell integration is eliminating fuel logistics for frequent travelers and eliminating recurring butane purchases.
Market Restraints
- Butane Price Volatility:Fluctuations in refined petroleum feedstock costs compress margins on fuel-dependent disposable and refillable models.
- Southeast Asian Supply Concentration:Manufacturing clustering in Vietnam and Indonesia creates single-source vulnerability for European and North American distributors.
- Electronic Lighter Battery Safety:Evolving lithium-ion safety standards impose testing costs that disadvantage smaller manufacturers lacking captive certification resources.
Strategic Opportunities
- Indonesia Domestic Market:Underpenetrated formal retail channels in Southeast Asia's largest archipelago offer first-mover positioning for child-resistant electronic variants.
- Windproof Specialty Positioning:Outdoor adventure applications command premium pricing unachievable in convenience-store disposable segments.
- SAMR Certification Acceleration:China's tightened GB enforcement creates competitive moats for manufacturers with established testing relationships in Zhejiang and Guangdong.
Industry Challenges
- Piezoelectric Engineering Talent:Precision ignition mechanism design requires specialized expertise concentrated in Japanese and German engineering centers.
- Multi-Jurisdiction Certification Timelines:Simultaneous US CPSC child-safety testing, EU REACH material compliance, and China SAMR GB adherence extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cigarette Lighter Market |
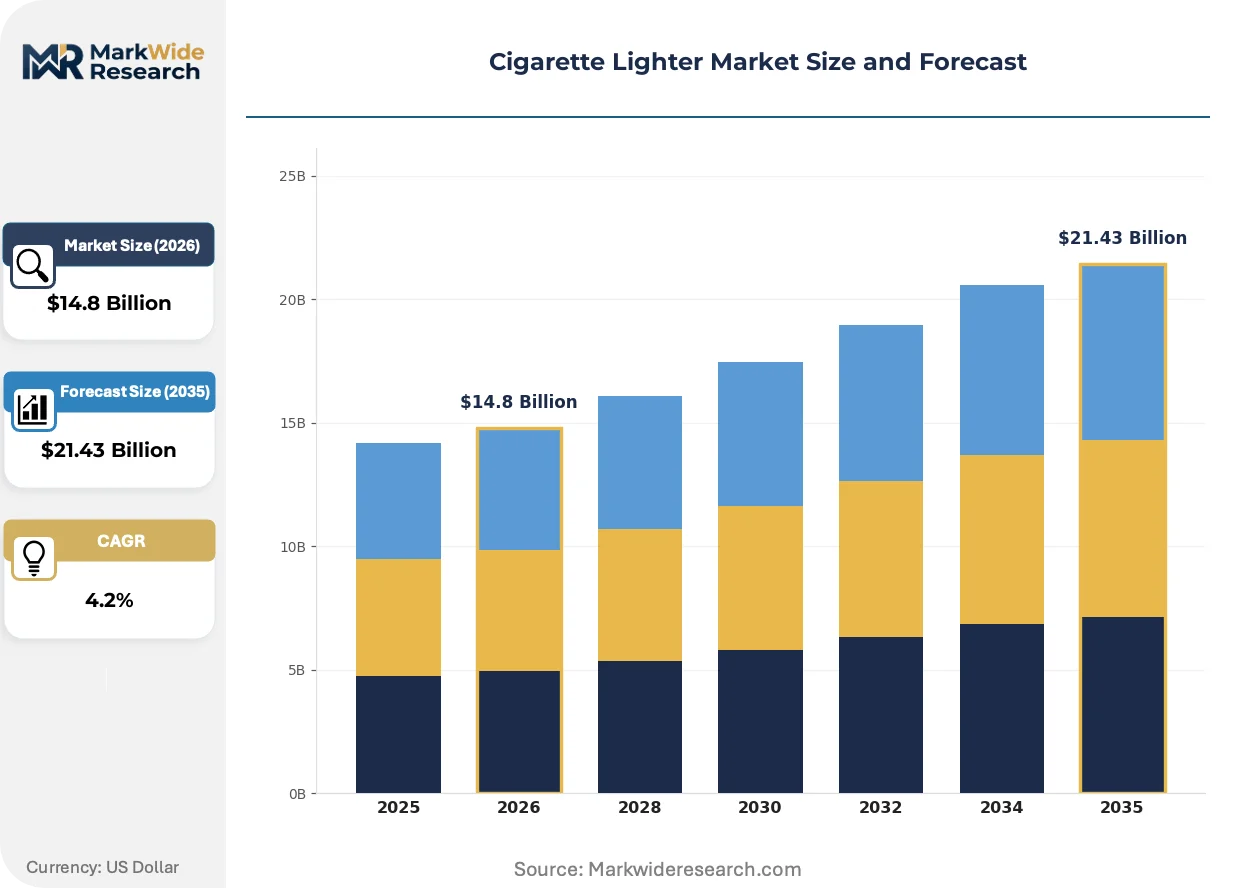
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Lighters, Disposable Lighters, Refillable Lighters, Windproof Lighters Material: Metal, Plastic, Butane, Zinc Alloy Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops Customer Type: Individual Consumers, Wholesale Buyers, Retail Store Owners, Gift Shops |
| Companies Covered | Flamagas, Tokai Co., Ltd., BIC Corporation, Ningbo Xinhai Electric Co., Ltd., Colibri, Zippo Manufacturing Company, S.T. Dupont, Visol Products, Swedish Match, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cigarette Lighter Market Strategic Shifts & Innovations
Electronic ignition architectures are compressing the traditional fuel-based lighter value chain while regulatory fragmentation across major markets forces parallel product development tracks.
Plasma arc ignition systems generate flameless heat through high-voltage electrical discharge between ceramic electrodes, eliminating fuel entirely. Outdoor specialty retailers and airport-duty-free operators are adopting these units rapidly for windproof reliability and travel compliance. This technology is rendering obsolete the butane logistics infrastructure that has defined lighter distribution for decades.
China's SAMR is tightening GB 25722 enforcement on child-resistant mechanism testing protocols, extending validation timelines for new product introductions. Domestic manufacturers in Wenzhou and Ningbo are absorbing compliance costs through vertical integration of testing laboratories. Export-bound production faces dual-track certification requirements that favor established players with regulatory affairs capacity.
Specialty outdoor retailers are consolidating lighter procurement into multi-year category management contracts with exclusive SKU development. This channel shift displaces the traditional cash-and-carry wholesale model that served convenience stores and gas stations. The transformation is most visible in Germany and Austria, where camping cooperative buying groups now specify custom windproof designs directly from Zhejiang manufacturers.
Cigarette Lighter Market Segmentation
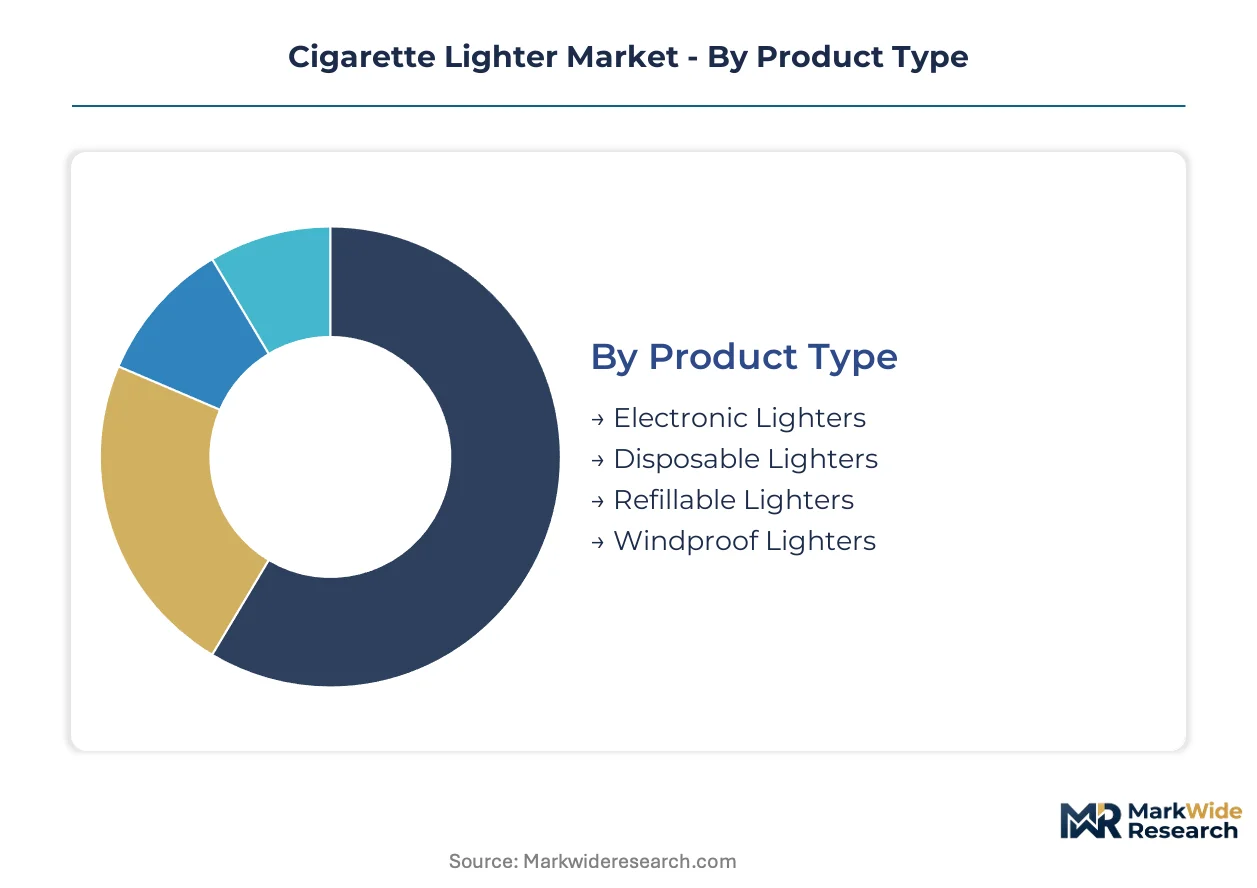
Segmentation in the cigarette lighter market determines margin capture, inventory velocity, and regulatory exposure. Product type dictates replacement frequency, while material selection governs REACH compliance costs and child-resistance certification pathways.
Product Type:
Replacement cycles range from single-use disposables to decade-spanning refillable metal units, creating divergent working capital requirements across manufacturer portfolios.
- Disposable Lighters:Single-use plastic-body units with fixed butane reservoirs and integrated flint ignition. Demand concentrates in convenience store channels across Indonesia and Vietnam where impulse purchasing dominates tobacco accessory procurement. Low unit economics compress margins but generate volume throughput that funds regulatory compliance investments.
- Electronic Lighters:USB-rechargeable lithium-ion architectures employing plasma arc or heated coil ignition without fuel. Southeast Asian manufacturing clusters in Shenzhen and Dongguan are absorbing capacity as European airport retail and outdoor specialty channels eliminate butane logistics. SAMR battery safety testing extends certification timelines for new entrants.
- Refillable Lighters:Metal-body designs with removable butane reservoirs and serviceable flint mechanisms. Zinc alloy construction commands durable goods positioning in German and Austrian camping cooperative buying groups.
- Windproof Lighters:Pressurized butane systems with modified combustion chambers for altitude and adverse weather reliability. Outdoor equipment retailers in the Alps and Rockies specify custom designs directly from Zhejiang manufacturers.
Disposable lighters dominate installed base. Electronic variants are where expansion concentrates.
Material:
REACH restrictions on plasticizers and heavy metals are forcing substitution decisions that separate premium zinc-alloy positioning from commodity plastic volumes.
- Metal:Stainless steel and brass constructions for premium refillable segments. German camping cooperatives specify metal-body minimums for fire-starting tool categories.
- Plastic:ABS and polypropylene disposable shells facing ECHA scrutiny on phthalate content. Wenzhou manufacturers are absorbing material substitution costs through backward integration into polymer compounding.
- Butane:Refined petroleum distillate fuel chemistry governed by flash point and purity specifications. Price volatility in refined feedstocks compresses margins on fuel-dependent product lines.
- Zinc Alloy:Die-cast ZAMAK constructions for mid-tier refillable positioning. Guangdong foundries supply European brands requiring REACH-compliant surface finishing.
Plastic commands volume throughput. Zinc alloy is where margin expansion concentrates.
Distribution Channel:
Channel selection determines price realization and regulatory documentation burden, with specialty retail imposing custom SKU requirements that convenience stores bypass.
- Convenience Stores:High-velocity impulse placement with minimal merchandising support. Indonesian and Vietnamese petrol station networks represent the densest outlet concentration.
- Online Retail:Cross-border e-commerce platforms requiring lithium-ion shipping compliance for electronic variants. Alibaba and JD.com channels dominate China domestic volume.
- Supermarkets:Mass merchandising with category management oversight. European hypermarket chains are consolidating procurement into multi-year contracts.
- Specialty Shops:Outdoor equipment and tobacco accessory retailers with exclusive windproof and gift-boxed positioning. German camping cooperatives now specify direct manufacturer relationships.
Convenience stores anchor volume throughput. Specialty shops are where premium positioning concentrates.
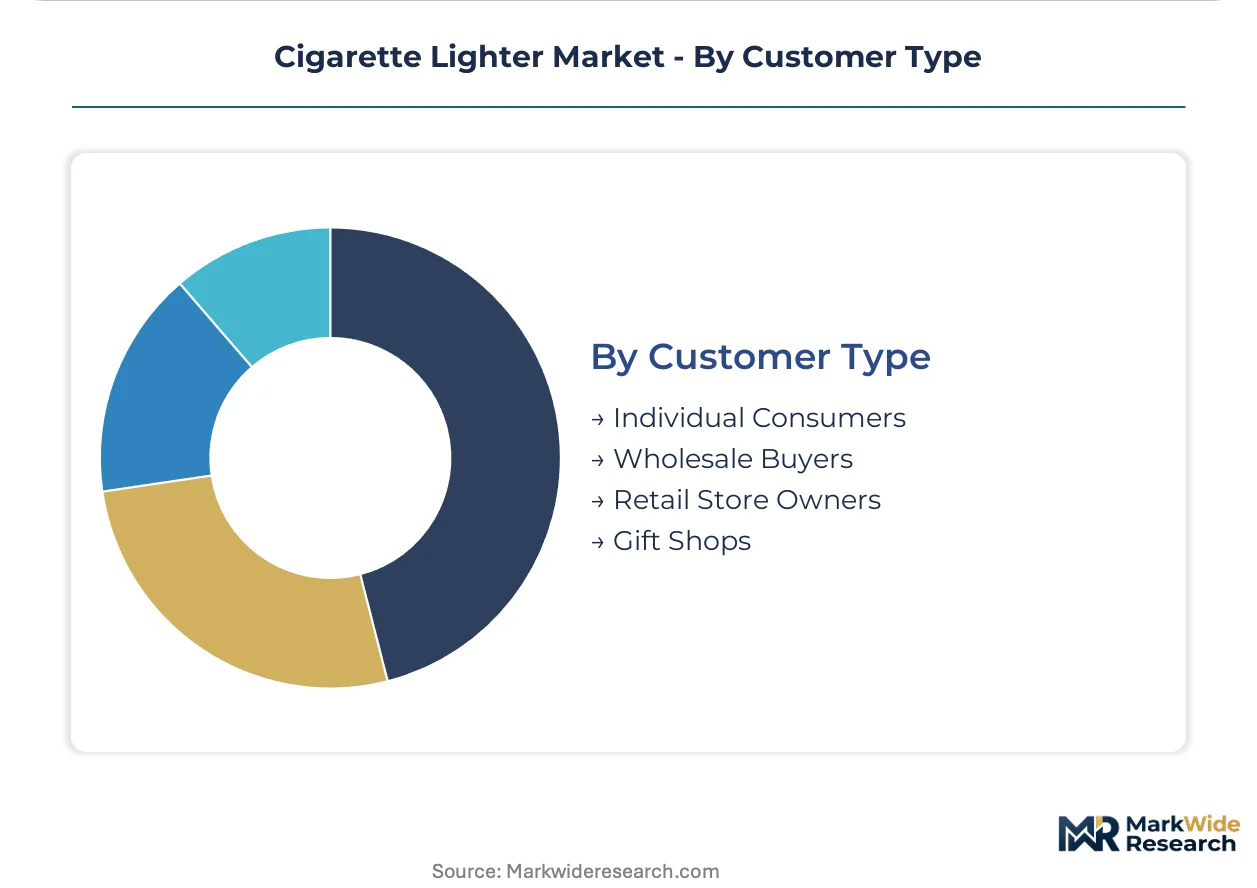
Customer Type:
Buyer sophistication determines certification documentation requirements and payment terms, with wholesale channels demanding batch testing records that individual consumers ignore.
- Individual Consumers:End-user purchasing with minimal technical specification awareness. European airport duty-free represents high-margin discretionary acquisition.
- Wholesale Buyers:Distributor procurement with mandatory CPSC child-safety testing documentation for US-bound shipments. Inventory pooling across multiple jurisdictions extends working capital cycles.
- Retail Store Owners:Independent convenience and tobacco shop operators with price-sensitive replenishment patterns. Indonesian archipelago distribution faces logistics fragmentation.
- Gift Shops:Curated merchandise selection emphasizing packaging differentiation and windproof reliability. Austrian and Swiss alpine resort retail commands premium placement fees.
Individual consumers dominate transaction frequency. Wholesale buyers are where compliance infrastructure concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters in Zhejiang and Guangdong provinces supply the majority of global lighter volumes, with Wenzhou and Ningbo foundries anchoring plastic disposable production while Dongguan facilities pivot toward electronic architectures.
China
Domestic consumption absorbs substantial volumes through convenience store networks in tier-two cities, while SAMR tightens GB 25722 enforcement on child-resistant testing protocols. Zhejiang manufacturers absorb compliance costs through captive testing laboratory investments.
United States
CPSC-mandated child-safety documentation burdens wholesale procurement channels, compressing margins on import-bound shipments. California and Texas distribution hubs face lithium-ion shipping restrictions on electronic variants entering through Long Beach and Houston ports.
Germany
Camping cooperative buying groups in Bavaria and Baden-Württemberg specify direct manufacturer relationships for windproof designs, displacing traditional wholesale intermediaries. ECHA REACH restrictions on phthalate content force material substitutions in disposable plastic imports.
Indonesia
Archipelago logistics fragmentation challenges formal retail penetration across 17,000 islands, creating first-mover positioning for child-resistant electronic variants in Jakarta and Surabaya metro areas. Local regulations on flammable product storage complicate distribution infrastructure.
Vietnam
Manufacturing migration from China accelerates in Hai Phong and Ho Chi Minh City industrial zones, though component sourcing dependencies on Guangdong suppliers persist. Domestic demand concentrates in petrol station convenience formats along the Red River Delta corridor.
Cigarette Lighter Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on ignition mechanism engineering. The market structures around three tiers: multinational disposable volume leaders, precision metal-body refiners, and emerging electronic architecture specialists. Competitive moves concentrate on backward integration into polymer compounding for REACH compliance and direct-to-retailer procurement relationships that bypass traditional wholesale channels.
Within the premium metal-body tier, Zippo Manufacturing Company and S.T. Dupont exemplify durable goods positioning through zinc-alloy construction and precision finishing. Tokai Co., Ltd. anchors Japanese precision engineering heritage in piezoelectric ignition systems. BIC Corporation occupies the scale-driven disposable segment with manufacturing throughput that funds multi-jurisdiction certification infrastructure.
| Leading Market Players |
|---|
| Flamagas |
| Tokai Co., Ltd. |
| BIC Corporation |
| Ningbo Xinhai Electric Co., Ltd. |
| Colibri |
| Zippo Manufacturing Company |
| S.T. Dupont |
| Visol Products |
| Swedish Match |
| Others |
Cost & Logistics Intelligence
Wenzhou manufacturing clusters anchor global disposable lighter capacity, and their production scale directly determines downstream pricing power across European and North American import channels. SAMR certification costs and REACH material compliance create tiered margin structures that separate captive-testing manufacturers from commodity exporters.
Pricing Analysis
EU REACH restrictions dictate the pricing tier structure across the cigarette lighter market, separating premium zinc-alloy refillable designs from phthalate-scrutinized plastic disposables. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and brand heritage, with German camping cooperatives least sensitive to price and Indonesian petrol station networks most reactive to unit cost shifts. Cost compression in disposable plastic tiers is intensifying because polymer substitution expenses and child-resistance testing burdens concentrate on smaller manufacturers lacking vertical integration.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electronic lighter architectures with lithium-ion cells. Manufacturing concentrates in China, Vietnam, and Indonesia, with component sourcing drawing from Guangdong piezoelectric specialists and Zhejiang polymer compounders. Single-source vulnerability persists in precision ignition mechanism engineering anchored in Japanese and German technical centers. Distribution runs through camping cooperative buying groups in Central Europe and convenience store wholesale networks across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as channel shifts from cash-and-carry wholesale to direct manufacturer-retailer relationships create niche positioning openings for specialized players.
For Market Incumbents: Insulate market position by accelerating captive laboratory investments for SAMR GB 25722 compliance acceleration, creating competitive moats against emerging electronic lighter specialists from Shenzhen. Prioritize direct procurement relationships with German and Austrian camping cooperatives to displace wholesale intermediaries and capture windproof premium pricing. For New Entrants and Emerging Players: Build out white-space positioning in Indonesia's underpenetrated formal retail channels, where archipelago logistics fragmentation has stalled multinational penetration. Target Jakarta and Surabaya metro areas with child-resistant electronic variants, leveraging USB-rechargeable architectures to bypass butane storage regulations complicating traditional distribution infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods conglomerates with neglected lighter divisions lacking electronic architecture R&D investment. Long-term viability hinges on lithium-ion safety certification capabilities and direct-to-retailer channel control rather than volume scale. Watch for SAMR enforcement acceleration as the inflection signal separating compliant asset values from stranded disposable plastic exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Laboratory Investment | Accelerates SAMR GB 25722 certification timelines for Zhejiang and Guangdong manufacturers against smaller competitors. |
| Direct-to-Retailer Procurement Relationship | Bypasses wholesale intermediaries for German camping cooperatives specifying custom windproof designs from Dongguan. |
| Electronic Architecture Pivot | Eliminates butane logistics dependencies through USB-rechargeable plasma arc systems penetrating airport duty-free channels. |
| Backward Integration into Polymer Compounding | Absorbs REACH phthalate substitution costs for Wenzhou disposable manufacturers facing ECHA scrutiny. |
| Windproof Specialty SKU Development | Commands premium placement fees in Austrian and Swiss alpine resort retail through altitude-reliable pressurized systems. |
Research Approach
Initial hypotheses were tested against primary input from product development engineers, regulatory affairs specialists at SAMR-certified laboratories, camping cooperative procurement managers, and convenience store wholesale distributors, then refined through secondary validation against customs trade records, ECHA substance restriction databases, CPSC child-safety testing protocols, and SEC filings from disclosed lighter manufacturers. Bottom-up demand modeling across product type, material composition, distribution channel, and customer archetype segments was triangulated with top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning disposable versus electronic versus refillable architectures, metal versus plastic versus zinc-alloy material tiers, and convenience store versus specialty retail versus online channel pathways. CAGRs were derived from installed base replacement cycles, regulatory-driven product obsolescence patterns, and channel shift velocity in outdoor equipment retail.
Stress conditions across butane feedstock price volatility, lithium-ion shipping restriction tightening, and SAMR enforcement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on replacement frequency and channel migration timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smoking Accessories
Herb Grinder Market
Smoking Accessories
United States Cigarette Lighter Market
Smoking Accessories
Rolling Papers Market
Smoking Accessories
Electric Pocket Lighter Market
Smoking Accessories
China Smoking Pipe Market
Smoking Accessories
US Smoking Pipe Market
Smoking Accessories
Global Blunt Wrap Market
Smoking Accessories
Smart Ashtray Market
Smoking Accessories
Smoking Accessories Market
Smoking Accessories
China Smoking Accessories Market
Smoking Accessories
Smart E-Cigarettes Market
Smoking Accessories
Latin America Cigarette Lighter Market
Smoking Accessories
UK Smoking Pipe Market
Smoking Accessories
Smoking Pipe Market
Smoking Accessories
Ashtray Market
Smoking Accessories
Pocket Lighter Market