
 Europe E-Commerce Logistics Market | 2026-2036
Europe E-Commerce Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe E-Commerce Logistics Market Insights
The gap between premium express and standard delivery tiers is expanding across European corridors. Deutsche Post DHL leverages its integrated parcel and freight network to dominate cross-border lanes. GLS Parcel Service anchors its position through dense ground hub coverage in Central Europe. DPDgroup differentiates via automated sortation investments in France and the Benelux.
Europe e-commerce logistics encompasses the planning, execution, and control of goods movement from seller to buyer through digital retail channels, typically involving parcel sortation hubs operating at throughputs exceeding 50,000 items per hour. The sector serves omnichannel retail fulfillment, industrial parts distribution, and pharmaceutical cold-chain delivery across the continent. Express delivery commands premium pricing in peri-urban zones while standard shipping retains volume leadership in rural catchments. Warehouse automation absorbs capital fastest among technology integration categories as labor scarcity bites in Poland and the Czech Republic.
EU Green Deal mandates and the F-Gas Regulation constrain diesel fleet renewal timelines across member states. ECHA chemical safety rules and national packaging ordinances in Germany and France shape material specifications for last-mile containers. Stakeholders must weigh electrification capex against route density thresholds before committing to zero-emission fleet rollouts.
Market Dynamics
The EU Green Deal is forcing fleet electrification timelines while warehouse automation races to offset labor scarcity in Central European distribution hubs. This dual pressure compresses capital deployment windows across the sector.
Growth Catalysts
- Last-Mile Electrification Mandates:The EU Green Deal and F-Gas Regulation accelerate zero-emission vehicle adoption in peri-urban delivery zones. Member states align national subsidies with these frameworks.
- Fashion E-Commerce Velocity:Apparel retailers drive parcel volume growth through omnichannel fulfillment models requiring same-day and next-day service tiers. Returns processing density creates hub economies.
- Automated Sortation Scale:Hub throughputs exceeding 50,000 items per hour reduce unit handling costs. Robotics integration addresses throughput bottlenecks in Benelux corridor operations.
Market Restraints
- Route Density Thresholds:Electrification capex requires minimum stop density per route that rural catchments fail to achieve. Fleet operators defer battery-electric rollouts to secondary markets.
- Labor Scarcity in Poland:Warehouse operator availability constrains fulfillment center expansion in the Czech Republic and Polish logistics corridors. Wage compression limits automation ROI calculations.
- ECHA Chemical Packaging Rules:Last-mile container specifications face material compliance costs under evolving chemical safety standards. Reusable packaging systems absorb redesign investment.
Strategic Opportunities
- Pharmaceutical Cold-Chain:Temperature-controlled last-mile infrastructure remains underdeveloped in Southern Europe. Specialized fleet assets capture premium pricing in Italy and Spain.
- Industrial Parts Distribution:B2B e-commerce logistics for machinery components lacks dedicated network density. Express corridors between Germany and France offer white-space entry.
- CSRD Disclosure Requirements:Corporate Sustainability Reporting Directive mandates create demand for carbon-accounting logistics services. Providers embedding emissions tracking gain procurement preference.
Industry Challenges
- Automation Integration Complexity:Legacy warehouse management systems resist API connectivity with robotic sortation modules. Retrofit timelines extend operational disruption.
- Certification Lag for Electric Fleets:Type-approval processes for heavy electric vans vary across German Länder and French regions. Homologation delays stall cross-border fleet standardization.
- Skills Gap in Hub Robotics:Maintenance technician availability trails automated facility deployment in the Netherlands. Training pipelines fail to match capital investment pace.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe E-Commerce Logistics Market |
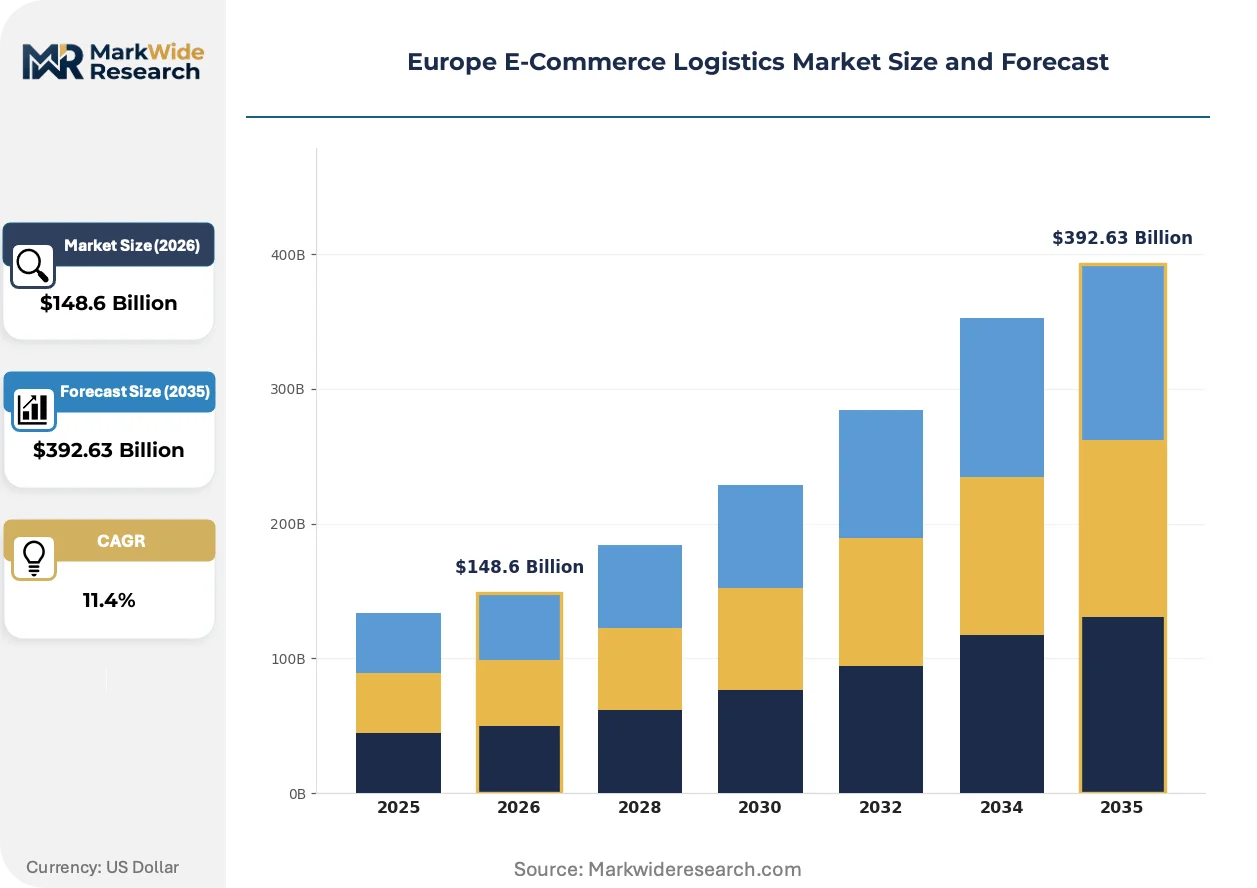
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $392.63 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Method: Standard Shipping, Express Delivery, Same-Day Delivery, Click & Collect Package Type: Boxes, Envelopes, Pallets, Custom Packaging Client Type: B2B, B2C, C2C, Marketplace Technology Integration: Warehouse Automation, Track & Trace Systems, GPS Routing, Drones |
| Companies Covered | UPS, GLS Parcel Service, Deutsche Post DHL, DSV, Kuehne + Nagel, DPDgroup, DB Schenker, GEODIS, FedEx, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe E-Commerce Logistics Market Trends and Innovations
Micro-fulfillment networks are compressing delivery radii while regulatory emissions frameworks and buyer delivery expectations converge to reshape network architecture decisions.
Autonomous mobile robots in parcel sortation hubs are decentralizing hub-and-spoke concentration by enabling smaller, distributed fulfillment nodes at viable unit economics. Fashion and grocery retailers deploy these systems in urban infill locations. The technology is decentralizing inventory positioning toward demand centers rather than regional mega-hubs.
The EU Green Deal's F-Gas Regulation and national diesel phase-out schedules constrain fleet procurement choices across member states. Logistics operators face compressed replacement windows for thermal vehicles. Cold-chain and express segments in Germany and France absorb the steepest compliance cost premiums.
Delivery slot precision and real-time tracking transparency now dominate buyer selection criteria over pure speed claims. Subscription-based delivery memberships displace per-transaction shipping fees in urban corridors. This preference shift concentrates most visibly in Dutch and Belgian metropolitan markets with high e-commerce penetration.
Europe E-Commerce Logistics Market Segmentation
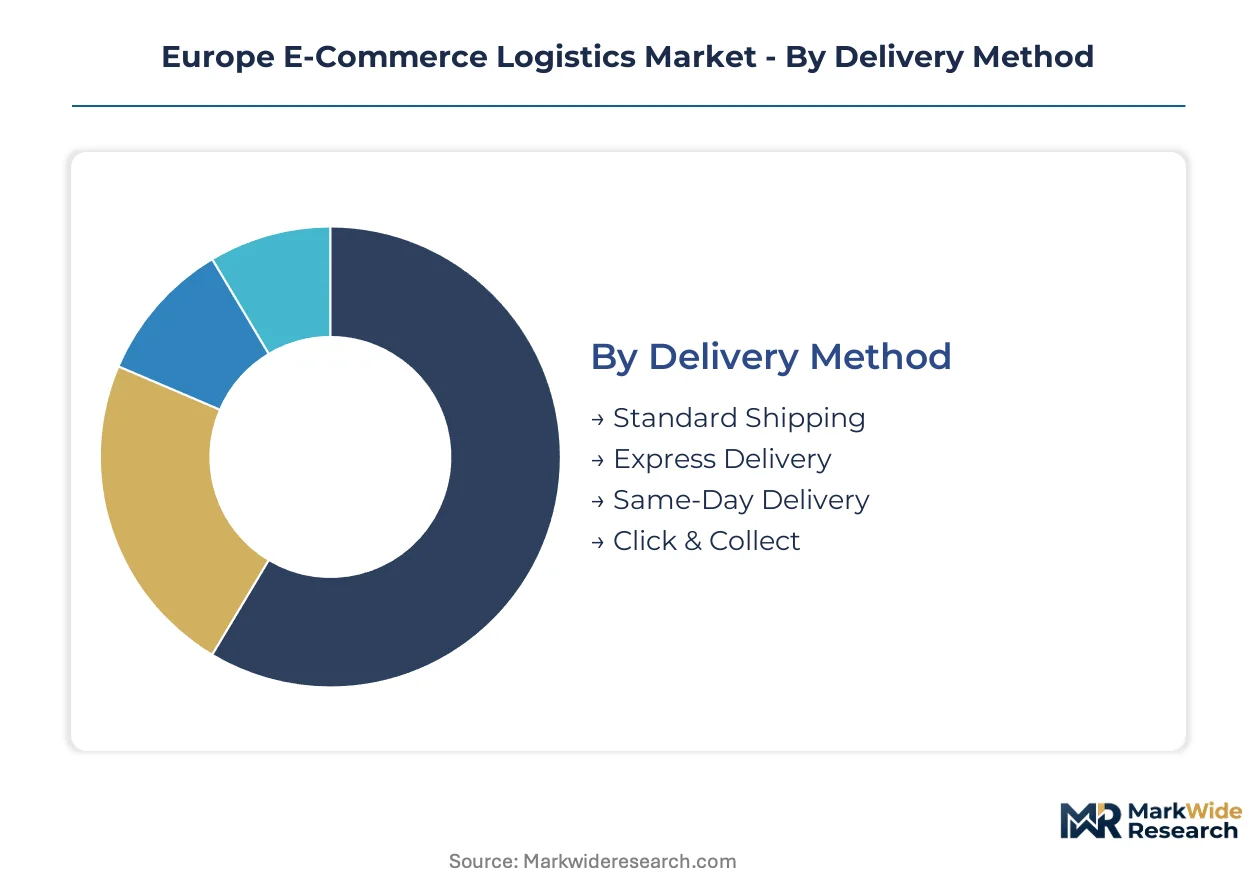
Delivery method, package configuration, client relationships, and technology deployment each create distinct operational requirements and margin profiles across European e-commerce corridors. Network operators configure assets differently for fashion B2C versus industrial B2B flows. Understanding these segment boundaries clarifies where capital deployment yields differential returns.
Delivery Method:
Standardization dominates at the economy tier while customization intensity escalates through express and same-day tiers, with each step demanding denser infrastructure and predictive routing capabilities.
- Standard Shipping:Consolidated line-haul networks with 2-5 day transit windows capture volume leadership in rural catchments across Poland and the Czech Republic. Deutsche Post DHL and GLS Parcel Service optimize hub-and-spoke density for this tier. Labor scarcity in Central European sortation facilities constrains throughput expansion despite parcel volume growth.
- Express Delivery:Premium next-day services command pricing power in peri-urban zones surrounding Amsterdam, Frankfurt, and Paris. DPDgroup's automated Benelux hubs support this tier. EU Green Deal electrification mandates impose fleet replacement costs that operators recover through surcharges in dense delivery corridors.
- Same-Day Delivery:Micro-fulfillment nodes within 15-kilometer radii enable urban inventory positioning. Fashion retailers in Dutch and Belgian metropolitan markets drive adoption.
- Click & Collect:Locker networks and retail partner pickup points reduce failed delivery rates. Grocery and apparel sectors deploy this method to offset last-mile labor costs.
Most installed capacity flows through Standard Shipping. Expansion is steepest in Same-Day Delivery.
Package Type:
Volume-to-weight ratios and fragility requirements segment handling equipment investments, with automation economics favoring standardized dimensions over irregular formats.
- Boxes:Corrugated containers between 1-20 kilograms dominate parcel sortation throughput, compatible with high-speed automated induction systems. Fashion and consumer electronics flows through German and French hubs concentrate here. ECHA chemical safety rules and national packaging ordinances reshape material specifications and compliance costs.
- Envelopes:Flat mailers and polybags below 2 kilograms enable letter-network leveraging for document and apparel shipments. Benelux corridor operations optimize for this lightweight segment.
- Pallets:Unitized freight movements serve B2B industrial parts distribution between Germany and France. Express corridor density remains underdeveloped for this freight class.
- Custom Packaging:Branded unboxing experiences and protective configurations for fragile goods absorb design investment from premium retailers.
Boxed parcel flows absorb the majority of automated sortation capital. Custom Packaging commands the highest unit handling premiums.
Client Type:
Contract structures and service level agreements diverge sharply between volume-committed B2B relationships and transaction-scale B2C fulfillment.
- B2B:Industrial parts distribution and wholesale replenishment require scheduled delivery windows and proof-of-delivery documentation. Machinery component flows between Germany and France lack dedicated network density, creating white-space entry opportunities.
- B2C:Omnichannel fashion retail drives parcel volume through same-day and next-day service tiers. Returns processing density creates hub economies in the Netherlands.
- C2C:Peer-to-peer marketplace shipments rely on drop-off point networks and simplified labeling interfaces.
- Marketplace:Platform-integrated logistics demand API connectivity and seller-agnostic fulfillment services.
B2C parcel volumes justify the majority of last-mile infrastructure deployment. B2B express corridors offer the steepest expansion trajectory for specialized operators.
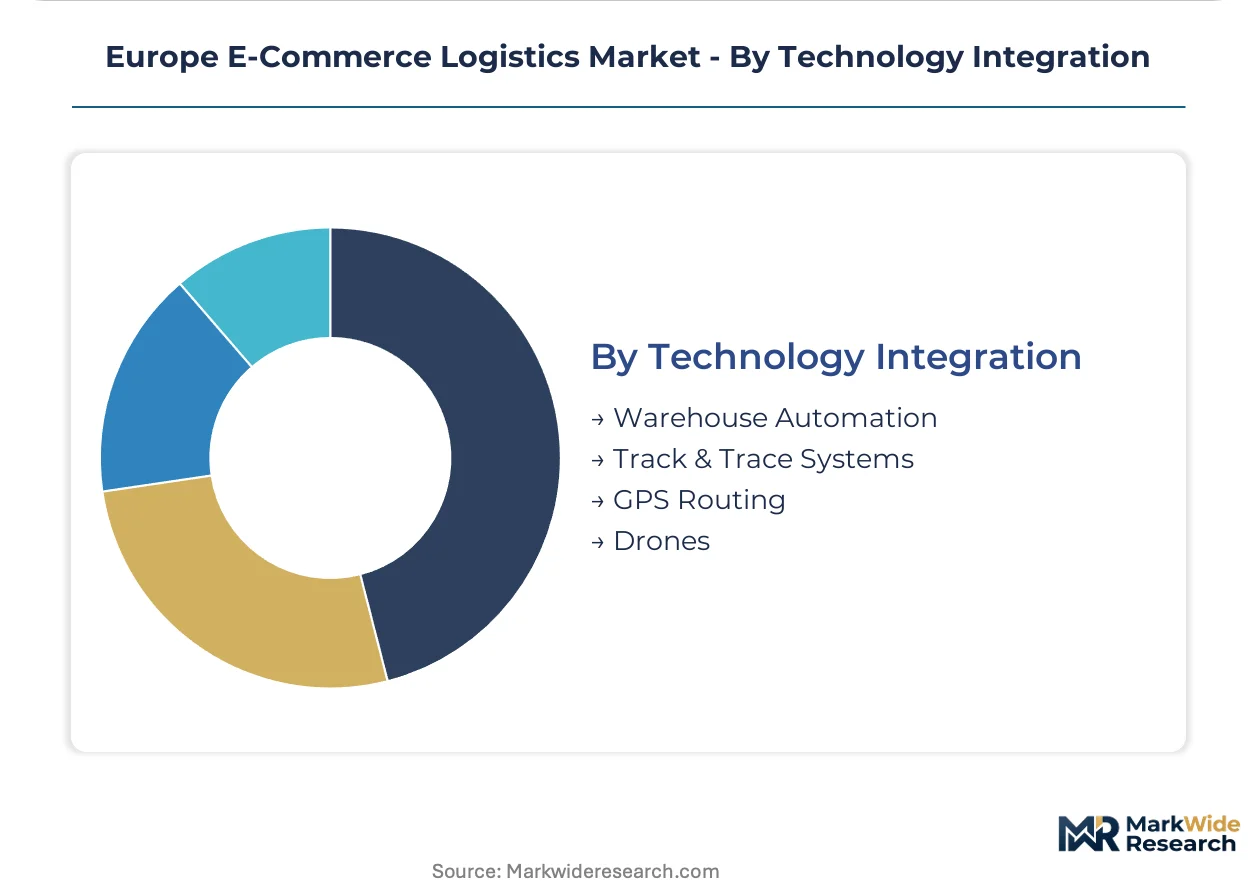
Technology Integration:
Capital absorption rates vary by technology maturity, with warehouse automation racing ahead of drone deployment timelines constrained by regulatory certification.
- Warehouse Automation:Robotic sortation modules and autonomous mobile robots enable hub throughputs exceeding 50,000 items per hour. Poland and the Czech Republic see fastest capital deployment as labor scarcity bites.
- Track & Trace Systems:Real-time visibility platforms now dominate buyer selection criteria over pure speed claims. CSRD disclosure requirements embed emissions tracking into procurement specifications.
- GPS Routing:Dynamic route optimization reduces per-stop costs in electrified last-mile fleets.
- Drones:Last-mile aerial delivery remains constrained by type-approval variations across German Länder and French regions.
Warehouse Automation captures the largest share of technology capital. Track & Trace Systems are gaining procurement preference fastest as sustainability reporting mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the deepest parcel sortation infrastructure, while France concentrates premium express corridor development. The Netherlands and Belgium anchor Benelux automation density. Poland and the Czech Republic absorb the steepest labor scarcity pressures.
Germany
Fashion omnichannel fulfillment and industrial parts distribution drive parcel throughput. The EU Green Deal and F-Gas Regulation compress diesel fleet replacement timelines. Dense hub-and-spoke networks radiate from the Rhine-Ruhr corridor toward Frankfurt and Hamburg.
France
Apparel retailers and pharmaceutical cold-chain logistics sustain express delivery premiums. ECHA chemical packaging rules reshape last-mile container specifications. Automated sortation investments cluster around Paris and Lyon distribution zones.
Netherlands
Returns processing density and same-day delivery subscriptions concentrate buyer demand. CSRD disclosure requirements embed emissions tracking into procurement specifications. Rotterdam and Amsterdam metropolitan markets exhibit the highest e-commerce penetration rates.
Belgium
Cross-border corridor traffic between France, Germany, and the Netherlands generates transit volume. National diesel phase-out schedules align with EU Green Deal frameworks. Brussels and Antwerp logistics zones optimize for lightweight envelope and polybag flows.
Poland
Warehouse automation races to offset labor scarcity in fulfillment center expansion. Central European logistics corridors attract capital deployment from Western European operators. Warsaw and Wrocław distribution hubs absorb robotic sortation investments fastest.
Europe E-Commerce Logistics Market Competitive Landscape
Top-tier vendors anchor integrated parcel and freight networks, while regional specialists concentrate on automated hub density or corridor-specific express lanes. The vendor base stratifies across three archetypes: integrated multinational operators, regional hub-scale specialists, and niche cold-chain or B2B express providers. Capacity expansion and electrification capex commitments represent the dominant competitive moves across the forecast window.
Among integrated network operators, Deutsche Post DHL and UPS exemplify the hub-and-spoke scale archetype, while DPDgroup occupies a position within the automated sortation specialist tier. These entities represent contrasting strategic postures: multinational scope versus corridor-specific automation density.
| Leading Market Players |
|---|
| UPS |
| GLS Parcel Service |
| Deutsche Post DHL |
| DSV |
| Kuehne + Nagel |
| DPDgroup |
| DB Schenker |
| GEODIS |
| FedEx |
| Others |
Pricing and Supply Chain Analysis
Diesel fuel price indices cascading through European line-haul networks compress margin structures across standard shipping tiers while electrification capex concentrates in premium express corridors. Three-tier pricing structure across premium, standard, and economy levels reflects divergent infrastructure commitments rather than uniform cost-plus calculations.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors in Central European standard shipping. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and route density. Price differentiation hinges on electrification compliance costs in German urban corridors and automation scale in Benelux hubs. Rural catchments exhibit highest buyer price sensitivity due to lower stop density and deferred fleet upgrades.
Supply Chain Analysis
CE marking for electric van homologation and ECHA chemical safety certifications gate supplier participation in German and French last-mile container markets. Warehouse automation equipment concentrates in Germany, the Netherlands, and Poland. Lithium-ion battery cells, corrugated packaging materials, and robotic sortation modules anchor component dependencies. Single-source vulnerability sits with Asian battery cell suppliers for electric fleet rollouts. Distribution runs through hub-and-spoke networks radiating from Rhine-Ruhr, Paris, and Amsterdam metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European e-commerce logistics rests on warehouse automation absorbing labor scarcity costs and express tiers capturing electrification compliance premiums. Electrification capex compression and automated sortation scale define the cost-down trajectory.
For Market Incumbents: To counter labor scarcity in Polish and Czech fulfillment corridors, Deutsche Post DHL and GLS Parcel Service should accelerate robotic sortation deployment in Central European hubs. Backward integration into last-mile electric van procurement through direct OEM partnerships reduces fleet homologation delays across German Länder. Certification investment in ECHA-compliant reusable packaging systems defends position against regulatory redesign costs. For New Entrants and Emerging Players: Capture pharmaceutical cold-chain white space in Southern Europe where temperature-controlled infrastructure remains underdeveloped. Industrial parts distribution between Germany and France offers the most penetrable B2B corridor given existing express network gaps. A specialized fleet asset strategy targeting Italy and Spain with GDP-compliant vehicles enables premium pricing capture before incumbent network extension. For Investors and Strategic Acquirers: Asymmetric upside sits with automated sortation specialists possessing dense Benelux hub coverage and API-integrated warehouse management platforms. Five-to-ten-year viability favors operators embedding CSRD-compliant emissions tracking into procurement specifications. The signal to watch is battery-electric fleet certification harmonization progress across French regions and German Länder as inflection indicator for cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sortation Scale-Up | Hub throughputs exceeding 50,000 items per hour reduce unit handling costs in Poland and Czech Republic. |
| Electric Fleet Rollout | EU Green Deal compliance in German peri-urban zones recovers capex through express delivery surcharges. |
| Pharmaceutical Cold-Chain Buildout | GDP-certified infrastructure in Italy and Spain captures premium pricing from temperature-sensitive biologics. |
| CSRD-Compliant Emissions Tracking | Embedded carbon accounting in Dutch and Belgian procurement specifications gains buyer preference. |
| Micro-Fulfillment Network Expansion | 15-kilometer urban radii in Amsterdam and Brussels metropolitan markets enable same-day subscription models. |
Research Methodology
Bottom-up parcel volume modeling reconciled against top-down fleet capacity tracking forms the analytical core of this study. Primary interviews with logistics network planners, warehouse operations directors, last-mile fleet managers, and retail procurement leads combined with secondary validation from EU customs data, national packaging ordinance filings, and ECHA chemical safety registrations. Deutsche Post DHL and DPDgroup public disclosures on hub automation investments triangulate against Polish Central Statistical Office warehouse employment data.
Input-output matrices map delivery method segments through package type configurations and client relationship structures across the projection horizon. Modeled dimensions span standard-express-same-day delivery tiers, box-envelope-pallet formats, and B2B-B2C-C2C flows. CAGRs derive from corridor-specific volume elasticity coefficients applied to electrification capex schedules and automation deployment timelines. Forecast inputs incorporate EU Green Deal regulatory phase-outs and F-Gas Regulation fleet replacement mandates.
Regulatory enforcement delays, battery supply chain disruptions, and labor migration pattern shifts are the dominant revision risks to modeled outcomes. Forecasts embed assumptions on homologation harmonization progress and robotic technician training pipeline scaling. A model refresh is warranted upon material change in EU member state subsidy alignment with zero-emission vehicle adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
E-Commerce in Nigeria Market