
 North America FMCG B2B E-Commerce Market | 2026-2036
North America FMCG B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
North America FMCG B2B E-Commerce Market Insights
Headless commerce architecture is rewriting how FMCG suppliers connect with business buyers, decoupling front-end interfaces from back-end inventory systems to enable real-time pricing and availability. Amazon Business leverages its fulfillment density to dominate same-day delivery for bulk consumables. Staples Business Advantage anchors its position through dedicated account management layered onto digital procurement portals. Sysco Shop differentiates by integrating temperature-controlled logistics visibility directly into restaurant buyer dashboards.
North America FMCG B2B E-Commerce encompasses digital wholesale transactions of fast-moving consumer goods between businesses, spanning health and beauty, groceries, household supplies, and snacks, typically executed through platforms offering negotiated pricing, volume-tiered catalogs, and integrated payment terms rather than standard retail checkout flows. The customer type dimension reveals wholesale distributors and restaurant operators as the fastest-growing buyer segments, drawn by centralized spend tracking and automated reordering protocols that reduce procurement labor. Delivery model dynamics show subscription frameworks capturing the most predictable margin pools, while click-and-collect remains concentrated among retailers with existing physical infrastructure.
The US Federal Trade Commission scrutinizes platform pricing transparency and most-favored-nation clauses that may constrain supplier flexibility across competing marketplaces. Canada's Office of the Privacy Commissioner enforces PIPEDA compliance for cross-border transaction data, affecting how US platforms store Canadian buyer information. Mexico's Federal Economic Competition Commission evaluates marketplace concentration in food distribution corridors. Stakeholders must monitor how evolving antitrust interpretations of platform self-preferencing reshape vendor access rules and category exclusivity terms.
Market Dynamics
Headless commerce architecture is decoupling front-end buyer interfaces from back-end inventory systems, forcing FMCG suppliers to rebuild their technology stacks around real-time API connectivity or lose procurement contracts to digitally native competitors.
Growth Catalysts
- PIPEDA Compliance Mandates:Canada's privacy framework is accelerating platform investments in secure cross-border data handling, creating procurement advantages for compliant US distributors serving Canadian independent retailers.
- Midwest Manufacturing Corridor Concentration:Ohio, Michigan, and Illinois factory clusters are consolidating vendor relationships through centralized e-procurement portals that automate reordering for maintenance, repair, and operations supplies.
- Restaurant Operator Digitization:Regional foodservice chains are abandoning phone-based ordering for dashboard-driven procurement with integrated temperature-logging visibility.
Market Restraints
- Most-Favored-Nation Clause Constraints:FTC scrutiny of platform pricing transparency limits supplier flexibility to offer differentiated rates across competing B2B marketplaces.
- API Integration Costs:Legacy ERP systems in family-owned distributors require expensive middleware development to achieve real-time inventory synchronization with buyer platforms.
- Cross-Border Data Localization:PIPEDA requirements force US platforms to maintain Canadian-dedicated server infrastructure, raising operational overhead for mid-market entrants.
Strategic Opportunities
- Mexico Food Distribution Corridors:Underpenetrated B2B e-commerce in Mexican wholesale markets offers first-mover positioning for platforms with Spanish-language interfaces and peso-denominated trade credit.
- Subscription Framework Expansion:Predictable reordering protocols for janitorial supplies and office consumables capture margin pools through automated replenishment algorithms.
- Temperature-Controlled Logistics Integration:Cold-chain visibility technology convergence with procurement dashboards creates premium positioning for perishable goods distributors.
Industry Challenges
- Legacy System Migration Complexity:Family-owned distributors face multi-year ERP replacement timelines that delay platform connectivity and risk contract losses to digitally integrated competitors.
- Specialized Talent Scarcity:Demand for full-stack developers with both FMCG domain knowledge and API architecture expertise outstrips supply in secondary US markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America FMCG B2B E-Commerce Market |
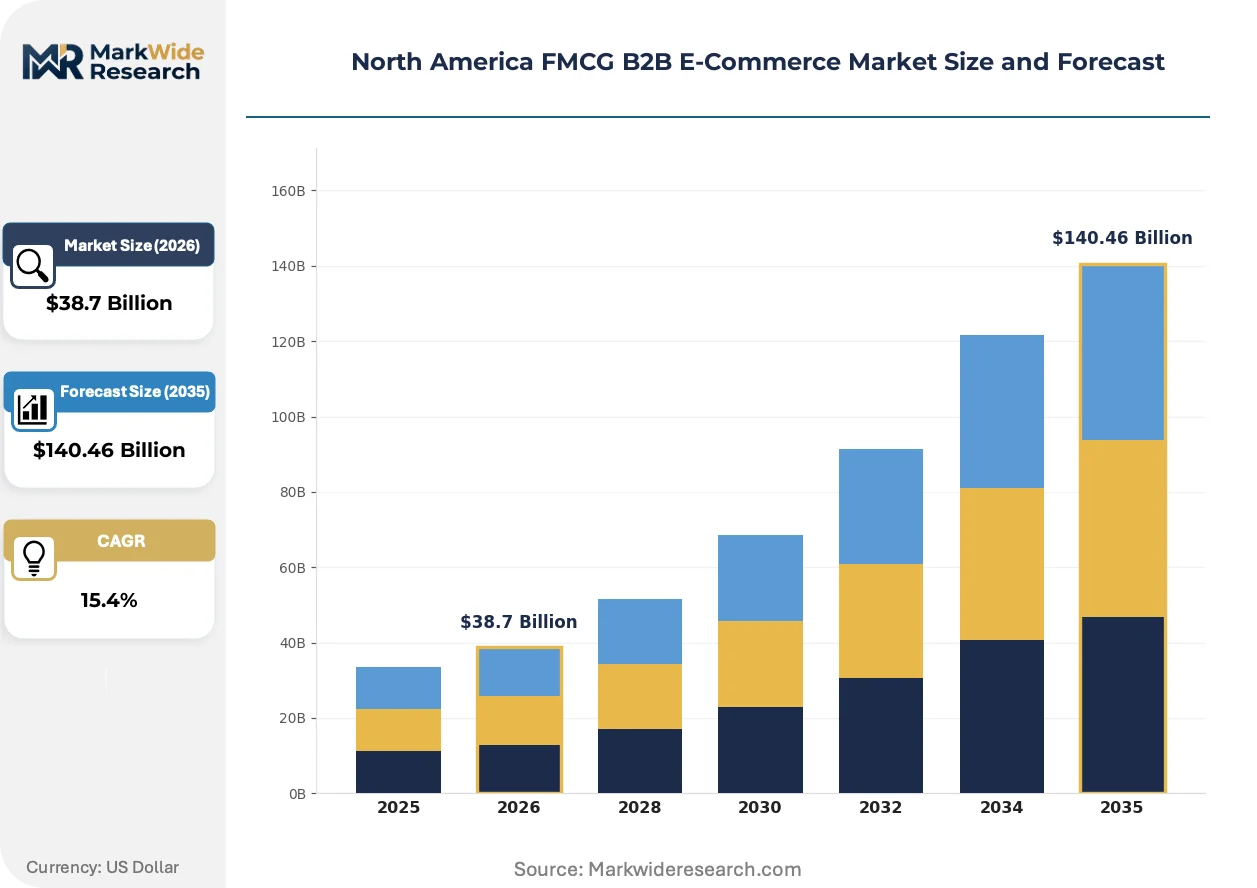
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $140.46 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health & Beauty, Groceries, Household Supplies, Snacks Customer Type: Wholesale Distributors, Retailers, Restaurants, Manufacturers Delivery Model: Direct Shipping, Click & Collect, Express Delivery, Subscription Order Size: Bulk Orders, Small Orders, Average Orders, High-Volume Orders |
| Companies Covered | Amazon Business, Walmart Business, Staples Business Advantage, The Kroger Co, W.W. Grainger Inc., Office Depot Inc., Home Depot Pro, Thomasnet, Sysco Shop, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America FMCG B2B E-Commerce Market Trends and Innovations
Real-time inventory visibility and automated procurement protocols are compressing buyer decision cycles and redefining competitive advantage around data integration depth rather than catalog breadth alone.
Headless commerce platforms are rendering obsolete monolithic e-procurement systems that batch-process orders through overnight inventory updates. Regional restaurant chains and independent convenience stores are adopting API-first architectures within twelve-month procurement system replacement cycles. This shift is compressing supplier response times from days to hours and eliminating competitive differentiation based solely on catalog size.
Canada's Office of the Privacy Commissioner is intensifying PIPEDA enforcement for cross-border transaction data, compelling US platforms to segment Canadian buyer information onto domestic servers. This regulatory pressure is raising compliance costs for mid-market entrants while creating structural advantages for enterprise platforms with existing Canadian infrastructure. Foodservice distributors with integrated Canadian operations are absorbing these requirements faster than pure-play technology vendors.
Centralized spend tracking is displacing decentralized purchasing authority across multi-location restaurant operators and retail chains. Procurement managers are consolidating vendor relationships onto single platforms that aggregate spend data for negotiated tier pricing. This behavioral shift is most visible in the US Midwest manufacturing corridor, where plant maintenance supervisors are losing autonomy over supplier selection to corporate procurement functions.
North America FMCG B2B E-Commerce Market Segmentation
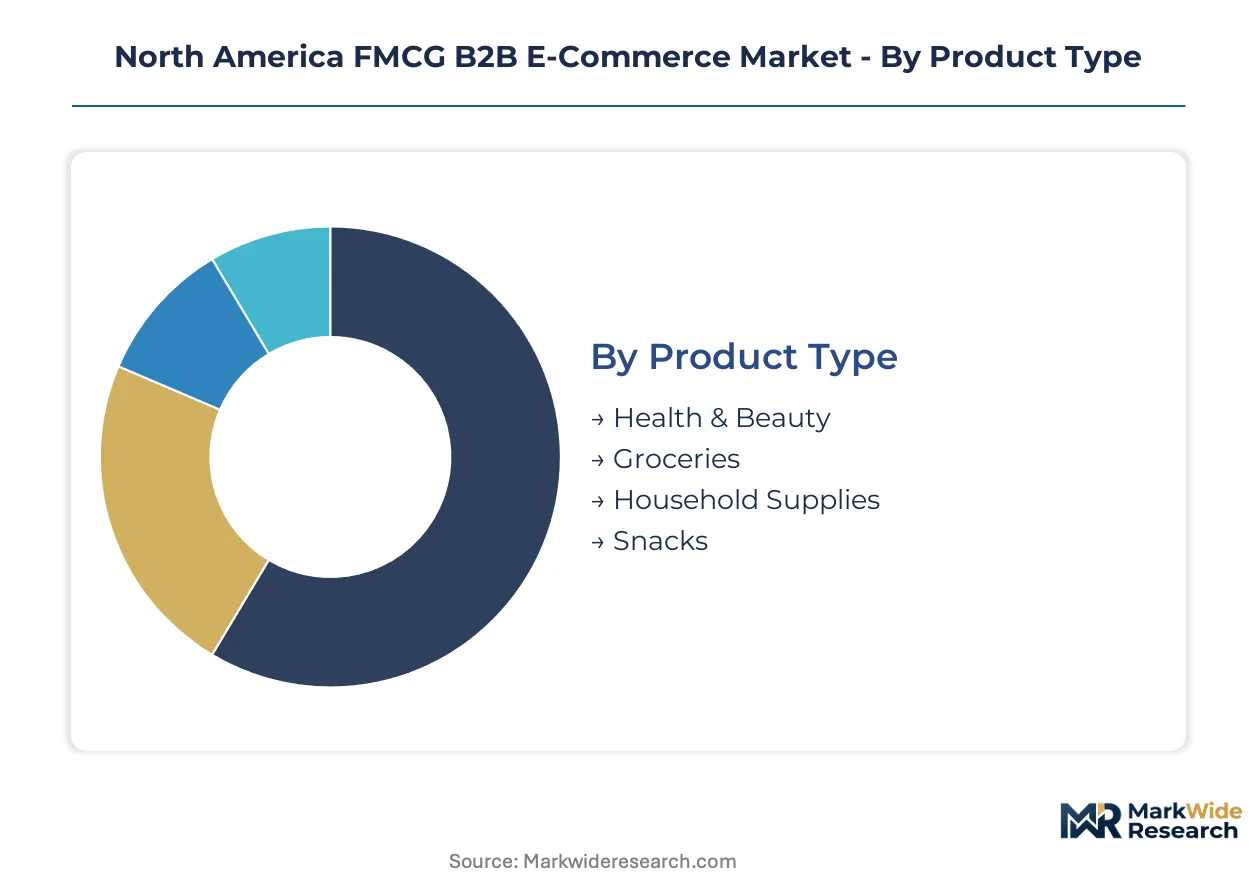
Segmentation in North America FMCG B2B E-Commerce reveals how procurement velocity, customer operational models, and fulfillment infrastructure create divergent margin profiles across product and service categories. Cycle time variations between perishable groceries and durable household supplies dictate platform technology investments and working capital requirements.
Product Type:
Inventory velocity separates segments requiring daily replenishment from those operating on monthly reorder cycles, reshaping warehouse network design and supplier payment terms.
- Health & Beauty:SKU-intensive categories with expiration-date sensitivity demand lot-tracking capabilities and temperature-controlled storage. Ohio and Michigan manufacturing corridor buyers consolidate pharmaceutical-grade personal care procurement through centralized portals with automated reorder points.
- Groceries:Perishables with compressed shelf lives drive the shortest procurement cycles in the market. Restaurant operators in the US Midwest corridor prioritize platforms integrating USDA compliance documentation with real-time spoilage alerts.
- Household Supplies:Stable-demand categories with extended storage horizons suit subscription frameworks and bulk consolidation. Janitorial supply buyers favor predictable delivery windows over speed.
- Snacks:Seasonal velocity spikes around holidays and sporting events create demand forecasting complexity. Regional convenience store chains require flexible minimum order quantities to manage cash flow.
Groceries dominates installed base transaction volume. Health & Beauty is where expansion concentrates as specialty distributors build API-first platforms.
Customer Type:
Procurement sophistication varies sharply across buyer categories, with enterprise-grade ERP integration separating high-volume accounts from phone-order holdouts.
- Wholesale Distributors:Intermediaries with legacy warehouse management systems face expensive middleware development to achieve real-time inventory synchronization. PIPEDA compliance investments by Canadian distributors create procurement advantages for cross-border US suppliers.
- Retailers:Independent convenience stores are abandoning distributor sales representatives for self-service portals with negotiated tier pricing. Illinois-based retail chains lead adoption of centralized spend tracking dashboards.
- Restaurants:Regional foodservice chains demand temperature-logging visibility integrated directly into procurement workflows. FTC scrutiny of platform pricing transparency constrains their ability to source across competing marketplaces.
- Manufacturers:Plant maintenance supervisors in Ohio factory clusters are losing supplier selection autonomy to corporate procurement functions. MRO supply consolidation onto single platforms aggregates spend for volume discounts.
Wholesale Distributors dominate installed base platform relationships. Restaurants are climbing the fastest as temperature-controlled logistics integration becomes a competitive differentiator.
Delivery Model:
Fulfillment infrastructure requirements create divergent capital intensity profiles, with same-day capabilities demanding dense warehouse networks that mid-market entrants cannot replicate.
- Direct Shipping:Standard freight arrangements from supplier DCs to buyer locations suit non-urgent replenishment. Michigan manufacturers favor this model for MRO supplies with predictable consumption patterns.
- Click & Collect:Buyer pickup at designated fulfillment points concentrates among retailers with existing brick-and-mortar footprints. Illinois-based distributors leverage retail locations as order consolidation hubs.
- Express Delivery:Same-day or next-day fulfillment requires last-mile density that only enterprise platforms achieve at scale. FTC antitrust evaluations of platform self-preferencing reshape vendor access rules for express-capable marketplaces.
- Subscription:Automated replenishment algorithms capture the most predictable margin pools through reduced customer acquisition costs. Janitorial and office consumables buyers in the US Midwest corridor show highest adoption.
Direct Shipping dominates installed base fulfillment volume. Subscription is gaining share fastest as procurement labor reduction becomes a priority metric for multi-location operators.
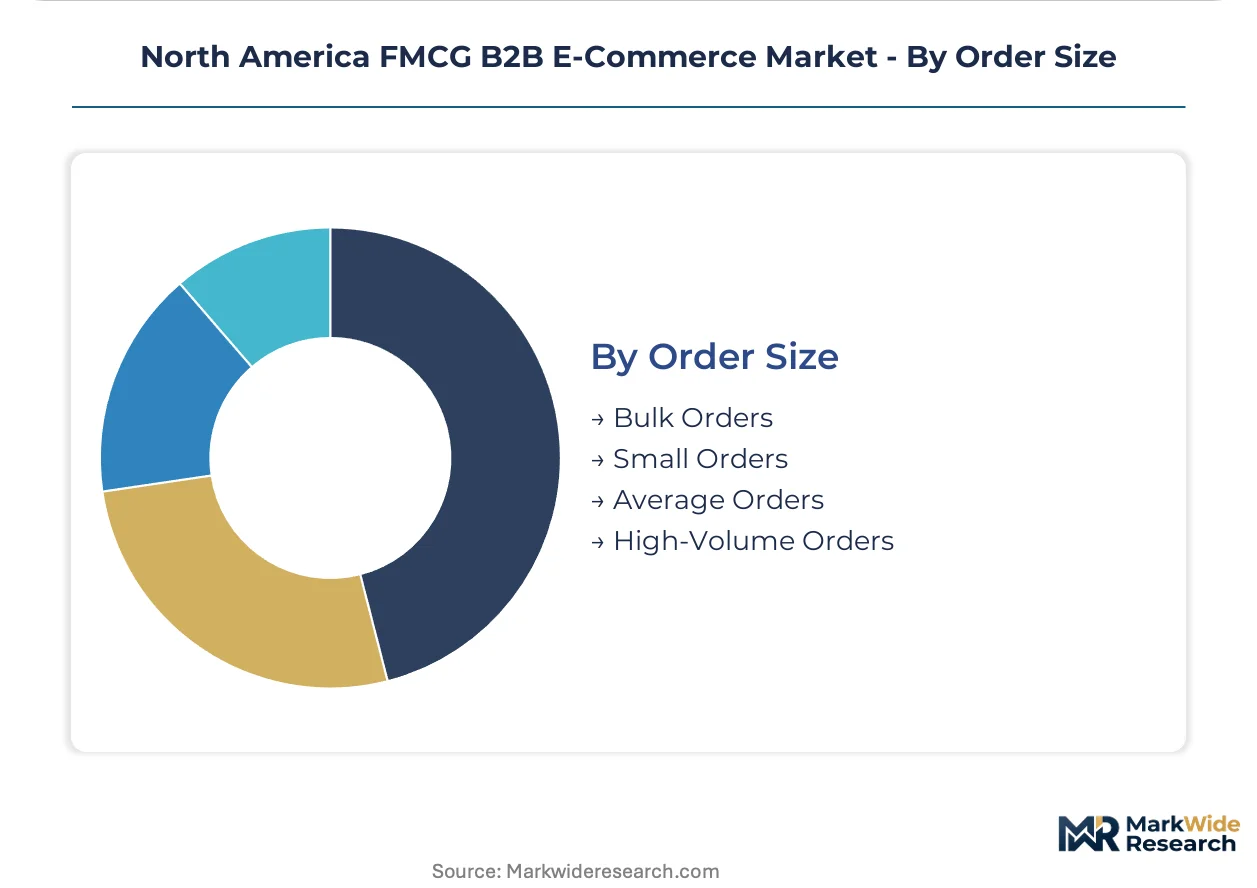
Order Size:
Minimum order quantity thresholds and freight economics segment buyers by working capital capacity, with small-order capabilities requiring disproportionate technology investment per revenue dollar.
- Bulk Orders:Full-truckload or pallet-quantity transactions suit high-volume manufacturers with dedicated receiving infrastructure. Ohio factory clusters consolidate vendor relationships through bulk procurement portals.
- Small Orders:Less-than-case quantities serve independent retailers with constrained storage space and cash flow. PIPEDA-compliant platforms gain advantage serving Canadian independent stores with flexible terms.
- Average Orders:Mid-tier volume tiers represent the competitive battleground where platform switching costs are lowest. Regional restaurant chains negotiate tier pricing based on aggregated spend across locations.
- High-Volume Orders:Enterprise accounts with dedicated account management requirements demand customized catalog configurations and payment term flexibility. FTC most-favored-nation clause scrutiny limits supplier pricing differentiation for this segment.
Bulk Orders dominates installed base revenue concentration. Small Orders show steepest expansion trajectory as platform technology reduces per-transaction service costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian distributors export temperature-controlled logistics services to US Midwest manufacturing clusters, while Mexican food distribution corridors supply fresh produce northward through integrated B2B procurement portals.
United States
Ohio, Michigan, and Illinois factory clusters drive MRO supply consolidation through centralized e-procurement portals. FTC scrutiny of most-favored-nation clauses constrains supplier pricing flexibility across competing marketplaces. The Midwest manufacturing corridor anchors demand for automated reordering protocols that reduce plant maintenance labor.
Canada
Independent convenience stores in Ontario and Quebec accelerate platform adoption for negotiated tier pricing and spend tracking. PIPEDA compliance mandates from the Office of the Privacy Commissioner force US platforms to maintain Canadian-dedicated server infrastructure. Toronto-based distributors gain procurement advantages serving cross-border US suppliers with compliant data handling.
Mexico
Regional restaurant chains in Mexico City and Nuevo León abandon phone-based ordering for dashboard-driven procurement with Spanish-language interfaces. The Federal Economic Competition Commission evaluates marketplace concentration in food distribution corridors. Jalisco-based wholesale markets offer first-mover positioning for platforms with peso-denominated trade credit.
North America FMCG B2B E-Commerce Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where fulfillment density separates enterprise-scale operators from mid-market entrants. Amazon Business leverages warehouse network concentration to dominate same-day delivery for bulk consumables. Staples Business Advantage anchors its position through dedicated account management layered onto digital procurement portals. Sysco Shop differentiates by integrating temperature-controlled logistics visibility directly into restaurant buyer dashboards. Competitive moves concentrate on API-first architecture investments and subscription framework expansion to capture predictable reordering revenue.
Within the fulfillment-integrated tier, Amazon Business and Walmart Business occupy positions defined by last-mile density and private-label breadth. Staples Business Advantage and Office Depot Inc. exemplify the account-managed archetype, layering procurement consulting onto digital portals for mid-market enterprise accounts. Sysco Shop anchors the foodservice-specialist segment, where temperature-logging integration creates defensible positioning for perishable goods procurement.
| Leading Market Players |
|---|
| Amazon Business |
| Walmart Business |
| Staples Business Advantage |
| The Kroger Co |
| W.W. Grainger Inc. |
| Office Depot Inc. |
| Home Depot Pro |
| Thomasnet |
| Sysco Shop |
| Others |
Pricing and Supply Chain Analysis
Ohio's manufacturing corridor warehouse density creates procurement leverage for bulk buyers negotiating volume-tiered contracts, compressing margins for distributors lacking comparable fulfillment infrastructure. FTC scrutiny of most-favored-nation clauses constrains supplier flexibility to offer differentiated rates across competing B2B marketplaces, reinforcing price transparency.
Pricing Analysis
Cost-plus contracts indexed to freight fuel surcharges dominate bulk consumables procurement, with three-tier pricing structure across premium, standard, and economy levels separating enterprise accounts with dedicated account management from self-service portal users. Price differentiation hinges on API integration depth and real-time inventory visibility rather than catalog breadth alone. Pricing pressure stems from Amazon Business fulfillment density enabling same-day delivery at scale, forcing mid-market distributors toward subscription frameworks to capture predictable reordering revenue. Independent convenience stores exhibit highest price sensitivity due to constrained working capital, while regional restaurant chains prioritize temperature-logging visibility over marginal cost savings.
Supply Chain Analysis
Third-party logistics providers concentrated in Illinois and Michigan hold contract-manufacturing capacity for temperature-controlled fulfillment, with regional cold-chain operators expanding cross-border into Ontario to serve PIPEDA-compliant Canadian buyers. Raw material dependencies center on packaging substrates, diesel fuel for last-mile delivery, and cloud computing infrastructure for platform operations. Supply chain risk concentrates in single-source vulnerability for specialized API developers combining FMCG domain knowledge with full-stack architecture expertise. Distribution runs through centralized e-procurement portals that aggregate spend data for negotiated tier pricing, displacing decentralized purchasing authority across multi-location operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as regional restaurant chains and independent convenience stores consolidate vendor relationships onto single platforms, fragmenting supplier pricing power across competing marketplaces.
For Market Incumbents: Insulate margin position by deepening Canadian infrastructure investments ahead of PIPEDA enforcement intensification, and acquire mid-market API development shops to address specialized talent scarcity threatening platform connectivity timelines. Threat of digitally native competitors with headless commerce architectures demands accelerated ERP replacement programs for legacy distributor networks. For New Entrants and Emerging Players: Jalisco-based wholesale markets in Mexico offer underpenetrated B2B e-commerce positioning for platforms with Spanish-language interfaces and peso-denominated trade credit, bypassing entrenched US Midwest competition. Target regional foodservice chains abandoning phone-based ordering for dashboard-driven procurement with integrated temperature-logging visibility. Go-to-market angle should emphasize subscription frameworks for janitorial supplies and office consumables capturing predictable margin pools. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors foodservice-specialist distributors with integrated Canadian operations absorbing PIPEDA compliance costs faster than pure-play technology vendors. Long-term viability rests on API-first architecture investments enabling real-time inventory synchronization across buyer platforms. Signal to watch is FTC antitrust interpretation of platform self-preferencing reshaping vendor access rules and category exclusivity terms.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | Headless commerce architectures decouple front-end interfaces from back-end systems for real-time pricing. |
| Canadian Infrastructure Expansion | PIPEDA-compliant server segmentation creates structural advantages for cross-border data handling. |
| Temperature-Controlled Logistics Integration | Cold-chain visibility convergence with procurement dashboards differentiates perishable goods distributors. |
| Subscription Framework Expansion | Automated replenishment algorithms capture margin pools through reduced customer acquisition costs. |
| Midwest Manufacturing Corridor Penetration | Ohio and Illinois factory clusters consolidate MRO supply relationships through centralized portals. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, procurement managers at regional restaurant chains, independent convenience store operators, and foodservice distribution executives; and secondary validation through SEC 10-K filings, customs and trade data, FTC antitrust dockets, and Canadian Office of the Privacy Commissioner enforcement records. Bottom-up and top-down triangulation cross-referenced platform transaction volume estimates against distributor warehouse capacity disclosures and ERP vendor implementation timelines.
Forecast inputs considered product type velocity variations, customer type procurement sophistication tiers, delivery model capital intensity profiles, and order size working capital constraints across the analysis window. Segmentation dimensions modeled include inventory turnover cycles, ERP integration complexity, fulfillment infrastructure requirements, and geographic regulatory clusters. CAGRs were derived from slope analysis of platform adoption curves and distributor technology investment cycles, incorporating temperature-controlled logistics penetration rates and subscription framework adoption patterns as industry-specific modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally native competitors with headless commerce architectures would shift outcomes beyond modeled ranges. Specific risk factors include FTC reinterpretation of most-favored-nation clauses, PIPEDA enforcement escalation requiring accelerated infrastructure investment, and API developer talent scarcity delaying platform connectivity programs. Quarterly review of antitrust docket filings, privacy commissioner enforcement actions, and distributor ERP replacement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Asia-Pacific Dropshipping Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Malta E-Commerce Market