
 Alcohol E-Commerce Market | 2026-2036
Alcohol E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol E-Commerce Market Outlook
Direct-to-consumer alcohol channels is fragmenting across competing fulfillment models. Drizly leverages its marketplace architecture to connect local retailers with on-demand buyers. Total Wine & More anchors its hybrid strategy through integrated in-store pickup and home delivery infrastructure.
Alcohol e-commerce denotes the digital sale and fulfillment of alcoholic beverages through web platforms and mobile applications, requiring real-time inventory synchronization, temperature-controlled logistics, and age-gating compliance at checkout. The primary commercial purpose centers on expanding producer and retailer reach beyond physical store footprints while capturing consumer preference data. Wine and spirits segments command premium margin pools due to higher per-unit values and subscription stickiness. Home delivery and click-and-collect models dominate transaction volume, though subscription services differentiate through curated discovery and predictable revenue streams.
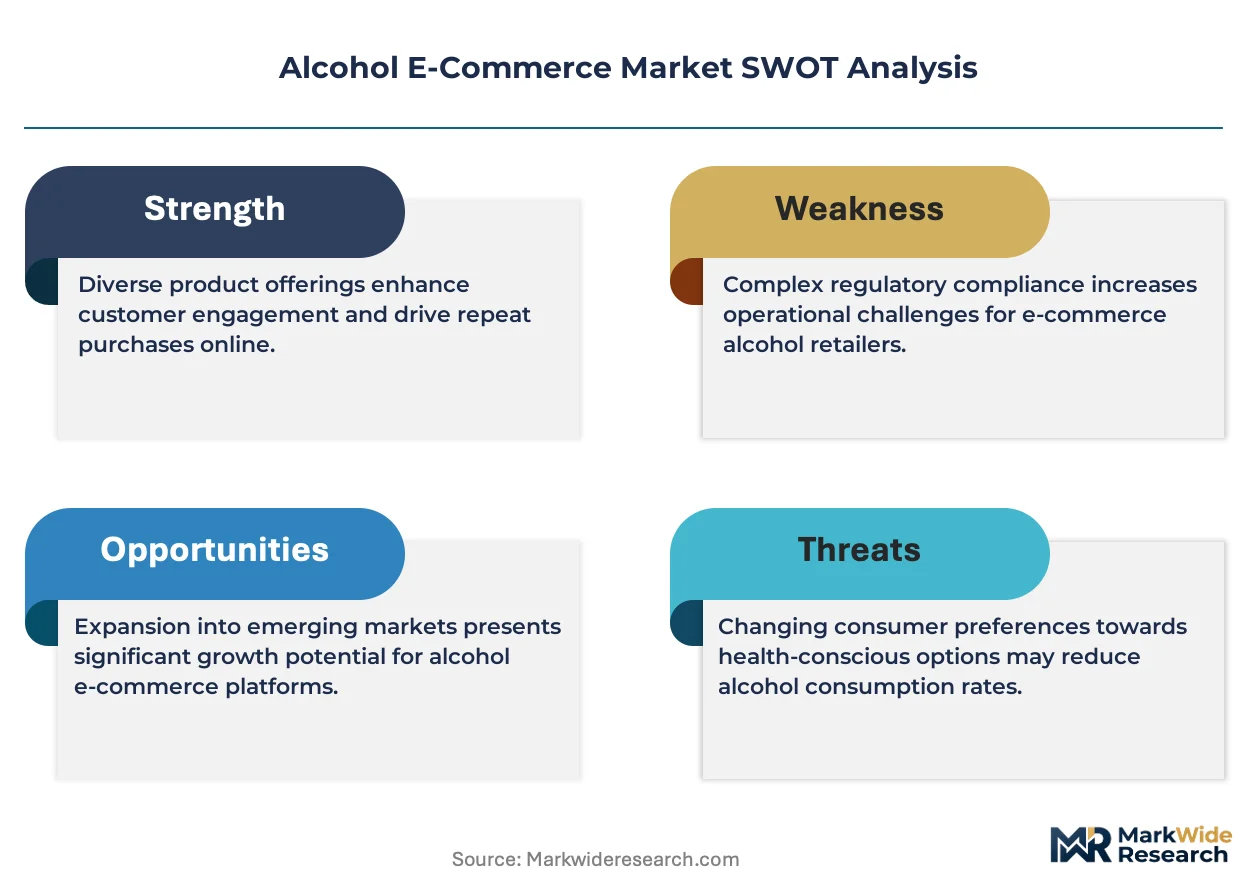
FDA guidelines on beverage labeling, state-level ABC (Alcoholic Beverage Control) licensing regimes, and the 21st Amendment's delegation of alcohol regulation to individual US states collectively shape market access and operational complexity. Compliance costs escalate for platforms shipping across state lines where direct-to-consumer statutes diverge sharply. Stakeholders must monitor pending federal legislation on interstate shipping parity and invest in modular verification stacks that adapt to jurisdictional patchwork.
Market Dynamics
State-level ABC licensing fragmentation and the 21st Amendment's delegation of alcohol authority to individual jurisdictions are forcing platforms to build modular compliance architectures that adapt to fifty distinct regulatory regimes.
Growth Catalysts
- Digital-native cohort expansion:Millennials and Gen Z consumers now constitute the dominant purchasing demographic, driving platform investment in mobile-first interfaces and subscription-based discovery models.
- Direct-to-consumer shipping liberalization:Recent statutory amendments in states like Kentucky and Pennsylvania have opened previously restricted markets, enabling winery fulfillment networks to extend their reach.
- Temperature-controlled logistics maturation:Cold-chain infrastructure investments by specialized 3PL providers are reducing spoilage rates and expanding perishable beverage categories into e-commerce channels.
Market Restraints
- Compliance cost escalation:Platforms shipping across state lines face divergent licensing fees, bond requirements, and label approval processes that compound operational overhead.
- Last-mile delivery concentration:Urban metro areas dominate profitable fulfillment zones, leaving rural and exurban markets underserved due to density economics.
- Substitution by on-premise recovery:Bars and restaurants are recapturing share as post-pandemic social consumption patterns normalize, particularly in spirits categories.
Strategic Opportunities
- AI-powered personalization engines:Machine learning recommendation systems paired with predictive inventory positioning are enabling curated subscription boxes that reduce customer acquisition costs.
- Blockchain provenance verification:Distributed ledger technologies are creating authenticated supply chain records that combat counterfeiting in premium wine and spirits segments.
- Texas and Florida market penetration:These high-population states maintain restrictive direct shipping statutes that, if liberalized, would unlock substantial addressable demand.
Industry Challenges
- Age verification technology arms race:Platforms must deploy biometric identity confirmation and document authentication systems that satisfy FDA guidelines while minimizing checkout friction.
- Interstate tax remittance complexity:Sellers face nexus determination ambiguities and excise tax calculation requirements that vary by product type, alcohol content, and destination jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol E-Commerce Market |
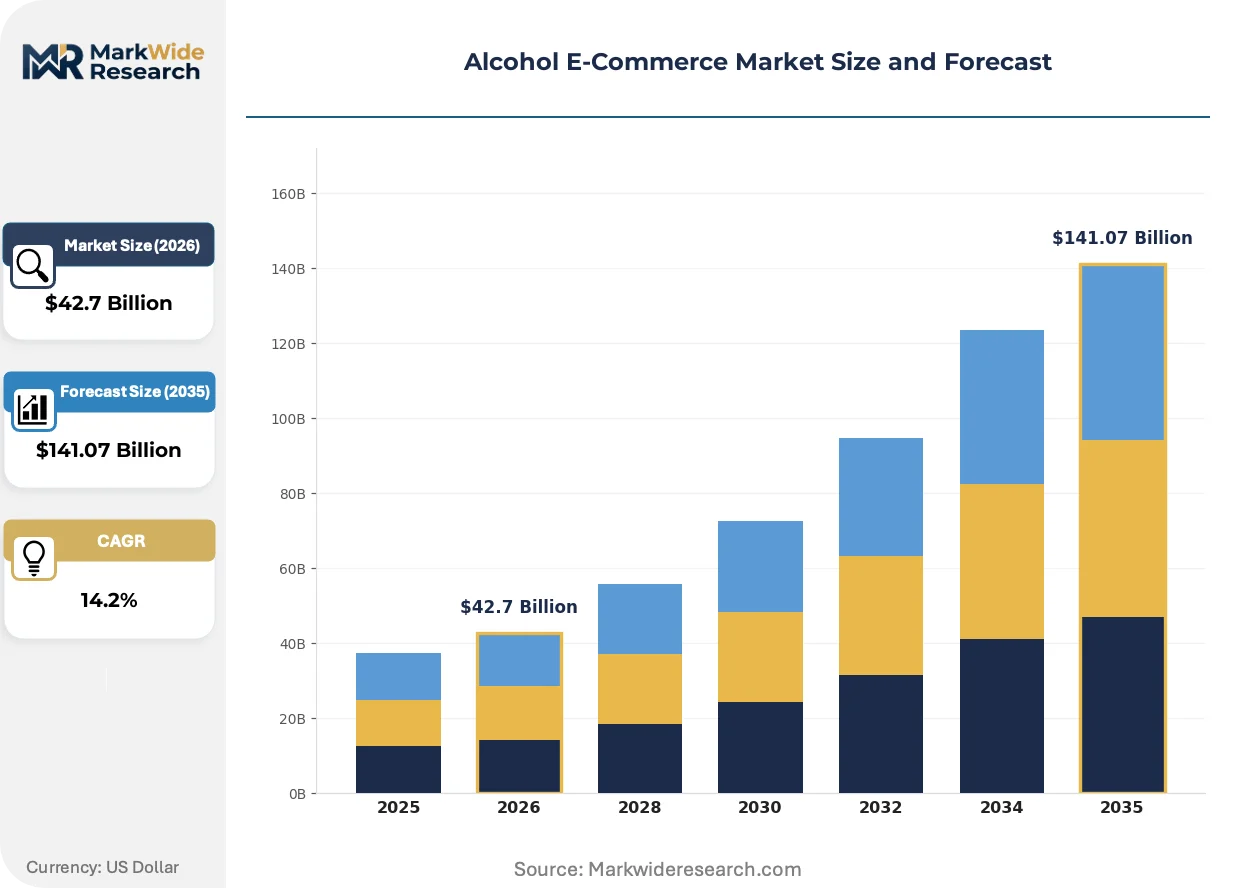
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $141.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Wine, Spirits, Cider Delivery Model: Home Delivery, In-Store Pickup, Subscription Service, Click & Collect Customer Type: Retail Consumers, Event Planners, Hospitality Businesses, Corporate Clients Payment Method: Credit Card, Digital Wallet, Bank Transfer, Gift Card |
| Companies Covered | Drizly, Total Wine & More, Wine.com, Minibar Delivery, BevMo!, Vivino, ReserveBar, Saucey, Flaviar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol E-Commerce Market Strategic Shifts
Three intersecting forces are compressing fulfillment timelines and reconfiguring platform economics: artificial intelligence is virtualizing inventory decisions, regulatory harmonization efforts are reducing cross-border friction, and buyer expectations for immediacy are reshaping last-mile infrastructure investments.
Machine learning demand forecasting is virtualizing warehouse placement and safety stock calculations across alcohol e-commerce platforms. Retailers and marketplaces are deploying predictive algorithms that anticipate regional preference shifts before they materialize. This capability is compressing working capital requirements and reducing out-of-stock incidents in high-velocity SKUs.
The FDA's evolving guidance on digital health claims and the EU's proposed updates to distance-selling regulations for alcoholic beverages are creating compliance template opportunities. Producers selling into multiple jurisdictions are consolidating label approvals and ingredient disclosures to satisfy the most stringent applicable standard. Wine exporters to Europe are adapting packaging to meet EFSA-aligned nutritional labeling requirements preemptively.
Subscription-based discovery models are displacing transactional purchasing in premium wine segments. Urban consumers in coastal US markets are committing to recurring curated deliveries that reduce decision fatigue and secure allocation-limited releases. This behavioral shift is concentrating lifetime value in predictable revenue streams and reducing platform dependence on paid acquisition channels.
Alcohol E-Commerce Market Segmentation
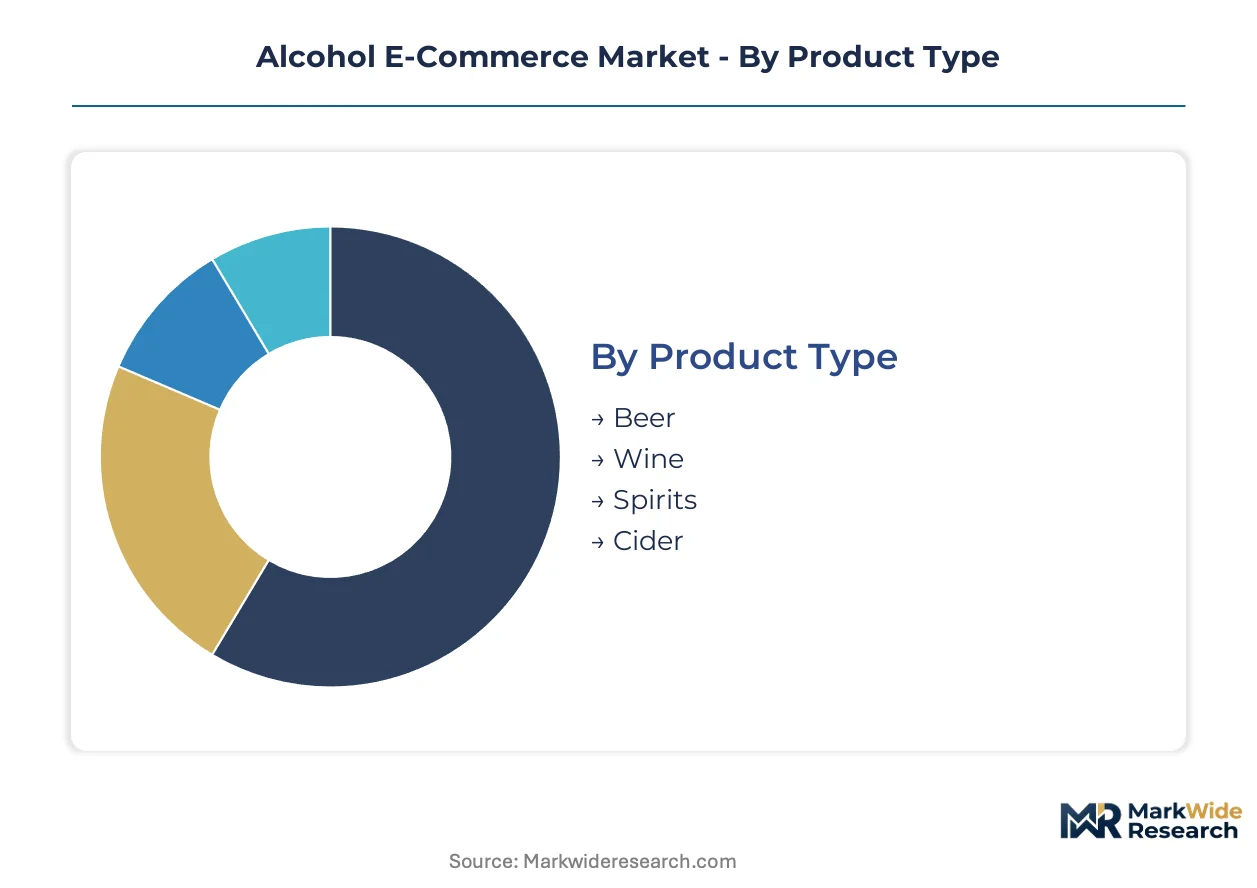
Segmentation in alcohol e-commerce reveals how fulfillment constraints and regulatory complexity fragment addressable demand. Platforms must architect distinct operational stacks for each product category and delivery modality while navigating divergent compliance requirements across customer types.
Product Type:
Margin profiles and temperature sensitivity diverge sharply across beverage categories, dictating divergent logistics investments and platform economics.
- Wine:Higher per-unit values justify specialized cold-chain fulfillment and subscription curation models. Direct-to-consumer shipping statutes in California, New York, and Oregon anchor volume concentration, though interstate licensing fragmentation constrains platform expansion into restrictive jurisdictions.
- Spirits:Premium SKUs command subscription stickiness and gift-giving velocity, with bourbon and single-malt whisky segments driving repeat purchase rates. Kentucky and Tennessee producers leverage recent statutory liberalization to extend direct fulfillment reach previously blocked by three-tier system constraints.
- Beer:Perishable inventory cycles and weight-driven shipping economics favor hyperlocal fulfillment networks anchored to urban metro density.
- Cider:Seasonal demand spikes and regional producer fragmentation create marketplace aggregation opportunities in Pacific Northwest and New England clusters.
Wine commands the established base. The steepest expansion runs through spirits subscription channels.
Delivery Model:
Customer proximity to fulfillment infrastructure determines service viability and unit economics across each modality.
- Home Delivery:Same-day and scheduled drop-off services require real-time inventory synchronization with licensed retailer networks. Urban density in Chicago, Los Angeles, and Miami enables profitable last-mile economics, while exurban zones remain underserved due to minimum order thresholds and delivery radius constraints.
- Subscription Service:Curated discovery boxes with predictive personalization reduce customer acquisition costs and secure allocation-limited releases. Coastal California and New York metropolitan consumers demonstrate highest lifetime value concentration in recurring revenue streams.
- In-Store Pickup:Hybrid fulfillment leverages existing licensed retail footprints to bypass direct shipping restrictions in controlled states.
- Click & Collect:Appointment-based retrieval from dedicated fulfillment centers reduces checkout friction for bulk purchases.
Home delivery anchors current transaction volume. Subscription services are gaining share fastest through retention economics.
Customer Type:
Purchasing scale and compliance documentation requirements stratify platform service tiers and account management intensity.
- Retail Consumers:Individual buyers drive mobile-first interface investments and age-verification technology deployment. Millennial and Gen Z cohorts in Texas and Florida concentrate demand despite restrictive direct shipping statutes that force marketplace rather than winery-direct fulfillment.
- Hospitality Businesses:Restaurants, bars, and hotels require volume pricing, invoice terms, and license verification at scale. Wholesale licensing regimes in Illinois and Massachusetts create distinct procurement workflows from consumer-facing channels.
- Event Planners:Time-bound bulk orders with specific delivery windows stress inventory allocation systems.
- Corporate Clients:Gifting programs and executive hospitality procurement demand white-label packaging and compliance documentation.
Retail consumers represent the volume foundation. Hospitality businesses are expanding most quickly as on-premise recovery extends procurement digitization.
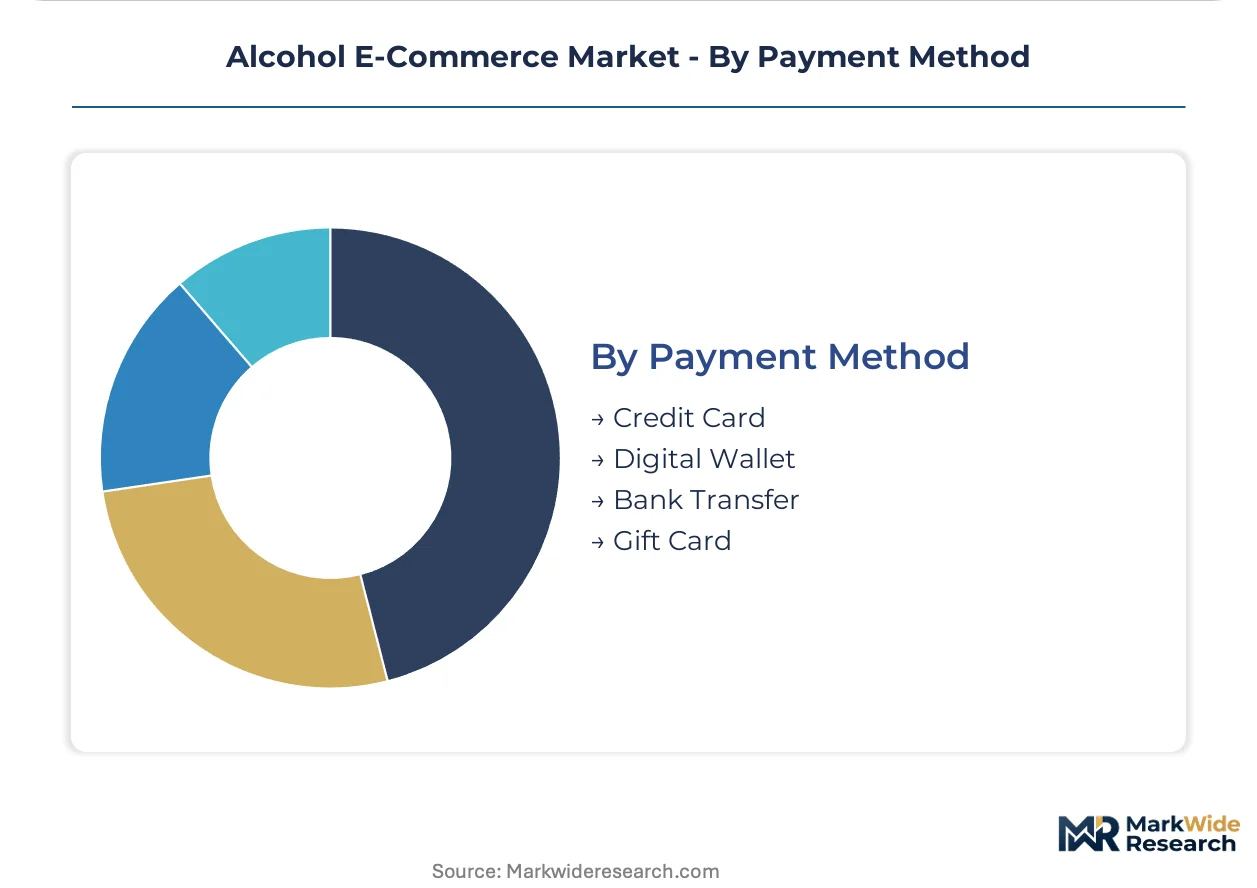
Payment Method:
Chargeback risk and age-verification audit trails shape platform payment stack configuration and fraud prevention investment.
- Credit Card:Dominant transaction rails with embedded age verification through issuer data matching. Visa and Mastercard network standards impose compliance documentation requirements that platforms must satisfy for merchant category code approval in alcohol sales.
- Digital Wallet:Apple Pay and Google Pay adoption accelerates mobile checkout conversion through biometric authentication layers that satisfy FDA-aligned identity confirmation standards.
- Bank Transfer:ACH rails reduce interchange costs for high-value corporate and hospitality accounts.
- Gift Card:Prepaid instruments extend purchase occasion reach while requiring secondary age verification at redemption.
Credit card infrastructure holds the incumbent position. Digital wallets are climbing the fastest through mobile-native cohort preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's direct-to-consumer wine shipping infrastructure commands premium pricing power over Texas, where restrictive ABC statutes force marketplace intermediation and compress producer margins.
United States
Millennial and Gen Z consumers in New York and California drive mobile-first platform adoption, while the 21st Amendment's state-level delegation forces modular compliance architectures. FDA-aligned age verification standards intersect with divergent state ABC licensing regimes. Chicago and Los Angeles anchor profitable last-mile delivery zones where urban density enables same-day fulfillment economics.
United Kingdom
London's metropolitan concentration supports subscription curation models for premium wine discovery, with consumer willingness to pay for predictive personalization rising fastest in the Southeast. HMRC excise duty frameworks and distance-selling regulations shape cross-border fulfillment complexity. The Manchester-Liverpool corridor hosts emerging cold-chain logistics investments targeting perishable beverage categories.
Germany
Bavaria's brewery density and Baden-Württemberg's wine production create fragmented supplier bases that favor marketplace aggregation models. EFSA-aligned nutritional labeling requirements and BfR beverage container regulations impose pre-market compliance costs. Berlin's tech ecosystem incubates AI-powered inventory forecasting startups serving centralized retail procurement.
France
Île-de-France's executive hospitality procurement digitization expands B2B platform penetration, while Provence-Alpes-Côte d'Azur's tourism economy sustains gift-giving velocity in premium spirits. ANSM labeling oversight and DGCCRF distance-selling enforcement create audit trail requirements. The Bordeaux wine cluster experiments with blockchain provenance verification for export authentication.
Australia
New South Wales and Victoria concentrate direct-to-consumer winery fulfillment adoption, with Sydney and Melbourne consumers demonstrating highest subscription retention rates. FSANZ beverage standards and state-level liquor licensing fragmentation mirror US jurisdictional complexity. The Barossa Valley producer network invests in temperature-controlled 3PL partnerships to extend e-commerce reach into Asian export markets.
Alcohol E-Commerce Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in age-verification stacks and cold-chain logistics. The vendor base clusters around three functional layers: marketplace aggregators connecting licensed retailers with on-demand demand, hybrid retailers blending physical inventory with digital fulfillment, and subscription curators capturing lifetime value through predictive personalization. Consolidation pressure concentrates in the marketplace tier where network effects reward scale, while vertical integration moves target captive supply of temperature-controlled last-mile capacity.
Within the marketplace aggregation tier, Drizly and Minibar Delivery occupy positions that exemplify the local retailer connection model, while Wine.com anchors the direct fulfillment archetype for winery-to-consumer channels. These named entities represent strategic poles rather than exhaustive enumeration, with each archetype commanding distinct compliance cost structures and margin profiles based on licensing posture and inventory ownership.
| Leading Market Players |
|---|
| Drizly |
| Total Wine & More |
| Wine.com |
| Minibar Delivery |
| BevMo! |
| Vivino |
| ReserveBar |
| Saucey |
| Flaviar |
| Others |
Value Chain & Pricing Dynamics
Napa Valley's temperature-controlled fulfillment capacity anchors premium wine pricing power through scarcity-driven allocation models, while Texas and Florida's restrictive ABC statutes force marketplace intermediation that compresses producer margins and elevates platform take rates.
Pricing Analysis
Configured-to-order subscription curation commands 35-50% premiums over standard transactional pricing in premium wine segments. Three-tier pricing structure across allocation-limited releases, mid-tier discovery boxes, and economy retail SKUs stratifies buyer access. Cost compression in economy tiers intensifies because Drizly-style marketplace models aggregate commoditized inventory. Hospitality buyers demonstrate highest price sensitivity due to volume procurement workflows, while corporate gifting clients show lowest sensitivity.
Supply Chain Analysis
ITAR-aligned biometric verification export controls limit age-authentication technology flows to certain jurisdictions, constraining platform compliance stack standardization. Supply concentrates in California's winery-direct infrastructure, Kentucky's spirits fulfillment networks, and Washington state's cold-chain 3PL hubs. Raw material dependencies span temperature-controlled packaging, specialized ethylene-vinyl acetate liners, and blockchain-enabled provenance tags. Single-source vulnerability runs through concentrated third-party logistics providers in urban metro zones. Distribution runs through hybrid marketplace-retailer channels rather than pure direct-to-consumer pipes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alcohol e-commerce functions as a regulatory-moat market where state-level licensing entrenchment creates switching costs that protect incumbent platform economics from price-based disruption.
For Market Incumbents: Build compliance-modularity moats by investing in API-first age-verification stacks that adapt to fifty-state regulatory patchwork. Deepen backward integration into captive cold-chain last-mile capacity in Chicago and Los Angeles to defend against specialized 3PL margin capture. Counter emerging entrant threat from AI-native curation startups by locking exclusive allocation-limited releases through multi-year producer contracts.
For New Entrants and Emerging Players: Texas underpenetration offers the most penetrable white-space target given recent statutory liberalization momentum and 30 million resident demand concentration. Target Florida's similarly restrictive market through hospitality-B2B procurement digitization rather than consumer-direct channels. Pursue white-label age-verification licensing to incumbent marketplaces as lowest-friction go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a subscription-retention play because recurring revenue concentration in curated discovery boxes reduces customer acquisition cost dependence. Acquisition target archetype: AI-powered personalization engines with demonstrated cohort retention lift. Monitor interstate shipping parity legislation as primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Age-Verification Stack Deployment | FDA-aligned identity confirmation reduces checkout friction while satisfying ABC audit requirements. |
| Cold-Chain 3PL Partnership | Temperature-controlled logistics partnerships with specialized providers reduce perishable spoilage rates. |
| AI-Powered Curation Engine | Machine learning recommendation systems secure allocation-limited releases for high-lifetime-value subscribers. |
| Interstate Licensing Modularization | API-first compliance architectures adapt to divergent state ABC bond requirements and label approvals. |
| Blockchain Provenance Verification | Distributed ledger authentication combats counterfeiting in premium bourbon and single-malt whisky segments. |
Study Parameters
Cross-validation between executive interviews with alcohol e-commerce platform operators and secondary analysis of state ABC regulatory filings anchors the qualitative findings. Primary fieldwork encompassed marketplace technology leads, winery direct-to-consumer directors, cold-chain logistics operators, and hospitality procurement managers. Secondary sources included FDA guidance documents, state liquor control board enforcement data, SEC 10-K disclosures from publicly traded retailers, and trade association shipping reports. Bottom-up transaction volume estimates and top-down addressable market sizing underwent iterative reconciliation.
Calibration against historical direct-to-consumer wine shipment volumes and spirits subscription retention curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product category, delivery modality, customer type, and state regulatory cluster. CAGRs derived from logistic adoption curves fitted to digital-native cohort penetration patterns. Forecast inputs incorporated temperature-controlled logistics cost trajectories and pending federal interstate shipping parity legislation probability.
Practitioners should monitor state-level ABC statute amendments and biometric verification technology cost curves for early signals. Forecasts reflect assumptions regarding regulatory fragmentation persistence and Millennial/Gen Z purchasing share expansion. Material shifts in federal 21st Amendment reinterpretation or cold-chain infrastructure investment cycles would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
E-Commerce Logistics Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Iceland E-Commerce Market
E-Commerce Solutions
China Alcohol E-Commerce Market