
 Norway E-Commerce Market | 2026-2036
Norway E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Norway E-Commerce Market Outlook
Sweden's Nordic logistics corridor is fragmenting as cross-border fulfillment networks compete for Norwegian market share. Komplett AS anchors its position through deep specialization in consumer electronics verticals. Elkjøp Norge AS leverages its brick-and-mortar footprint to sustain hybrid click-and-collect density across Norwegian population centers. Zalando SE differentiates through fashion-focused platform algorithms and localized return infrastructure.
Norway E-Commerce encompasses digitally mediated transactions for goods and services, executed through web interfaces and mobile applications with integrated payment gateways, inventory management systems, and last-mile delivery orchestration. The ecosystem serves both consumer convenience and enterprise procurement efficiency through automated order processing and real-time stock visibility. Electronics and clothing categories dominate transaction volumes, with electronics commanding higher average order values and clothing driving repeat purchase frequency. Marketplaces as a sales channel capture substantial traffic aggregation, while direct sales models retain margin control for established Nordic brands.
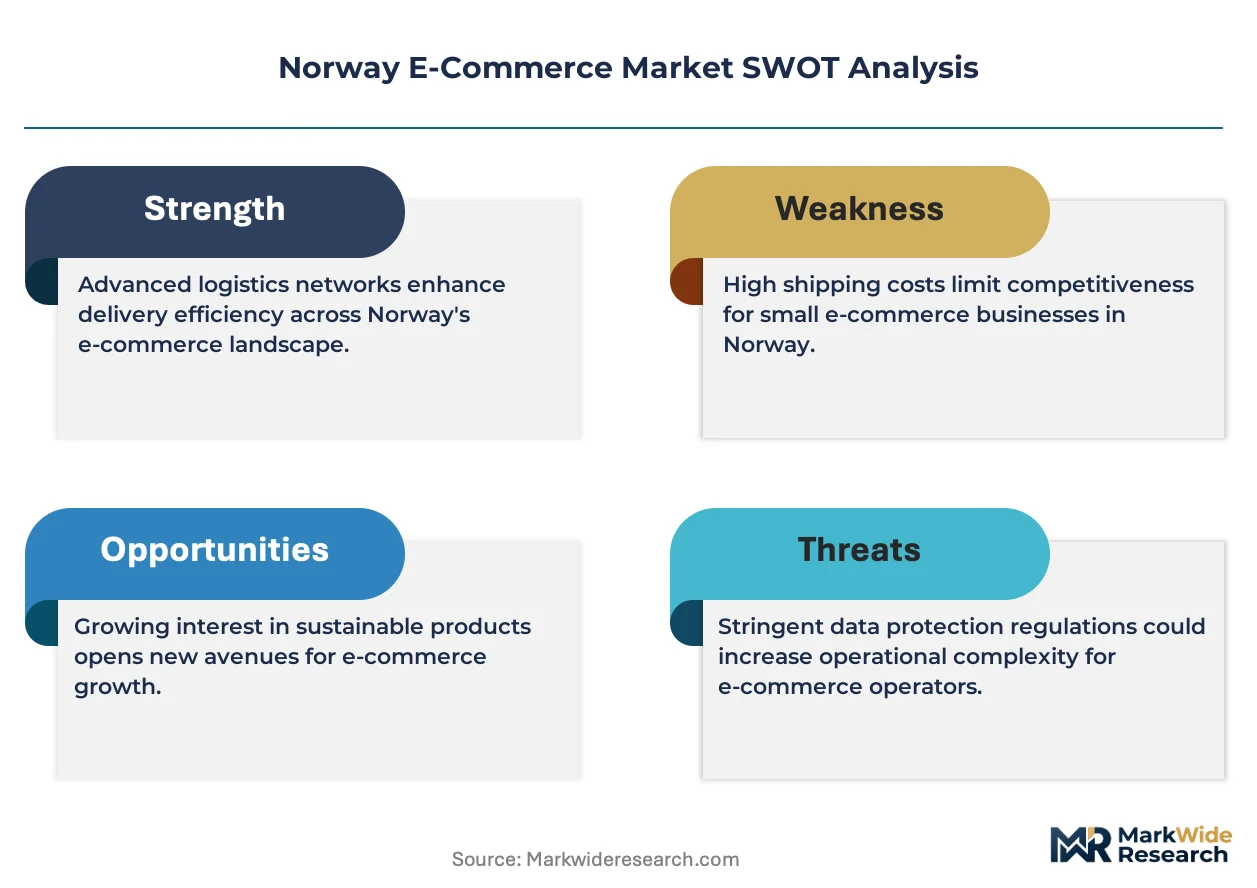
The Norwegian Data Protection Authority enforces GDPR-aligned consumer privacy mandates that constrain platform data harvesting and retargeting precision. Norway's Consumer Council supplements this framework through aggressive scrutiny of dark pattern interfaces and subscription trap mechanisms. Stakeholders must monitor evolving enforcement intensity around algorithmic pricing transparency and cross-border VAT compliance as regulatory attention shifts from data collection toward transactional fairness.
Market Dynamics
Norwegian grocery shoppers are migrating online at accelerating velocity, compressing traditional retail foot traffic while GDPR-aligned enforcement from the national data protection authority constrains platform data harvesting capabilities.
Growth Catalysts
- Urban Logistics Density:Oslo's metropolitan corridor concentrates affluent households and same-day delivery infrastructure, creating self-reinforcing network effects for premium digital retail services.
- GDPR Enforcement Intensity:The Norwegian Data Protection Authority's strict interpretation of consumer privacy mandates forces platforms to innovate consent-based personalization, differentiating compliant operators.
- Electronics Vertical Specialization:Deep category expertise in consumer electronics generates higher average order values and repeat purchase loyalty compared to generalist marketplaces.
Market Restraints
- Cross-Border VAT Complexity:Norwegian customs procedures and distance-selling thresholds create administrative friction for international marketplace sellers.
- Last-Mile Geography:Fjord-indented terrain and dispersed rural populations inflate delivery costs beyond metropolitan corridors.
- Data Retargeting Limitations:GDPR-aligned constraints on third-party cookies and device fingerprinting degrade conversion optimization precision for performance marketing.
Strategic Opportunities
- Hybrid Click-and-Collect Expansion:Brick-and-mortar footprint integration enables inventory pooling and reduced last-mile costs in secondary Norwegian cities.
- Subscription Commerce Models:Recurring revenue frameworks for groceries and personal care products lock in customer lifetime value while smoothing demand forecasting.
- Green Logistics Certification:EU Green Deal-aligned carbon disclosure requirements favor early adopters of electric delivery fleets and circular packaging systems.
Industry Challenges
- Algorithmic Pricing Transparency:The Norwegian Consumer Council's scrutiny of dynamic pricing interfaces demands explainable automation and audit trails.
- Legacy ERP Integration:Established Nordic retailers face friction connecting modern marketplace APIs to decades-old inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway E-Commerce Market |
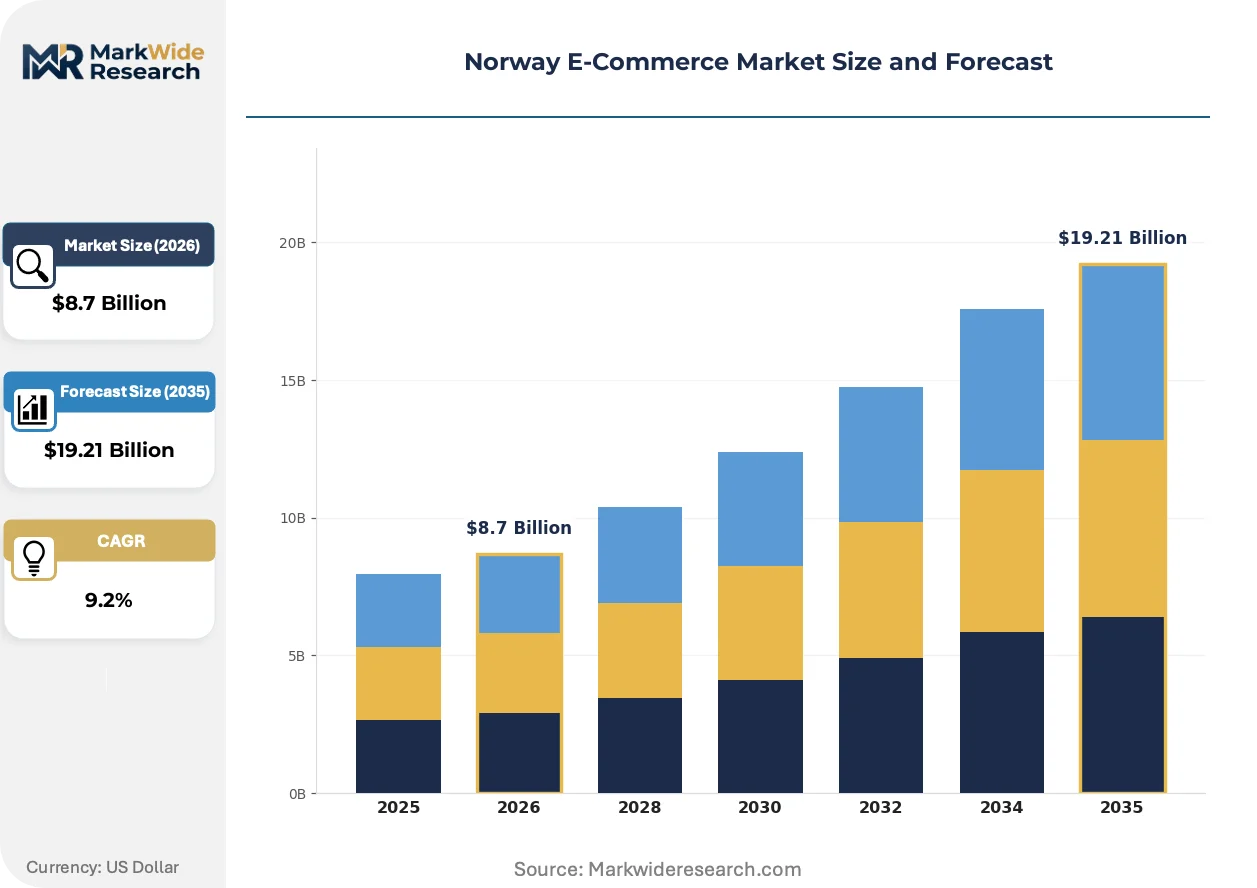
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Clothing, Beauty, Home Goods Customer Type: Consumers, Businesses, Government, Non-profits Payment Method: Credit Card, PayPal, Bank Transfer, Cash on Delivery Sales Channel: Direct Sales, Marketplaces, Social Media, Mobile Apps |
| Companies Covered | Elkjøp Norge AS, Komplett AS, Prisjakt Sverige AB, Zalando SE, Finn.no, Oda (Kolonial.no), XXL ASA, H&M Hennes and Mauritz AB, IKEA Norge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway E-Commerce Market Strategic Shifts
Platform operators are reconfiguring around privacy-preserving personalization and sustainable fulfillment as regulatory and consumer pressure intensifies.
Artificial intelligence-driven demand forecasting is collapsing inventory holding requirements for Norwegian fashion and electronics retailers. Mid-market direct-to-consumer brands are adopting these tools fastest, compressing working capital cycles from ninety days to under thirty while maintaining stock availability.
The Norwegian Consumer Council's enforcement against dark pattern interfaces is reshaping checkout design standards. Subscription trap mechanisms and forced account creation now trigger formal complaints, pushing platforms toward transparent guest checkout flows. Fashion marketplaces with complex return policies face the steepest redesign costs.
Consolidated grocery procurement through dedicated apps is fragmenting traditional supermarket loyalty. Oslo households now split weekly purchases across three to four specialized platforms rather than single-store baskets. This behavior concentrates in dual-income households with limited weekend availability for physical shopping.
Norway E-Commerce Market Segmentation
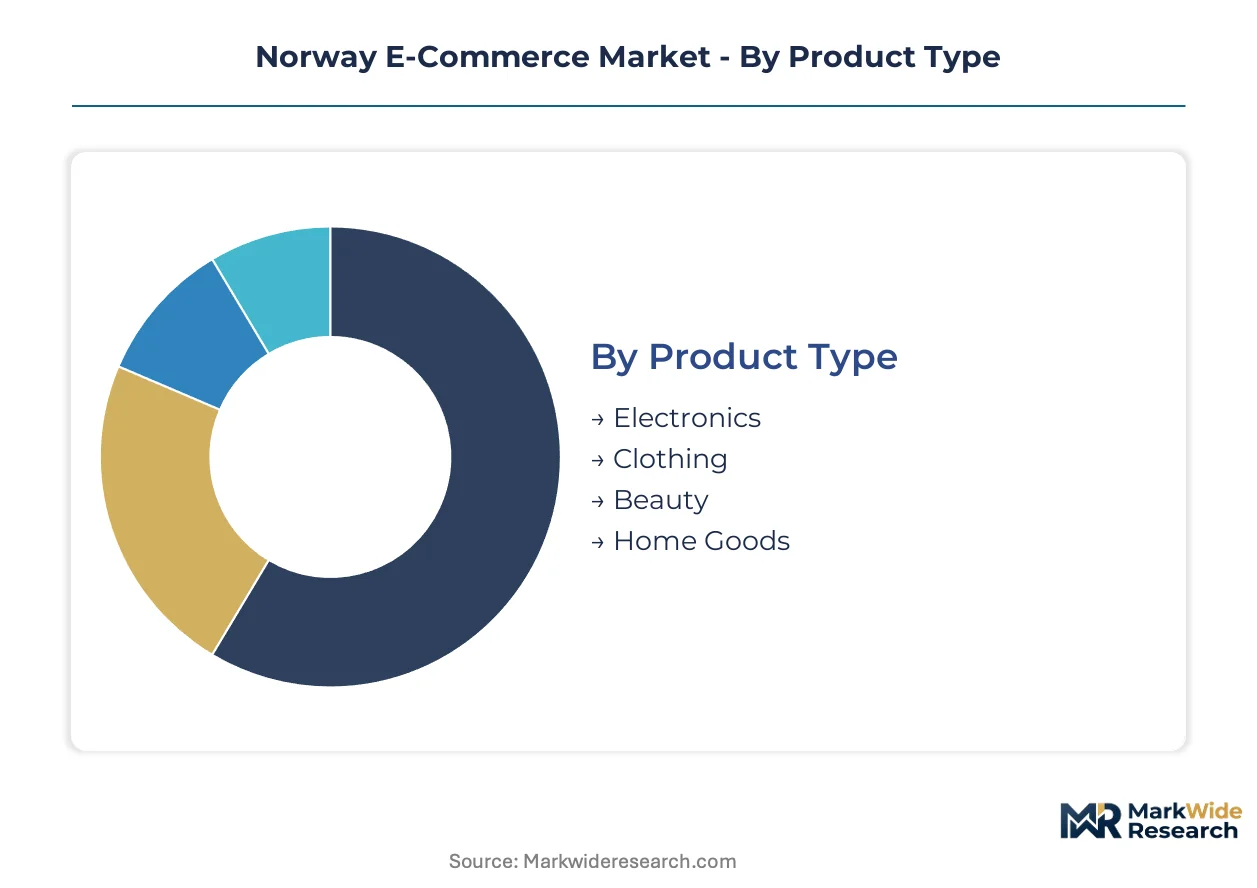
E-commerce segmentation in Norway reveals how platform architecture, payment infrastructure, and fulfillment density concentrate around distinct use-case profiles. Understanding these divides clarifies where Oslo's metropolitan corridor generates disproportionate transaction velocity versus where rural dispersion inflates unit economics.
Product Type:
Consumer electronics and fashion command divergent logistics requirements, with high-value durable goods demanding secure handling and apparel requiring flexible return processing.
- Electronics:Consumer electronics encompasses smartphones, laptops, and home entertainment systems with elevated average order values and extended warranty considerations. Oslo households drive disproportionate demand for same-day delivery of high-ticket items, constrained by the Norwegian Data Protection Authority's limits on purchase-history retargeting.
- Clothing:Fashion retail operates on compressed trend cycles with elevated return rates necessitating localized reverse logistics infrastructure. Bergen and Stavanger shoppers favor free-return policies that compress margin structures for pure-play digital retailers.
- Beauty:Cosmetics and personal care products require temperature-controlled fulfillment for premium skincare formulations.
- Home Goods:Furniture and décor categories face last-mile complexity from fjord-indented geography outside metropolitan corridors.
Established volume favors electronics; emerging adoption favors beauty subscription models.
Customer Type:
Procurement patterns diverge sharply between individual convenience-driven purchasing and institutional volume contracting with invoice-based settlement terms.
- Consumers:Individual shoppers prioritize mobile-optimized checkout flows and flexible delivery windows, with dual-income Oslo households splitting weekly purchases across multiple specialized platforms rather than single-store baskets.
- Businesses:B2B procurement emphasizes punchout catalog integration and volume-based pricing tiers with net-30 payment terms, concentrated in Trondheim's manufacturing corridor and Stavanger's energy sector.
- Government:Public sector purchasing follows strict tender procedures with mandatory e-invoicing compliance under Norwegian accounting standards.
- Non-profits:Charitable organizations leverage tax-exempt status with specialized donation-processing gateways.
Consumer transactions dominate transaction frequency; business procurement commands the highest average order values.
Payment Method:
Settlement infrastructure reflects Norway's high card penetration alongside residual preference for invoice-based alternatives in B2B contexts.
- Credit Card:Card-present and tokenized digital transactions dominate consumer purchases, with Norwegian banks issuing contactless-enabled debit cards as default payment instruments.
- PayPal:Cross-border marketplace purchases favor this wallet for buyer protection guarantees on international seller transactions.
- Bank Transfer:Direct account debits persist for high-value B2B settlements and invoice-based government procurement.
- Cash on Delivery:Limited rural penetration remains where digital banking access lags, concentrated in northern county remote settlements.
Credit card settlement anchors consumer convenience; bank transfer retains institutional preference.
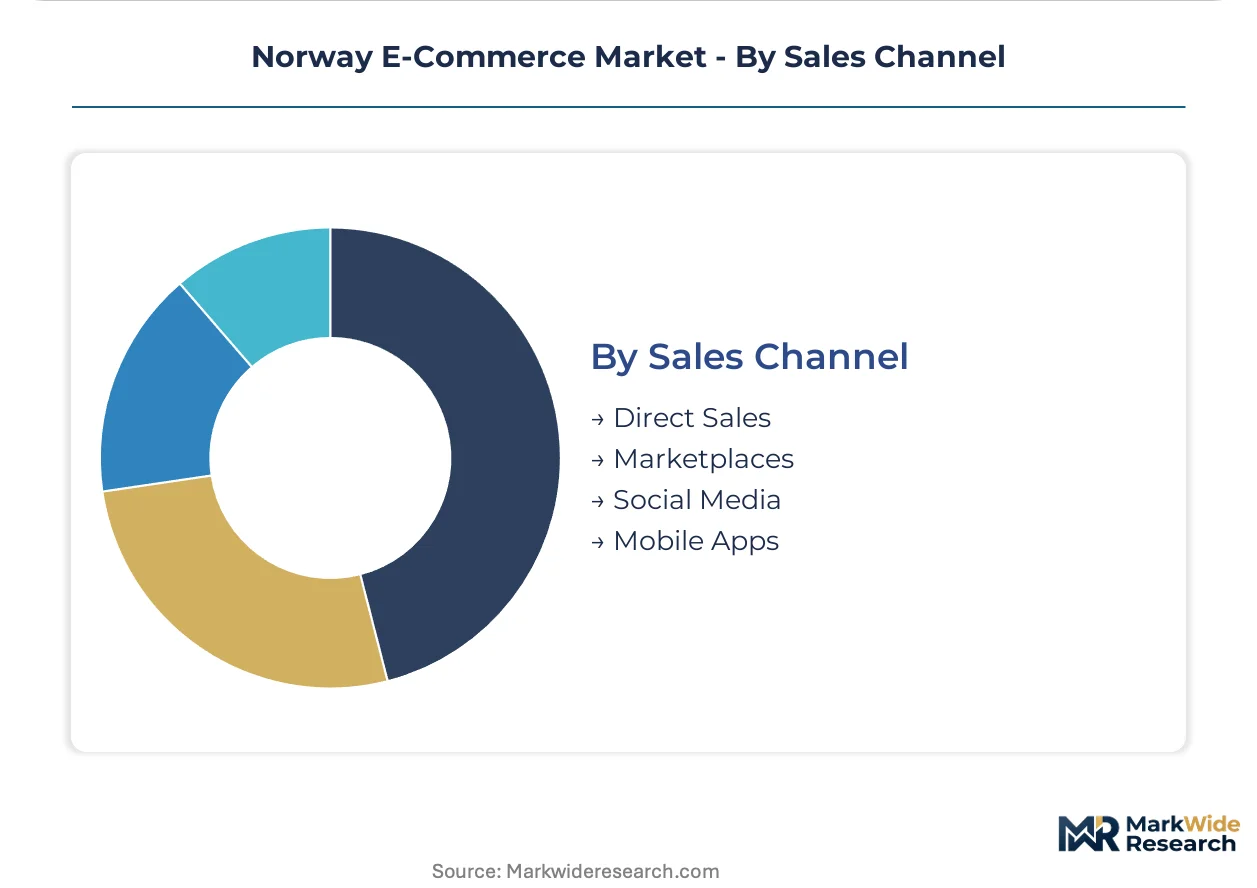
Sales Channel:
Traffic aggregation and margin control trade off across platform architectures, with marketplace density competing against direct-brand relationship building.
- Direct Sales:Brand-controlled websites capture full margin and first-party customer data, with established Nordic retailers investing in loyalty program infrastructure to offset GDPR-constrained retargeting capabilities.
- Marketplaces:Aggregator platforms concentrate discovery traffic and fulfillment scale, though commission structures compress net margins for third-party sellers navigating cross-border VAT complexity.
- Social Media:Shoppable content integrates discovery and transaction within feed-based browsing, gaining traction among younger demographics in urban centers.
- Mobile Apps:Dedicated applications enable push-notification re-engagement and streamlined biometric checkout, with grocery platforms capturing highest install rates among Oslo households.
Marketplace density concentrates discovery traffic; mobile apps are climbing the fastest for retention-driven categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norwegian Data Protection Authority enforces GDPR-aligned privacy mandates that constrain data harvesting across all sub-regions, while Oslo's metropolitan corridor concentrates fulfillment infrastructure and affluent household density that drives premium digital retail adoption.
Oslo Metropolitan Corridor
Dual-income households in Oslo, Bærum, and Lillestrøm split weekly purchases across three to four specialized grocery platforms rather than single-store baskets. The Norwegian Consumer Council scrutinizes dark pattern interfaces and subscription trap mechanisms in checkout flows across this corridor. Same-day delivery density reaches highest saturation in Oslo's core districts, where electric fleet operators capture Green Deal-aligned procurement preferences from municipal buyers.
Bergen and Western Norway
Fjord-indented terrain inflates last-mile costs beyond metropolitan corridors, yet free-return policies for fashion retail concentrate demand in Bergen and Stavanger. GDPR enforcement from the national data protection authority limits purchase-history retargeting for electronics retailers serving this sub-region. Localized reverse logistics infrastructure for apparel returns operates from Stavanger distribution nodes, compressing margin structures for pure-play digital operators.
Trondheim and Central Norway
B2B procurement for manufacturing and energy sector buyers emphasizes punchout catalog integration with net-30 payment terms. The Norwegian Data Protection Authority's strict interpretation of consent-based personalization forces platform operators to redesign customer data architectures. Trondheim's manufacturing corridor anchors institutional purchasing volume, though legacy ERP integration friction slows marketplace API adoption among established Nordic suppliers.
Tromsø and Northern Norway
Limited rural penetration of digital banking infrastructure sustains residual cash-on-delivery settlement in remote northern county settlements. Cross-border VAT complexity from Norwegian customs procedures creates administrative friction for international marketplace sellers reaching this sub-region. Temperature-controlled fulfillment for premium skincare formulations requires specialized logistics partnerships that few platforms maintain at viable unit economics.
Southern Norway
Kristiansand and surrounding population centers support hybrid click-and-collect expansion from brick-and-mortar footprints, enabling inventory pooling and reduced last-mile costs. The Norwegian Consumer Council's enforcement against algorithmic pricing transparency demands explainable automation and audit trails from platforms operating here. Mobile app install rates for grocery platforms climb fastest among dual-income households with limited weekend availability for physical shopping.
Norway E-Commerce Market Competitive Environment
Capability concentration sits with specialized vertical players; scale advantage sits with cross-border marketplace operators. The vendor base organizes around three tiers: domestic electronics specialists with deep category expertise, Nordic hybrid retailers leveraging physical footprint density, and European fashion platforms with localized return infrastructure. Consolidation pressure intensifies as GDPR-constrained retargeting capabilities erode performance marketing efficiency for generalist operators. Dominant competitive moves include hybrid click-and-collect network expansion and subscription commerce model deployment for recurring revenue capture.
Among domestic electronics specialists, Komplett AS anchors the vertical expertise tier through consumer electronics specialization that generates higher average order values than generalist alternatives. Elkjøp Norge AS occupies the hybrid retail position, leveraging brick-and-mortar footprint density to sustain click-and-collect services across Norwegian population centers. Zalando SE represents the cross-border marketplace archetype, differentiating through fashion-focused platform algorithms and localized return infrastructure that addresses elevated apparel return rates in Bergen and Stavanger.
| Leading Market Players |
|---|
| Elkjøp Norge AS |
| Komplett AS |
| Prisjakt Sverige AB |
| Zalando SE |
| Finn.no |
| Oda (Kolonial.no) |
| XXL ASA |
| H&M Hennes and Mauritz AB |
| IKEA Norge |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Oslo's same-day delivery infrastructure drives premium pricing for expedited fulfillment while forcing platforms to absorb higher per-unit logistics costs in secondary corridors. This utilization squeeze compresses margins for nationwide operators attempting uniform pricing across Norway's divergent geography.
Pricing Analysis
Metropolitan-rural price spreads of 15-25% separate Oslo's dense delivery zones from fjord-indented peripheries where unit economics collapse. Three-tier pricing structure across premium same-day, standard next-day, and economy consolidated delivery levels dominates platform offerings. Pricing pressure stems from free-return policies in fashion retail that concentrate demand in Bergen and Stavanger. Small-town households exhibit highest price sensitivity; Oslo dual-income professionals show lowest elasticity for convenience premiums.
Supply Chain Analysis
Extended payment terms from 30 to 60 days now characterize supplier relationships as platforms seek working capital relief. Fulfillment infrastructure draws from Sweden, Denmark, and Germany for automated warehousing equipment and last-mile fleet vehicles. Warehouse management systems, electric delivery vans, and temperature-controlled packaging constitute critical input dependencies. Single-source vulnerability concentrates in cross-border parcel consolidation hubs serving Norwegian customs clearance. Distribution runs through Oslo metropolitan nodes before radiating to regional spokes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian e-commerce fragmentation creates acquisition opportunities as grocery shoppers split purchases across specialized platforms rather than consolidating with single retailers. This demand-side unbundling generates niche white-space for focused operators.
For Market Incumbents: Harden defensible positions by deepening vertical integration into temperature-controlled fulfillment for premium skincare and perishables, insulating against pure-play entrants. Secure exclusive click-and-collect footprint density in Kristiansand and Trondheim secondary corridors before hybrid competitors replicate Elkjøp's network. The Norwegian Consumer Council's algorithmic pricing scrutiny demands audit-trail infrastructure investment.
For New Entrants and Emerging Players: Build out subscription commerce models for beauty and personal care in Tromsø and northern counties where digital banking penetration lags but mobile app install rates climb. Target cash-on-delivery settlements in remote settlements underserved by incumbent logistics density. Partner with existing grocery platforms for last-mile access rather than building proprietary fleet infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric fleet deployment and circular packaging systems as EU Green Deal compliance hardens. Long-term viability favors operators with first-mover certification in carbon disclosure and sustainable fulfillment. Acquire mid-cap specialists with localized reverse logistics infrastructure for apparel returns in western Norway. Watch for inflection when the Norwegian Data Protection Authority escalates enforcement against subscription trap mechanisms.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Click-and-Collect Network Expansion | Elkjøp's brick-and-mortar density enables inventory pooling that reduces last-mile costs in secondary cities. |
| Subscription Commerce Model Deployment | Oda's grocery platform captures recurring revenue while smoothing demand forecasting for perishable procurement. |
| Green Logistics Certification Program | Electric fleet operators secure municipal procurement preferences under EU Green Deal-aligned carbon disclosure rules. |
| Privacy-Preserving Personalization Infrastructure | GDPR-compliant consent-based systems differentiate platforms as the Norwegian Data Protection Authority tightens retargeting constraints. |
| Localized Reverse Logistics Partnership | Stavanger distribution nodes for apparel returns address Bergen's free-return policy concentration without margin-destroying national buildout. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with e-commerce platform executives, last-mile logistics coordinators, grocery category managers, and Norwegian Consumer Council enforcement staff. Secondary validation drew from Statistics Norway retail trade data, customs declarations on cross-border parcel flows, Datatilsynet enforcement bulletins, and EU Green Deal implementation guidance. Bottom-up transaction volume estimates triangulated against top-down GDP-attributed retail spending across the analysis window.
Calibration against historical growth trajectories anchored forward projections without assuming structural breaks. Segmentation dimensions modeled include product category, customer type, payment method, and sales channel alongside fulfillment density tier. CAGRs derived from logistic adoption curves fitted to metropolitan versus rural divergence patterns. Forecast inputs incorporated GDPR enforcement intensity indices and electric fleet penetration assumptions.
Stress conditions across customs clearance friction, data protection penalty escalation, and fuel price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and technology adoption continuity. Macroeconomic contraction, abrupt GDPR reinterpretation, or breakthrough drone delivery deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Europe E-Commerce Apparel Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
Global Subscription E Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Japan Cross Border E Commerce Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
North America Dropshipping Market