
 North America E-Commerce Watch Market | 2026-2036
North America E-Commerce Watch Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Commerce Watch Market Insights
Health-conscious Millennials is reorganizing demand away from traditional jewelry buyers toward function-first consumers seeking biometric tracking and seamless mobile integration. Apple Inc. leverages its ecosystem lock-in to dominate direct-to-consumer smartwatch sales, while Garmin Ltd. specializes in GPS-enabled fitness trackers for outdoor enthusiasts. Samsung Electronics Co Ltd competes across multiple price tiers with Android-compatible wearables that anchor its broader device strategy.
The North America E-Commerce Watch comprises timekeeping devices sold through digital channels, encompassing smartwatches with AMOLED displays, sapphire crystal faces, and rechargeable lithium-ion cells designed for wrist-worn computing and health telemetry. Online Retail channels capture the largest transaction volume by eliminating physical inventory constraints, though Third-Party Marketplaces represent the fastest-growing avenue for discovery-driven purchases among Gen Z shoppers. Health Monitoring features command premium positioning as pulse oximetry and ECG functionality transform watches from accessories into FDA-scrutinized medical adjacent devices.
FCC certification requirements govern wireless transmission standards for all connected models sold in the United States, while Health Canada regulates health claim substantiation for devices marketed with biometric functions. Mexico's national consumer protection agency enforces labeling and warranty standards for cross-border e-commerce shipments. Stakeholders must monitor evolving FDA guidance on software-as-medical-device classifications that could reclassify advanced health-tracking features and trigger premarket submission requirements.
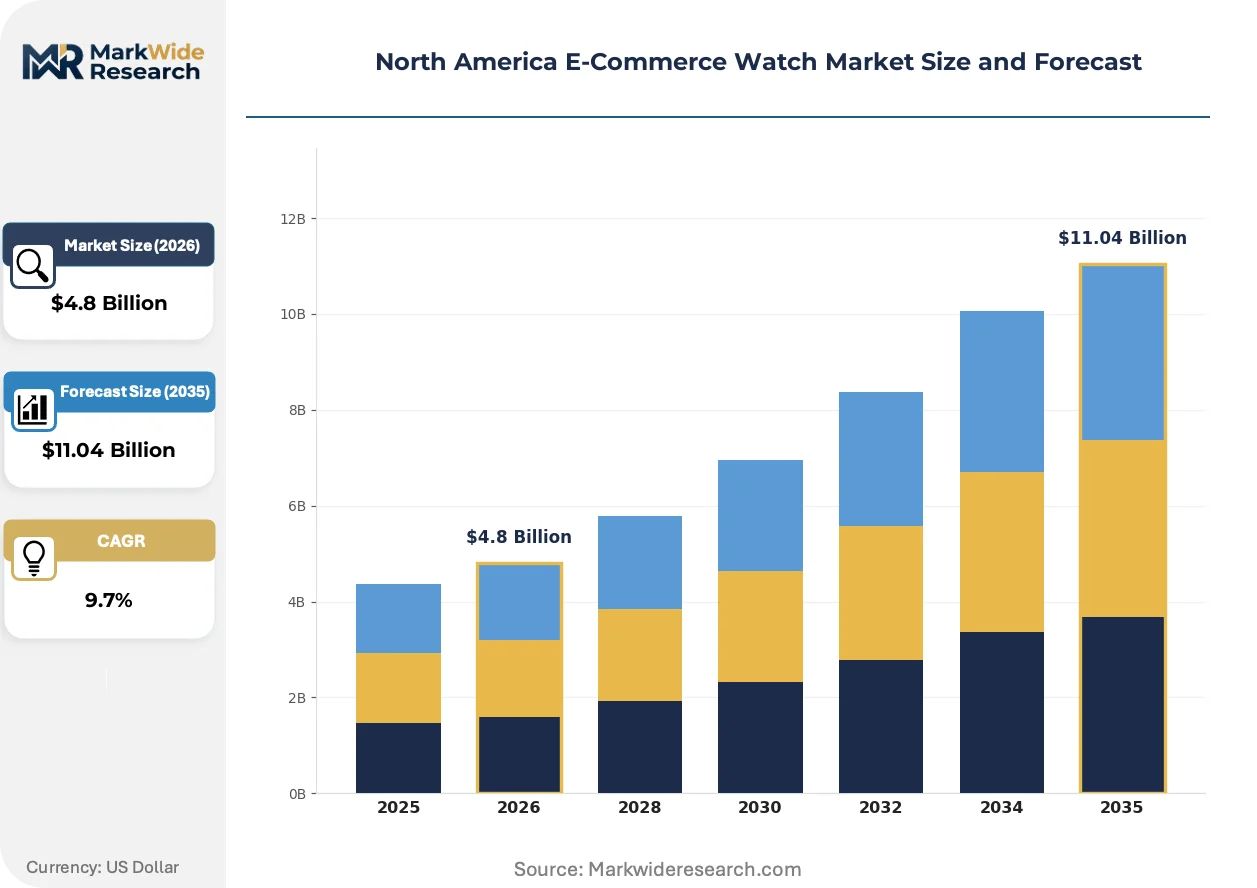
Market Dynamics
Direct-to-consumer channel migration is compressing wholesale margins while FDA software-as-medical-device scrutiny forces hardware makers to maintain dual compliance tracks for health-tracking features.
Growth Catalysts
- Biometric sensor fusion:Pulse oximetry and ECG integration transforms wrist-worn devices into clinical-grade monitoring platforms, expanding reimbursable use cases through Medicare Advantage wellness programs.
- California cluster density:Silicon Valley engineering talent concentration accelerates AMOLED display and sapphire crystal sourcing partnerships, reducing prototype-to-production cycles for DTC brands.
- FCC Part 15 certification streamlining:Pre-certified radio module availability lowers wireless connectivity barriers, enabling faster market entry for connected timepiece startups.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing dependence on Asian chemical refiners exposes North American assemblers to shipping cost volatility and tariff uncertainty.
- FDA 510(k) pathway friction:Health claim substantiation requirements for blood oxygen and arrhythmia detection extend product launch timelines by 12-18 months versus standard consumer electronics.
- Mechanical watch substitution resilience:Swiss automatic movement heritage brands retain collector loyalty, limiting smartwatch penetration among high-net-worth purchasers seeking heirloom assets.
Strategic Opportunities
- Mexico e-commerce infrastructure:Underdeveloped last-mile logistics in secondary cities creates first-mover advantage for fulfillment network investments targeting Monterrey and Guadalajara middle-class consumers.
- Health Canada streamlined approval:Medical device establishment licensing harmonization with FDA breakthrough device designation offers dual-market certification efficiency for biometric-enabled models.
- Telehealth integration:Remote patient monitoring reimbursement codes create enterprise channel demand, with health systems procuring watches as prescribed chronic disease management tools.
Industry Challenges
- Firmware security engineering scarcity:HIPAA-aligned data encryption and OTA update architecture expertise commands premium salaries, constraining mid-tier vendor R&D staffing.
- Conflict mineral traceability:Dodd-Frank Section 1502 tantalum and tungsten sourcing disclosure requirements complicate supply chain auditing for case and capacitor components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Commerce Watch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Luxury Watches, Hybrid Watches Sales Channel: Online Retail, Direct-to-Consumer, Third-Party Marketplaces, Specialty Stores Customer Segment: Millennials, Gen Z, Professionals, Seniors Feature: Health Monitoring, GPS Tracking, Mobile Notifications, Customization Options |
| Companies Covered | Apple Inc., Fossil Group Inc., Garmin Ltd., Rolex SA, Timex Group B.V., Casio Computer Co Ltd, Samsung Electronics Co Ltd, Citizen Watch Co Ltd, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Commerce Watch Market Trends and Innovations
Component integration density and regulatory classification complexity are forcing simultaneous hardware architecture and compliance workflow reinvention across the North American e-commerce watch sector.
Solid-state battery chemistry is miniaturizing energy storage footprints while maintaining lithium-ion equivalent capacity, enabling sub-8mm case designs that satisfy fashion-forward urban professionals demanding unobtrusive wearable profiles. Garmin and Apple engineering teams have accelerated solid-state pilot production timelines, compressing traditional battery supply agreements and forcing legacy cell manufacturers to retool cylindrical production lines or lose anchor customers.
FDA draft guidance on software-as-medical-device predicates is tightening algorithm validation requirements for heart rate variability and atrial fibrillation detection, compelling wearable OEMs to maintain clinical trial datasets exceeding 10,000-patient validation cohorts. Health Canada has signaled alignment with FDA predicate device pathways, creating transborder certification efficiency for vendors with existing 510(k) clearances. Early-stage companies lacking cardiovascular trial infrastructure face exclusion from premium health-monitoring positioning.
Subscription-based accessory bundling is displacing unit-transaction economics, with Gen Z purchasers prioritizing watch-face marketplace credits and fitness coaching integrations over upfront hardware discounts. Third-party marketplace discovery algorithms amplify this shift, rewarding vendors with recurring revenue attachments through improved search ranking placement. Urban professionals in New York and Los Angeles exhibit highest subscription attach rates, driving platform investment in personalized wellness content licensing.
North America E-Commerce Watch Market Segmentation
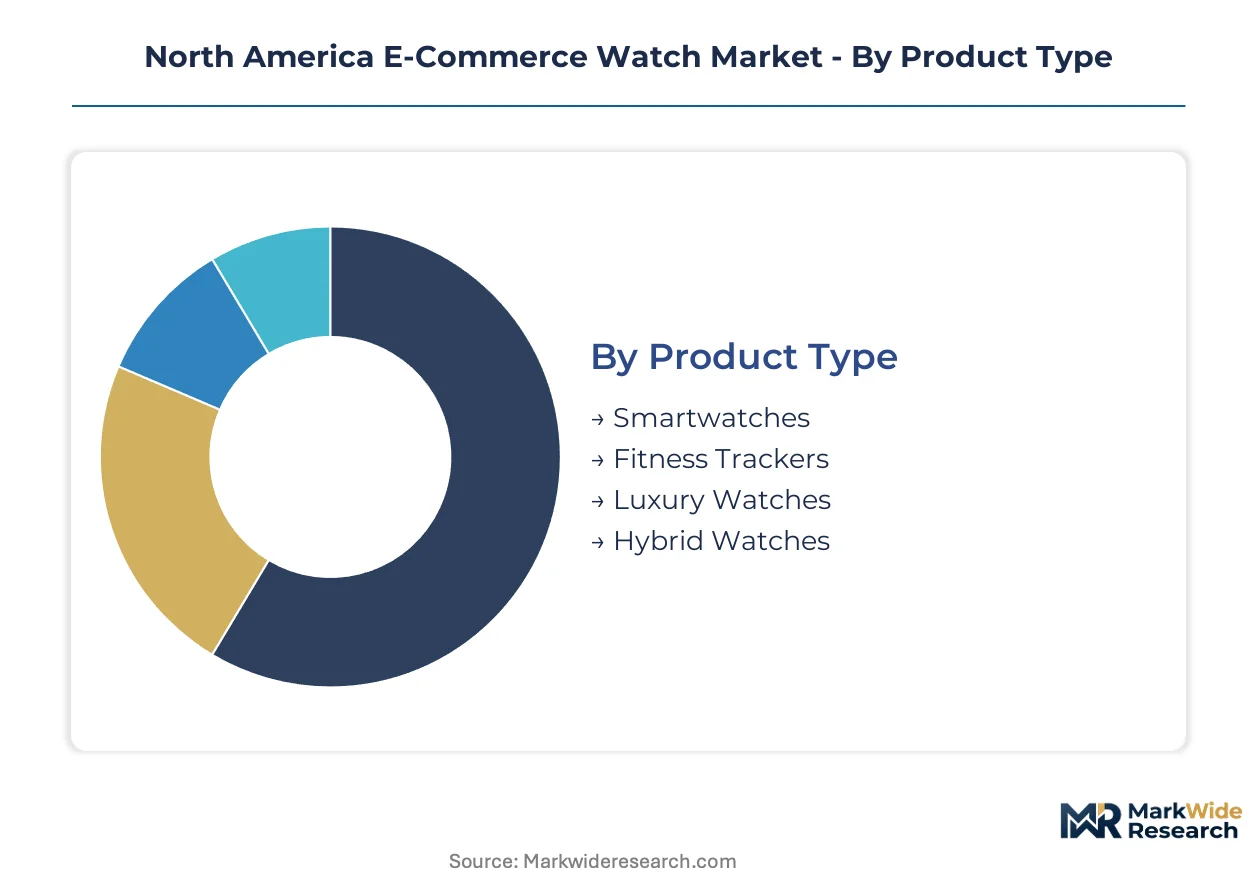
Segmentation in the North America E-Commerce Watch Market exposes divergent substitution pressures across product categories. Smartwatch vendors face mechanical watch heritage competition among collectors, while fitness trackers confront smartphone health app displacement.
Product Type:
Substitution pressure varies sharply across wrist-worn form factors, with clinical-grade health positioning insulating some segments from commodity erosion.
- Smartwatches:AMOLED displays and sapphire crystal faces support wrist-worn computing with FDA-scrutinized ECG and pulse oximetry functions. Demand concentrates among California and New York urban professionals seeking seamless iOS and Android ecosystem integration as Medicare Advantage wellness programs expand reimbursable use cases.
- Fitness Trackers:GPS-enabled units with rechargeable lithium-ion cells target outdoor enthusiasts with specialized biometric telemetry. Garmin engineering teams dominate this niche as FCC Part 15 certification streamlines wireless connectivity for GPS-sensor fusion models.
- Hybrid Watches:Analog-digital combinations with limited notification functions serve fashion-conscious buyers seeking reduced screen exposure.
- Luxury Watches:Swiss automatic movements retain heirloom asset status among high-net-worth purchasers resistant to smartwatch conversion.
Smartwatches retain volume leadership; fitness trackers hold the steepest expansion curve.
Sales Channel:
Margin compression intensity separates channels, with inventory-light models commanding valuation premiums over capital-intensive alternatives.
- Online Retail:Digital-first inventory elimination captures largest transaction volume across Amazon and Walmart platforms. Third-party marketplace discovery algorithms reward vendors with recurring revenue attachments through improved search ranking placement among Gen Z shoppers.
- Direct-to-Consumer:Apple and Samsung ecosystem lock-in strategies bypass wholesale margin erosion through owned digital storefronts. California cluster density accelerates prototype-to-production cycles for DTC brands leveraging Silicon Valley engineering partnerships.
- Third-Party Marketplaces:Discovery-driven purchase behavior dominates as algorithmic personalization substitutes for physical try-on experiences.
- Specialty Stores:Curated mechanical watch collections serve collector communities with authentication and servicing value-adds.
Online Retail commands transaction scale; Direct-to-Consumer captures margin expansion.
Customer Segment:
Generational cohort differentiation determines feature prioritization, with subscription attach rates varying by urban density and income concentration.
- Millennials:Health-conscious buyers prioritize biometric tracking and seamless mobile integration over traditional jewelry aesthetics. Los Angeles and New York urban professionals exhibit highest subscription attach rates for fitness coaching integrations.
- Gen Z:Watch-face marketplace credits and personalized wellness content licensing outweigh upfront hardware discounts in purchase calculus. Third-party marketplace discovery algorithms amplify this shift through improved search ranking placement.
- Professionals:Enterprise procurement channels emerge as health systems prescribe watches for chronic disease management under remote patient monitoring reimbursement codes.
- Seniors:Fall detection and medication reminder functions drive adoption as Medicare Advantage plans subsidize device costs.
Millennials retain volume leadership; Gen Z holds the steepest expansion curve.
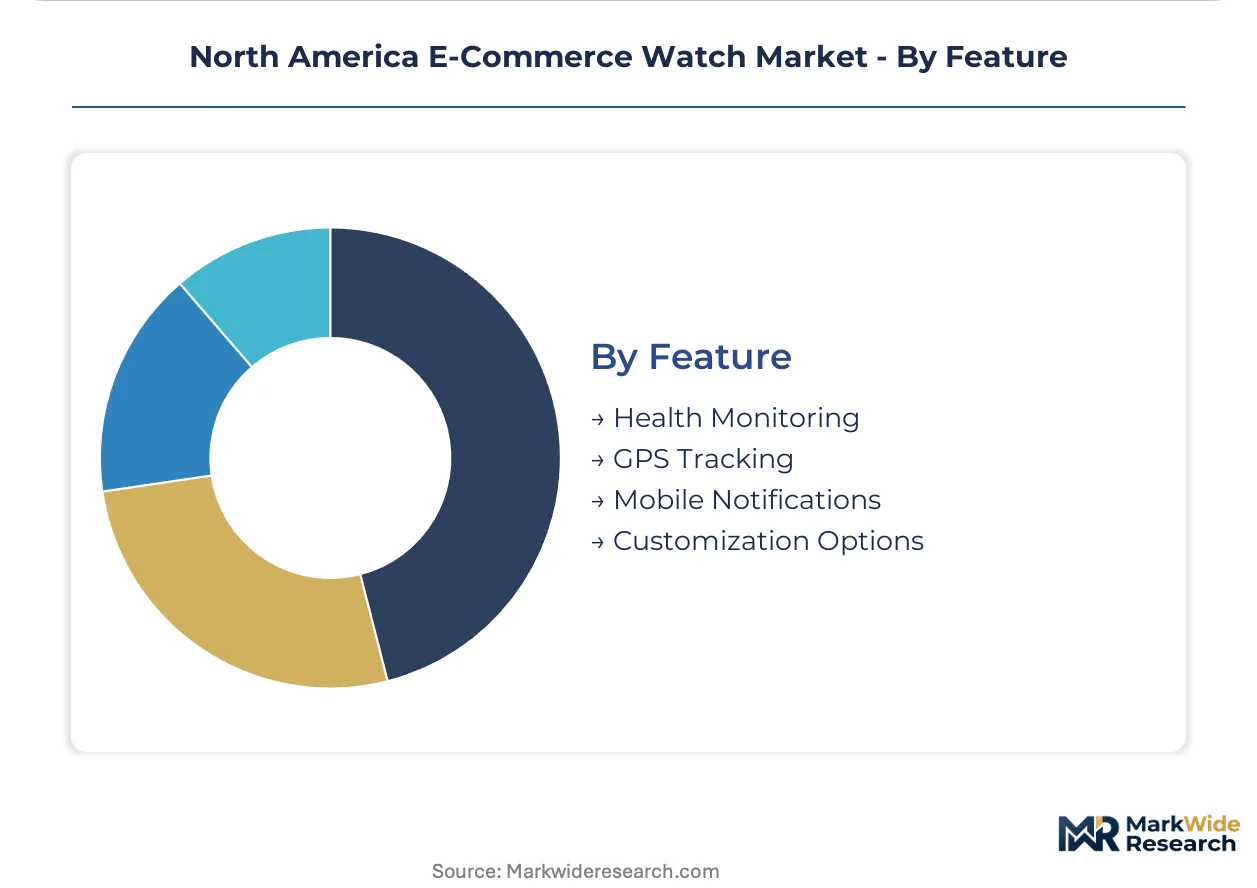
Feature:
Regulatory classification complexity stratifies positioning, with FDA-scrutinized functions commanding premium tier separation from consumer-grade alternatives.
- Health Monitoring:Pulse oximetry and ECG functionality transform accessories into medical-adjacent devices requiring 510(k) pathway navigation. FDA draft guidance on software-as-medical-device predicates compels wearable OEMs to maintain clinical trial datasets exceeding 10,000-patient validation cohorts.
- GPS Tracking:FCC-certified wireless transmission standards enable outdoor navigation and location-based services for fitness and safety applications.
- Mobile Notifications:Ecosystem-integrated alert systems anchor daily utility for professionals managing distributed work environments.
- Customization Options:Interchangeable bands and watch-face marketplaces support fashion-forward urban professionals demanding unobtrusive wearable profiles.
Health Monitoring retains volume leadership; Customization Options holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles-Long Beach port complex processes the majority of wrist-worn device imports entering North America, with intermodal rail links distributing inventory to Dallas-Fort Worth and Chicago fulfillment hubs within 72 hours.
United States
FDA 510(k) clearance pathways for pulse oximetry and ECG functions drive product launch timelines in the health-monitoring segment. FCC Part 15 certification governs wireless transmission standards for all connected models sold domestically. California's Silicon Valley engineering concentration accelerates AMOLED display sourcing partnerships and prototype-to-production cycles for direct-to-consumer brands.
Canada
Health Canada regulates health claim substantiation for biometric-enabled devices marketed to Medicare-eligible seniors in Ontario and Quebec. Medical device establishment licensing harmonization with FDA breakthrough device designation offers dual-market certification efficiency for vendors. Toronto's fintech corridor anchors enterprise procurement channels as health systems prescribe watches for remote patient monitoring.
Mexico
Cross-border e-commerce shipments face labeling and warranty enforcement by the national consumer protection agency as middle-class demand concentrates in Monterrey and Guadalajara. Underdeveloped last-mile logistics in secondary cities creates first-mover advantage for fulfillment network investments. Mexico City Metro serves as the primary distribution node for Central American re-export channels.
North America E-Commerce Watch Market Competitive Landscape
Listed leaders compete with private specialists across ecosystem integration and health-monitoring certification dimensions. The vendor base stratifies into three tiers: ecosystem-locked technology conglomerates, GPS-specialized outdoor equipment makers, and heritage mechanical watch houses. Strategic archetypes include platform-anchored smartwatch providers, clinical-grade biometric specialists, and Swiss automatic movement curators. Dominant competitive moves encompass direct-to-consumer storefront expansion and FDA 510(k) pathway pre-clearance investments.
Within the platform-anchored tier, Apple Inc. and Samsung Electronics Co Ltd exemplify ecosystem lock-in strategies through owned digital storefronts. Garmin Ltd. occupies a position among GPS-specialized outdoor equipment providers. These three companies represent the primary competitive anchors shaping direct-to-consumer channel migration and health-monitoring feature differentiation across the North American e-commerce watch sector.
| Leading Market Players |
|---|
| Apple Inc. |
| Fossil Group Inc. |
| Garmin Ltd. |
| Rolex SA |
| Timex Group B.V. |
| Casio Computer Co Ltd |
| Samsung Electronics Co Ltd |
| Citizen Watch Co Ltd |
| Sony Corporation |
| Others |
Pricing and Supply Chain Analysis
Solid-state battery chemistry substitution for cylindrical lithium-ion cells is compressing case thickness tolerances while simultaneously shifting procurement geography toward East Asian pilot production facilities and fragmenting legacy supplier pricing power across tier-one assemblers.
Pricing Analysis
Volume-discount tiering structures separate FDA-cleared health-monitoring SKUs from consumer-grade alternatives, with certification-grade pulse oximetry and ECG functions commanding premium positioning. Price differentiation rests on software validation depth and wireless module pre-certification status rather than hardware BOM differentials alone. Cost compression in the fitness-tracker tier is intensifying as smartphone health-app substitution erodes standalone device utility. Enterprise procurement through health-system channels exhibits lowest price sensitivity, while Gen Z marketplace shoppers drive hardware margin erosion through discovery-algorithm price comparison.
Supply Chain Analysis
Inventory lead times for AMOLED display panels and sapphire crystal substrates have compressed from sixteen weeks to nine weeks as California-based DTC brands accelerate prototype iterations. Component sourcing concentrates in South Korea for display drivers, Japan for precision crystal growth, and China for lithium-ion cell cathode processing. Single-source vulnerability in tantalum capacitor supply exposes assemblers to Dodd-Frank Section 1502 traceability audit costs. Distribution runs through Los Angeles-Long Beach port entry with intermodal rail links to Dallas-Fort Worth and Chicago fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
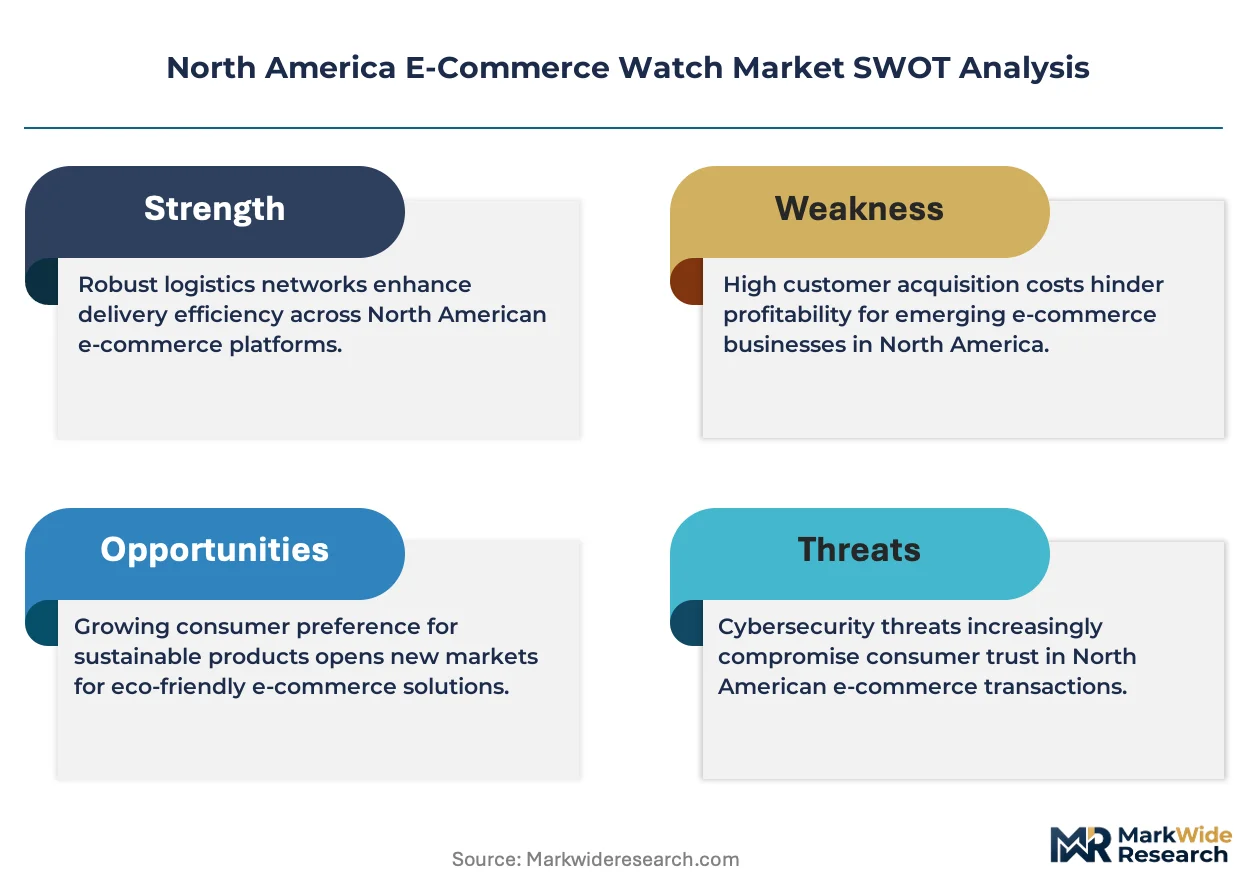
Mechanical watch heritage substitution threatens smartwatch penetration among high-net-worth collectors seeking heirloom assets, forcing digital-native vendors to defend clinical-grade health positioning as their primary differentiation moat.
For Market Incumbents: Shield ecosystem lock-in through proprietary health-data architecture and OTA update infrastructure that raises switching costs for Medicare Advantage subscribers. Deepen FDA 510(k) pathway investments to extend clearance moats against mid-tier competitors lacking cardiovascular trial datasets. Prioritize captive supply agreements with solid-state battery pilot lines to secure sub-8mm case designs before capacity constraints tighten. For New Entrants and Emerging Players: Subscription-layer service gaps in personalized wellness content licensing offer white-space entry where Apple and Samsung under-index on fitness coaching depth. Target Mexico's Monterrey and Guadalajara middle-class corridors through fulfillment network partnerships ahead of incumbent last-mile investments. Lead with Gen Z watch-face marketplace credits and algorithmic discovery optimization rather than hardware specification competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with GPS-specialized outdoor equipment makers possessing FCC Part 15 certification infrastructure but lacking health-monitoring clinical trial capabilities. Five-to-ten-year viability hinges on FDA software-as-medical-device predicate alignment rather than hardware refresh cycles alone. Monitor Health Canada breakthrough device designation harmonization signals as dual-market certification efficiency inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pre-Clearance Investment | Clinical trial datasets exceeding 10,000-patient validation cohorts secure premium health-monitoring tier positioning against consumer-grade alternatives. |
| Direct-to-Consumer Storefront Expansion | Owned digital channels bypass wholesale margin erosion while capturing subscription attach revenue from Los Angeles and New York urban professionals. |
| Solid-State Battery Supply Agreement | Sub-8mm case designs satisfy fashion-forward unobtrusive wearable demand before cylindrical cell manufacturers complete retooling. |
| Mexico Fulfillment Network Buildout | First-mover infrastructure in Monterrey and Guadalajara secures middle-class demand ahead of incumbent last-mile investments. |
| Telehealth Integration Partnership | Remote patient monitoring reimbursement codes transform watches into prescribed chronic disease management tools for enterprise health-system procurement. |
Research Methodology
Operator-level perspectives from wearable OEM product managers, FDA regulatory affairs consultants, health-system procurement officers, and third-party marketplace algorithm specialists anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA 510(k) clearance databases, FCC equipment authorization filings, Health Canada medical device establishment licensing records, and Medicare Advantage wellness program reimbursement documentation. Bottom-up demand modeling across customer segments and sales channels converged with top-down market sizing through customs import data and port throughput analysis.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios, lithium-ion cell tariff rate assumptions, and smartphone health-app substitution elasticity parameters. Segmentation dimensions modeled encompass product type, sales channel architecture, generational cohort, and feature certification tier across the projection horizon. CAGRs derived from fitted growth curves applied to validated base-year estimates, with health-monitoring reimbursement expansion and solid-state battery commercialization timelines as key industry-specific demand drivers.
Forecasts assume regulatory continuity in FDA software-as-medical-device guidance and Health Canada harmonization pathways; material policy shifts would require re-modeling algorithm validation requirements and premarket submission timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Global Digital Commerce Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Latvia E-Commerce Market