
 United Kingdom OOH and DOOH Market | 2026-2036
United Kingdom OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom OOH and DOOH Market Insights
Creative technologist talent is rotating toward programmatic and data-driven OOH capabilities, tightening supply for traditional print production crews. JCDecaux UK leverages its transport concession dominance across rail and bus networks to sustain recurring inventory access. Clear Channel UK anchors suburban roadside portfolios while Ocean Outdoor UK specializes in premium large-format digital sites in city centres.
Out-of-home and digital out-of-home advertising encompasses physical media placements in public environments, spanning printed vinyl wraps on billboards through to networked LED screens with real-time content management and audience measurement integration. The primary commercial purpose is to capture consumer attention during transit and dwell moments in high-footfall locations. Digital screens within the Format dimension are attracting the fastest investment as advertisers seek dynamic rotation and day-parting flexibility, while Static Displays retain volume leadership in secondary roadside positions where capital replacement cycles lag. Street Furniture in the Media Type dimension holds concentrated margin pools due to exclusive municipal contracts and limited site availability.
The Advertising Standards Authority enforces visibility and decency standards that shape creative execution across all UK placements, while the Committee of Advertising Practice codes restrict data collection near sensitive locations. The UK GDPR framework and Information Commissioner's Office guidance limit facial recognition and mobile tracking integrations in DOOH networks. Stakeholders must weigh capital allocation between screen hardware refresh cycles and compliance infrastructure as privacy enforcement tightens.
Market Dynamics
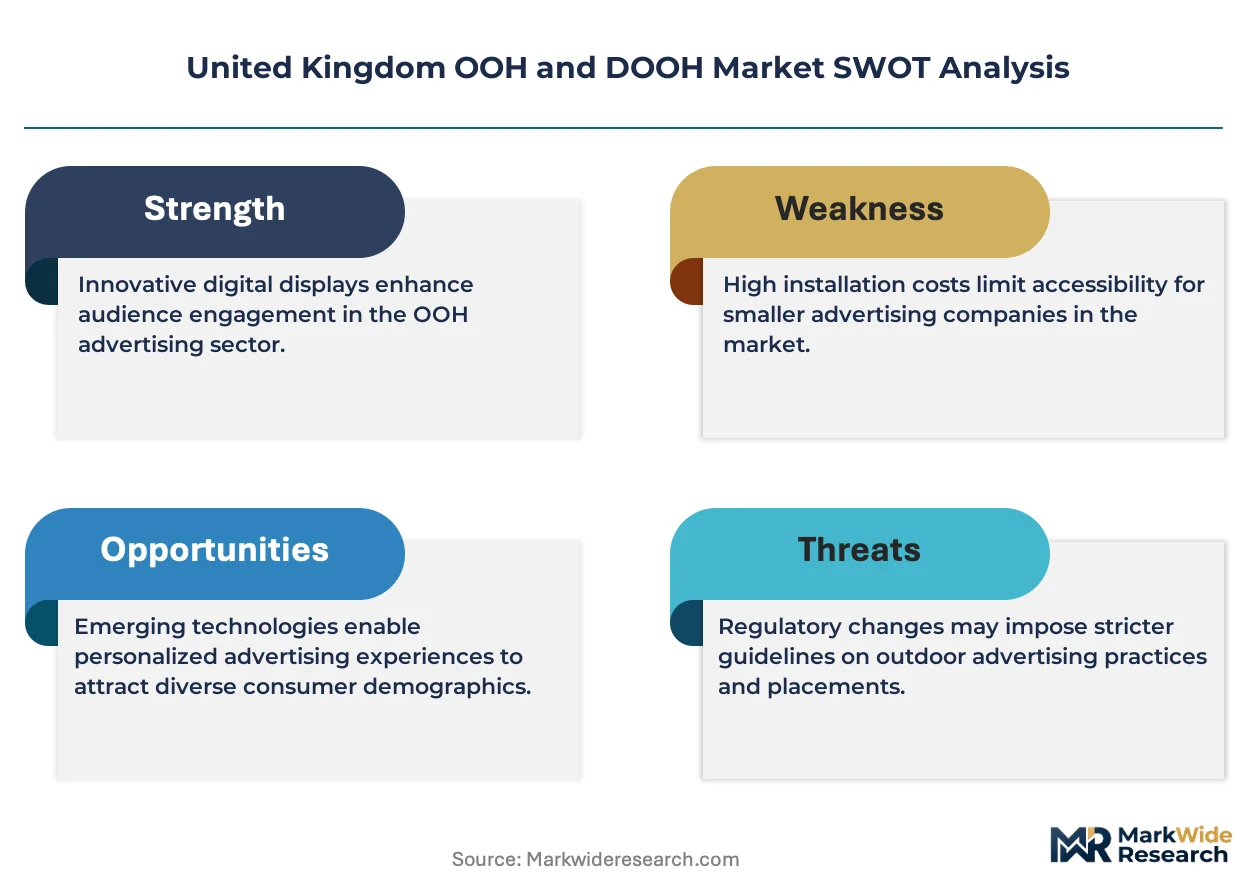
Programmatic trading infrastructure is compressing the sales cycle for digital inventory while the Advertising Standards Authority tightens visibility standards, forcing operators to reallocate capital from hardware expansion toward compliance systems.
Growth Catalysts
- Transport concession renewals:Exclusive long-term contracts across London Underground and National Rail networks lock in premium inventory access for incumbent operators, creating predictable revenue basins.
- GDPR-compliant audience measurement:Privacy-preserving mobile signal aggregation is replacing facial recognition systems, unlocking DOOH network expansion near sensitive locations previously restricted by Information Commissioner's Office guidance.
- Manchester city centre regeneration:Property development clusters around Piccadilly Gardens and Spinningfields are delivering new large-format digital screen sites with extended dwell-time capture.
Market Restraints
- Copper and LED component volatility:Display hardware manufacturing depends on semiconductor and rare earth supply chains concentrated in East Asian foundries, exposing operators to input cost swings.
- Municipal contract exclusivity:Street furniture site access is locked behind 10-15 year concessions with local authorities, blocking new entrants from high-margin urban pedestrian zones.
- Static display replacement lag:Secondary roadside vinyl billboards face extended capital refresh cycles as operators prioritize DOOH deployment, fragmenting format quality across the estate.
Strategic Opportunities
- Retail media network convergence:Supermarket and shopping centre DOOH estates are integrating with e-commerce data platforms, enabling closed-loop attribution between physical exposure and online purchase.
- West Midlands transport devolution:Birmingham's metro expansion and bus network restructuring are creating unsold inventory pools in a market historically underserved relative to London and Manchester.
- Committee of Advertising Practice code evolution:Relaxed restrictions on animated content in roadside environments are enabling new creative formats previously restricted to transport and retail interiors.
Industry Challenges
- Programmatic talent scarcity:Demand for data scientists and ad-tech engineers with OOH-specific experience exceeds supply, inflating compensation costs and extending implementation timelines for automated trading platforms.
- Legacy CMS integration friction:Operators with mixed estates of static and digital inventory face middleware complexity when unifying content management across disparate hardware generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom OOH and DOOH Market |
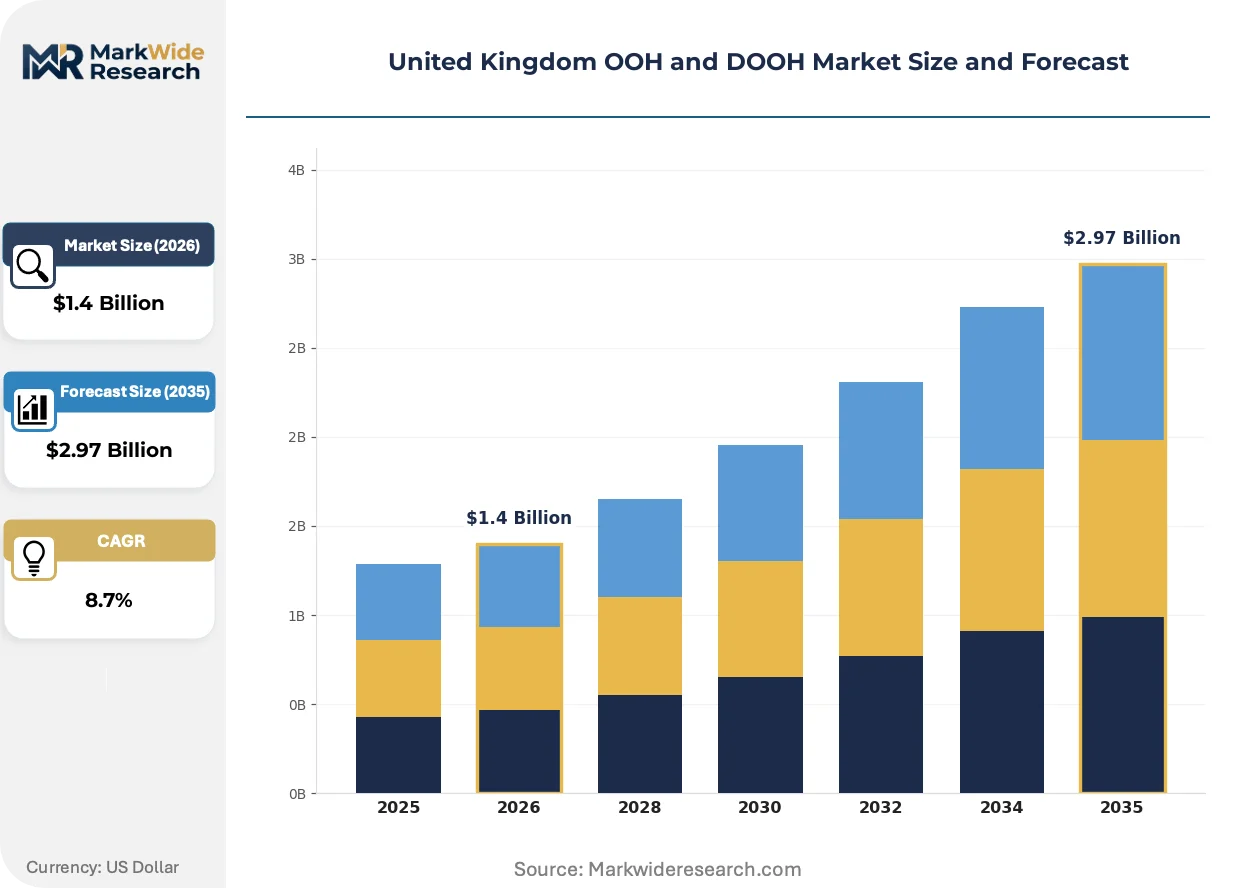
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Ads, Street Furniture, Airports Format: Digital Screens, Static Displays, Interactive Kiosks, Video Walls Target Audience: Commuters, Tourists, Local Residents, Business Professionals Advertising Strategy: Brand Awareness, Product Launch, Event Promotion, Seasonal Campaigns |
| Companies Covered | JCDecaux UK, Clear Channel UK, Global, Ocean Outdoor UK, Alight Media, Outfront Media, Ströer, Primesight, 75Media, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom OOH and DOOH Market Trends and Innovations
Real-time audience analytics and dynamic creative optimization are converging to transform how inventory is priced and sold, compressing the gap between physical and digital media trading models.
Computer vision systems with privacy-preserving edge processing are displacing traditional demographic estimation methods in DOOH networks. Retail and transit advertisers are deploying these tools at scale across London's West End and Canary Wharf estates. The technology is displacing day-parted static scheduling with impression-level audience verification, enabling outcome-based pricing structures previously restricted to online channels.
The Advertising Standards Authority's updated visibility and illumination codes are mandating minimum luminance thresholds and anti-glare positioning for new digital installations. Operators must retrofit existing screens or face placement restrictions in sensitive zones near schools and hospitals. The regulations are compressing deployment timelines as engineering teams reconcile hardware specifications with compliance documentation.
Agency holding groups are consolidating OOH buying into centralized trading desks with direct platform integrations, bypassing traditional media owner sales teams. Independent agencies and mid-market brands are accessing this infrastructure through self-serve interfaces, fragmenting the historical account management relationship. The shift is most visible in London's competitive pitch environment where procurement cycles have compressed from quarterly to continuous trading.
United Kingdom OOH and DOOH Market Segmentation
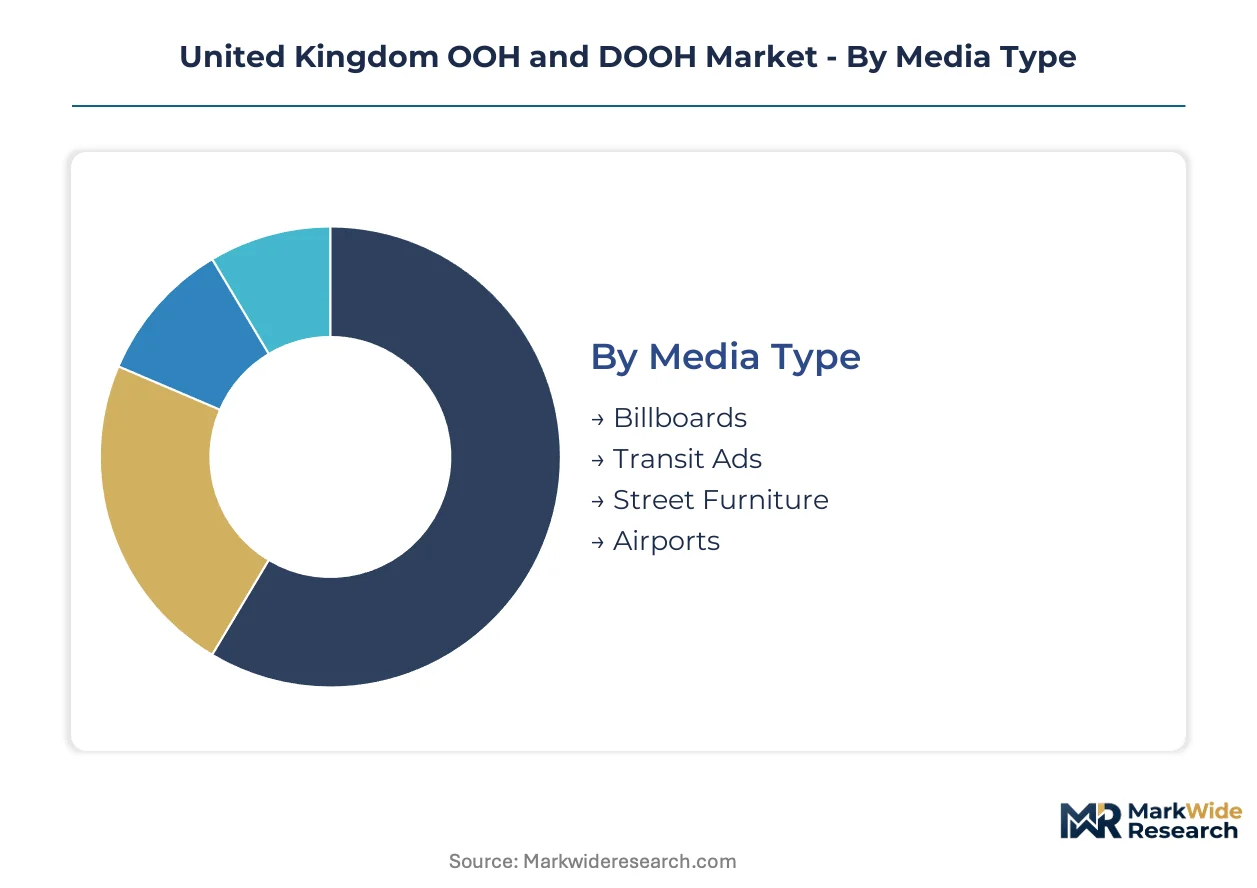
Segmentation in the United Kingdom OOH and DOOH Market reflects divergent regulatory exposure across media placements and format technologies. The Advertising Standards Authority applies distinct visibility and data privacy standards depending on physical location and screen capabilities, reshaping capital allocation and creative execution strategies.
Media Type:
The Advertising Standards Authority enforces stricter illumination and content standards near transport infrastructure and pedestrian zones, creating compliance cost differentials across placement categories.
- Billboards:Large-format roadside structures dominate secondary highway corridors and urban approach routes. The Committee of Advertising Practice restricts animated content on roadside billboards, preserving static vinyl dominance on arterial roads into Birmingham and Leeds where digital refresh cycles lag.
- Transit Ads:Rail and bus network placements capture extended dwell periods in London Underground and National Rail stations. JCDecaux UK's concession dominance across Transport for London estates locks in premium inventory access, though GDPR constraints on passenger tracking limit dynamic personalization.
- Street Furniture:Bus shelters and telephone kiosks concentrate in high-footfall pedestrian zones with exclusive municipal contracts. Manchester City Council and Transport for London award 10-15 year concessions, blocking competitive entry into margin-rich urban cores.
- Airports:Terminal and airside placements serve international departure lounges and baggage reclaim zones. Heathrow and Gatwick digital estates command rate premiums for business professional targeting, though aviation authority security protocols delay hardware installation timelines.
Established volume favors Billboards; emerging adoption favors Transit Ads.
Format:
Hardware replacement cycles and content management complexity create cost tier differentiation between legacy static infrastructure and networked digital systems.
- Digital Screens:Networked LED and LCD panels enable real-time rotation, day-parting, and programmatic trading. London's West End and Canary Wharf estates deploy these at scale, with privacy-preserving mobile signal aggregation replacing facial recognition under Information Commissioner's Office guidance.
- Static Displays:Printed vinyl wraps on paper or PVC substrates retain volume leadership in secondary roadside positions. Operators defer capital refresh here to fund DOOH deployment, fragmenting production quality across northern England and Scottish estate peripheries.
- Interactive Kiosks:Touch-enabled screens with integrated payment or information functions. Retail and transit hubs in Liverpool One and Westfield London integrate these with e-commerce data platforms, though GDPR consent mechanisms complicate user data capture.
- Video Walls:Seamless multi-panel LED arrays delivering high-resolution brand storytelling. Ocean Outdoor UK specializes in these across premium city centre sites, with the Advertising Standards Authority's luminance thresholds forcing hardware specification upgrades near schools and hospitals.
Capital deployment concentrates in Digital Screens; Static Displays retain legacy volume anchoring secondary markets.
Target Audience:
Dwell-time patterns and journey purpose shape media planning and creative format selection across demographic segments.
- Commuters:Regular transit users on predictable routes through London Underground, National Rail, and Manchester Metrolink. Day-parting flexibility enables breakfast and evening peak targeting, with programmatic buying compressing sales cycles for this high-frequency exposure.
- Tourists:International and domestic visitors concentrated in West End theatre districts, Oxford Street retail clusters, and Edinburgh festival zones. Seasonal demand surges align with event promotion strategies, though currency fluctuation impacts inbound visitor volumes.
- Local Residents:Neighborhood-level repeat exposure through suburban high streets and community facilities. Clear Channel UK's roadside portfolio targets this segment, with static displays retaining cost efficiency for hyperlocal retail and service advertising.
- Business Professionals:Corporate audiences in Canary Wharf, City of London, and Birmingham's Colmore Business District. Extended dwell in airport lounges and premium transit services supports B2B messaging with higher creative production investment.
Reach depth favors Commuters; rate premium capture favors Business Professionals.
Advertising Strategy:
Campaign objectives determine format selection, measurement frameworks, and attribution methodologies across the planning cycle.
- Brand Awareness:Sustained reach campaigns prioritizing share of voice in competitive categories. Large-format digital and static placements across transport and roadside estates serve FMCG and automotive advertisers with established creative production pipelines.
- Product Launch:Time-bound concentrated blitzes requiring rapid scale and geographic precision. Programmatic DOOH enables real-time optimization, with retail media network convergence supporting closed-loop attribution between physical exposure and online purchase.
- Event Promotion:Temporary installations aligned with cultural, sporting, or commercial calendar moments. West End theatre and Manchester Arena events drive seasonal demand spikes, with modular screen configurations enabling rapid deployment and removal.
- Seasonal Campaigns:Recurring annual cycles in retail, travel, and hospitality verticals. Q4 retail peaks and summer tourism windows command rate premiums, with advance booking patterns enabling inventory yield management across mixed static-digital estates.
Planning maturity favors Brand Awareness; technology integration favors Product Launch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London concentrates DOOH investment in transport hubs and premium retail zones while northern England and Scotland retain static-heavy roadside estates, creating a bifurcated consumption geography across the UK market.
London and the Southeast
Transport for London's concession network and West End retail clusters drive programmatic DOOH deployment. The Advertising Standards Authority enforces strict luminance codes near schools and hospitals. Canary Wharf and Oxford Street estates host privacy-preserving mobile signal aggregation systems replacing facial recognition.
Midlands
Birmingham's metro expansion and bus network restructuring are unlocking unsold inventory pools in historically underserved transport corridors. West Midlands transport devolution programs are accelerating municipal contract renegotiations. The Colmore Business District anchors B2B-focused digital screen installations targeting business professionals.
North England
Manchester's Piccadilly Gardens and Spinningfields regeneration clusters are delivering new large-format digital sites with extended dwell-time capture. Manchester City Council's 10-15 year street furniture concessions block competitive entry into margin-rich urban cores. Leeds and Liverpool retain static vinyl dominance on arterial approaches where digital refresh cycles lag.
Scotland
Edinburgh's festival economy drives seasonal demand spikes for temporary event promotion installations. The Committee of Advertising Practice restricts animated content on roadside billboards across Scottish arterial roads. Glasgow's suburban high streets maintain static display cost efficiency for hyperlocal retail advertising.
Wales and Northern Ireland
Cardiff and Belfast city centres are emerging as secondary digital estate development zones with lower concession competition than English metros. Local authority procurement frameworks favor incumbent operators with legacy static portfolios. Rural roadside positions across both regions face extended capital refresh cycles as operators prioritize urban DOOH deployment.
United Kingdom OOH and DOOH Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with transport concession holders and premium city-centre operators commanding distinct margin pools. The market structure concentrates around exclusive municipal contracts and long-term rail network agreements that lock in inventory access. Three archetypes dominate: transport concession incumbents with recurring estate control, premium large-format digital specialists, and suburban roadside portfolio operators. Competitive moves center on programmatic trading platform integration and compliance infrastructure investment as privacy enforcement tightens.
Within the transport concession tier, JCDecaux UK and Clear Channel UK exemplify integrated leaders with recurring inventory access across rail and bus networks. Ocean Outdoor UK occupies a position among premium large-format digital specialists focused on city-centre estates. These three anchors represent the strategic archetypes shaping capital allocation between hardware refresh cycles and compliance systems.
| Leading Market Players |
|---|
| JCDecaux UK |
| Clear Channel UK |
| Global |
| Ocean Outdoor UK |
| Alight Media |
| Outfront Media |
| Ströer |
| Primesight |
| 75Media |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at East Asian LED foundries concentrates display hardware supply in a narrow geographic band, creating asymmetric pricing power for operators with long-term procurement contracts and elevating price floors for mid-tier entrants lacking volume commitments.
Pricing Analysis
Long-term concession contracts with Transport for London and Manchester City Council anchor pricing structures across the UK OOH market, locking in predictable revenue basins for incumbents while spot-market inventory trades at volatile premiums. Price differentiation hinges on site exclusivity tenure and GDPR-compliant audience measurement certification, with transport hub placements commanding premiums over roadside static positions. Cost compression in secondary roadside vinyl tiers is intensifying as operators defer capital refresh to fund DOOH deployment. Retail media networks show lowest price sensitivity due to closed-loop attribution capabilities, while local SME advertisers exhibit highest sensitivity to rate fluctuations.
Supply Chain Analysis
Port congestion at Rotterdam and Felixstowe elevates inbound logistics costs for semiconductor components and rare earth phosphors sourced from China, South Korea, and Taiwan. Display hardware manufacturing draws from concentrated East Asian foundries for LED modules, driver ICs, and aluminum framing systems. Single-source vulnerability in advanced LED chip supply creates exposure to export restriction risks. Distribution runs through specialized AV integrators and direct operator procurement teams, with final-mile installation handled by regional electrical contractors holding municipal street works licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK OOH market functions as a defensive-moat industry where decade-long municipal concessions and transport network exclusivity create regulatory entrenchment that shields incumbent revenue streams from competitive erosion.
For Market Incumbents: Shield concession renewals through proactive compliance infrastructure investment ahead of Advertising Standards Authority visibility code tightening. Prioritize GDPR-compliant audience measurement certification to unlock expansion near sensitive locations previously restricted by Information Commissioner's Office guidance. Deepen backward integration into programmatic trading platform development to capture margin from agency trading desk consolidation.
For New Entrants and Emerging Players: Mid-market suburban roadside portfolios represent an underserved service-layer gap where Clear Channel UK's static-heavy estate under-invests in digital refresh. Target Birmingham's West Midlands transport devolution corridors and Cardiff's emerging digital estate development zones as penetrable geographies with lower concession competition. Deploy self-serve programmatic interfaces to bypass established account management relationships and capture independent agency spend.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among transport concession holders with 10-15 year municipal contracts, offering superior cash flow predictability versus premium city-centre digital specialists exposed to cyclical advertising demand. Prioritize acquisition targets with locked-in rail network agreements and compliance infrastructure already deployed. Watch for Information Commissioner's Office guidance relaxation on privacy-preserving mobile signal aggregation as the signal indicating expanded DOOH network valuation upside.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Investment | Transport for London and National Rail contract extensions lock in multi-year inventory access against competitive bidding. |
| Programmatic Platform Integration | Direct agency trading desk connections bypass sales team intermediaries and compress procurement cycles. |
| GDPR-Compliant Measurement Deployment | Privacy-preserving mobile signal aggregation replaces facial recognition and unlocks sensitive location expansion. |
| Retail Media Network Convergence | Supermarket and shopping centre DOOH integration with e-commerce data enables closed-loop attribution. |
| West Midlands Geographic Expansion | Birmingham metro development creates unsold inventory pools in historically underserved transport corridors. |
Research Methodology
A standing panel of media planning directors at agency holding groups, programmatic trading desk operators, municipal procurement officers at Transport for London and Manchester City Council, outdoor advertising sales executives, and compliance officers at the Advertising Standards Authority provided ongoing calibration throughout data collection. Primary interview insights combined with secondary validation from Ofcom spectrum allocation records, Committee of Advertising Practice code documentation, Information Commissioner's Office guidance publications, and Transport for London concession contract disclosures. Bottom-up site-level inventory analysis and top-down advertising expenditure tracking enabled triangulation across independent verification paths.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including media type, format technology, target audience journey purpose, and advertising strategy objective. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and hardware replacement cycle timing. Industry-specific forecast inputs incorporated transport concession renewal schedules and municipal contract renegotiation windows.
Forecasts assume regulatory continuity in UK GDPR enforcement and Advertising Standards Authority visibility codes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
LED Billboard Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Global Cross Platform and Mobile Advertising Market
Advertising and Marketing Media
Adtech Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Middle East and Africa Programmatic Advertising Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Social Video Advertising Market