
 Global Advertising Software Market | 2026-2036
Global Advertising Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advertising Software Market Foresight
Market Context
Subscription-based access to real-time bidding infrastructure is hardening into the dominant commercial model for advertising software. The Trade Desk leverages its independent demand-side platform position to sustain buyer-side relationships across connected television and retail media channels. Google anchors the market through DoubleClick's integration with search, video, and display inventory. Amazon DSP competes by controlling first-party commerce data that differentiates audience targeting for consumer brands.
Technical Definition and Segment Structure
Advertising software encompasses platforms, algorithms, and interfaces that automate media planning, buying, optimization, and measurement across digital channels, typically processing bid requests within 100 milliseconds through real-time auction protocols. The primary commercial purpose is to replace manual insertion orders with algorithmic decisions that match advertiser budgets to impression opportunities at individual-user granularity. Cloud-based deployment leads in new installations because media agencies and brand advertisers prioritize elastic compute for seasonal campaign spikes. Demand-side platforms capture the largest share of solution-type revenue, while customer data platforms are expanding fastest as advertisers build unified identity graphs to replace deprecating third-party cookies. Creative automation within application segments shows concentrated margin pools where generative tools reduce production costs for multivariate testing.
Regulatory Frame and Outlook
The European Union's GDPR and the Digital Markets Act constrain how advertising software collects, processes, and activates personal data, while the United States lacks federal privacy legislation but enforces sector-specific rules through the FTC's deception and unfairness authority. China's SAMR and Personal Information Protection Law impose localization requirements that shape how multinational platforms architect their data infrastructure for Chinese media buyers. Stakeholders must monitor regulatory fragmentation across jurisdictions to determine whether to build compliant regional stacks or accept operational complexity from unified global deployments.
Market Dynamics
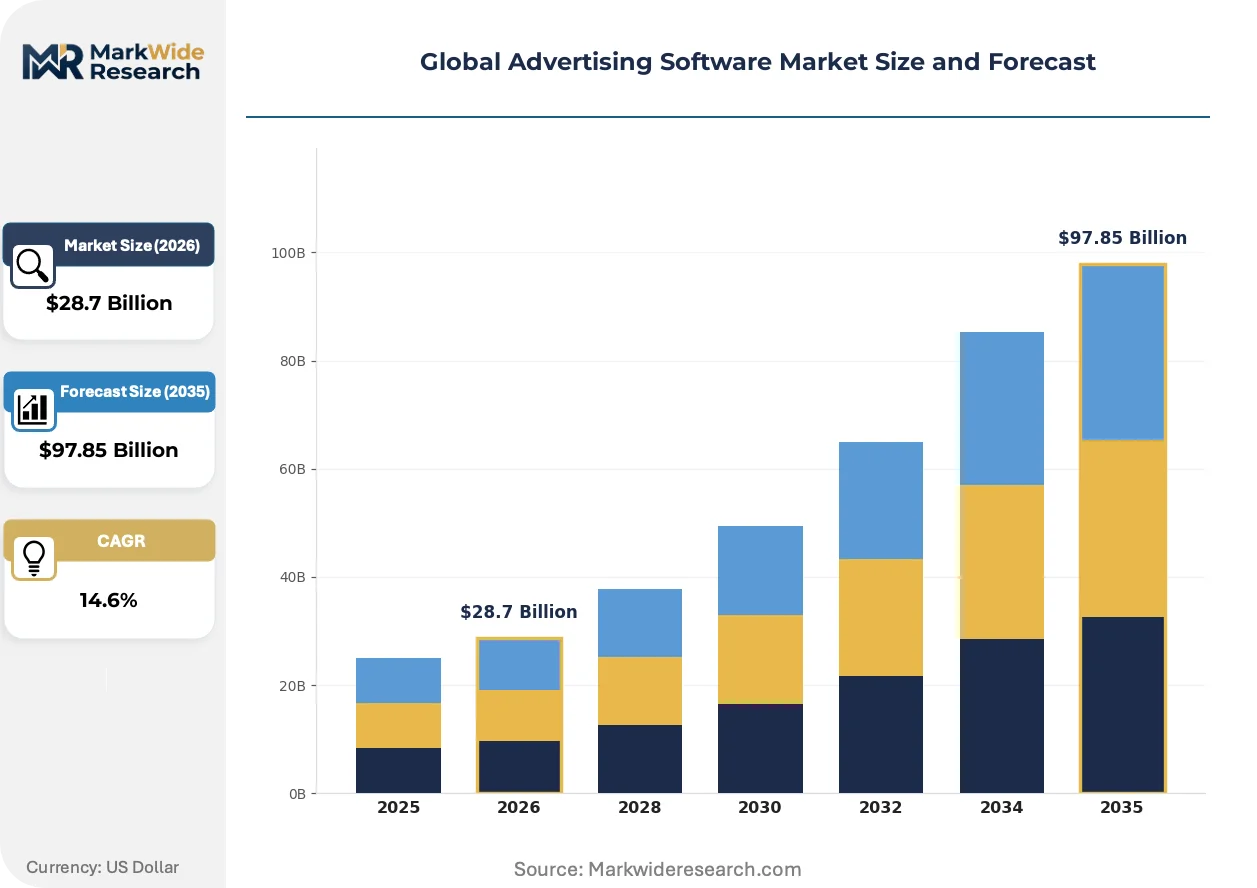
Real-time bidding infrastructure is consolidating around cloud-native architectures as privacy regulations force platform redesigns and retail media networks expand software procurement among brand advertisers seeking first-party data activation.
Growth Catalysts
- GDPR enforcement:European consent management requirements are accelerating investment in privacy-compliant targeting infrastructure as brands rebuild audience graphs around authenticated first-party data.
- Connected television:Streaming inventory expansion is pulling demand-side platform adoption into living-room screens where programmatic buying replaces traditional upfront negotiations.
- Retail media networks:Walmart, Target, and Carrefour are launching proprietary ad platforms that require brand advertisers to license specialized campaign management software.
Market Restraints
- Third-party cookie deprecation:Google's Privacy Sandbox timeline uncertainty is freezing R&D budgets as engineering teams await stable technical specifications for audience targeting.
- Cloud compute concentration:Amazon Web Services, Google Cloud, and Microsoft Azure control elastic infrastructure pricing for real-time bidding platforms, limiting vendor margin flexibility.
- Identity fragmentation:Proprietary device graphs from Apple, Google, and Amazon are creating incompatible targeting standards that increase campaign execution complexity.
Strategic Opportunities
- India programmatic infrastructure:Jio and Flipkart are building retail media stacks where multinational platforms can partner for localized demand-side technology deployment.
- Generative creative automation:Text-to-image and video synthesis tools are converging with dynamic creative optimization to reduce production costs for multivariate testing at scale.
- EU AI Act compliance:Risk classification frameworks for automated decision-making are creating advisory service revenue streams around algorithmic transparency documentation.
Industry Challenges
- Identity resolution engineering:Shortage of engineers with expertise in probabilistic matching, clean rooms, and differential privacy is constraining platform development velocity.
- Cross-border data localization:China's Personal Information Protection Law and Russia's data sovereignty rules are forcing architectural splits that multiply operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advertising Software Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Application: Programmatic Buying, Campaign Management, Audience Targeting, Data Analytics, Creative Automation End User: Digital Agencies, Brand Advertisers, Media Publishers, E-Commerce Platforms, Independent Marketers Solution Type: Demand-Side Platforms, Supply-Side Platforms, Data Management Platforms, Customer Data Platforms, Attribution Solutions |
| Companies Covered | AppNexus (Xandr), Amazon DSP, The Trade Desk, RTB House, Smartly, Google (DoubleClick), Adobe Advertising Cloud, FreeWheel, Criteo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advertising Software Market Shifts & Advancements
Algorithmic media buying is fragmenting across specialized channels as generative tools compress creative production cycles and regulatory pressure forces transparency into automated decision systems.
Clean room technology is expanding into the core infrastructure for audience targeting as privacy walls separate data owners from execution platforms. Advertisers in financial services and healthcare are adopting these encrypted environments fastest, with procurement cycles compressing from eighteen months to six. The technology is expanding into retail media networks where commerce data owners monetize insights without direct data transfers.
GDPR's Article 22 on automated decision-making is forcing demand-side platforms to build explainability layers into bid algorithms. Vendors must now document logic chains for why specific impressions receive budget allocation. European advertisers face the strictest audit requirements, while US brands are voluntarily adopting similar transparency standards ahead of potential federal legislation.
Self-service interfaces are displacing managed service contracts as mid-market advertisers demand direct control over campaign parameters. Agencies are unbundling execution from strategy, with brands in-houseing platform licenses for programmatic video and connected television. This pattern is most visible in the United States and United Kingdom where marketing operations teams have matured technically.
Global Advertising Software Market Segmentation
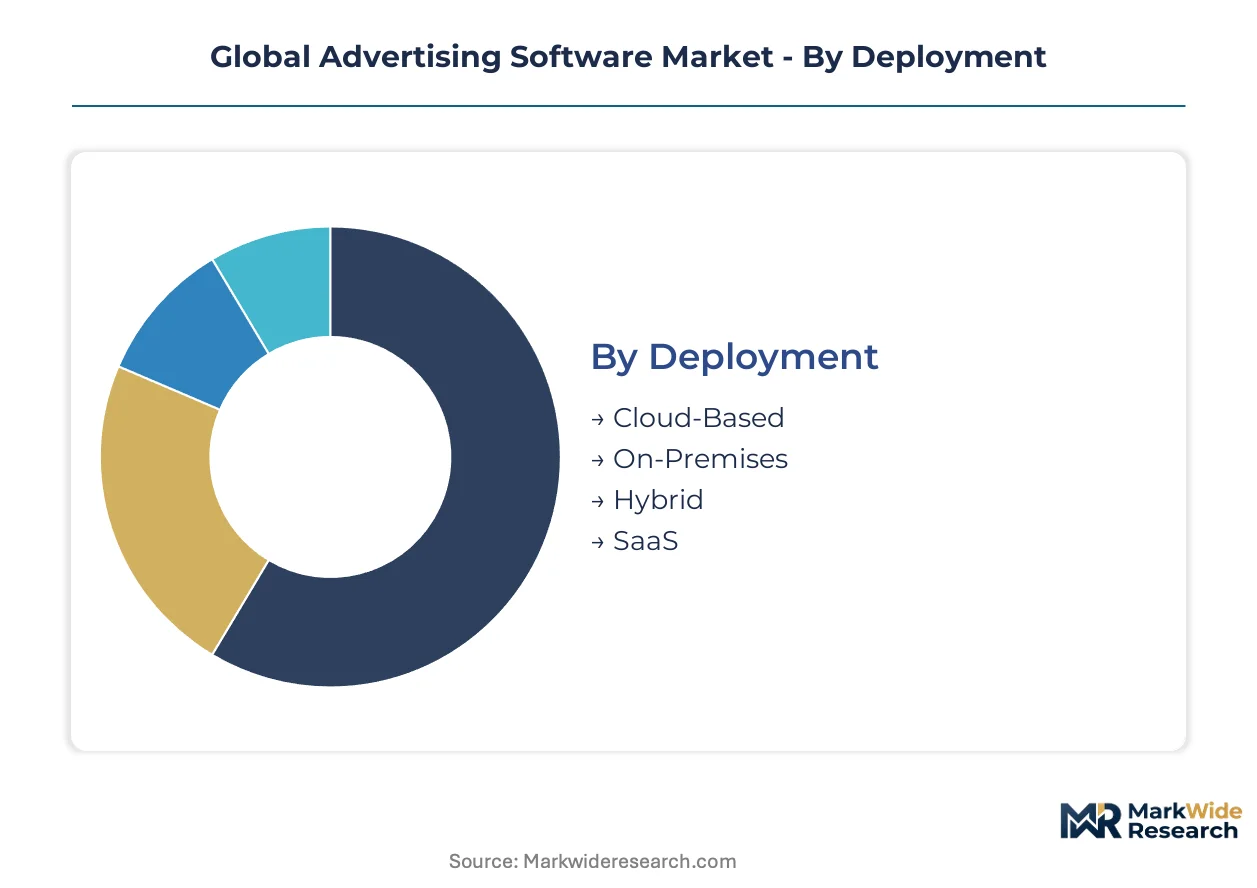
Segmentation in advertising software reveals how procurement patterns diverge between cloud-native enterprises and legacy media buyers, with deployment choices directly constraining which solution types and applications buyers can operationalize. Understanding these category boundaries helps vendors align product roadmaps with the infrastructure maturity and data sovereignty requirements of distinct buyer cohorts.
Deployment:
Cost tier separates buyers in this category, with elastic compute budgets determining access to advanced features like real-time bidding at scale.
- Cloud-Based:Elastic infrastructure provisions compute resources dynamically for seasonal campaign spikes, with media agencies in the United States and United Kingdom prioritizing this model for programmatic video workloads. The architecture eliminates capital expenditure barriers for mid-market advertisers entering connected television.
- SaaS:Subscription licensing bundles software access with managed infrastructure, appealing to brand advertisers seeking predictable operational expenditure without platform maintenance overhead. European buyers under GDPR jurisdiction favor this model for vendor accountability in data processing agreements.
- Hybrid:Combines on-premises data residency with cloud execution, serving financial services advertisers in Germany and Switzerland with strict custody requirements for customer data.
- On-Premises:Self-managed installations persist among Chinese media buyers under SAMR localization mandates and defense-sector advertisers with air-gapped security protocols.
Cloud-Based deployments lead volumes today; SaaS is gaining share fastest as procurement teams consolidate vendor relationships.
Application:
Application selection tracks customer technical maturity, with sophisticated buyers in-housing complex functions while others outsource execution.
- Programmatic Buying:Real-time auction protocols process bid requests within 100 milliseconds, automating media transactions across display, video, and connected television inventory. Demand concentrates among digital agencies in the United States managing cross-channel campaigns for consumer brands, though privacy sandbox uncertainty is freezing some R&D investment.
- Creative Automation:Generative tools synthesize image and video assets for multivariate testing, reducing production costs for retail media campaigns. Adoption is climbing fastest among e-commerce platforms in China and the United Kingdom seeking personalized creative at scale.
- Campaign Management:Workflow orchestration across planning, trafficking, and reporting functions, primarily licensed by full-service agencies retaining strategic control.
- Audience Targeting:Identity graph construction and activation, now rebuilding around first-party data as third-party cookies deprecate.
- Data Analytics:Measurement and attribution dashboards, with procurement accelerating among brand advertisers demanding transparent return-on-ad-spend verification.
Programmatic Buying leads volumes today; Creative Automation is expanding most quickly as generative tools compress production cycles.
End User:
End user type determines pricing power and customization demands, with large platforms extracting volume discounts while independents prioritize self-service interfaces.
- Digital Agencies:Full-service and specialized shops license platform stacks to execute programmatic campaigns across client portfolios, with the largest holding companies in the United States negotiating enterprise terms for multi-market access. Technical staffing shortages are pushing mid-tier agencies toward managed service arrangements.
- Brand Advertisers:Direct platform licensing by marketing operations teams displacing agency intermediaries, particularly in the United Kingdom where CPG and automotive verticals have matured in-house capabilities. First-party data activation needs are driving demand for customer data platform integration.
- E-Commerce Platforms:Retail media network operators building proprietary ad stacks, with Walmart and Flipkart in India recruiting specialized campaign management vendors.
- Media Publishers:Supply-side platform adoption to monetize inventory programmatically, constrained by header bidding complexity and identity fragmentation.
- Independent Marketers:Self-serve tools for small and mid-sized businesses, with product-led growth models expanding access in India and Southeast Asia.
Digital Agencies lead volumes today; Brand Advertisers are climbing the fastest as in-housing accelerates.
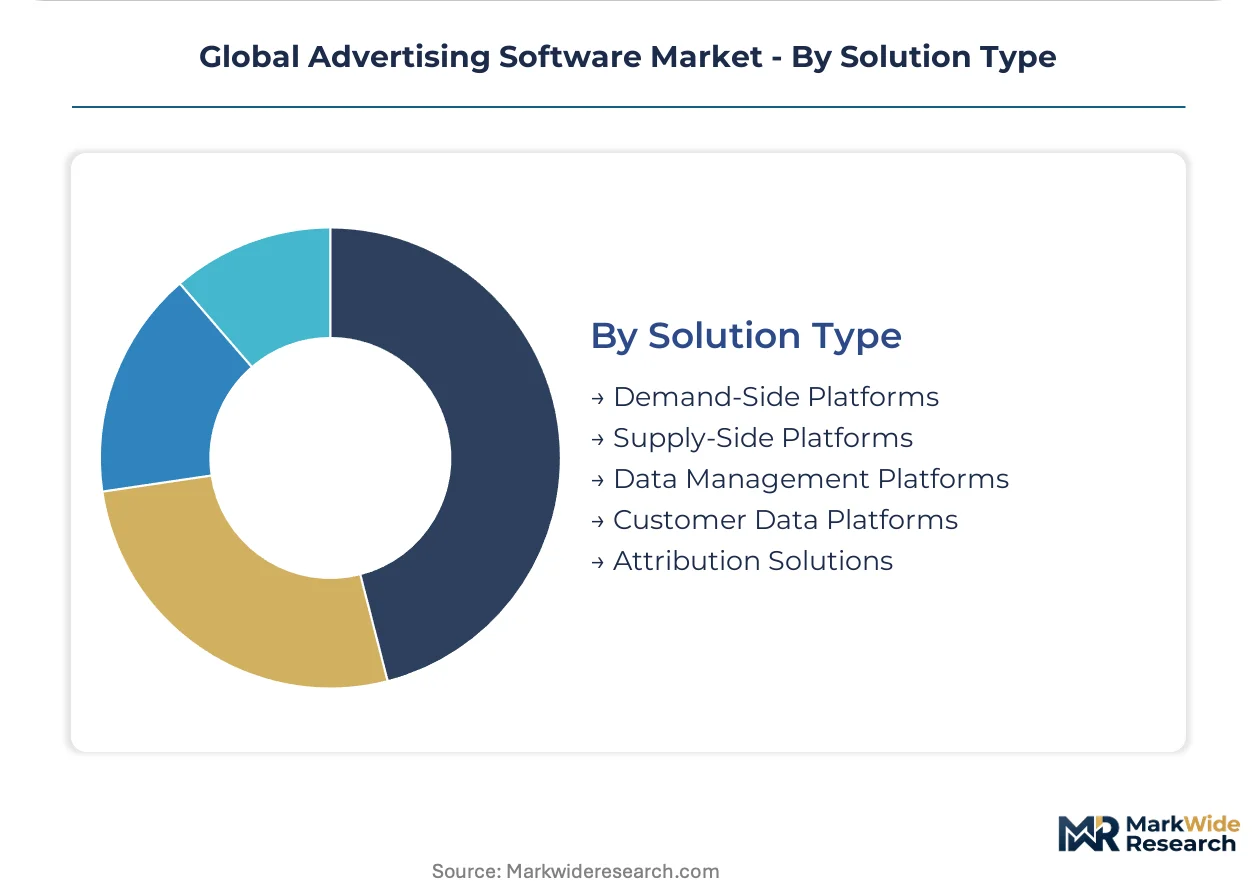
Solution Type:
Solution type alignment reflects buyer position in the ad transaction chain, with demand-side and supply-side platforms serving opposing interests in auction mechanics.
- Demand-Side Platforms:Buyer-side interfaces for real-time bidding across multiple inventory sources, capturing the largest share of solution-type revenue through The Trade Desk and independent competitors. Procurement concentrates among agencies and brand advertisers in the United States seeking connected television and retail media access.
- Customer Data Platforms:Unified identity graph construction for first-party data activation, expanding fastest as advertisers rebuild audience targeting around authenticated relationships. Financial services and healthcare buyers in Europe are adopting these systems ahead of strictest GDPR enforcement.
- Supply-Side Platforms:Publisher tools for inventory monetization, with consolidation around Google Ad Manager and independent alternatives like Magnite.
- Data Management Platforms:Third-party data aggregation and segmentation, declining as cookie deprecation erodes core functionality.
- Attribution Solutions:Cross-channel measurement and media mix modeling, with demand accelerating among advertisers seeking privacy-compliant incrementality testing.
Demand-Side Platforms lead volumes today; Customer Data Platforms show the steepest expansion trajectory as identity infrastructure rebuilds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between jurisdictions are redirecting advertising software procurement toward markets with clearer regulatory frameworks. The United States, China, United Kingdom, Germany, and India host the largest programmatic infrastructure investments, each presenting distinct operational conditions for platform vendors.
United States
Connected television inventory expansion is accelerating demand-side platform adoption among brand advertisers replacing traditional upfront negotiations. The FTC enforces sector-specific privacy rules through deception and unfairness authority rather than comprehensive federal legislation. New York and Los Angeles anchor the largest agency holding company procurement clusters, where marketing operations teams are in-housing platform licenses.
China
Retail media networks operated by domestic e-commerce platforms are driving specialized campaign management software procurement. SAMR and the Personal Information Protection Law impose data localization requirements that shape multinational platform architecture decisions. Beijing and Shanghai concentrate the largest programmatic trading desks serving consumer brands with first-party commerce data activation.
United Kingdom
Mid-market advertisers are displacing managed service contracts with self-service interfaces as technical capabilities mature. GDPR enforcement through the Information Commissioner's Office is accelerating investment in privacy-compliant targeting infrastructure. London hosts the densest concentration of independent demand-side platforms competing for connected television and retail media budgets.
Germany
Financial services advertisers are adopting clean room technology fastest to satisfy strict custody requirements for customer data. The EU AI Act's risk classification frameworks for automated decision-making are creating advisory service revenue streams around algorithmic transparency. Frankfurt and Munich cluster the largest brand advertiser in-housing operations for programmatic video.
India
Jio and Flipkart are building retail media stacks where multinational platforms can partner for localized demand-side technology deployment. TRAI regulations shape data governance expectations for domestic media buyers. Bangalore and Mumbai concentrate the fastest-growing independent marketer segments accessing self-serve tools through product-led growth models.
Global Advertising Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with independent platforms capturing buyer-side relationships while integrated technology stacks anchor supply-side monetization. The vendor base concentrates around cloud-native architectures serving real-time bidding workloads. Three archetypes dominate: independent demand-side platforms, commerce-data-anchored retail media systems, and creative automation specialists. M&A activity targets identity resolution capabilities, while strategic partnerships secure retail media network access.
Within the independent platform tier, The Trade Desk and RTB House exemplify buyer-side positioning across connected television and retail media channels. Google, operating through DoubleClick, anchors the integrated stack segment with search, video, and display inventory convergence. Amazon DSP occupies a distinct archetype leveraging first-party commerce data for consumer brand audience differentiation.
| Leading Market Players |
|---|
| AppNexus (Xandr) |
| Amazon DSP |
| The Trade Desk |
| RTB House |
| Smartly |
| Google (DoubleClick) |
| Adobe Advertising Cloud |
| FreeWheel |
| Criteo |
| Others |
Supply & Pricing Matrix
Engineers with probabilistic matching expertise cluster in Bangalore and San Francisco, creating labor-cost differentials that widen pricing-tier spreads between premium algorithmic transparency tools and economy-tier campaign management suites.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-based deployment tiers as domestic talent pools expand. Three-tier pricing structure across premium, standard, and economy levels segments buyers by real-time bidding volume commitment and algorithmic explainability requirements. Price differentiation hinges on GDPR audit documentation depth and connected television inventory access breadth. Mid-market advertisers in the United Kingdom show highest price sensitivity, while financial services buyers in Germany absorb premium tiers for clean room custody guarantees.
Supply Chain Analysis
Regional distribution centers in Dublin, Singapore, and Virginia Beach anchor hub-and-spoke patterns for real-time bidding infrastructure delivery. Cloud compute provisioning draws from United States, Ireland, and Singapore data center clusters, with specialized hardware for sub-100-millisecond auction processing resting on NVIDIA GPU supply and custom ASIC development. Single-source vulnerability concentrates in Amazon Web Services, Google Cloud, and Microsoft Azure elastic capacity allocation. Distribution runs through direct platform licensing to enterprise buyers and agency holding company master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as retail media network proliferation sustains procurement velocity across brand advertiser portfolios.
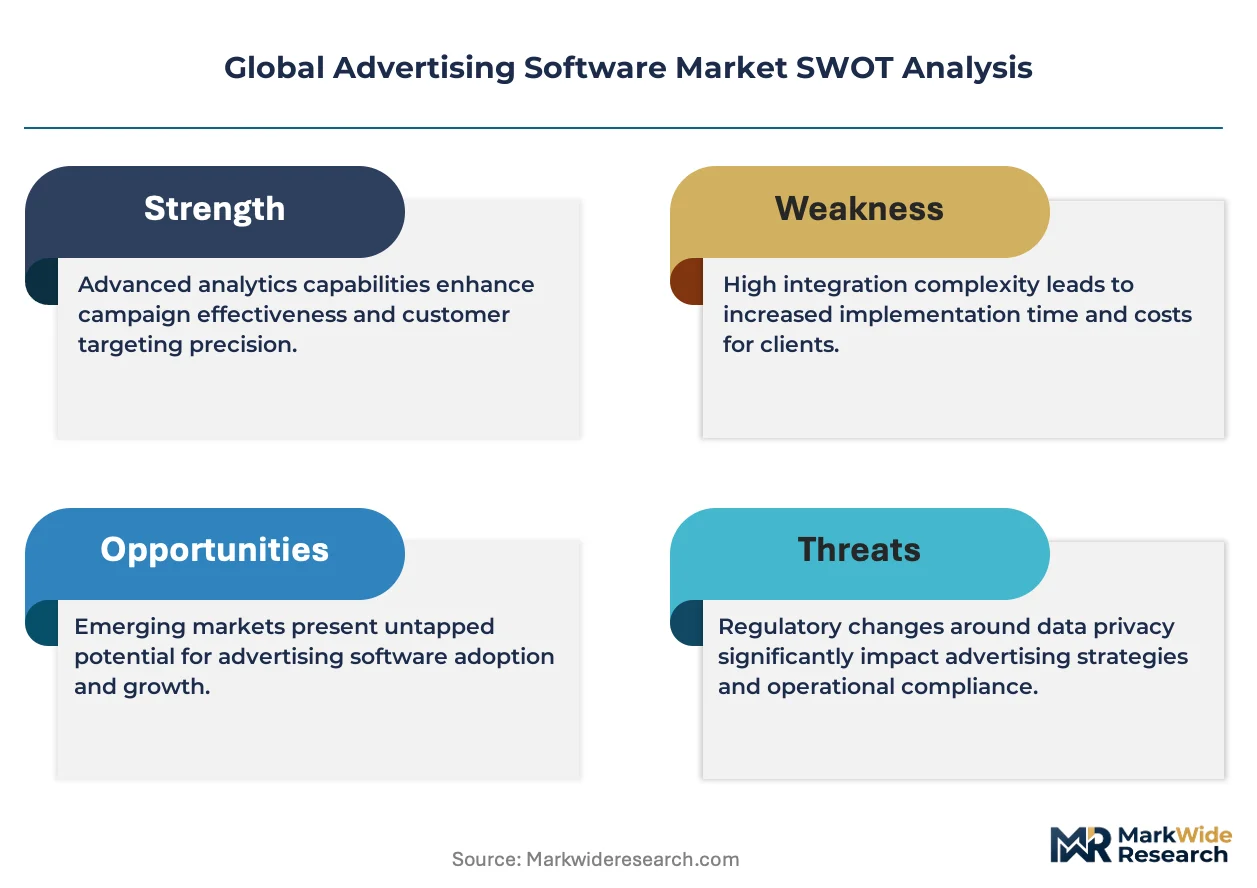
For Market Incumbents: Hedge against identity fragmentation by deepening clean room technology partnerships with financial services and healthcare verticals. Fortify connected television positioning through retail media network API integrations before proprietary commerce data moats harden. Capacity addition in Frankfurt and Mumbai preserves margin flexibility as European GDPR enforcement tightens. For New Entrants and Emerging Players: Enter via self-service interface specialization targeting independent marketers in India and Southeast Asia where product-led growth models show lowest competitive density. White-space concentrates in generative creative automation for retail media campaigns, with mid-market e-commerce platforms in China and the United Kingdom representing the most penetrable buyer cohort. Go-to-market should anchor on dynamic creative optimization APIs that compress multivariate testing production cycles. For Investors and Strategic Acquirers: Cloud hyperscalers are the most active acquirer in this space, seeking demand-side platform capabilities to anchor retail media infrastructure plays. Five-to-ten year viability favors customer data platform specialists with differential privacy engineering depth and healthcare vertical penetration. Monitor EU AI Act risk classification implementation velocity as the signal for algorithmic transparency documentation service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Room Technology Partnership | Encrypted environments satisfy GDPR custody requirements for financial services advertisers in Germany. |
| Retail Media API Integration | Direct Walmart and Flipkart connectivity secures first-party commerce data activation for consumer brands. |
| Generative Creative Automation Launch | Text-to-image synthesis reduces production costs for multivariate testing at retail media scale. |
| Algorithmic Explainability Investment | GDPR Article 22 compliance documentation opens advisory revenue streams across European demand-side platforms. |
| Geographic Expansion | Localized demand-side technology deployment in India captures Jio and Flipkart retail media stack procurement. |
Research Methodology
Coverage spans the United States, China, United Kingdom, Germany, and India, with primary inputs from each market cluster combining interviews with demand-side platform engineers, retail media network operators, brand advertiser marketing operations directors, and agency programmatic trading desk leads. Secondary validation draws from SEC 10-K filings, TRAI regulatory disclosures, EU AI Act implementation guidance, and hyperscaler capex announcements. Bottom-up sizing of customer data platform installations triangulates against top-down advertising software spend estimates from national statistical offices.
Granularity-level modeling disaggregates revenue across deployment model, end-user type, solution category, and regional regulatory cluster. Projections incorporate connected television inventory expansion curves, retail media network launch timelines, and third-party cookie deprecation phase-out assumptions. CAGRs derive from segment-level growth rate synthesis anchored to programmatic infrastructure investment patterns. Privacy sandbox specification stability and GDPR enforcement intensity serve as scenario-weighting inputs.
The model holds under sustained retail media network expansion and stable cloud compute pricing; deviation in antitrust-driven platform unbundling or acute GPU supply constraint would shift trajectory. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Digital Ad Spending Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Multiscreen Advertising Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
Global Advertising Agency Software Market