
 Smart Advertising Market | 2026-2036
Smart Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
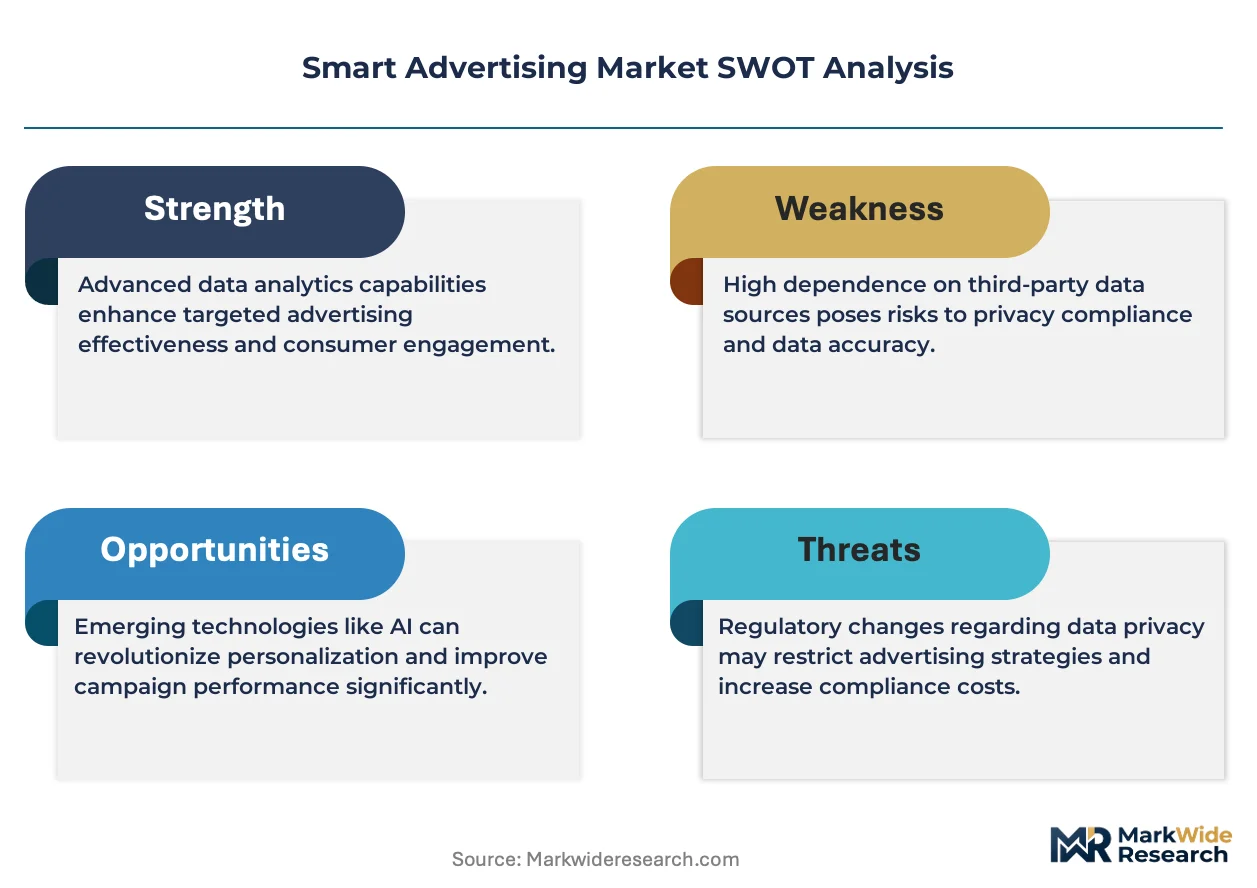
Smart Advertising Market Analysis
Programmatic inventory access is narrowing as walled gardens tighten their control over first-party data and authenticated user graphs. Google leverages its search and YouTube data moat to sustain dominance in closed-loop attribution. Amazon anchors retail media spending through its on-site sponsored product network and off-site DSP extension. Meta competes by integrating Reels inventory with AI-powered creative optimization across its messaging apps.
Smart advertising encompasses data-driven systems that automate audience segmentation, creative delivery, and performance measurement across digital and physical channels using real-time bidding protocols and predictive algorithms. These systems process consumer signals through demand-side platforms and supply-side exchanges to optimize cost-per-acquisition metrics for brand advertisers. Cloud-based deployment models now lead enterprise adoption by eliminating infrastructure latency and enabling elastic scaling during peak campaign periods. Programmatic advertising technology captures the fastest expansion as header bidding and private marketplace deals displace direct insertion orders. AI and machine learning segments concentrate margin pools where predictive bidding engines reduce customer acquisition costs for e-commerce and automotive end users.
The Federal Trade Commission scrutinizes dark patterns and deceptive ad targeting practices that manipulate consumer choice architecture. The EU AI Act and GDPR jointly constrain automated profiling for behavioral advertising, forcing platforms to deploy explainable algorithms and explicit consent mechanisms. The FCC monitors broadband privacy rules that affect ISP-based addressable advertising capabilities. Stakeholders must weigh compliance investments against the revenue at risk from restricted data flows and evolving platform policies.
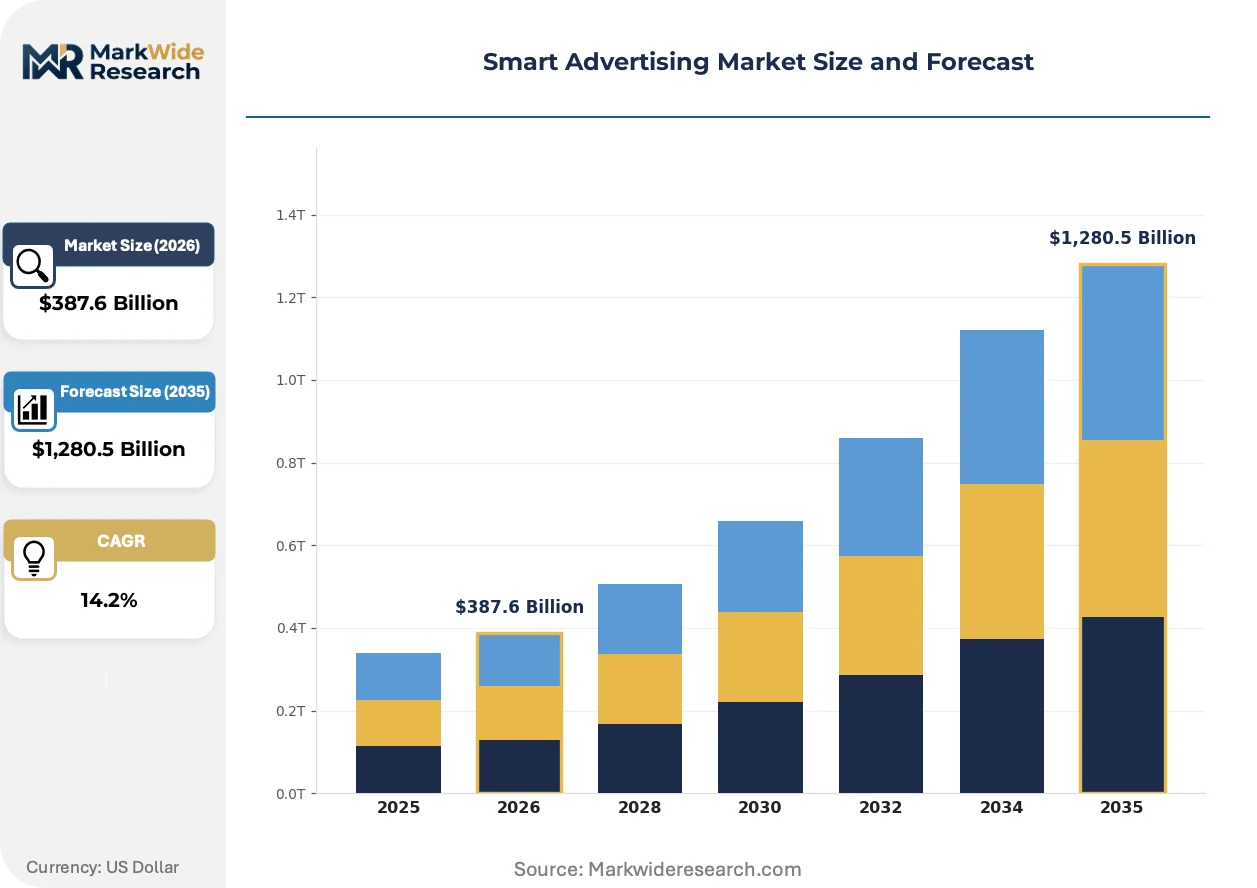
Market Dynamics
Programmatic advertising infrastructure is consolidating around authenticated identity graphs as third-party cookie deprecation forces platforms to rebuild targeting capabilities on first-party data foundations. This structural compression rewards closed ecosystems with direct consumer relationships.
Growth Catalysts
- Retail Media Networks:E-commerce platforms monetize on-site search and browse data through sponsored product placements, capturing brand budgets that previously flowed to open-web display.
- EU AI Act Transparency Mandates:Explainable algorithm requirements create compliance-driven demand for interpretable machine learning tools in automated bidding systems.
- Connected TV Inventory Expansion:Streaming services deploy ad-supported tiers that inject addressable impressions into living-room screens, bridging digital precision with television reach.
Market Restraints
- Data Localization Requirements:Cross-border data transfer restrictions in the European Union, China, and India fragment audience graphs and inflate infrastructure duplication costs.
- Walled Garden Concentration:Three platforms control over seventy percent of programmatic spend, extracting tolls on measurement and attribution that compress independent agency margins.
- Attribution Signal Degradation:Apple's App Tracking Transparency and browser privacy defaults sever the conversion loops that powered performance advertising optimization.
Strategic Opportunities
- Commerce Media Off-Site Extension:Retailers deploy demand-side platforms to target consumers across the open web using purchase-intent signals from loyalty programs and transaction histories.
- Privacy-Enhancing Technologies:Differential privacy and federated learning enable cohort-based targeting without individual identification, satisfying GDPR and emerging state-level consumer privacy laws.
- India and Southeast Asia:Smartphone-first consumer bases and underpenetrated digital ad spend per capita offer expansion terrain for mobile-native advertising infrastructure.
Industry Challenges
- Cross-Platform Measurement Fragmentation:Advertisers reconcile inconsistent metrics across walled gardens, streaming services, and retail media networks without standardized currency.
- Ad Fraud and Made-for-Advertising Sites:Invalid traffic detection l behind sophisticated bot networks and low-quality content farms that siphon programmatic budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Advertising Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premise, Hybrid, Managed Services Technology: AI, Machine Learning, Augmented Reality, Programmatic Advertising End User: Retail, E-commerce, Automotive, Healthcare Pricing Model: Cost-Per-Click, Subscription-Based, Pay-Per-View, Fixed Rate |
| Companies Covered | Google, Amazon, Meta, Adobe, Alibaba, Magnite, JCDecaux Group, Salesforce, Verizon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Advertising Market Emerging Trajectories
Artificial intelligence is compressing the creative production cycle from weeks to hours, enabling dynamic asset generation that matches messaging to micro-segments in real time. This capability is redrawing competitive boundaries between creative agencies and technology platforms.
Generative AI is migrating from experimental pilot programs to core infrastructure for dynamic creative optimization. Automotive and financial services advertisers deploy synthetic video and copy variants at scale, reducing production costs while expanding testable permutations. This shift is compressing the traditional agency retainer model and concentrating spend on platforms with native generative tools.
The EU AI Act's risk-based classification system imposes documentation and human oversight requirements on high-risk automated decision systems used in behavioral advertising. Platforms serving the European market must deploy algorithmic impact assessments and maintain audit trails for bidding logic. Retail media networks and demand-side platforms with European operations are restructuring engineering workflows to embed compliance checkpoints.
Advertiser procurement patterns favor consolidated buying through retail media networks and streaming platforms with direct consumer relationships. Mid-market brands bypass traditional agency intermediaries to access self-serve interfaces with transparent auction mechanics. This disintermediation is most pronounced in the United States, where connected TV and commerce media budgets are shifting from upfront commitments to always-on programmatic activation.
Smart Advertising Market Segmentation
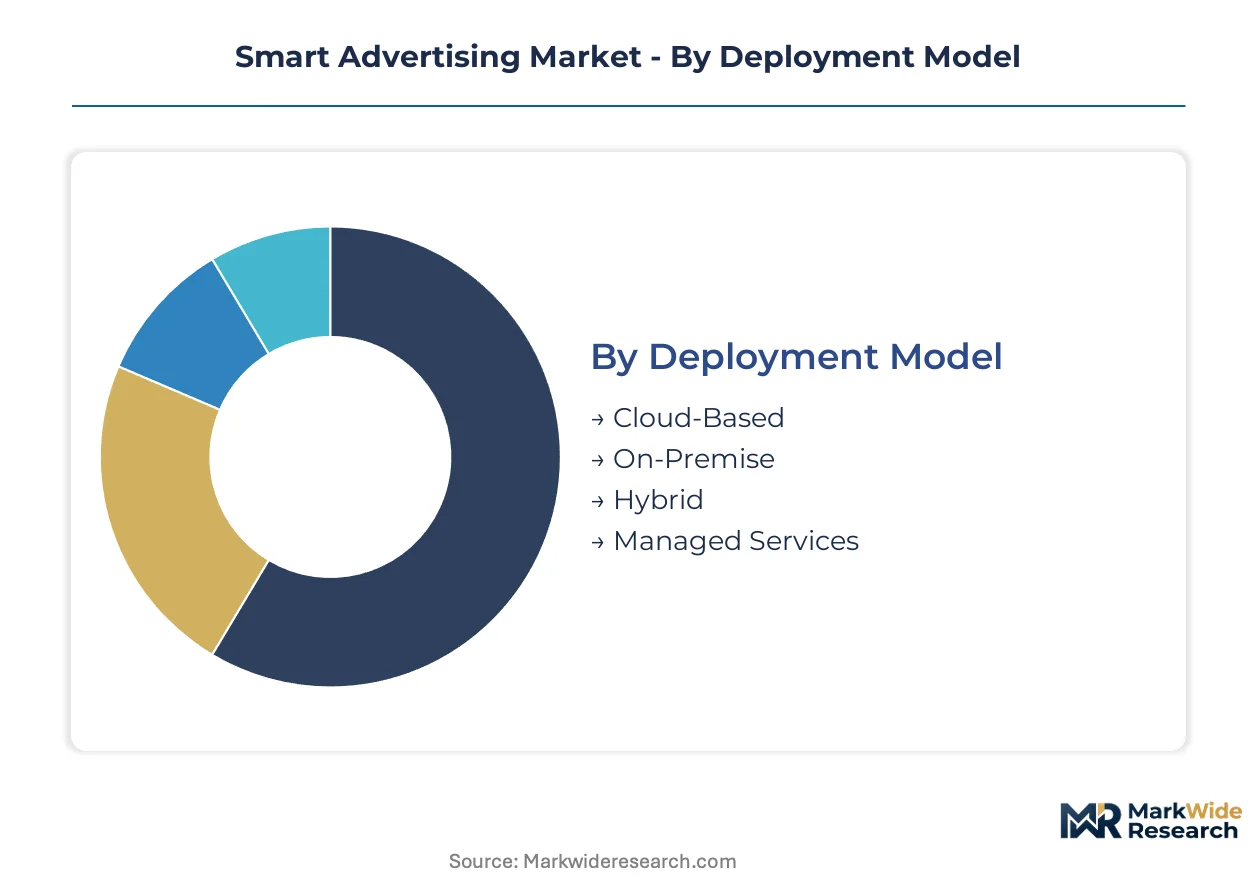
Smart advertising segmentation reveals how infrastructure choices, algorithmic capabilities, and commercial models fragment buyer preferences across enterprise scale and regulatory exposure. Deployment decisions hinge on data sovereignty requirements, while technology selection separates performance-driven advertisers from brand-focused buyers.
Deployment Model:
Mature cloud architectures dominate enterprise procurement, though hybrid configurations gain traction where latency and compliance create dual constraints.
- Cloud-Based:Elastic infrastructure eliminates capital expenditure for seasonal campaign spikes. Retail media networks and connected TV platforms deploy multi-tenant architectures to handle peak auction volumes during holiday shopping periods without provisioning idle capacity.
- On-Premise:Dedicated hardware installations satisfy financial services and healthcare advertisers with strict data residency mandates. These deployments incur higher fixed costs but prevent cross-tenant data leakage in highly regulated European and Middle Eastern markets.
- Hybrid:Split architectures process anonymized cohort data in cloud environments while retaining personally identifiable information on local servers. Automotive advertisers use this model to reconcile consumer privacy laws across multiple jurisdictions.
- Managed Services:Outsourced operations combine platform licensing with dedicated engineering support. Mid-market brands without in-house programmatic expertise contract these arrangements to access sophisticated bidding algorithms.
Cloud-based deployments retain volume leadership; hybrid configurations hold the steepest expansion curve as cross-border data rules tighten.
Technology:
Algorithm sophistication separates margin pools, with predictive engines commanding premium fees against legacy rule-based systems.
- AI:Neural networks optimize creative selection and audience matching in real-time auctions. Generative capabilities now produce synthetic video variants, compressing production timelines from weeks to hours for automotive and retail advertisers.
- Machine Learning:Supervised learning models predict conversion probabilities from behavioral signals. E-commerce platforms deploy these engines to retarget abandoned carts with dynamic product recommendations.
- Augmented Reality:Spatial computing overlays digital assets onto physical environments through smartphone cameras. Beauty and furniture retailers use try-on experiences to bridge online browsing with purchase confidence.
- Programmatic Advertising:Automated trading infrastructure connects demand-side platforms to supply-side exchanges through real-time bidding protocols. Header bidding and private marketplace deals displace direct insertion orders as the primary transaction mechanism.
Programmatic advertising anchors current spend volumes; AI capabilities are climbing the fastest as generative tools migrate from pilot to production infrastructure.
End User:
Vertical specialization drives platform configuration, with retail and automotive advertisers demanding distinct attribution models and creative formats.
- Retail:Sponsored product placements monetize on-site search data, capturing brand budgets that previously flowed to open-web display. Walmart and Target operate retail media networks that extend off-site through proprietary demand-side platforms.
- E-commerce:Direct-to-consumer brands prioritize cost-per-acquisition optimization over impression-based metrics. These advertisers deploy AI-powered creative testing across Meta and TikTok to identify high-converting audience segments.
- Automotive:Long purchase cycles require multi-touch attribution spanning digital research and dealership visits. OEMs integrate connected TV campaigns with CRM data to measure incremental lot traffic.
- Healthcare:Strict privacy regulations constrain targeting precision, favoring contextual placement over behavioral profiling. Pharmaceutical advertisers concentrate spend on condition-specific content rather than individual patient identification.
Retail applications command the largest current allocation; healthcare verticals are expanding most quickly as privacy-enhancing technologies mature.
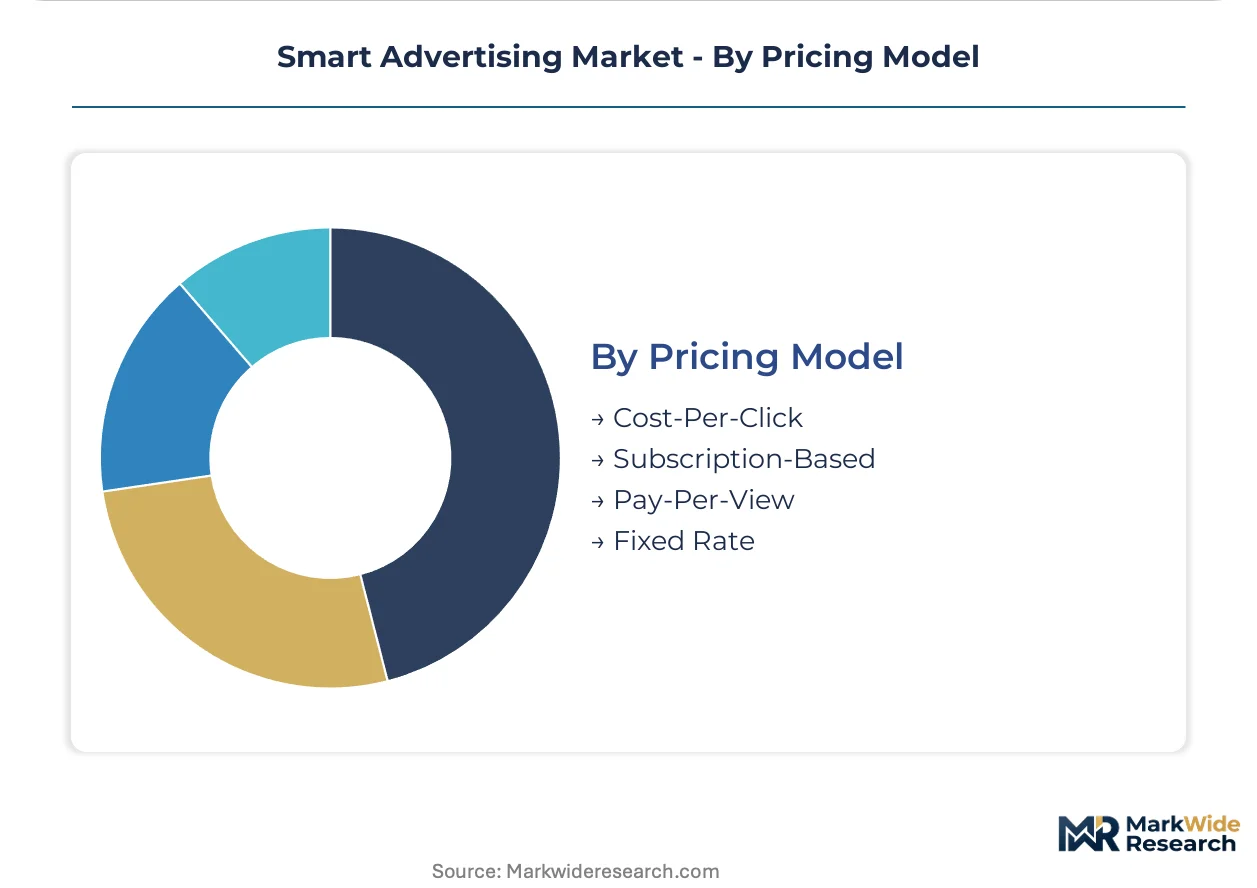
Pricing Model:
Outcome-based structures displace fixed commitments as advertisers demand accountability for media spend efficiency.
- Cost-Per-Click:Performance advertisers pay only for verified engagement, aligning platform incentives with conversion outcomes. Search and social platforms dominate this model through auction-based keyword and interest targeting.
- Subscription-Based:Flat-rate access to software platforms enables predictable budgeting for always-on campaigns. Mid-market brands favor this structure to avoid volatility in auction clearing prices.
- Pay-Per-View:Video-centric billing charges for completed views rather than impressions. Connected TV platforms use this model to justify premium rates against skippable digital video.
- Fixed Rate:Guaranteed placement contracts persist in premium publisher direct deals. Brand advertisers reserve this structure for high-visibility sponsorships where contextual association matters more than direct response.
Cost-per-click mechanisms retain transaction volume leadership; subscription-based models are gaining share fastest as procurement seeks budget predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber optic cables and subsea data corridors position the United States as the primary hub for programmatic ad exchange infrastructure. Dense metropolitan data center clusters in Northern Virginia and Frankfurt process real-time bidding volumes that dwarf other markets.
United States
Connected TV inventory and retail media networks command premium placement fees from brand advertisers shifting budgets from linear television. The FTC scrutinizes dark patterns and deceptive ad targeting practices that manipulate consumer choice architecture. New York and Los Angeles anchor the national advertising complex where agency holding companies negotiate upfront commitments with streaming platforms.
China
Smartphone-first consumer bases and super-app ecosystems generate behavioral signals that power predictive bidding engines at massive scale. The MIIT and SAMR enforce data localization requirements that constrain cross-border audience graph portability. Shenzhen and Hangzhou host the headquarters of dominant commerce media platforms that monetize on-site search data through sponsored product networks.
Germany
Automotive OEMs demand multi-touch attribution spanning digital research and dealership visits, creating specialized demand for privacy-compliant measurement tools. The EU AI Act and GDPR jointly constrain automated profiling for behavioral advertising, forcing platforms to deploy explainable algorithms. Munich and Stuttgart concentrate ad tech engineering talent serving European automotive and industrial advertisers.
United Kingdom
Financial services advertisers with strict data residency mandates favor hybrid cloud deployments that process anonymized cohort data in cloud environments. The Information Commissioner's Office enforces explicit consent mechanisms for behavioral targeting under GDPR-derived domestic legislation. London's programmatic trading desks serve as European headquarters for multinational demand-side platforms.
India
Underpenetrated digital ad spend per capita offers expansion terrain for mobile-native advertising infrastructure targeting smartphone-first users. TRAI monitors broadband privacy rules that affect ISP-based addressable advertising capabilities. Mumbai and Bangalore host engineering centers developing privacy-enhancing technologies for cohort-based targeting without individual identification.
Smart Advertising Market Vendor Landscape
On the supply side, the industry is consolidating around authenticated identity graphs as third-party cookie deprecation forces platforms to rebuild targeting capabilities on first-party data foundations. Three platforms control over seventy percent of programmatic spend, extracting tolls on measurement and attribution that compress independent agency margins. Strategic archetypes include closed-loop commerce media operators, open-web programmatic infrastructure providers, and creative optimization specialists. Dominant competitive moves involve retail media network expansion and generative AI capability integration.
Within the closed ecosystem tier, Google and Amazon exemplify divergent data moat strategies. Google leverages its search and YouTube data moat to sustain dominance in closed-loop attribution across digital channels. Amazon anchors retail media spending through its on-site sponsored product network and off-site DSP extension. Meta occupies a position integrating Reels inventory with AI-powered creative optimization across messaging apps.
| Leading Market Players |
|---|
| Amazon |
| Meta |
| Adobe |
| Alibaba |
| Magnite |
| JCDecaux Group |
| Salesforce |
| Verizon |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European ad tech infrastructure compresses auction clearing prices while forcing suppliers toward performance-based billing structures. Cloud compute utilization rates below sixty percent in Frankfurt and Amsterdam data centers push demand-side platforms toward elastic pricing models that transfer volume risk to buyers.
Pricing Analysis
Volume-discount tiering structures separate enterprise advertisers committing annual minimums from mid-market self-serve users and experimental test budgets. Pricing stratifies across premium private marketplace access, standard open-exchange inventory, and remnant auction tiers with varying data enrichment levels. Cost compression in the standard tier intensifies as retail media networks capture brand budgets with closed-loop attribution guarantees. Mid-market direct-to-consumer brands exhibit highest price sensitivity, while automotive OEMs with long purchase cycles accept premium rates for deterministic measurement.
Supply Chain Analysis
Extended payment terms from ninety to one hundred twenty days now dominate supplier-financing arrangements between demand-side platforms and independent creative studios. Supply concentrates in the United States, China, and Germany where hyperscaler data centers anchor programmatic exchange infrastructure. Raw material dependencies include cloud compute capacity, subsea fiber bandwidth, and specialized GPU clusters for generative AI workloads. Single-source vulnerability in NVIDIA's GPU supply chain threatens creative optimization pipelines. Distribution runs through direct platform relationships with brand advertisers, bypassing traditional agency holding companies in the mid-market segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against retail media networks capturing brand budgets that previously flowed to open-web display through superior closed-loop attribution. First-party data substitution threatens independent ad tech vendors lacking direct consumer relationships.
For Market Incumbents: Harden defensive moats by deepening first-party data collection through loyalty program integration and authenticated user graphs. Invest in generative AI creative tools to compress production timelines and retain brand relationships. Build vertical integration into measurement infrastructure to counter signal degradation from Apple's App Tracking Transparency.
For New Entrants and Emerging Players: Establish a beachhead in privacy-enhancing technologies serving healthcare and financial services advertisers with strict data residency mandates. Target India's smartphone-first consumer base where digital ad spend per capita remains underpenetrated relative to mobile engagement hours. Lead with differential privacy and federated learning capabilities that satisfy GDPR without individual identification.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among retail media networks with embedded sponsored product placement infrastructure and off-site DSP extensions. Long-term viability centers on platforms with direct consumer transaction data rather than third-party cookie-dependent intermediaries. Watch for inflection when EU AI Act enforcement actions trigger consolidation among non-compliant demand-side platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Network Expansion | Retail media networks monetize purchase-intent signals through off-site DSP extensions, capturing budgets from open-web display. |
| Generative AI Creative Infrastructure | Platforms deploy synthetic video variants at scale, compressing production timelines from weeks to hours for automotive advertisers. |
| Privacy-Enhancing Technology Integration | Differential privacy enables cohort-based targeting that satisfies GDPR constraints on behavioral profiling in European markets. |
| Connected TV Inventory Aggregation | Streaming ad-supported tiers inject addressable impressions into living-room screens, bridging digital precision with television reach. |
| Cross-Border Compliance Architecture | Hybrid cloud deployments process anonymized cohort data offshore while retaining personally identifiable information on local servers. |
Methodological Framework
A spread of perspectives from programmatic traders at demand-side platforms, retail media network operators, brand marketing executives, privacy compliance officers, and creative agency producers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed ad tech companies, FTC enforcement action records, EU AI Act implementation guidance, and IAB technical specifications. Bottom-up sizing of auction volumes and top-down triangulation against reported platform revenues anchored the quantitative framework.
Demand-supply-balance framing modeled programmatic impression availability against advertiser budget commitments across the projection horizon. Segmentation dimensions included deployment model, algorithmic technology tier, end-user vertical, and pricing structure. CAGRs derived from regression analysis of historical auction growth rates and forward-looking budget allocation surveys from brand advertisers. Industry-specific inputs incorporated connected TV inventory expansion curves and retail media network revenue trajectories.
Sensitivities concentrate around regulatory enforcement timing, third-party cookie deprecation schedules, and generative AI capability maturation. Forecasts reflect documented assumptions on platform concentration trends and privacy technology adoption rates. Macroeconomic contraction in brand advertising, accelerated regulatory restriction on behavioral targeting, or breakthrough advances in privacy-preserving measurement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
Digital Advertising Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
Programmatic Display Advertising Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Turkey OOH and DOOH Market
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Philippines OOH and DOOH Market