
 Japan OOH and DOOH Market | 2026-2036
Japan OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Japan OOH and DOOH Market Insights
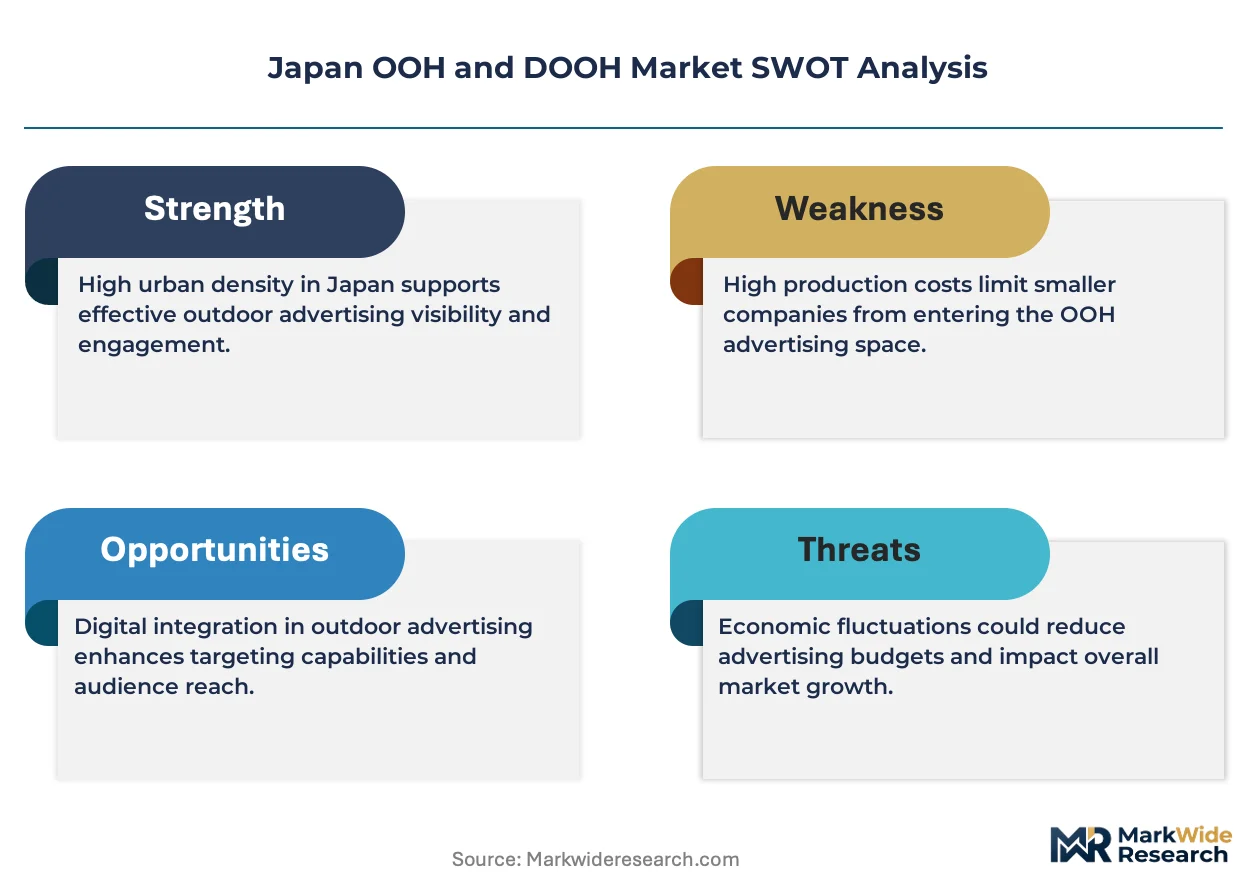
Digital creative talent scarcity is bifurcating the Japan OOH and DOOH market into premium full-service networks and commoditized display operators. Dentsu Inc. leverages its integrated agency model to control both content production and media placement across JR East rail properties. LIVE BOARD Inc. specializes in programmatic digital out-of-home inventory, competing against legacy poster contractors with real-time audience analytics.
Out-of-home and digital out-of-home advertising encompasses static and electronically rendered visual media deployed in publicly accessible environments, typically using LED modules with pixel pitches ranging from 2.5mm for close-viewing transit screens to 16mm for highway billboards, serving brand awareness and localized promotional objectives. The media format dimension shows digital displays capturing margin pools as advertisers shift spend from paper posters to networked LED screens, while the transportation sector within the sector dimension anchors volume due to JR Group and private railway operators converting station concourses to digital signage estates. LCD technology still occupies legacy indoor kiosk applications, but LED dominates new installations for brightness and energy efficiency.
METI enforces energy conservation standards under the Act on the Rational Use of Energy, directly constraining power draw specifications for permanent outdoor digital installations, while the Ministry of Land, Infrastructure, Transport and Tourism regulates advertising structures near roadways and rail corridors. JIS standards for electronic display safety and electromagnetic compatibility create compliance thresholds that filter smaller hardware vendors. Stakeholders must monitor municipal ordinances in Tokyo and Osaka that increasingly mandate disaster-warning integration into public digital displays, reshaping procurement criteria and hardware specifications.
Market Dynamics
The conversion of JR Group station concourses to digital signage estates is compressing the legacy poster contractor base while elevating premium network operators with integrated content production capabilities.
Growth Catalysts
- METI energy efficiency mandates:The Act on the Rational Use of Energy is accelerating LED retrofits across permanent outdoor installations, forcing hardware upgrades that expand addressable digital inventory.
- Transit authority digital estate expansion:Municipal authorities in Tokyo, Osaka, and Fukuoka are tendering multi-year concessions for rail station and airport screen networks, consolidating advertising real estate under programmatic-capable operators.
- Commuter density corridors:The Greater Tokyo Area transportation spine sustains premium rate cards that subsidize network buildouts in secondary Japanese cities.
Market Restraints
- Input cost volatility in LED modules:Pixel pitch specifications for transit-grade displays (2.5mm-6mm) require gallium nitride substrates subject to supply concentration in East Asian foundries.
- JIS electromagnetic compatibility certification:Hardware vendors face 12-18 month approval timelines for electronic display safety standards, filtering smaller suppliers from municipal procurement pools.
- Static print residual demand:Local retail and event promoters in prefectural capitals maintain paper poster commitments that delay full digital conversion of outdoor advertising estates.
Strategic Opportunities
- Kansai corridor underpenetration:Osaka-Kobe-Kyoto rail nodes carry 40% of Tokyo passenger volumes but maintain lower digital screen density per platform, creating whitespace for concession operators.
- Disaster-warning integration mandates:Tokyo and Osaka municipal ordinances increasingly require public digital displays to carry emergency broadcast capability, reshaping procurement criteria toward hardened hardware specifications.
- Programmatic-trading convergence:Real-time audience analytics platforms are merging with digital out-of-home inventory management, enabling impression-based buying models that attract mobile-first advertisers.
Industry Challenges
- Creative technologist scarcity:The shortage of talent capable of producing motion-optimized content for 2.5mm-16mm pixel pitch ranges is bifurcating the market between full-service networks and commoditized display operators.
- Legacy LCD integration friction:Indoor kiosk estates running aging LCD panels resist seamless content management system upgrades, forcing hybrid operational workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan OOH and DOOH Market |
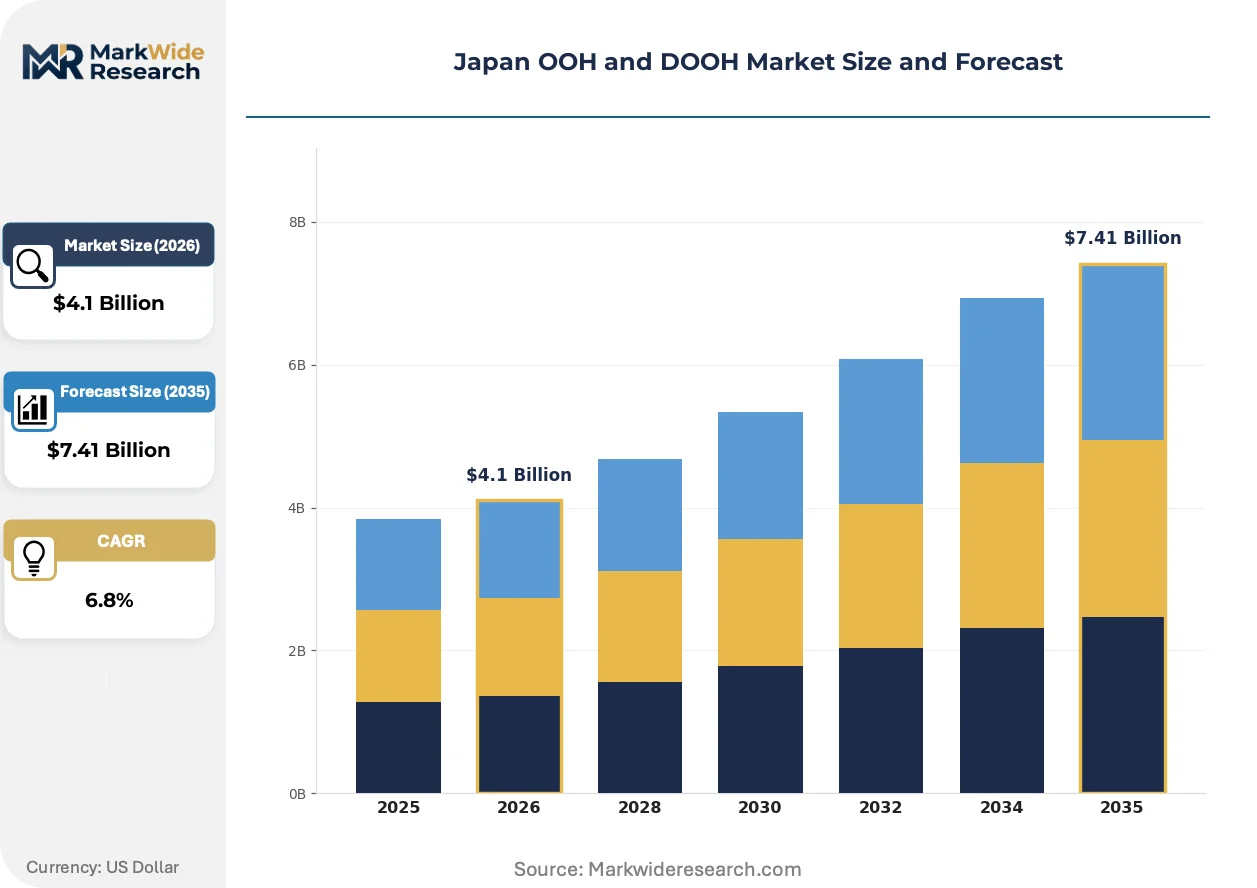
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Format: Billboards, Digital Displays, Posters, Kiosks Technology: LCD, LED, Projection, Interactive Sector: Retail, Transportation, Entertainment, Hospitality Service Type: Advertising, Analytics, Content Management, Creative Services |
| Companies Covered | Dentsu Inc., MCDecaux (JCDecaux Group), LIVE BOARD Inc., Kyoritz Advertising Agency Co., Ltd., Hit Co., Ltd., Hakuhodo DY Holdings Inc., JR East Marketing & Communications, Inc., Tokyo Metro Advertising, Inc., Osaka Metro Advertising, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan OOH and DOOH Market Trends and Innovations
Networked LED infrastructure is displacing static media formats while regulatory mandates reshape hardware procurement specifications and buyer behavior shifts toward impression-based trading models.
Fine-pitch LED modules (2.5mm-4mm) are displacing legacy LCD and projection systems in close-viewing transit environments. Railway operators in Tokyo and Osaka are specifying these technologies for platform-edge and concourse installations where passenger dwell times exceed 90 seconds. This displacement is compressing maintenance cost structures while expanding the addressable creative canvas for motion-based advertising.
METI enforcement of energy conservation standards under the Act on the Rational Use of Energy is constraining power draw specifications for permanent outdoor digital installations. Hardware vendors must now certify maximum wattage per square meter to qualify for municipal transit concessions. The transportation sector is responding by specifying high-efficiency LED drivers and ambient light sensors that dim displays during off-peak hours.
Buyer contracting patterns are rotating from fixed-duration slot purchases toward audience-impression guarantees verified by computer vision analytics. Transit advertisers in the Greater Tokyo Area are demanding proof-of-play metrics that mirror mobile and digital video accountability standards. This behavioral shift is most visible among consumer packaged goods brands with centralized media procurement functions in Minato-ku and Nishi-Shinjuku.
Japan OOH and DOOH Market Segmentation
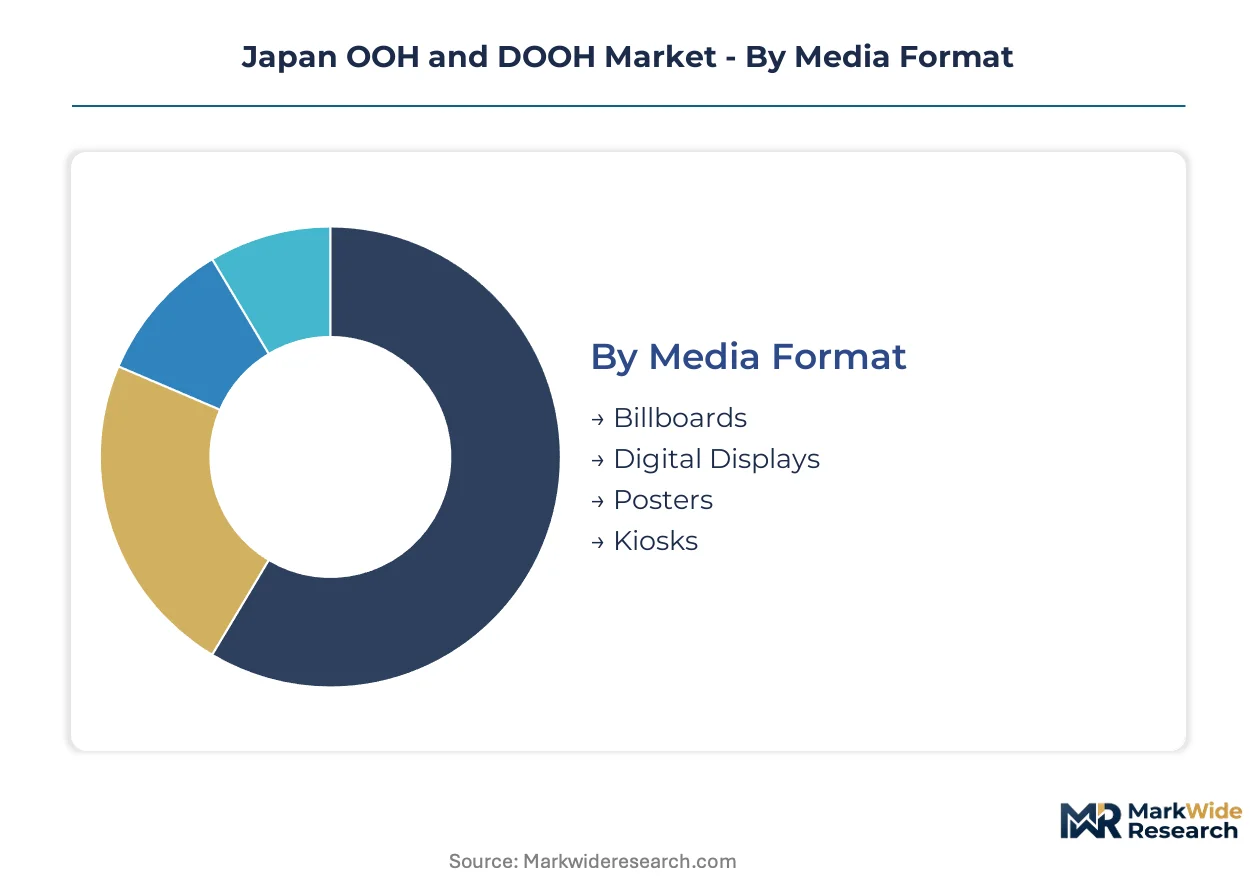
Segmentation in the Japan OOH and DOOH market reveals how margin pools migrate toward digital inventory and integrated service capabilities. Understanding these dimensions clarifies why certain technology-media combinations command premium rate cards while others face commoditization pressure.
Media Format:
Margin pools concentrate in digital displays where networked LED infrastructure enables programmatic trading and impression-based accountability.
- Digital Displays:LED modules with pixel pitches from 2.5mm for transit concourses to 16mm for highway installations capture expanding advertiser budgets. Railway operators in Tokyo, Osaka, and Fukuoka are consolidating concessions around these assets as METI energy efficiency mandates accelerate hardware upgrades.
- Billboards:Static and digital large-format structures along arterial roadways maintain residual demand from national brand advertisers. The Ministry of Land, Infrastructure, Transport and Tourism regulates placement near roadways, constraining new site development in the Greater Tokyo Area.
- Posters:Paper-based static formats persist in prefectural capitals where local retail and event promoters maintain commitments, though JR Group station conversions are compressing the legacy contractor base.
- Kiosks:Indoor information terminals in retail and transit environments run aging LCD panels that resist seamless content management upgrades, forcing hybrid operational workflows.
Digital Displays hold installed capacity. Kiosks is rotating up the share rankings as municipal authorities mandate disaster-warning integration into public terminals.
Technology:
Technology selection determines compliance timelines and procurement eligibility under JIS certification frameworks.
- LED:Gallium nitride substrates enable brightness and energy efficiency that dominate new installations. Fine-pitch modules (2.5mm-4mm) are displacing legacy systems in platform-edge environments where passenger dwell times exceed 90 seconds.
- LCD:Legacy indoor applications retain installed base but face integration friction with modern content management systems. The technology occupies kiosk estates where replacement cycles lag transit-grade LED specifications.
- Projection:Temporary and experiential deployments in entertainment venues offer creative flexibility without permanent infrastructure commitments.
- Interactive:Touch-enabled and sensor-integrated displays attract experiential advertisers in retail and hospitality sectors, though creative technologist scarcity limits deployment scale.
LED dominates new procurement volumes. Interactive is climbing the fastest as advertisers demand proof-of-play metrics mirroring mobile accountability standards.
Sector:
Sector concentration follows commuter density corridors where transportation infrastructure sustains premium advertising economics.
- Transportation:JR Group and private railway operators anchor market volume through station concourse conversions. The Greater Tokyo Area transportation spine subsidizes network buildouts with rate cards that secondary cities cannot replicate.
- Retail:Shopping mall and storefront deployments concentrate in Osaka-Kobe-Kyoto nodes where digital screen density per platform lags Tokyo benchmarks, creating whitespace for concession operators.
- Entertainment:Stadiums, cinemas, and event venues deploy projection and interactive formats for experiential campaigns with shorter duration commitments.
- Hospitality:Hotels and restaurants in Fukuoka and other regional hubs maintain localized promotional inventory with lower programmatic integration.
Transportation holds installed capacity. Retail is gaining share fastest as Kansai corridor underpenetration attracts new concession tenders.
Service Type:
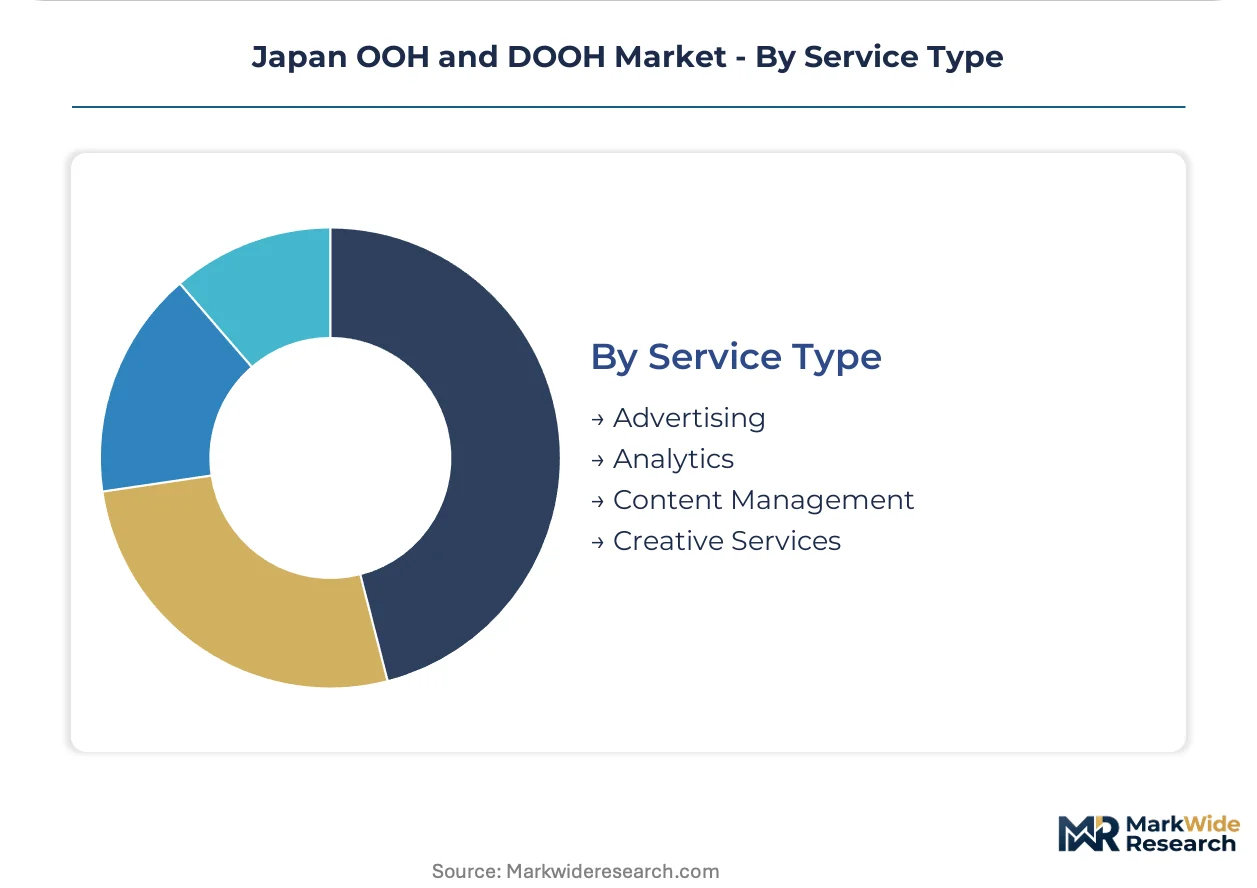
Service bundling separates full-service network operators from commoditized display contractors.
- Advertising:Media placement and slot sales remain the core revenue stream, though buyer contracting patterns are rotating from fixed-duration purchases toward audience-impression guarantees.
- Creative Services:Motion-optimized content production for 2.5mm-16mm pixel pitch ranges commands premium pricing due to talent scarcity. Agencies with integrated production capabilities control placement across premium rail properties.
- Analytics:Computer vision platforms enabling real-time audience measurement are merging with inventory management systems. Consumer packaged goods brands with centralized procurement functions in Minato-ku and Nishi-Shinjuku drive adoption.
- Content Management:Software platforms coordinating networked display estates face friction integrating legacy LCD kiosks with LED-native workflows.
Advertising holds installed capacity. Analytics is rotating up the share rankings as programmatic-trading convergence attracts mobile-first advertisers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI anchors Japan's digital infrastructure governance, with municipal ordinances in Tokyo and Osaka mandating disaster-warning integration into public displays. Regional deployment concentrates along commuter density corridors where rail operators convert station estates to networked LED signage.
Kanto/Tokyo
JR East Marketing & Communications controls premium rail concourse inventory across the Greater Tokyo Area, where commuter density sustains the highest advertising rate cards in Japan. Tokyo municipal ordinances require emergency broadcast capability in all new public digital installations, reshaping procurement specifications toward hardened hardware. The Shibuya and Shinjuku station clusters anchor network buildouts that subsidize expansion into secondary corridors.
Kansai/Osaka
Osaka Metro Advertising tenders multi-year concessions for subway and rail station networks, though digital screen density per platform remains 40% below Tokyo benchmarks. METI energy efficiency standards under the Act on the Rational Use of Energy constrain power draw specifications for permanent outdoor installations throughout the corridor. The Osaka-Kobe-Kyoto rail nodes carry substantial passenger volumes that attract concession operators seeking whitespace opportunities.
Chubu/Nagoya
Central Japan Railway Company properties in Nagoya Station and surrounding terminals convert legacy poster estates to fine-pitch LED modules for close-viewing environments. JIS electromagnetic compatibility certification creates 12-18 month approval timelines that filter smaller hardware vendors from municipal procurement pools. The Nagoya-Toyota industrial corridor sustains localized demand from automotive brand advertisers with concentrated manufacturing presence.
Kyushu
Fukuoka municipal authorities expand digital screen networks across airport and rail properties as the primary growth node outside Japan's main island. METI guidelines on digital infrastructure reshape deployment standards for LED systems in regional transportation hubs. The Fukuoka-Hakata station complex anchors network buildouts that extend digital inventory into northern Kyushu prefectures.
Hokkaido
Sapporo and regional rail operators maintain lower digital penetration due to harsh winter conditions and reduced commuter density compared to Honshu corridors. JIS standards for electronic display safety create compliance thresholds that elevate procurement costs for outdoor installations in sub-zero environments. The Sapporo Snow Festival and seasonal tourism generate temporary experiential demand rather than permanent networked infrastructure commitments.
Japan OOH and DOOH Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with agency-holding companies and rail-affiliated operators commanding premium network positions. The market structure reflects consolidation around concession-holding entities with direct transit authority relationships, while programmatic specialists compete on audience analytics capabilities. Three archetypes dominate: integrated agency-network operators, rail-captive concession holders, and programmatic technology platforms. Competitive moves center on multi-year concession tenders and content production capability acquisitions that secure placement control across premium real estate.
Within the integrated agency tier, Dentsu Inc. and Hakuhodo DY Holdings Inc. exemplify holding-company structures that span creative production through media placement. LIVE BOARD Inc. occupies a position among programmatic specialists, while JR East Marketing & Communications anchors the rail-captive concession segment. These entities represent the strategic positioning spectrum from full-service integration to technology-enabled trading platforms.
| Leading Market Players |
|---|
| Dentsu Inc. |
| MCDecaux (JCDecaux Group) |
| LIVE BOARD Inc. |
| Kyoritz Advertising Agency Co., Ltd. |
| Hit Co., Ltd. |
| Hakuhodo DY Holdings Inc. |
| JR East Marketing & Communications, Inc. |
| Tokyo Metro Advertising, Inc. |
| Osaka Metro Advertising, Inc. |
| Others |
Pricing and Supply Chain Analysis
JIS electromagnetic compatibility certification gates both hardware vendor qualification and rate-card tiering simultaneously, filtering smaller suppliers from municipal procurement pools while elevating premium network operators with integrated content production capabilities to command sustained pricing power across JR Group rail properties.
Pricing Analysis
Greater Tokyo Area rate cards sustain premiums that subsidize network buildouts in secondary Japanese cities. Three-tier pricing structure across premium, standard, and economy levels separates full-service networks with creative capabilities from commoditized display operators and legacy poster contractors. Cost compression in standard-tier inventory is intensifying because programmatic-trading convergence attracts mobile-first advertisers demanding impression-based accountability. Local retail promoters in prefectural capitals exhibit highest price sensitivity, while consumer packaged goods brands with centralized procurement functions in Minato-ku and Nishi-Shinjuku demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of gallium nitride substrates mitigates foundry concentration risk among East Asian suppliers serving fine-pitch LED module production. Hardware manufacturing draws from Taiwan, South Korea, and China for semiconductor substrates, Japan for precision LED drivers, and domestic assembly for transit-grade enclosures. Single-source vulnerability in gallium nitride wafer supply creates exposure to geopolitical disruption. Distribution runs through rail-captive concession holders and programmatic technology platforms to end advertisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobile and digital video advertising presents a substitution threat that OOH and DOOH incumbents must navigate through impression-based accountability convergence and creative capability differentiation.
For Market Incumbents: Fortify concession-holding positions across JR East and private railway properties through multi-year tender participation and backward integration into motion-optimized content production. Secure disaster-warning integration certifications ahead of Tokyo and Osaka municipal mandate expansion to lock out smaller competitors from procurement pools. For New Entrants and Emerging Players: Differentiate on real-time audience analytics capabilities targeting the Kansai corridor where Osaka-Kobe-Kyoto rail nodes carry substantial passenger volumes at 40% lower digital screen density per platform than Tokyo benchmarks. Pursue white-space concession tenders in Fukuoka and northern Kyushu prefectures where municipal authorities actively expand airport and rail screen networks. For Investors and Strategic Acquirers: METI enforcement of energy conservation standards under the Act on the Rational Use of Energy reshapes the acquisition landscape toward hardware vendors with certified high-efficiency LED driver portfolios. Long-term viability centers on programmatic-trading convergence enabling impression-based buying models. Monitor adoption velocity of computer vision analytics platforms merging with inventory management systems as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Concession Tender Participation | Secures premium rail estate access against JR Group and private railway operator consolidation. |
| Backward Integration into Creative Production | Captures margin pools migrating from commoditized display operators to full-service networks. |
| Disaster-Warning Integration Certification | Meets Tokyo and Osaka municipal procurement criteria reshaping hardware specifications. |
| Programmatic Trading Platform Development | Enables impression-based buying models attracting mobile-first advertisers in Minato-ku. |
| Fine-Pitch LED Module Specification | Displaces legacy LCD systems in platform-edge environments with passenger dwell times exceeding 90 seconds. |
Research Methodology
Initial hypotheses were tested against primary input from transit authority procurement officers, railway advertising concession managers, LED hardware vendor technical directors, and programmatic platform engineers, and refined through secondary validation against METI policy documents, JIS certification databases, municipal ordinance filings, and JR Group concession tender disclosures. Bottom-up installation counts across Tokyo, Osaka, Fukuoka, and Nagoya station networks triangulated with top-down advertising spend estimates from media agency holding companies.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation dimensions modeled include media format, technology type, service bundling tier, and commuter density corridor classification. CAGRs were derived from logistic diffusion curves fitted to digital display penetration rates against static format residual demand. Industry-specific forecast inputs incorporate METI energy efficiency compliance timelines and municipal disaster-warning integration mandate rollout schedules.
Material uncertainties — gallium nitride substrate supply disruption, JIS certification timeline extensions, and programmatic trading adoption velocity — sit outside the modeled envelope. Forecasts reflect assumptions about concession tender award patterns and advertiser budget rotation from paper posters to networked LED inventory. Revision becomes warranted when mobile advertising impression pricing convergence crosses thresholds that accelerate or retard DOOH accountability standard adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Brand Licensing Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Native Video Advertising Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
North America Programmatic Advertisement Market
Advertising and Marketing Media
Advertisement Management Solutions Market