
 Indonesia OOH and DOOH Market | 2026-2036
Indonesia OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia OOH and DOOH Market Insights
Programmatic ad-serving infrastructure is reconfiguring how inventory reaches buyers across Indonesia's fragmented media landscape. JCDecaux SE leverages its airport concession network to sustain premium positioning in Jakarta and Bali gateways. Next Digital Indonesia anchors metropolitan digital screen density through mall and retail partnerships. StickEarn differentiates via gig-economy driver-wrapped vehicles that extend reach into secondary cities where static inventory dominates.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display media deployed in public spaces for commercial messaging, spanning static vinyl billboards, LED digital screens with remote content management capability, and vehicle-mounted mobile installations. The primary commercial purpose centers on capturing consumer attention during transit, dwell, and purchase-intent moments outside residential environments. Digital screens command disproportionate margin expansion due to real-time auction mechanics and dynamic creative optimization, while transit ads represent the fastest-growing format category as Jakarta MRT corridor extensions and Transjakarta busway upgrades multiply premium inventory nodes. Static billboards retain volume leadership in tier-two cities where capital constraints limit LED conversion.
BIS certification requirements for imported display hardware shape procurement timelines and supplier qualification for Indonesian operators. The country's national advertising regulator and local municipal permitting offices jointly control street furniture placement rights, creating fragmented approval pathways across Jakarta, Surabaya, and Bandung. Stakeholders must monitor how forthcoming local content regulations affect LED module sourcing strategies and whether transit authority concession renewals in Greater Jakarta unlock exclusive digital network rights.
Market Dynamics
Programmatic ad-serving infrastructure is collapsing the traditional sales cycle between inventory owners and media buyers across Indonesia's fragmented OOH landscape. Real-time auction mechanics now compress what required weeks of manual negotiation into milliseconds, forcing operators to rebuild yield management systems around dynamic pricing algorithms.
Growth Catalysts
- Transit Infrastructure Expansion:Jakarta MRT corridor extensions and Transjakarta busway upgrades multiply premium digital inventory nodes along Java's northern coastal corridor.
- MIIT-Influenced Display Imports:Chinese display technology procurement channels are streamlining LED module sourcing timelines for Indonesian operators seeking BIS-aligned hardware certification.
- Retail Brand Programmatic Commitments:FMCG and luxury advertisers in Surabaya and Jakarta are shifting budget allocation toward programmatic guaranteed deals on mall-based digital screens.
Market Restraints
- Import Hardware Certification Friction:BIS certification requirements for LED modules create 12-18 month procurement timelines that constrain network expansion velocity.
- Municipal Permitting Fragmentation:Street furniture placement rights require separate approvals from Jakarta, Surabaya, and Bandung municipal authorities with non-standardized documentation.
- Static-to-Digital Capex Gap:Tier-two city operators face capital constraints limiting LED conversion, perpetuating vinyl billboard volume dominance outside Java's primary metros.
Strategic Opportunities
- Secondary City Mobile Wrap Networks:Surabaya-based operators can replicate StickEarn's gig-economy driver model to penetrate Medan, Makassar, and Denpasar where static inventory still dominates.
- Airport Concession Digital Renewal:Soekarno-Hatta and Ngurah Rai gateway concession renegotiations present exclusive network rights for integrated digital-physical installations.
- Local Content Regulation Preparation:Anticipated domestic assembly requirements for LED modules create first-mover advantage for operators establishing Indonesian surface-mount partnerships ahead of mandate implementation.
Industry Challenges
- Yield Management Talent Scarcity:Programmatic auction optimization and dynamic creative trafficking require skill sets concentrated in Singapore and Kuala Lumpur, not Jakarta.
- Legacy Sales Force Retraining:Established OOH operators must restructure commission structures and technical literacy for account teams accustomed to annual rate-card negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia OOH and DOOH Market |
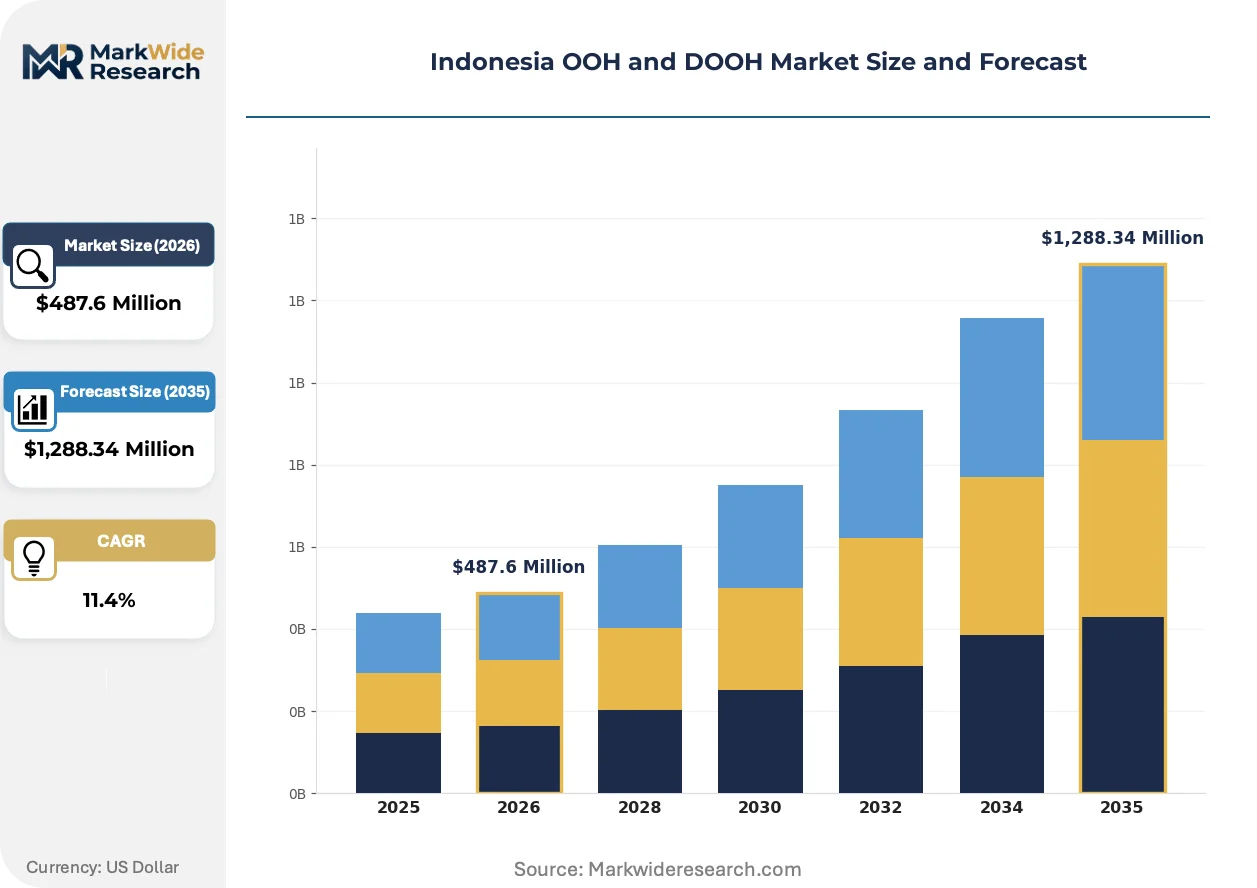
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Billboards, Posters, Digital Screens, Transit Ads Audience Type: Urban Shoppers, Commuters, Tourists, Event Attendees Installation Type: Static, Digital, Interactive, Mobile Content Type: Promotional, Informational, Experiential, Brand Awareness |
| Companies Covered | JCDecaux SE, Hivestack, Next Digital Indonesia, Moving Walls, Eye Indonesia, StickEarn, 8Infini, Arfadia, Dentsu Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia OOH and DOOH Market Trends and Innovations
Real-time data integration is collapsing the boundary between audience measurement and creative execution in Indonesian DOOH deployments. Three interconnected developments are compressing planning cycles and rewiring competitive positioning.
Dynamic creative optimization (DCO) engines are collapsing the production-to-playback pipeline for Indonesia's retail and transit screen networks. Unilever and Indofood brand teams now deploy weather-triggered, inventory-responsive creative variants without reshooting base assets. JCDecaux's airport network and Next Digital's mall partnerships are prioritizing DCO-enabled inventory in pitch materials, compressing traditional creative agency retainers into self-service platform subscriptions.
BIS certification requirements for imported display hardware are reshaping procurement strategies across Indonesian operator networks. The Bureau of Indian Standards alignment for LED modules forces suppliers to pre-certify driver ICs and power management components before shipment, extending supplier qualification timelines. Operators in Jakarta and Surabaya are responding by consolidating purchase volumes through MIIT-registered Chinese manufacturers with established Indonesian distributor relationships.
Retail advertisers are unbundling media planning from creative production, bringing audience data science in-house while outsourcing playback logistics. This procurement pattern disrupts the traditional full-service agency model that dominated Indonesian OOH buying. FMCG brands in Surabaya now license programmatic demand-side platforms directly, contracting screen operators for inventory access without intermediary planning commissions.
Indonesia OOH and DOOH Market Segmentation
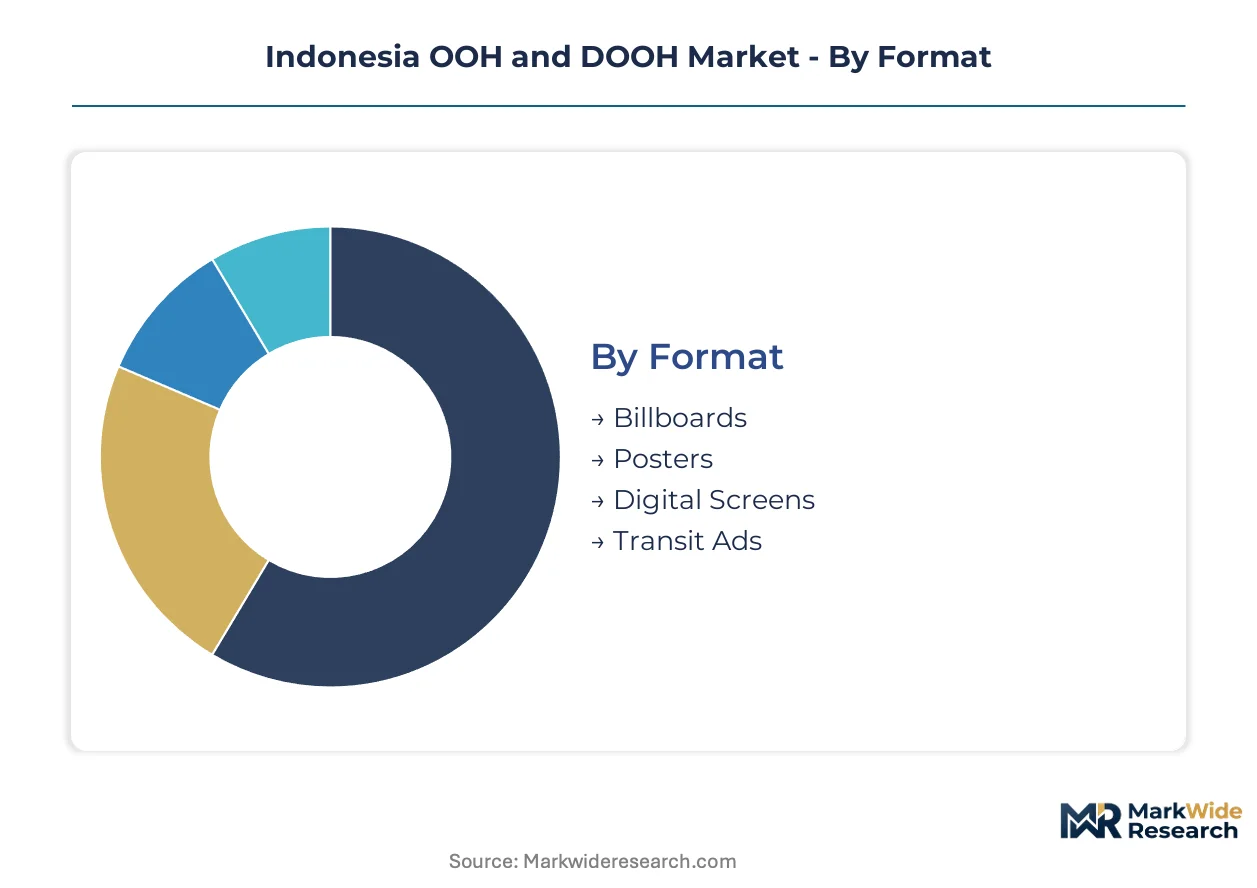
Format diversification across Indonesia's OOH landscape reflects divergent capital intensity and margin profiles. Audience targeting precision and installation technology choices determine yield optimization potential for operators navigating Jakarta's premium inventory scarcity versus tier-two city expansion.
Format:
Cost tier differentiation separates high-capex digital networks from legacy static assets across Indonesian metropolitan corridors.
- Billboards:Large-format vinyl or flex-faced structures dominate arterial road visibility in Jakarta, Surabaya, and Bandung. Municipal permitting fragmentation constrains new site approvals, entrenching incumbents with grandfathered positions along Java's northern coastal highway network.
- Digital Screens:LED modules with remote content management enable programmatic auction mechanics and dynamic creative optimization. Transit corridor installations at Jakarta MRT stations and Surabaya mall atriums command premium rate cards due to dwell-time metrics and real-time audience measurement.
- Posters:Standardized paper or vinyl displays at bus shelters and street furniture locations offer entry-level inventory for regional FMCG campaigns. Lower procurement thresholds attract mid-market advertisers excluded from premium digital rate floors.
- Transit Ads:Vehicle wraps, station dominations, and in-carriage panels leverage Jakarta MRT and Transjakarta busway infrastructure expansion. BIS certification requirements for imported LED modules create hardware procurement bottlenecks that static wrap formats bypass.
Billboards hold installed capacity. Digital Screens is rotating up the share rankings.
Audience Type:
Application focus determines creative format selection and placement geography within Indonesia's fragmented urban hierarchy.
- Urban Shoppers:Mall-based digital networks target purchase-intent moments at Jakarta's Grand Indonesia and Surabaya's Tunjungan Plaza. Retail brand programmatic commitments concentrate inventory procurement around these high-frequency shopping destinations.
- Commuters:Daily transit riders along Jakarta MRT corridors and Transjakarta dedicated lanes generate repetitive impression frequency. Dwell-time metrics at station platforms enable dynamic creative optimization triggered by arrival countdown data.
- Tourists:International arrivals at Soekarno-Hatta and Ngurah Rai gateways encounter JCDecaux's airport concession networks. Seasonal demand volatility requires yield management systems balancing guaranteed bookings with programmatic auction fill.
- Event Attendees:Temporary installations at Jakarta convention centers and Surabaya sports venues capture concentrated attention windows. Short-term activation contracts demand flexible logistics networks absent from permanent infrastructure operators.
Commuters deliver impression volume consistency. Tourists is climbing the fastest in rate card realization.
Installation Type:
Technology maturity separates established static formats from emerging interactive and mobile deployment models.
- Static:Vinyl billboards and paper posters retain volume leadership in tier-two cities where LED conversion capex exceeds operator balance sheet capacity. Medan, Makassar, and Denpasar inventory remains predominantly static due to municipal permitting delays and hardware import certification friction.
- Digital:Networked LED screens with centralized content management enable real-time auction mechanics that collapse traditional sales cycles. MIIT-influenced display technology imports from Chinese manufacturers are streamlining procurement timelines for BIS-aligned certification.
- Interactive:Touch-enabled screens and gesture-responsive displays at Jakarta mall atriums generate engagement metrics beyond passive impression counting. Higher unit economics require advertiser education on performance attribution versus traditional reach-and-frequency planning.
- Mobile:Vehicle-mounted installations and StickEarn's gig-economy driver-wrapped networks extend reach into secondary cities. Capital-light deployment models bypass municipal street furniture permitting constraints that immobilize static site development.
Static dominates installed base. Mobile is gaining share fastest among new capital deployment.
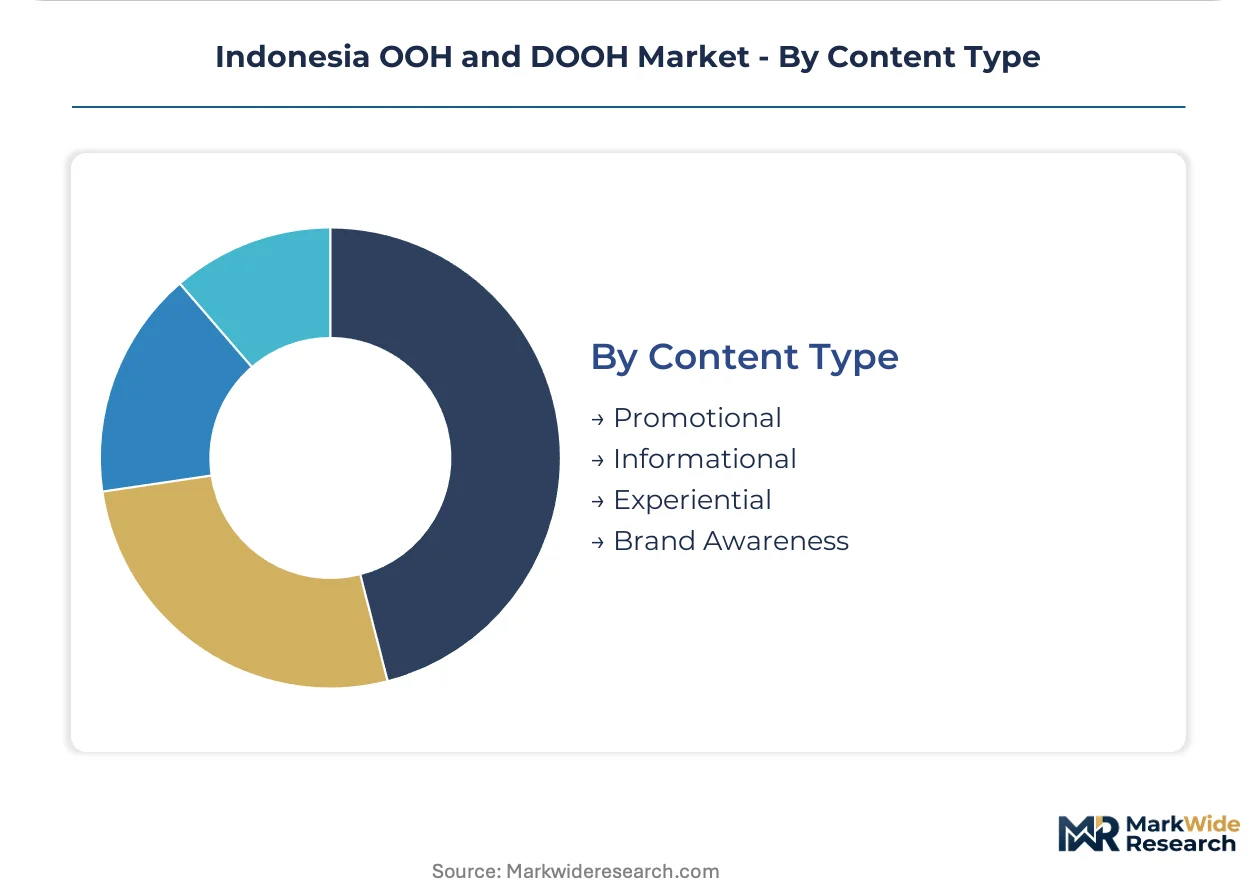
Content Type:
Customer objective segmentation aligns creative production complexity with measurement methodology and pricing structure.
- Promotional:Price-point and offer-driven messaging demands rapid creative turnaround and geo-fenced deployment flexibility. FMCG brands in Surabaya leverage programmatic demand-side platforms to trigger inventory-responsive variants without agency intermediary commissions.
- Informational:Wayfinding, public service, and transit schedule content occupies concession-mandated inventory shares at Jakarta MRT stations. Municipal authority requirements for civic messaging constrain commercial yield optimization at certain network nodes.
- Experiential:Immersive installations combining physical presence with augmented reality or sensory activation command premium production budgets. Limited scalability restricts deployment to flagship locations with documented footfall verification.
- Brand Awareness:Sustained presence campaigns prioritize reach accumulation over immediate response attribution. Annual rate-card commitments from established Indonesian conglomerates provide baseline revenue visibility for operator network planning.
Brand Awareness commands committed annual budgets. Promotional is rotating up the share rankings through programmatic channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese display manufacturers route MIIT-registered LED modules through Jakarta and Surabaya procurement channels, feeding BIS certification pipelines that supply Java's northern coastal corridor expansion.
Java
Jakarta MRT corridor extensions and Transjakarta busway upgrades multiply premium digital inventory nodes along the northern coastal highway network. BIS certification requirements for imported display hardware shape procurement timelines for operators seeking LED module approvals. Greater Jakarta and Surabaya concentrate programmatic digital screen density through mall partnerships and transit station installations.
Sumatra
Medan's static billboard inventory retains volume leadership where capital constraints limit LED conversion velocity. Municipal permitting fragmentation across North Sumatra provincial authorities creates non-standardized documentation requirements for street furniture placement. The city of Medan anchors regional FMCG campaign deployment through standardized paper and vinyl poster networks.
Sulawesi
Makassar's secondary city status perpetuates vinyl billboard dominance as operator balance sheets exclude high-capex digital network expansion. Local municipal authorities control street furniture placement rights through fragmented approval pathways distinct from Java's regulatory frameworks. South Sulawesi's industrial corridor generates transit advertising demand through port logistics and manufacturing facility commuting patterns.
Bali
International tourist arrivals at Ngurah Rai gateway sustain premium rate card realization for airport concession networks. Seasonal demand volatility requires yield management systems balancing guaranteed bookings with programmatic auction fill. Denpasar and Kuta corridor installations target purchase-intent moments at hospitality and retail destinations.
Kalimantan
Resource extraction industry commuting patterns generate repetitive impression frequency along mining corridor transit routes. Capital-light mobile wrap deployment models bypass municipal street furniture permitting constraints that immobilize static site development. Balikpapan and Samarinda anchor regional brand awareness campaigns through vehicle-mounted installation networks.
Indonesia OOH and DOOH Market Competitive Landscape
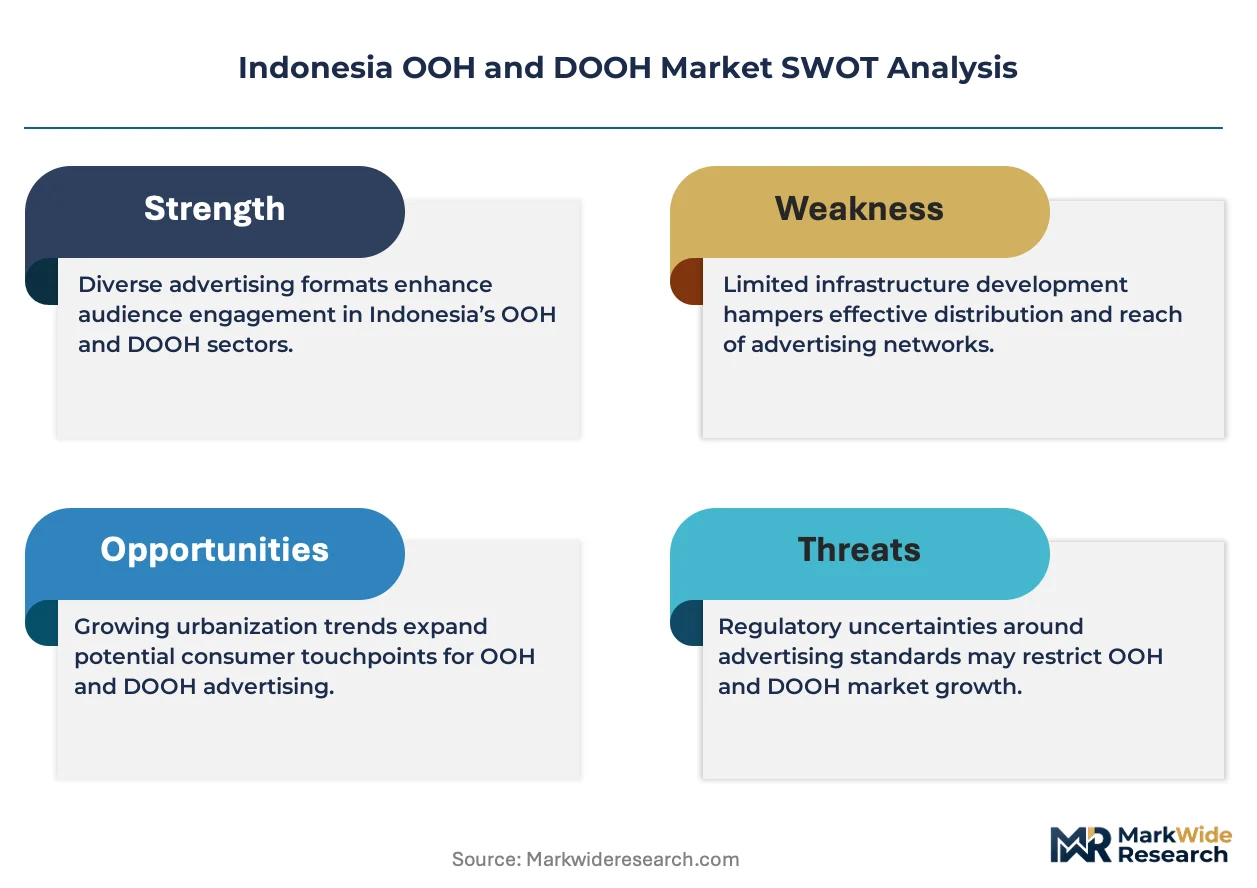
Channel-controlling players compete with product-specialist players across Indonesia's fragmented OOH landscape. Airport concession operators and mall-based network owners hold consolidated positions in premium inventory nodes, while mobile wrap specialists and programmatic platform providers fragment the mid-market tier. Three archetypes dominate: infrastructure-locked incumbents with grandfathered municipal permits, technology-integrated operators with dynamic creative optimization capabilities, and capital-light deployers leveraging gig-economy logistics networks. Competitive moves concentrate on concession renewal negotiations and programmatic yield management system deployment.
Among infrastructure-locked incumbents, JCDecaux SE occupies a position representing airport concession network control, while Next Digital Indonesia exemplifies metropolitan digital screen density through mall and retail partnerships. StickEarn sits within the capital-light deployer tier, representing gig-economy driver-wrapped vehicle extension into secondary cities where static inventory dominates.
| Leading Market Players |
|---|
| JCDecaux SE |
| Hivestack |
| Next Digital Indonesia |
| Moving Walls |
| Eye Indonesia |
| StickEarn |
| 8Infini |
| Arfadia |
| Dentsu Indonesia |
| Others |
Pricing and Supply Chain Analysis
BIS certification bottlenecks for LED module imports create 12-18 month procurement delays that simultaneously compress digital screen margins and force operator consolidation around MIIT-registered Chinese suppliers with established Indonesian distributor relationships. This regulatory chokepoint widens pricing spreads between premium programmatic-enabled inventory and static vinyl alternatives while reshaping procurement toward volume-consolidated purchasing agreements.
Pricing Analysis
Current-generation LED digital screens command rate-card premiums of 3-4x over prior-generation static vinyl billboards, while next-generation interactive and mobile formats are capturing experimental budgets from retail advertisers seeking engagement metrics beyond passive impression counting. Pricing stratifies across premium programmatic-guaranteed, standard direct-sold, and economy programmatic-open tiers, with differentiation driven by certification grade and dwell-time measurement capability. Cost compression in the economy tier is intensifying as Chinese display manufacturers flood the market with BIS-aligned hardware. Tier-two city operators show highest price sensitivity due to capital constraints limiting LED conversion, while Jakarta-based airport and mall networks demonstrate lowest sensitivity given exclusive concession positioning.
Supply Chain Analysis
Tariff exposure between China and Indonesia dominates supply chain risk calculations for LED module procurement, with MIIT-registered manufacturers in Shenzhen and Guangzhou serving as primary sourcing nodes. Indonesian operators draw from Chinese driver ICs, Korean power management components, and Taiwanese LED chip substrates to assemble compliant display hardware. Single-source vulnerability concentrates in BIS-certified driver IC suppliers, where qualification timelines create effective lock-in effects. Distribution runs through Jakarta and Surabaya-based import distributors who manage certification documentation and customs clearance before downstream delivery to operator installation teams across Java's northern coastal corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward programmatic-enabled advertisers consolidating media planning functions in-house, fragmenting the traditional full-service agency intermediary layer that once controlled Indonesian OOH procurement decisions.
For Market Incumbents: Entrench airport and premium mall concession positions through early renewal negotiations ahead of competitive bidding rounds, while investing in dynamic creative optimization capabilities to differentiate against technology-integrated challengers. Yield management system deployment represents the critical lever for defending margin position against retail brands bringing audience data science in-house. For New Entrants and Emerging Players: Build out capital-light mobile wrap networks in Medan, Makassar, and Denpasar where static inventory dominance and municipal permitting fragmentation create white-space opportunities inaccessible to infrastructure-locked incumbents. The gig-economy driver model pioneered by StickEarn offers the most penetrable entry angle, bypassing street furniture approval constraints that immobilize traditional site development. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors operators with programmatic infrastructure and exclusive concession rights over pure-play hardware deployers. Long-term viability hinges on securing renewable network positions in transit corridors and gateway airports. Watch for BIS certification timeline compression as the inflection signal indicating supply chain normalization and accelerated digital conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Programmatic Platform Integration | Enables real-time auction mechanics that collapse traditional sales cycles between inventory owners and media buyers. |
| Airport Concession Renewal | Soekarno-Hatta and Ngurah Rai gateway positions command premium rate cards through exclusive international arrival exposure. |
| Secondary City Mobile Expansion | Vehicle-mounted installations bypass municipal permitting constraints that immobilize static site development in tier-two markets. |
| BIS-Aligned Supplier Consolidation | Volume purchasing through MIIT-registered Chinese manufacturers streamlines certification timelines for LED module procurement. |
| Dynamic Creative Optimization Investment | DCO-enabled inventory attracts retail brand commitments seeking weather-triggered, inventory-responsive creative variants. |
Research Methodology
A standing panel of OOH network operators, programmatic platform engineers, retail brand media directors, and municipal permitting officials provided ongoing calibration against operating reality throughout the study period. Primary interviews with transit authority concession managers and mall partnership directors combined with secondary validation from BIS certification databases, MIIT hardware registration records, and municipal street furniture placement registries. Bottom-up installation counts across Jakarta, Surabaya, and Bandung triangulated against top-down media spending estimates from FMCG and luxury advertiser categories.
Scenario-bracketing around transit infrastructure completion timelines and BIS certification velocity variations bounded the projection horizon across format, audience type, installation technology, and content objective segmentation dimensions. CAGRs derived from installation growth trajectories, programmatic adoption curves, and retail brand budget reallocation patterns. Forecast inputs incorporated MRT corridor extension schedules, LED import volume trends, and municipal permitting approval rate observations.
The forecast holds incumbent behavior within observed patterns; aggressive concession renewal bidding by infrastructure-locked players or accelerated BIS certification streamlining by regulatory authorities would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Social Network Advertising Market
Advertising and Marketing Media
Germany OOH and DOOH Market
Advertising and Marketing Media
Asia Pacific Programmatic Advertising Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Out of Home Advertising Market
Advertising and Marketing Media
Austria OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
China OOH and DOOH Market
Advertising and Marketing Media
South Africa Out-Of-Home (OOH) and Digital Out-Of-Home (DOOH) Market
Advertising and Marketing Media
North America Advertising Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Europe Public Relation Services Market