
 APAC Interior Design Software Market | 2026-2036
APAC Interior Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Interior Design Software Market Outlook
Subscription-based feature licensing is pivoting how vendors monetize design tools across the region. Autodesk leverages its BIM ecosystem to anchor enterprise contracts with major architecture firms. Coohom competes through browser-native rendering that eliminates local hardware dependencies. Infurnia Technologies specializes in modular kitchen and wardrobe configuration tools for India's residential contractor segment.
APAC interior design software encompasses digital tools for spatial planning, material specification, and photorealistic visualization, typically operating through parametric modeling engines that process geometric constraints and lighting physics in real time. These platforms enable architects and real estate developers to shorten client approval cycles and reduce physical prototyping costs. Cloud-based deployment leads the market as bandwidth infrastructure improves across Indonesia, Vietnam, and the Philippines, while on-premise installations retain share among Japanese firms with stringent data sovereignty requirements. Residential design solutions command the largest revenue pool, though commercial design applications are expanding fastest as hybrid workplace retrofits accelerate across Singapore and Australia.
China's MIIT enforces GB standards for cloud service security classifications that foreign-hosted platforms must satisfy before domestic commercial deployment. Japan's METI promotes digital transformation subsidies that offset software acquisition costs for small and mid-sized design studios. India's TRAI data localization consultations create uncertainty for vendors routing rendering computations through overseas server farms. Stakeholders must monitor how cross-border data governance rulings affect cloud architecture decisions and partner selection across the region.
Market Dynamics
Cloud rendering pipelines are compressing hardware procurement cycles across APAC design studios, forcing vendors to re-architect licensing models around browser-native compute rather than perpetual workstation software.
Growth Catalysts
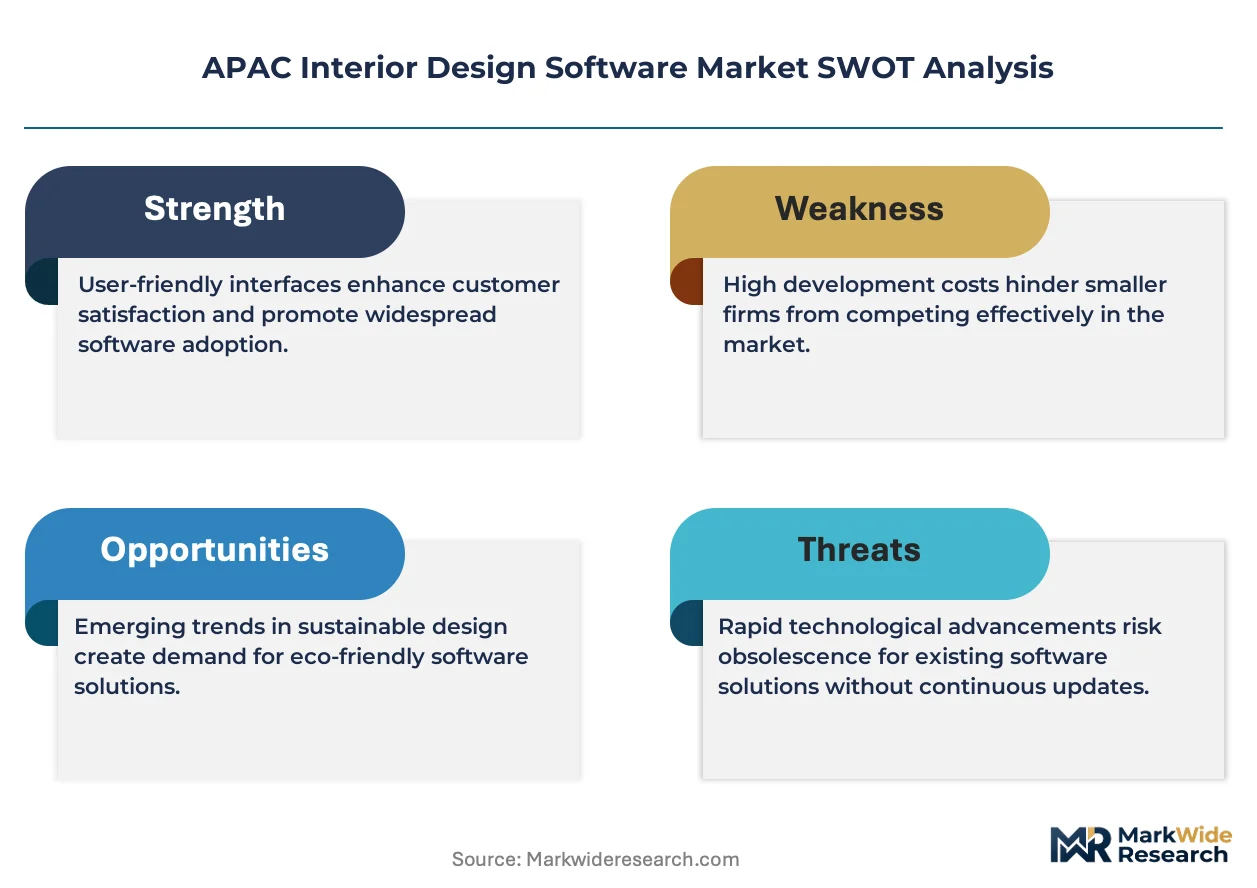
- MIIT Cloud Security Classifications:China's GB standards for data sovereignty create compliant pathways for foreign-hosted platforms to enter domestic commercial deployment.
- Hybrid Workplace Retrofits:Singapore and Australia commercial real estate developers accelerate visualization tool procurement for flexible office reconfigurations.
- Parametric Modeling Engines:Real-time geometric constraint processing enables Bangalore and Mumbai studios to collapse client approval timelines on high-rise residential projects.
Market Restraints
- GPU Supply Concentration:Taiwan and South Korea foundry dependencies create input cost volatility for vendors maintaining on-premise rendering farms.
- TRAI Data Localization Uncertainty:India's pending cross-border data rulings stall cloud architecture decisions for vendors routing computations through overseas servers.
- Legacy CAD File Format Lock-in:Proprietary Autodesk DWG dependencies constrain interoperability for emerging browser-native competitors.
Strategic Opportunities
- Vietnam and Philippines Bandwidth Expansion:Underpenetrated cloud infrastructure creates first-mover advantage for vendors establishing localized edge nodes.
- Modular Kitchen Configuration Tools:India's residential contractor segment demands specialized wardrobe and kitchen planning modules absent from generalist platforms.
- METI Digital Transformation Subsidies:Japan's small-studio software acquisition incentives offset customer acquisition costs for vendors targeting mid-market architecture practices.
Industry Challenges
- Real-Time Lighting Physics Expertise:Shortage of shader programming talent constrains vendor ability to optimize browser-based ray-tracing performance.
- Cross-Border Compliance Timelines:Multi-jurisdictional data governance certifications delay product launches across Indonesia, Thailand, and Malaysia simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Interior Design Software Market |
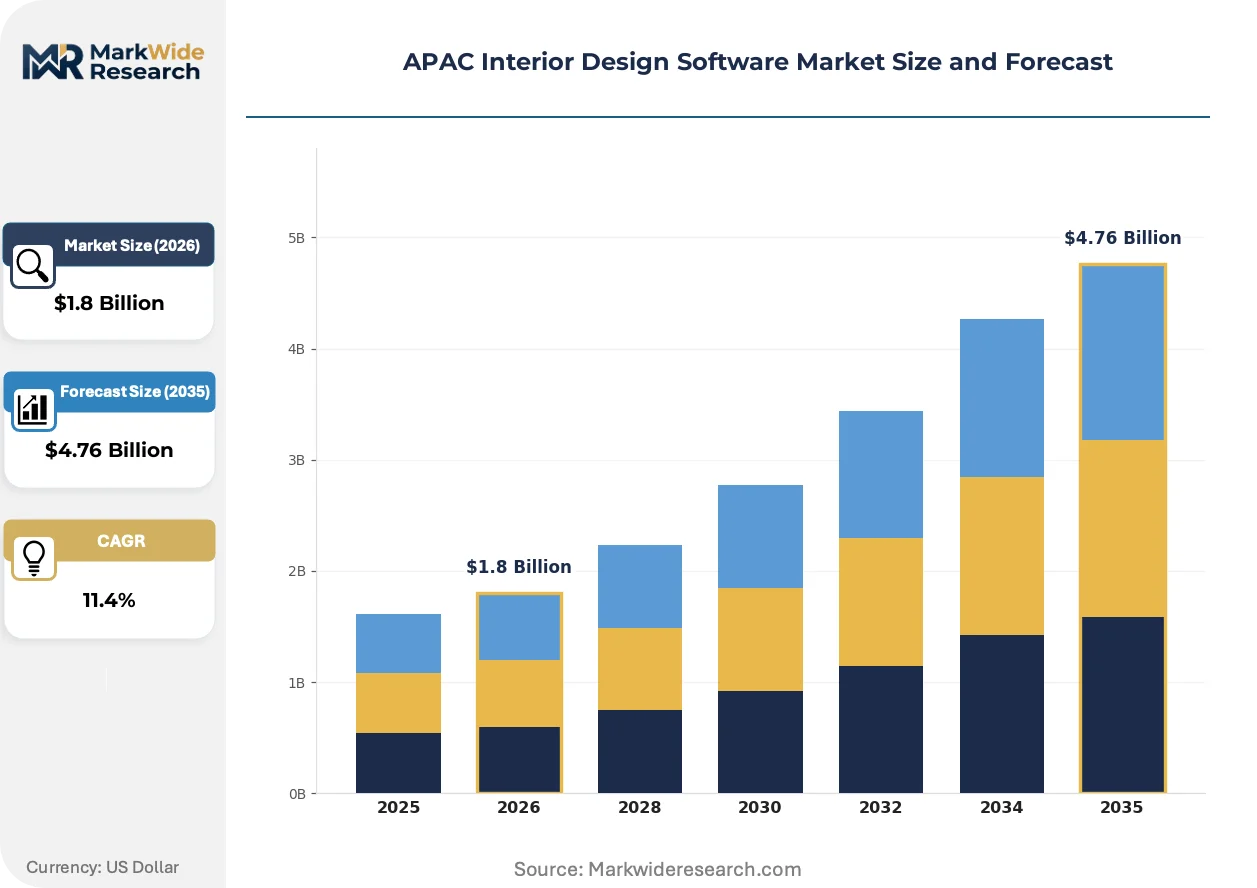
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, CAD Software, Rendering Tools, Visualization Software Deployment: On-Premise, Cloud-Based, Hybrid, Subscription End User: Architects, Designers, Contractors, Real Estate Developers Solution: Residential Design, Commercial Design, Landscape Design, Furniture Design |
| Companies Covered | Autodesk, Trimble, Dassault Systèmes, Coohom, AiHouse, Foyr, Infurnia Technologies, Homestyler, SketchUp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Interior Design Software Market Strategic Shifts
Generative AI is infiltrating spatial planning workflows across APAC studios, compressing concept-to-render pipelines while forcing vendors to reposition human designers as curators rather than draftspersons.
Browser-native WebGL rendering is absorbing the computational burden previously handled by local GPU workstations. Mid-sized Shanghai and Seoul studios adopt these platforms within eighteen-month refresh cycles. The shift is absorbing capital expenditure from hardware procurement into recurring SaaS licensing.
METI's digital transformation subsidy framework mandates ISO 27001 certification for vendor eligibility. Japanese small and mid-sized studios now filter procurement shortlists through compliance checklists. The policy is absorbing non-certified competitors from the mid-market segment.
Subscription unbundling is fragmenting how Bangkok and Jakarta studios purchase design capabilities. Customers now assemble toolchains from specialized kitchen, lighting, and material libraries rather than monolithic suites. The pattern is most visible among residential contractors in Indonesia's secondary cities.
APAC Interior Design Software Market Segmentation
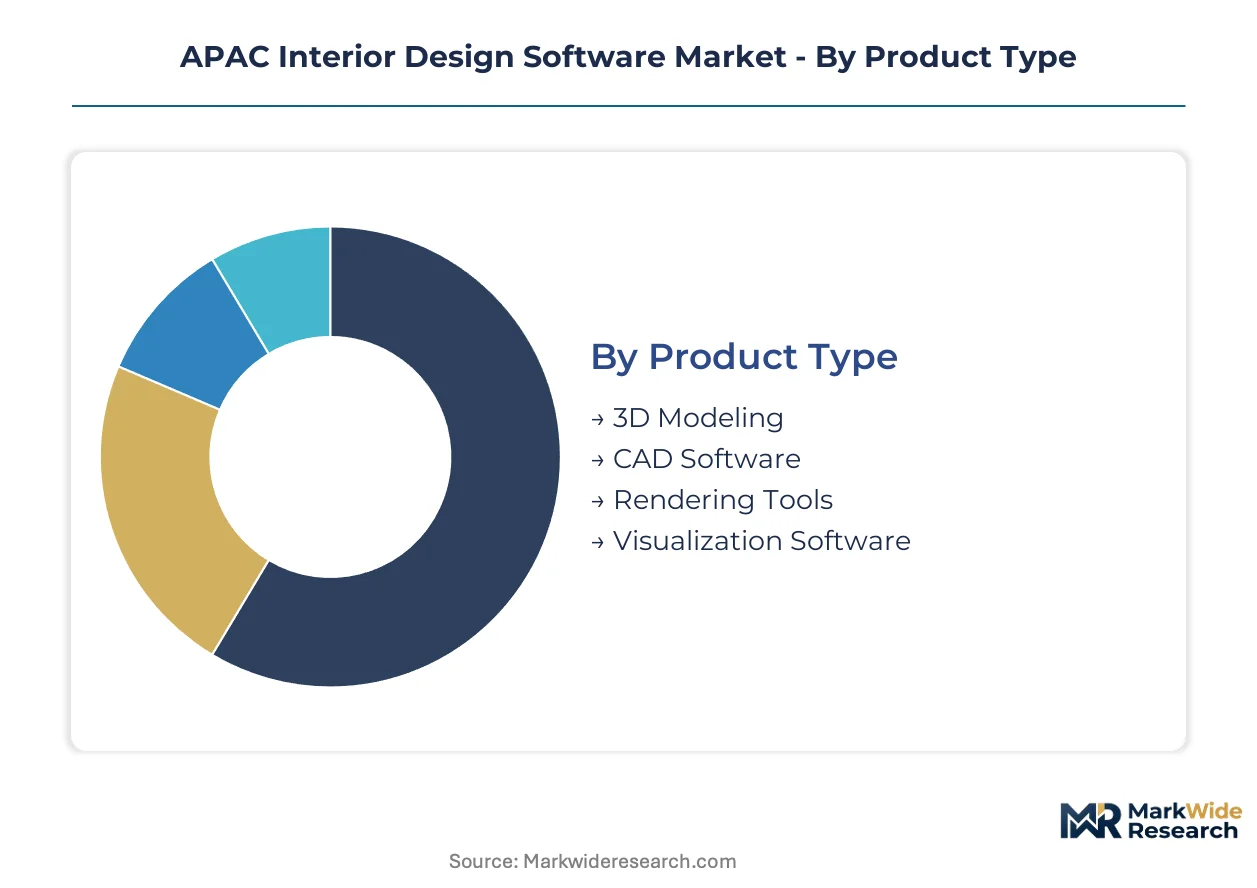
Interior design software procurement across APAC follows distinct upgrade cycles tied to hardware refresh timelines, cloud infrastructure maturity, and regulatory compliance windows. Vendors must align product roadmaps with these replacement rhythms to capture budget allocation cycles in architecture and real estate development sectors.
Product Type:
Studio hardware refresh cycles drive replacement decisions, with GPU workstation upgrades triggering concurrent software evaluations every 24-36 months.
- 3D Modeling:Parametric engines process geometric constraints and spatial relationships in real time. Demand concentrates in Bangalore and Mumbai high-rise residential studios where client approval compression drives adoption.
- CAD Software:Drafting platforms with DWG-native file handling anchor enterprise architecture workflows. Japanese firms with stringent data sovereignty requirements sustain on-premise deployments despite cloud migration pressure.
- Rendering Tools:Ray-tracing modules execute photorealistic lighting physics calculations.
- Visualization Software:Browser-native WebGL platforms eliminate local GPU dependencies.
3D Modeling sits at the top of the volume ranking, with Visualization Software climbing the fastest.
Deployment:
Cost tier differentiation separates capital-intensive perpetual licenses from operational expenditure SaaS models, reshaping vendor revenue recognition and customer cash flow profiles.
- Cloud-Based:Browser-native compute shifts rendering workloads to distributed server farms. Indonesia, Vietnam, and Philippines bandwidth expansion creates first-mover advantage for vendors establishing localized edge nodes.
- On-Premise:Local installation retains data within physical infrastructure boundaries. Japanese METI subsidy eligibility and ISO 27001 certification requirements filter procurement shortlists toward compliant domestic hosting.
- Hybrid:Split architectures process sensitive files locally while offloading compute-intensive rendering.
- Subscription:Recurring licensing unbundles capability modules for flexible procurement.
Cloud-Based deployment commands the largest revenue pool, with Subscription models gaining share fastest.
End User:
Customer type specialization determines feature prioritization, with enterprise architects demanding interoperability while residential contractors seek kitchen-specific configuration tools.
- Architects:BIM ecosystem integration requirements dominate procurement criteria. Autodesk enterprise contracts anchor major firm workflows through file format lock-in and multi-disciplinary collaboration protocols.
- Real Estate Developers:Visualization speed compresses pre-sales marketing timelines. Southeast Asian residential developers accelerate cloud-based platform procurement to shorten client approval cycles.
- Designers:Freelance practitioners prioritize browser-native accessibility over workstation performance.
- Contractors:India's residential construction segment drives modular kitchen and wardrobe planning module demand.
Architects sit at the top of the volume ranking, with Real Estate Developers expanding most quickly.
Solution:
Application maturity varies across building typologies, with residential workflows standardizing faster than commercial retrofit complexity.
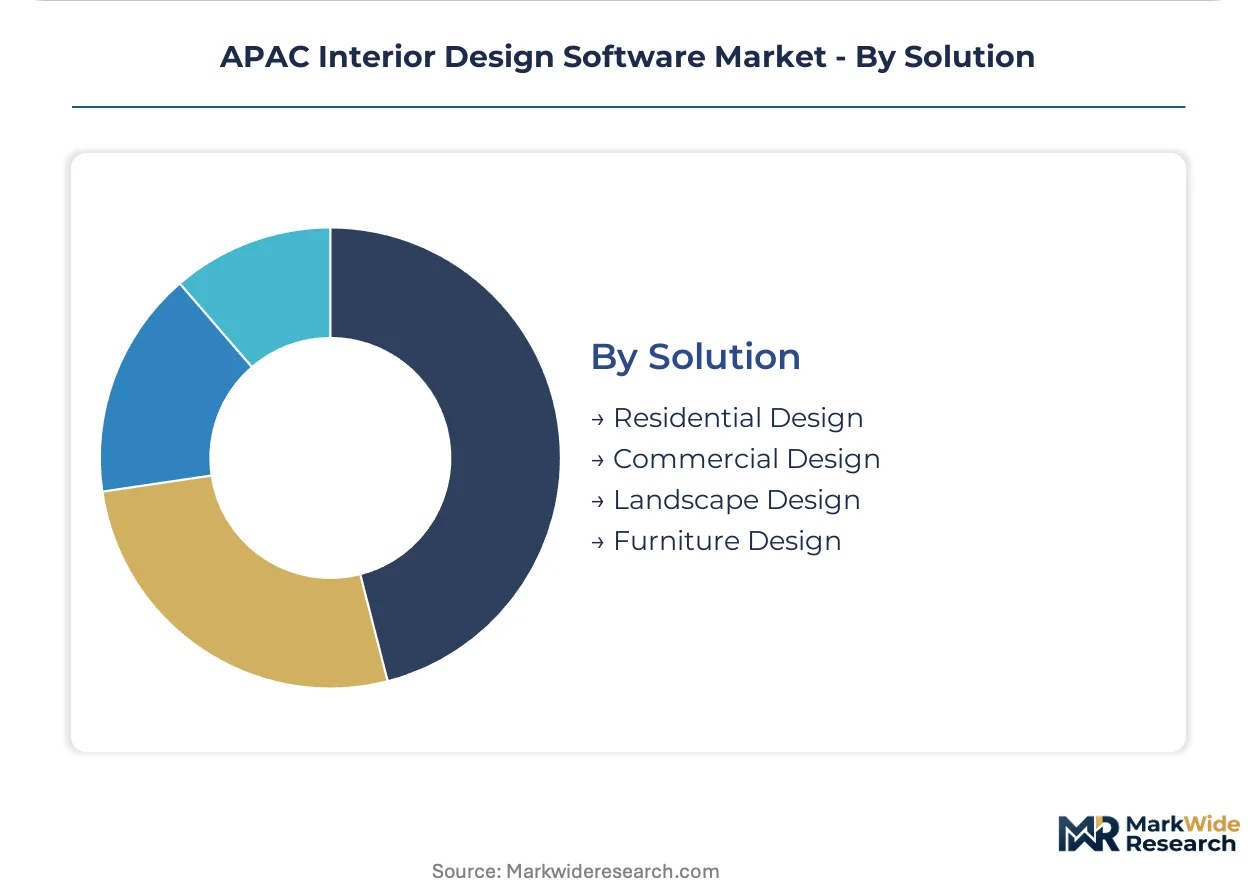
- Residential Design:High-rise apartment visualization dominates revenue concentration. Bangalore and Mumbai studios deploy 3D rendering tools for rapid client iteration on unit layouts and material specifications.
- Commercial Design:Hybrid workplace retrofits accelerate across Singapore and Australia. Flexible office reconfiguration demands drive fastest-expanding procurement for spatial planning and furniture systems.
- Landscape Design:Outdoor spatial planning integrates terrain modeling and vegetation libraries.
- Furniture Design:Product-level configuration tools support manufacturing workflow integration.
Residential Design sits at the top of the volume ranking, with Commercial Design climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting cloud infrastructure investment toward jurisdictions with clearer data governance frameworks. Vendors are relocating rendering compute capacity to markets where compliance costs are lower and certification timelines are predictable.
China
MIIT cloud security classifications and GB standards for data sovereignty are creating compliant pathways for foreign-hosted platforms entering domestic commercial deployment. Shanghai and Beijing studios drive enterprise adoption of parametric modeling engines for high-rise residential visualization.
Japan
METI digital transformation subsidies offset software acquisition costs for small and mid-sized design studios. Tokyo and Osaka architecture practices filter procurement through ISO 27001 certification requirements, sustaining on-premise deployments despite cloud migration pressure.
India
TRAI data localization consultations create uncertainty for vendors routing rendering computations through overseas server farms. Bangalore and Mumbai studios anchor regional demand for 3D rendering tools, compressing client approval timelines on high-rise residential projects.
Singapore
Hybrid workplace retrofits accelerate commercial real estate developer procurement of visualization tools for flexible office reconfigurations. The city-state's bandwidth infrastructure and data center density attract vendors establishing regional edge nodes for Southeast Asian markets.
Australia
Commercial design applications expand fastest as hybrid workplace retrofits drive spatial planning and furniture systems procurement. Sydney and Melbourne studios adopt browser-native WebGL platforms within compressed hardware refresh cycles.
APAC Interior Design Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The vendor base clusters around three tiers: enterprise platform ecosystems anchoring major architecture firms, browser-native challengers eliminating local GPU dependencies, and specialized module providers serving residential contractor segments. Strategic moves concentrate on M&A for BIM interoperability and geographic expansion through localized edge node deployment.
Within the enterprise platform tier, Autodesk anchors major firm workflows through file format lock-in and multi-disciplinary collaboration protocols. Coohom exemplifies the browser-native challenger archetype, occupying a position that eliminates local hardware dependencies for mid-sized studios. Infurnia Technologies represents the specialized module provider archetype, serving India's residential contractor segment with configuration tools for modular kitchens and wardrobes.
| Leading Market Players |
|---|
| Autodesk |
| Trimble |
| Dassault Systèmes |
| Coohom |
| AiHouse |
| Foyr |
| Infurnia Technologies |
| Homestyler |
| SketchUp |
| Others |
Value Chain & Pricing Dynamics
GPU memory pricing indices cascade through APAC interior design software supply chains, compressing margins for workstation-dependent vendors while amplifying SaaS pricing power for browser-native platforms serving bandwidth-expanding Southeast Asian markets.
Pricing Analysis
Distributor margins on perpetual CAD licenses are collapsing under cloud-subscription displacement, while direct-to-enterprise SaaS contracts command premium pricing through ISO 27001 certification bundling. Three-tier pricing structure across premium, standard, and economy levels separates Autodesk enterprise anchoring from Coohom mid-market accessibility and Infurnia contractor-specialist modules. Pricing pressure stems from GPU foundry cost volatility in Taiwan and South Korea, which squeezes on-premise rendering farm economics. Residential contractors in India's secondary cities exhibit highest price sensitivity, while Japanese METI-subsidized studios show lowest sensitivity due to acquisition cost offsets.
Supply Chain Analysis
Refurbished workstation GPU flows from Seoul and Taipei gaming cafes feed secondary markets in Jakarta and Bangkok, extending hardware refresh cycles for cash-constrained studios. Cloud rendering infrastructure concentrates in Singapore, Sydney, and Tokyo data center clusters. Taiwan and South Korea foundry dependencies for GPU fabrication create single-source vulnerability for vendors maintaining captive rendering capacity. Distribution runs through hyperscaler marketplaces and direct vendor sales teams, bypassing traditional software resellers as browser-native deployment eliminates physical media logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in APAC interior design software rests on GPU cost absorption into cloud infrastructure and premium-tier certification bundling for compliance-sensitive Japanese procurement committees.
For Market Incumbents: Acquire browser-native rendering engine startups to neutralize Coohom's hardware-elimination threat and secure edge node deployment rights in Vietnam and Philippines bandwidth expansion zones. Consolidate modular kitchen configuration specialists to block Infurnia's contractor segment penetration. Defensive patenting around parametric modeling interoperability constrains emerging DWG-independent challengers. For New Entrants and Emerging Players: Enter via Indonesia's secondary city residential contractor segment, where subscription unbundling creates white-space for specialized lighting and material library modules. Target Philippines design studios through localized edge node partnerships with Singapore-based infrastructure providers. Go-to-market leverage rests on METI subsidy eligibility certification to access Japan's mid-market acquisition incentives. For Investors and Strategic Acquirers: Asymmetric upside sits with ISO 27001-certified SaaS vendors positioned for Japan's compliance-filtered procurement consolidation. Long-term viability favors platforms with localized rendering compute in data-sovereignty-certain jurisdictions. Monitor TRAI data localization rulings as inflection signal for India cloud architecture investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's BIM ecosystem anchoring captures multi-disciplinary firm workflows through file format protocols. |
| Geographic Expansion | Localized edge nodes in Vietnam and Philippines exploit bandwidth infrastructure gaps before incumbent cloud deployment. |
| Acquisition of Specialist Firm | Modular kitchen configuration tools address India's residential contractor segment demand absent from generalist platforms. |
| Strategic Partnership | Singapore data center partnerships enable Southeast Asian market access with compliance-predictable hosting. |
| Product Launch | Browser-native WebGL rendering eliminates local GPU dependencies for mid-sized Shanghai and Seoul studios. |
Study Parameters
Bottom-up real estate developer and architecture studio modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core of this study. Primary interviews with CTOs at mid-sized design studios, IT procurement officers at residential developers, platform engineers at browser-native vendors, and integration specialists at BIM consultancies combined with secondary validation against MIIT cloud security classification filings, METI subsidy program disclosures, TRAI consultation papers, and hyperscaler capex reports. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level accuracy.
Historical trendline analysis of software procurement cycles, hardware refresh patterns, and cloud migration trajectories informed projection frameworks across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, solution type, end-user category, and regional regulatory cluster. CAGRs derive from geometric progression of adoption curves weighted against infrastructure maturity indices and compliance timeline probabilities. Browser-native rendering performance benchmarks and data sovereignty ruling schedules constitute industry-specific forecast inputs.
Inputs from MIIT, METI, and TRAI regulatory filings were available through the study window; gaps in pending India data localization enforcement timelines introduce uncertainty bands around cloud deployment forecasts. Practitioners should monitor GPU foundry capacity allocation announcements and cross-border data governance rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Expense Management Software Market
Software & Services
Video Communications Software Market
Software & Services
Dynamic Slotting and Storage Optimization Software Market
Software & Services
Mobile Application Development Platform (MADP) Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Global Funeral Home Software Market
Software & Services
Meditation Software Market
Software & Services
Global Data Governance Software Market
Software & Services
Braking Systems Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Cloud Enterprise Application Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
IT Professional Services Market
Software & Services
Camera Tracking Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Federal Government Software Market