
 Global Performance Analytics Market | 2026-2036
Global Performance Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Performance Analytics Market Foresight
Platform licensing revenue is rewriting profit pools across the analytics value chain. IBM Corporation leverages its Watson portfolio to anchor enterprise-grade AI performance monitoring. SAP SE sustains dominance in ERP-embedded analytics through deep integration with S/4HANA workflows. Microsoft Corporation competes aggressively via Azure Synapse and Power BI bundling within cloud productivity suites.
Performance analytics encompasses the systematic measurement, visualization, and optimization of operational and financial metrics using statistical models, machine learning inference, and real-time data pipelines. The discipline processes structured and unstructured inputs—ranging from IoT sensor streams to transactional ledgers—to generate actionable intelligence for resource allocation and strategic planning. Cloud-based deployment leads absolute spending as enterprises retire on-premises data warehouses, while predictive analytics solutions capture the fastest expansion trajectory due to demand for forward-looking risk and demand forecasts. Edge computing remains nascent but gains traction in manufacturing and telecom latency-sensitive use cases.
The U.S. SEC mandates granular performance disclosures under climate and cybersecurity rules, forcing BFSI end users to upgrade analytics infrastructure for audit readiness. The EU AI Act imposes conformity requirements on automated decision systems, compelling vendors serving European enterprises to embed explainability modules. India's BIS cloud standards and data localization guidelines add compliance layers for multinational deployments. Stakeholders must weigh regulatory divergence against platform standardization when architecting cross-border analytics stacks.
Market Dynamics
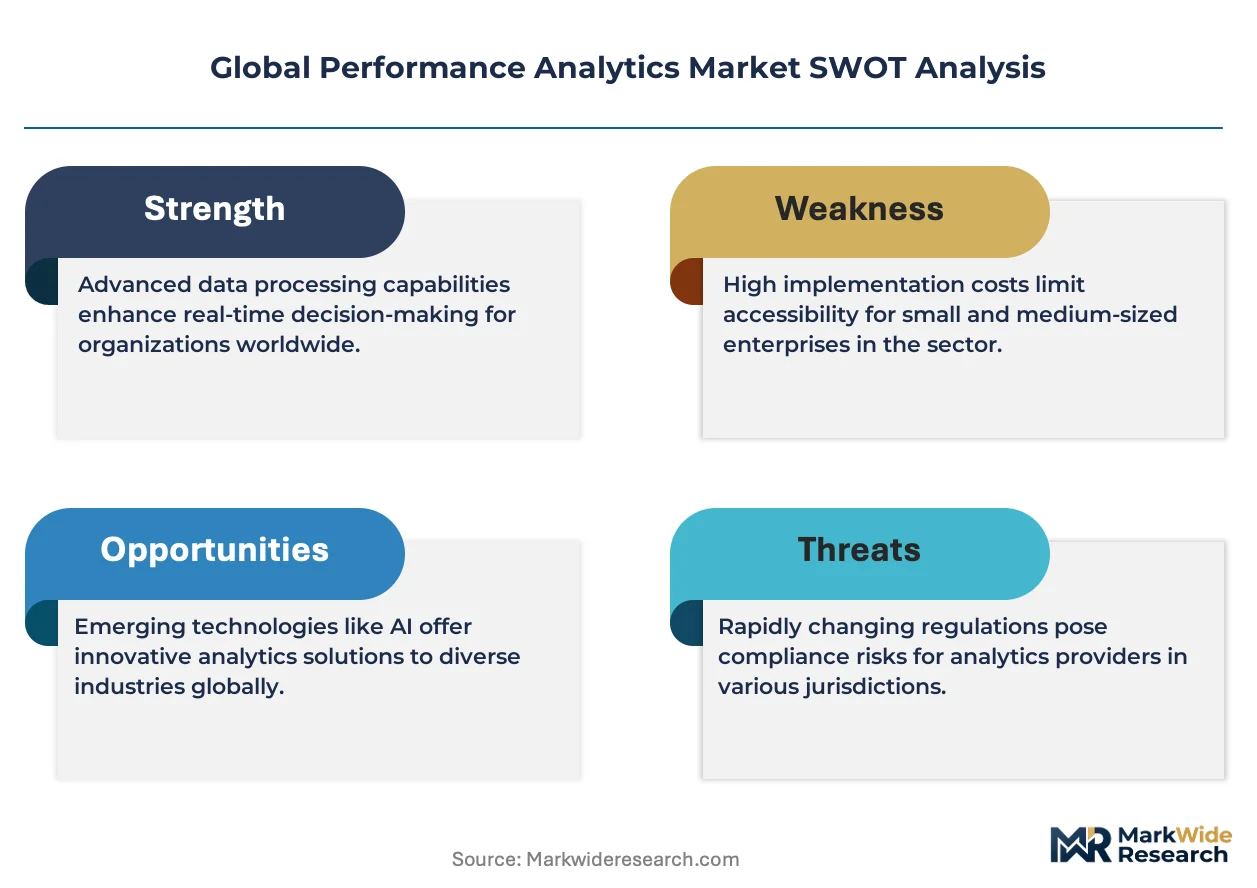
Cloud migration mandates under the EU AI Act and SEC climate disclosure rules are forcing enterprises to retire legacy on-premises data warehouses, creating procurement urgency for real-time analytics infrastructure that satisfies audit-grade explainability requirements.
Growth Catalysts
- SEC Climate Disclosure Rules:Financial services firms in the United States must deploy granular performance dashboards for emissions tracking, accelerating infrastructure modernization cycles.
- ERP-Embedded Analytics:Deep integration with S/4HANA workflows sustains demand for operational intelligence that unifies transactional and analytical processing.
- India:BIS cloud standards and data localization guidelines compel multinational vendors to establish compliant hosting infrastructure, expanding addressable market for domestic deployments.
Market Restraints
- Specialized Talent Scarcity:Machine learning operations and real-time pipeline engineering skills concentrate in Germany, the United States, and India, inflating implementation costs elsewhere.
- EU AI Act Conformity:Automated decision systems require embedded explainability modules, extending development timelines and certification overhead for vendors serving European enterprises.
- On-Premises Inertia:Heavy sunk investments in legacy business intelligence infrastructure delay cloud migration decisions at mid-market manufacturers.
Strategic Opportunities
- Edge Computing Manufacturing:Latency-sensitive IoT sensor analytics in German automotive and Japanese precision equipment plants creates greenfield deployment potential.
- EU Green Deal Alignment:Sustainability-linked reporting requirements generate demand for carbon performance analytics that integrate with existing ERP systems.
- Convergence of AI Inference and Streaming:Unified platforms combining predictive models with real-time data pipelines reduce architectural complexity for BFSI risk monitoring.
Industry Challenges
- Cross-Border Data Architecture:Enterprises must reconcile India's data localization mandates against EU GDPR portability requirements when designing unified analytics stacks.
- Legacy System Integration:Extracting structured and unstructured inputs from decades-old transactional ledgers without disrupting operational continuity demands specialized middleware expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Performance Analytics Market |
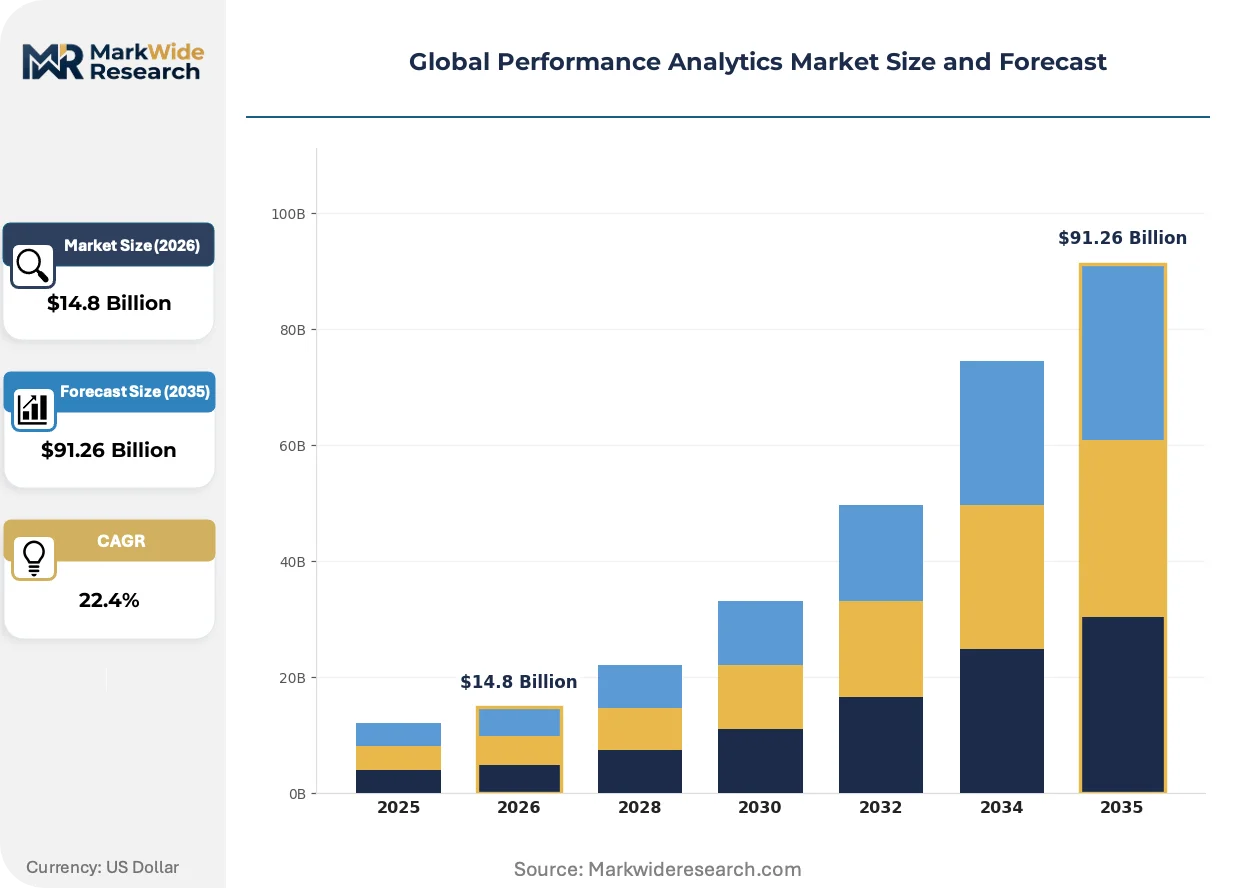
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $91.26 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution/Offering: Data Visualization, Predictive Analytics, Reporting Tools, Benchmarking Software, Optimization Platforms Application: Customer Experience Management, Fraud Detection, Supply Chain Optimization, Workforce Productivity, Risk Management End User: BFSI, Telecom Operators, E-Commerce Firms, Manufacturing Units, Government Agencies |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, SAS Institute Inc., Microsoft Corporation, Siemens AG, ServiceNow Inc., Workday Inc., TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Performance Analytics Market Shifts & Advancements
Performance analytics is undergoing architectural transformation as statistical models embed directly into operational workflows, compressing the latency between data generation and decision execution across manufacturing, financial services, and telecom verticals.
Real-time inference engines are migrating from batch-processed historical reporting toward continuous scoring of streaming IoT and transactional data. Automotive manufacturers in Germany adopt sub-second latency dashboards for predictive maintenance. This compression of analytical cycles is migrating from specialized data science teams toward operational line managers.
The EU AI Act imposes conformity assessment requirements on automated decision systems used in credit scoring and insurance underwriting. Vendors must embed model interpretability and audit trails by design. Financial services firms in Germany and France are prioritizing explainable AI modules in procurement evaluations.
Buyer preference is consolidating around bundled cloud productivity suites rather than standalone analytics licenses. Enterprise procurement teams in the United States negotiate Azure Synapse and Power BI as unified subscriptions. This unbundling of point solutions is most visible among mid-market BFSI institutions modernizing under SEC cybersecurity disclosure pressure.
Global Performance Analytics Market Segmentation
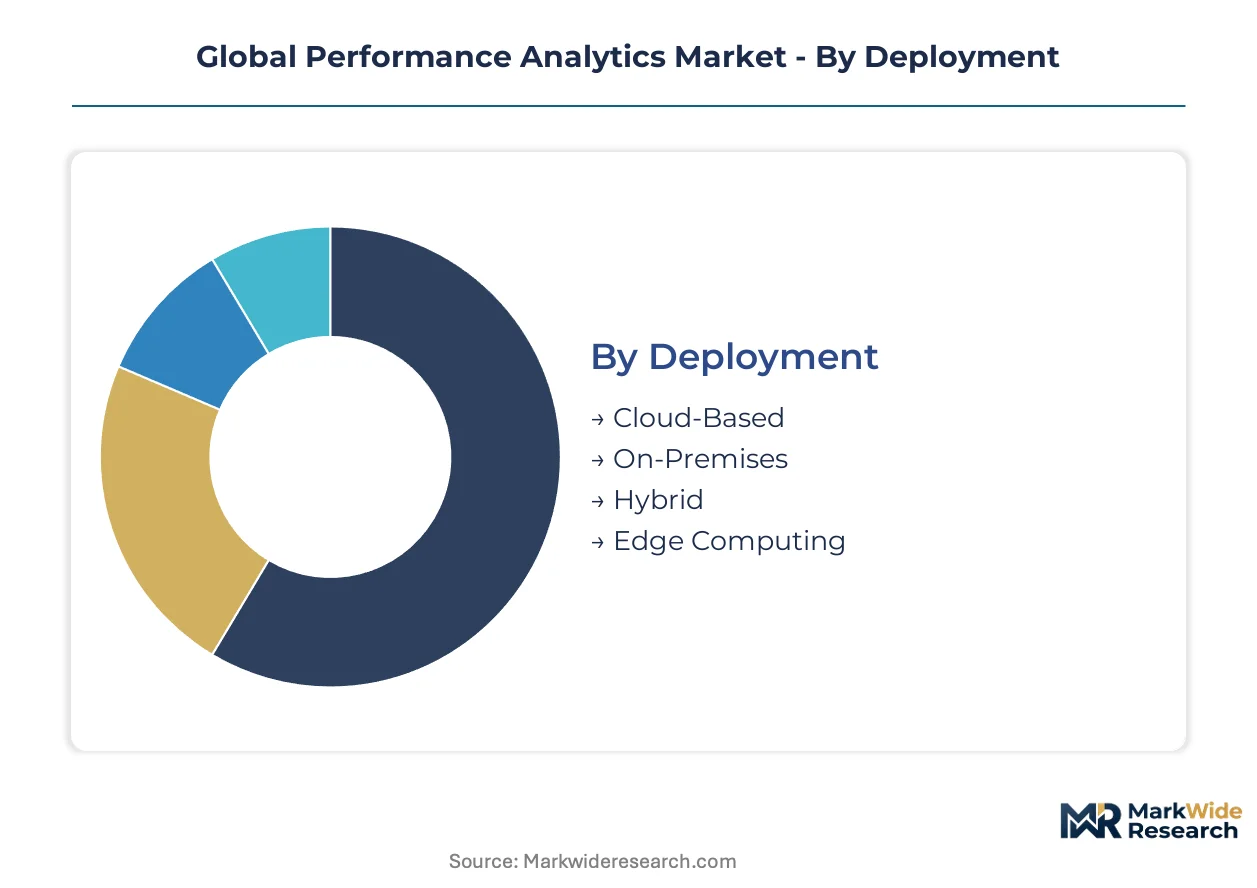
Architectural choices in deployment mode determine integration complexity and recurring revenue durability for analytics vendors. Solution differentiation increasingly hinges on embedded AI capabilities rather than standalone visualization features. Application focus and end-user verticals dictate compliance requirements and sales cycle length across procurement workflows.
Deployment:
After-sales service intensity varies sharply across deployment architectures, with cloud-based implementations demanding continuous infrastructure optimization and edge computing requiring specialized field engineering support.
- Cloud-Based:Multi-tenant SaaS architectures with auto-scaling compute clusters process petabyte-scale streaming data. Financial services firms in the United States and Germany dominate procurement, driven by SEC climate disclosure mandates and EU AI Act conformity deadlines. By volume, Cloud-Based leads. By growth pace, Edge Computing is ahead.
- On-Premises:Dedicated hardware installations within enterprise data centers retain sensitive transactional data under direct custody. Mid-market manufacturers in India and Germany delay migration due to heavy sunk investments in legacy business intelligence infrastructure.
- Hybrid:Split architectures partition sensitive workloads on-premises while bursting analytical processing to public cloud resources. German automotive suppliers favor this model for intellectual property protection alongside computational elasticity.
- Edge Computing:Distributed inference nodes deployed directly on factory floors and telecom base stations enable sub-100ms latency decisioning. Japanese precision equipment plants and German automotive assembly lines drive nascent adoption for predictive maintenance use cases.
Cloud-based deployments capture the majority of new license value, though hybrid configurations retain strategic importance for regulated European enterprises.
Solution/Offering:
Cost tier stratification separates premium predictive platforms from standardized reporting tools, with pricing spreading across three levels based on model sophistication and integration depth.
- Predictive Analytics:Machine learning pipelines generating forward-looking demand forecasts and risk scores from historical pattern recognition. BFSI institutions in the United States and India prioritize procurement under regulatory pressure for proactive risk identification. Predictive Analytics commands premium pricing. Data Visualization scales fastest by unit volume.
- Data Visualization:Interactive dashboard frameworks rendering real-time metric streams through configurable chart libraries. E-commerce firms and government agencies in India deploy widely for operational transparency initiatives.
- Reporting Tools:Scheduled distribution engines delivering standardized performance summaries to stakeholder inboxes. Manufacturing units in Germany utilize these for compliance documentation under EU sustainability frameworks.
- Benchmarking Software:Comparative analytics platforms measuring organizational metrics against peer cohorts and industry standards. Telecom operators in India adopt these for network performance optimization against competitive baselines.
- Optimization Platforms:Prescriptive engines recommending resource allocation adjustments based on multi-variable constraint solving. Supply chain teams at German automotive manufacturers deploy these for inventory and logistics refinement.
Predictive analytics solutions expand most quickly as enterprises shift from descriptive reporting toward anticipatory decision systems.
Application:
Customer maturity levels diverge across application areas, with fraud detection demanding sophisticated in-house data science capabilities while workforce productivity solutions target line-manager self-service adoption.
- Fraud Detection:Real-time transaction scoring systems identifying anomalous patterns indicative of financial crime. BFSI institutions in the United States and Germany anchor demand under regulatory scrutiny from SEC and BaFin.
- Customer Experience Management:Sentiment analysis and journey orchestration tools correlating behavioral signals with satisfaction outcomes. E-commerce firms in India and the United States deploy these for churn reduction and conversion optimization.
- Supply Chain Optimization:Multi-echelon inventory and logistics coordination platforms minimizing fulfillment costs. Manufacturing units in Germany and India implement these for resilience against disruption.
- Workforce Productivity:Activity monitoring and performance feedback systems tracking employee output metrics. Government agencies in India adopt these for civil service accountability programs.
- Risk Management:Integrated frameworks quantifying operational, financial, and cyber risk exposure. BFSI and telecom operators in Germany prioritize these under EU DORA and AI Act requirements.
Risk management applications gain share fastest as regulatory disclosure mandates expand across jurisdictions.
End User:
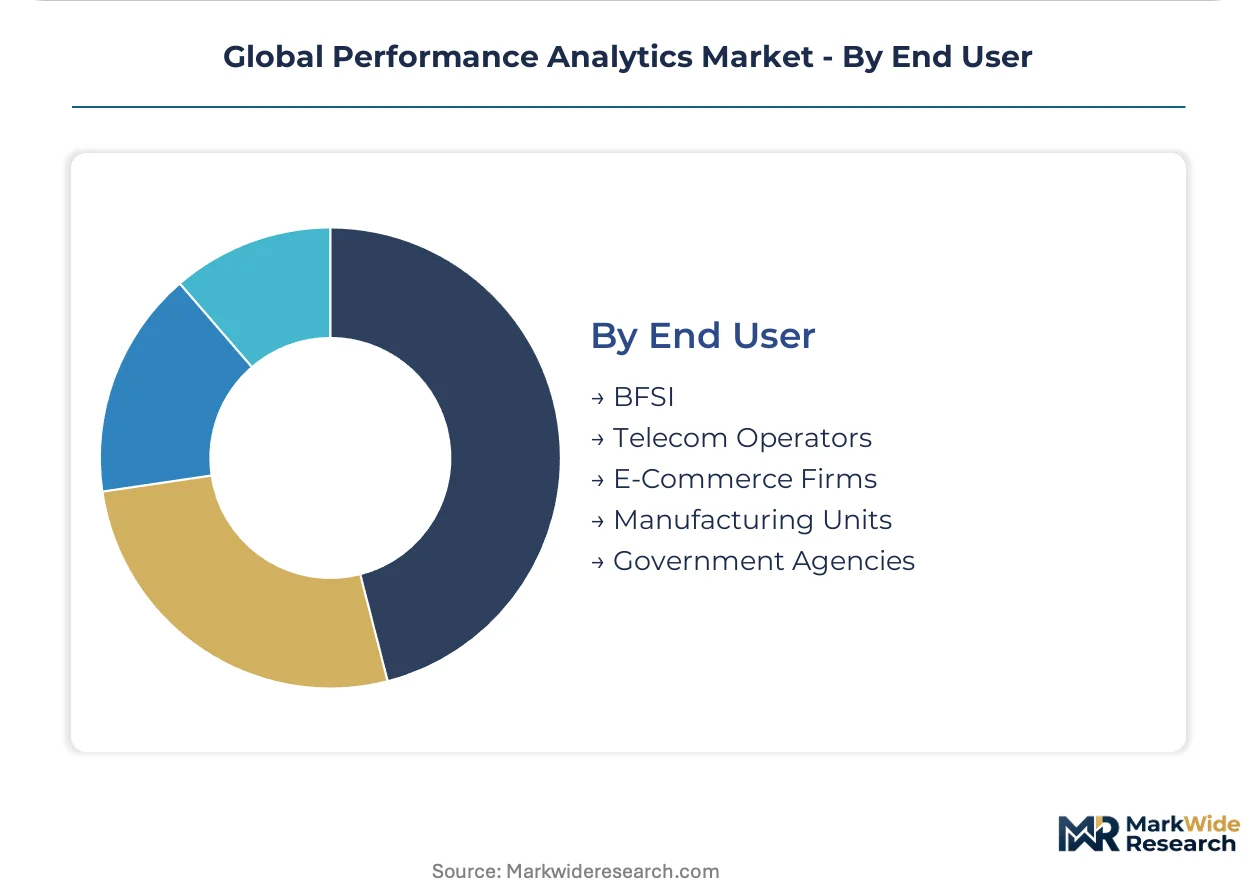
Volume concentration clusters in BFSI and manufacturing, though government procurement cycles in India create distinct tender-driven demand patterns with extended evaluation timelines.
- BFSI:Banks, insurers, and capital markets firms requiring audit-grade analytics for regulatory reporting and trading surveillance. United States and German institutions lead spending under SEC and ECB disclosure frameworks.
- Manufacturing Units:Discrete and process industrial facilities monitoring equipment health and production efficiency. German automotive and Japanese precision engineering plants deploy edge-enabled predictive maintenance.
- Telecom Operators:Network infrastructure managers optimizing spectrum utilization and customer retention. Indian carriers invest heavily under TRAI quality-of-service mandates and competitive 5G rollout pressures.
- E-Commerce Firms:Digital retailers analyzing conversion funnels and inventory turnover. United States and Indian platforms dominate adoption for real-time personalization and logistics coordination.
- Government Agencies:Public sector entities monitoring program outcomes and citizen service delivery. Indian state and central government bodies expand procurement under digital governance initiatives.
BFSI generates the highest revenue per deployment, while manufacturing accounts for the largest installed base by site count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit the highest price elasticity, driving demand for modular SaaS tiers, while German and US enterprises absorb premium pricing for compliance-embedded solutions. Regulatory fragmentation across jurisdictions forces vendors to maintain parallel certification tracks. Cloud infrastructure investments concentrate where data localization mandates intersect with manufacturing density.
United States
SEC climate disclosure rules and cybersecurity mandates compel BFSI institutions to upgrade real-time dashboard infrastructure for audit-grade emissions tracking. Financial services firms in New York and Chicago anchor procurement volumes for predictive risk analytics. The SEC's granular reporting timelines create procurement urgency unmatched in other jurisdictions.
Germany
EU AI Act conformity requirements and BaFin supervisory expectations drive demand for explainable AI modules in automated underwriting systems. Automotive manufacturers in Bavaria deploy edge-enabled predictive maintenance for sub-second latency quality control. Stuttgart and Munich clusters sustain the highest per-enterprise analytics spending in Europe.
India
BIS cloud standards and RBI data localization guidelines force multinational vendors to establish compliant domestic hosting infrastructure. Manufacturing units in Maharashtra and Karnataka modernize legacy ERP systems under PLI scheme incentives. Government agencies in Delhi-NCR expand procurement for civil service productivity monitoring.
Japan
METI's digital transformation subsidies and JIS standards for industrial IoT accelerate edge computing adoption in precision equipment plants. Automotive suppliers in Nagoya and Osaka implement latency-sensitive sensor analytics for predictive quality assurance. Domestic vendors face pricing pressure from bundled cloud suite competitors.
United Kingdom
FCA operational resilience requirements and CSRD alignment pressures drive BFSI infrastructure modernization in London and Edinburgh. Fintech clusters in Manchester and Bristol adopt hybrid deployment models for regulatory data sovereignty. Post-Brexit divergence from EU AI Act creates parallel compliance certification overhead for vendors.
Global Performance Analytics Market Competitive Landscape
Enterprise software conglomerates and specialized analytics pure-plays split the market into distinct competitive spheres with minimal direct overlap. Consolidation pressure intensifies as procurement teams favor bundled cloud productivity suites over standalone licenses. Three archetypes dominate: ERP-embedded analytics providers, hyperscale cloud platform operators, and vertical-specialized performance optimization vendors. M&A activity concentrates on acquiring real-time pipeline engineering talent, while strategic partnerships between hardware OEMs and software vendors accelerate edge computing penetration.
Within the ERP-embedded tier, SAP SE and Oracle Corporation exemplify platform consolidation strategies that unify transactional and analytical processing within single vendor relationships. Microsoft Corporation anchors the hyperscale cloud vector through Azure Synapse and Power BI bundling within enterprise productivity subscriptions. IBM Corporation occupies a position bridging legacy enterprise consulting relationships with Watson portfolio AI performance monitoring capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| SAS Institute Inc. |
| Microsoft Corporation |
| Siemens AG |
| ServiceNow Inc. |
| Workday Inc. |
| TIBCO Software Inc. |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber-optic cable routes linking data centers in California to Singapore and Mumbai transmit the bulk of cloud analytics traffic, with bandwidth cost volatility compressing margins for SaaS vendors while enabling tiered service differentiation between latency-optimized and standard-compute offerings.
Pricing Analysis
Extended service contracts and infrastructure optimization retainers generate the majority of lifetime customer value, shifting vendor focus from upfront licensing toward recurring revenue durability. Three-tier pricing structure across premium, standard, and economy levels stratifies by explainability module depth and audit-grade certification. Pricing pressure stems from bundled cloud productivity suites absorbing standalone analytics budgets. Mid-market manufacturers in India exhibit highest price elasticity, while German automotive enterprises absorb premium tiers for EU AI Act conformity.
Supply Chain Analysis
Supplier-financing facilities and 90-day extended payment terms from hyperscale cloud providers reduce working capital pressure for analytics platform vendors. Compute infrastructure concentrates in the United States, Ireland, and Singapore, with specialized GPU clusters tethered to Taiwan and South Korea semiconductor foundries. The supply chain draws from advanced logic chips, high-bandwidth memory modules, and subsea cable capacity. Single-source vulnerability in AI accelerator silicon poses structural risk. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time pipeline engineering and MLOps expertise concentrates among specialists in Germany, the United States, and India, constraining execution capacity for vendors attempting scaled deployments across regulated jurisdictions.
For Market Incumbents: Build switching-cost moats through deep ERP workflow integration and captive data pipeline infrastructure. Defend against bundled cloud suite displacement by anchoring procurement relationships through compliance-embedded explainability modules. Prioritize certification investment for EU AI Act and SEC disclosure frameworks. For New Entrants and Emerging Players: Pursue edge computing deployments in Japanese precision equipment and German automotive assembly lines as the most penetrable white-space. Target manufacturing units delaying cloud migration due to legacy BI sunk costs. Lead with field engineering partnerships rather than direct sales buildout. For Investors and Strategic Acquirers: Boutique real-time inference engineering shops with automotive or telecom vertical depth represent the most attractive acquisition archetype. Long-term viability hinges on differentiation from hyperscaler bundling rather than feature parity. Watch for consolidation signals when mid-market BFSI procurement teams consolidate vendor relationships under SEC cybersecurity disclosure pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Synapse and Power BI bundling absorbs standalone analytics procurement budgets at US mid-market BFSI institutions. |
| Acquisition of Specialist Firm | Real-time pipeline engineering talent scarcity in Germany and India drives M&A premiums for edge analytics pure-plays. |
| Strategic Partnership | Hardware OEM alliances with software vendors accelerate sub-100ms latency deployments in German automotive plants. |
| Geographic Expansion | Domestic hosting infrastructure in Maharashtra and Karnataka satisfies BIS cloud standards and RBI data localization mandates. |
| Product Launch | Explainable AI modules with embedded audit trails address BaFin supervisory expectations for automated underwriting systems. |
Research Methodology
Initial hypotheses were tested against primary input from chief data officers, MLOps engineers, procurement leads at BFSI institutions, and cloud platform architects and refined through secondary validation against SEC disclosure filings, EU regulatory impact assessments, hyperscaler capex disclosures, and BIS standard documentation. Bottom-up deployment volume estimates and top-down addressable market sizing were triangulated to converge on segment-level outputs.
Demand-supply balance dynamics across cloud infrastructure capacity and enterprise procurement urgency shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include deployment architecture, solution sophistication tier, application use case, and end-user vertical alongside regional regulatory cluster patterns. CAGRs were derived from fitted growth curves calibrated to disclosed vendor booking trends and infrastructure investment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive bundling moves by hyperscale cloud providers or accelerated EU AI Act enforcement timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Pandemic Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Drone Analytics Software Market
Analytics
Global Customer Analytics Market
Analytics
Network Analytics Services Market
Analytics
RAN Analytics and Monitoring Market
Analytics
Mobile Business Intelligence Market
Analytics
Connected Device Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Video Analytics Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Marketing Analytics Market
Analytics
India Contact Center Analytics Market
Analytics
Latin America Location Analytics Market