
 Processed Fruits and Vegetables Market | 2026-2036
Processed Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Fruits and Vegetables Market Analysis
Aseptic carton packaging is repositioning metal cans in ambient vegetable segments, reducing shipping weight and extending shelf life without preservatives. Dole Food Company leverages its plantation-to-retail pipeline to control raw material quality across tropical fruit lines. Del Monte Foods sustains category leadership in canned pineapple through backward integration into Philippine growing operations. Nestlé competes via R&D intensity in quick-frozen vegetable blends for European retail channels.
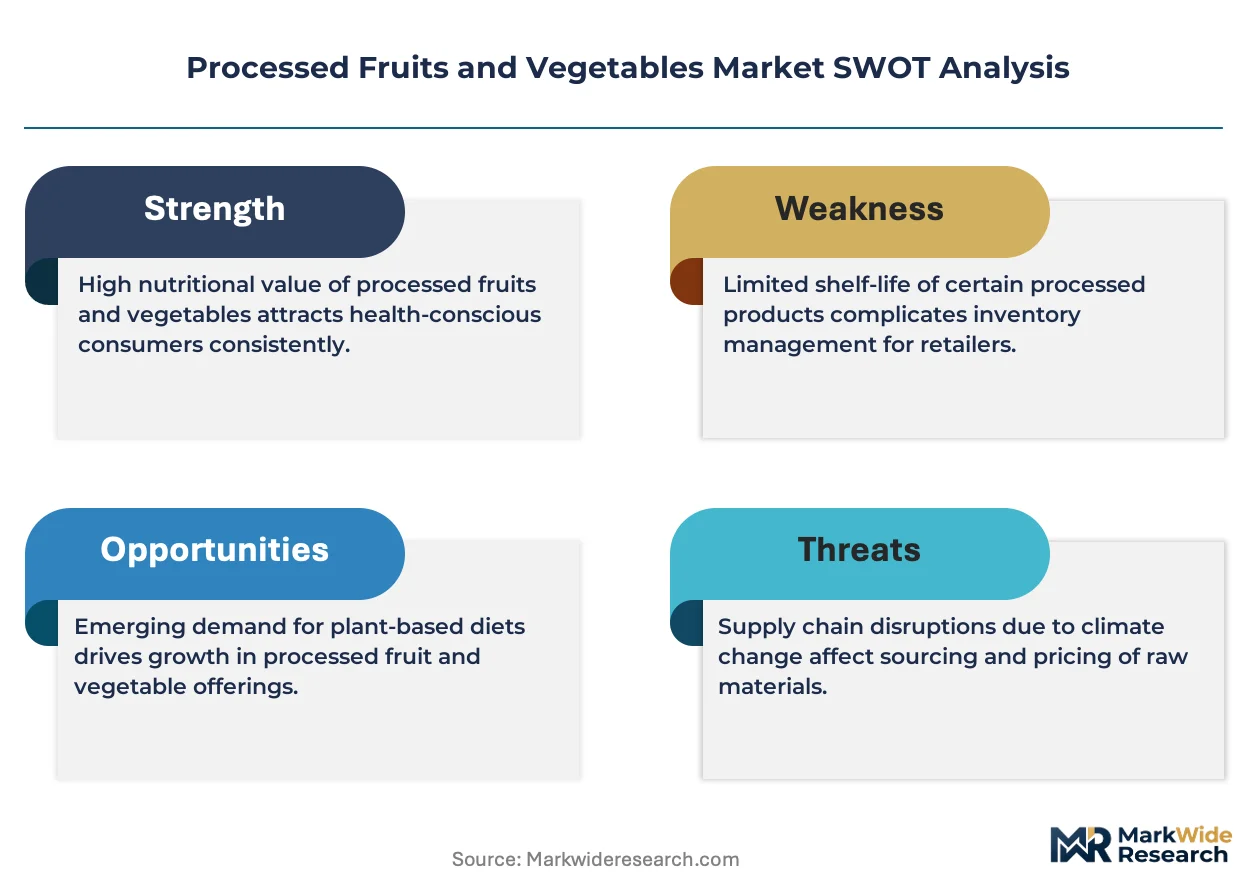
Processed fruits and vegetables encompass raw produce subjected to washing, sorting, blanching, thermal processing, dehydration, freezing, or acidification to achieve microbiological stability, typically with water activity below 0.85 or frozen core temperatures maintained at minus eighteen degrees Celsius for preservation. These products serve industrial food manufacturers, food service distributors, and retail consumers seeking convenience, year-round availability, and reduced perishability. Frozen vegetables command the largest volume position within product type segmentation, reflecting food service reliance on consistent portioning and minimal prep labor. Organic grade lines capture expanding margin pools as certification premiums persist across European and North American retail shelves. Tetra Pack aseptic formats in packaging type segmentation are displacing glass jars in fruit puree applications, driven by logistics efficiency and breakage reduction.
The FDA enforces Hazard Analysis Critical Control Point protocols across U.S. processing facilities, elevating compliance costs for imported canned fruit entrants while reinforcing domestic producer advantages. EFSA pesticide residue benchmarks under EU Regulation 396/2005 directly shape acceptable sourcing regions for frozen vegetable packers supplying European retailers. India's FSSAI packaged food labeling mandates require disclosure of added preservatives and sugar content, redirecting formulation strategies for fruit cup products targeting urban households. Stakeholders must monitor evolving maximum residue limits across jurisdictions to avoid supply exclusion and secure shelf placement in premium retail channels.
Market Dynamics
Aseptic carton packaging is displacing metal cans across ambient vegetable categories, compressing logistics costs while EU Green Deal pesticide thresholds force suppliers to reformulate sourcing networks and redirect procurement toward integrated plantation operations.
Growth Catalysts
- EU Green Deal residue mandates:Tightening MRL thresholds for imported produce push processors toward captive growing operations and certified organic lines, expanding margin pools in premium retail channels.
- Food service frozen vegetable procurement:Commercial kitchens prioritize pre-portioned, blast-frozen formats to minimize prep labor and standardize plate costs across multi-unit operations.
- Urban India's format shift:Indian metropolitan households are transitioning from daily fresh-market purchasing to shelf-stable packaged fruits, opening volume expansion in ambient and chilled segments.
Market Restraints
- Input cost volatility in tropical fruit concentrates:Weather-driven supply swings in pineapple and mango puree concentrates compress processor margins and complicate annual contracting.
- Philippine supply concentration:Canned pineapple processing depends heavily on Mindanao plantation belts, exposing buyers to typhoon disruption and port congestion risks.
- Substitution by fresh produce logistics:Cold-chain infrastructure improvements in emerging markets enable year-round fresh availability, eroding the seasonality advantage of processed alternatives.
Strategic Opportunities
- India's underpenetrated processed fruit cups:FSSAI labeling mandates are redirecting formulation toward clean-label, no-added-sugar products for urban households seeking convenience without preservative disclosure.
- Quick-frozen vegetable blends:European retail channels show unmet demand for ethnic cuisine-specific frozen mixes targeting home-cooking experimentation.
- Aseptic technology convergence:Tetra Pak formats combined with high-pressure processing enable preservative-free ambient stability, opening premium positioning against traditional canning.
Industry Challenges
- HACCP compliance timeline compression:FDA enforcement elevates facility audit frequency and documentation burdens for imported canned fruit entrants unfamiliar with preventive control protocols.
- Refrigerated logistics capex intensity:Frozen vegetable distribution requires fleet investment in minus eighteen degree Celsius transport and warehousing, straining mid-scale packer balance sheets.
- Organic certification lag:Three-year conversion periods for plantation land limit rapid scaling of certified organic lines despite retail price premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Fruits and Vegetables Market |
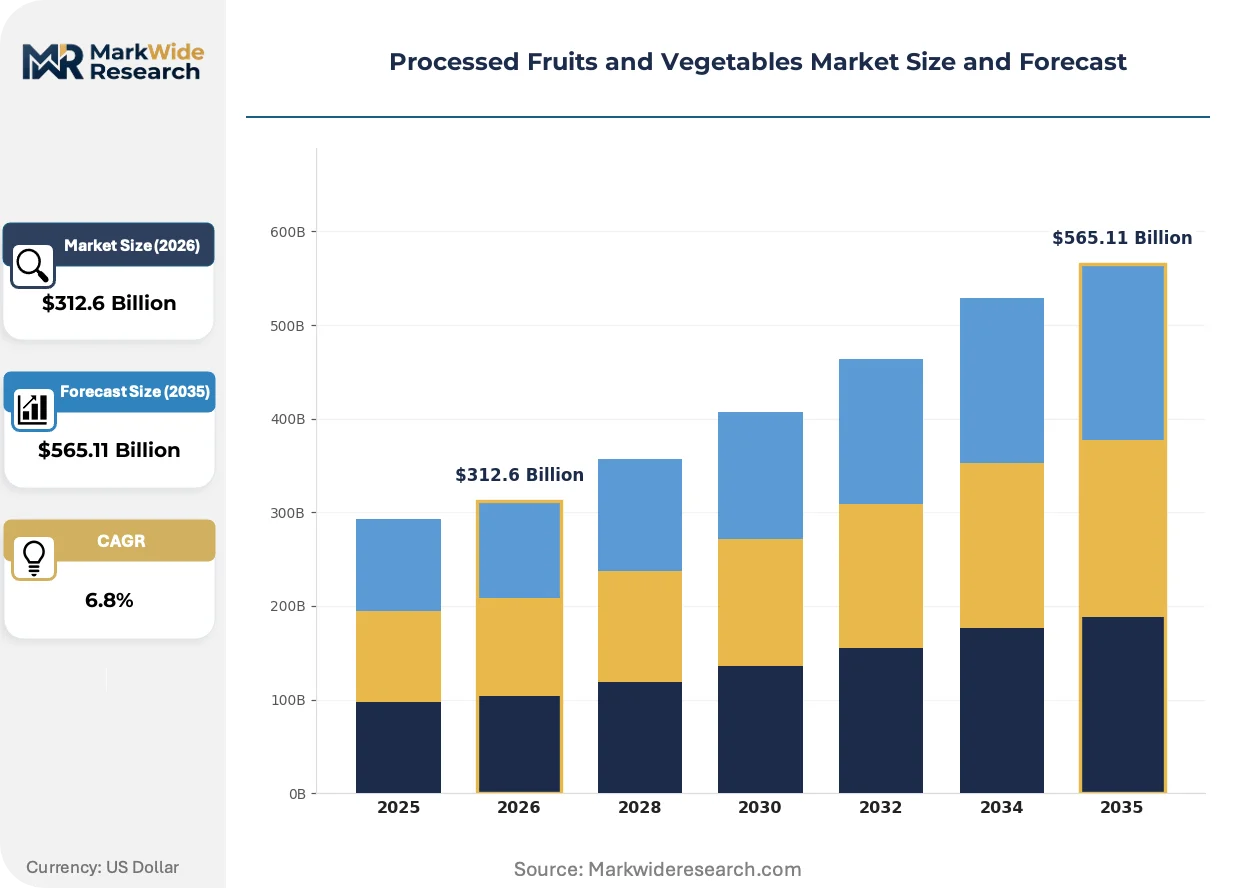
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Fruits, Dried Vegetables, Frozen Vegetables, Pickled Fruits Packaging Type: Glass Jar, Plastic Bag, Tetra Pack, Metal Can End Use: Food Service, Retail, Catering, Household Grade: Organic, Conventional, Non-GMO, Premium |
| Companies Covered | General Mills, Del Monte Foods, Dole Food Company, B&G Foods, Nestlé, Conagra Brands, ADM, Seneca Foods Corporation, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Fruits and Vegetables Market Emerging Trajectories
Processing technology is converging with packaging innovation to eliminate preservatives while extending shelf life, and regulatory pressure is accelerating capital deployment toward integrated supply chain control.
High-pressure processing technology applies isostatic pressure to fruit purees and vegetable juices, destroying pathogens without thermal degradation of vitamins or texture. European retail private-label buyers are adopting this for chilled smoothie and soup lines at accelerating pace. This preservation method is converging with aseptic flexible packaging to enable ambient distribution of previously refrigerated-only products, compressing cold-chain infrastructure requirements.
EFSA pesticide residue benchmarks under EU Regulation 396/2005 are tightening maximum limits for pyrethroids and organophosphates in frozen vegetable imports. Processors serving German and French retail banners must now map field-level application records across their supplier networks. Frozen vegetable packers are responding by backward integration into controlled-environment greenhouse operations in Morocco and Egypt to secure compliant sourcing.
Urban Indian households are abandoning daily fresh-market purchasing rhythms in favor of weekly stock-up trips to modern retail formats. Packaged fruit cups and frozen vegetable mixes are displacing loose produce in Mumbai and Bangalore supermarket baskets. This consumption-pattern shift concentrates demand during weekend promotional windows, forcing processors to align production scheduling with modern-trade replenishment cycles rather than traditional wholesale auction timing.
Processed Fruits and Vegetables Market Segmentation
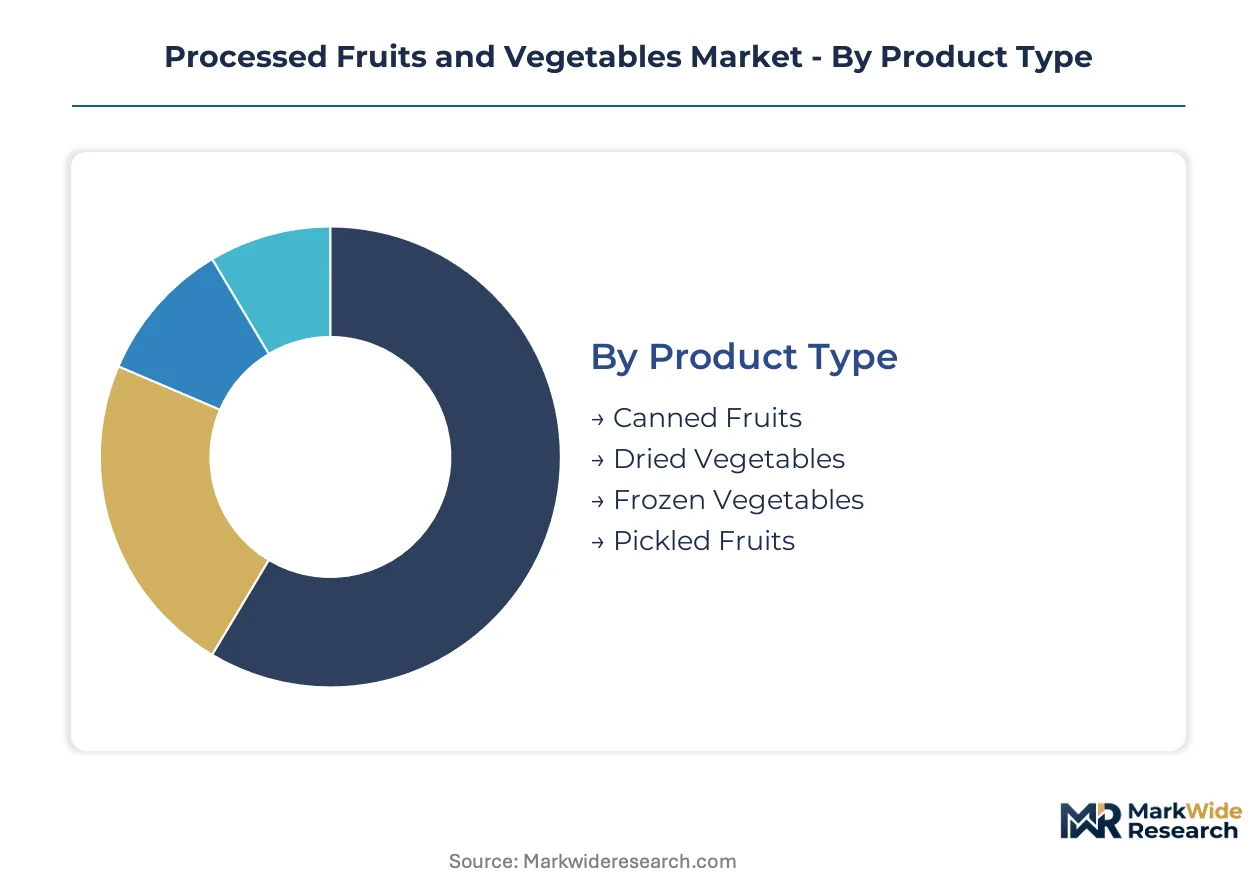
Segmentation in the processed fruits and vegetables market reveals how preservation method, packaging format, and certification grade determine channel access and margin capture. Processors must align product specifications with end-use requirements ranging from food service portion control to retail shelf-life demands.
Product Type:
Standardization dominates high-volume frozen and canned lines, while customization concentrates in dried vegetable blends and pickled fruit formulations targeting ethnic cuisine preferences.
- Frozen Vegetables:Blast-frozen at minus eighteen degrees Celsius to preserve cellular structure and nutrient density. Demand concentrates in European and North American food service channels where kitchen labor reduction drives procurement of pre-portioned formats. Frozen vegetable lines command the largest volume position within product type segmentation.
- Canned Fruits:Thermal processing in syrup or juice medium achieves ambient stability with water activity below 0.85. Philippine and Thai supply belts dominate pineapple and mango sourcing, though typhoon exposure creates procurement volatility for buyers. Canned pineapple sustains category leadership through backward integration into plantation operations.
- Dried Vegetables:Dehydration reduces moisture content to inhibit microbial growth, enabling lightweight logistics for soup and seasoning manufacturers.
- Pickled Fruits:Acidification with vinegar or brine creates shelf-stable formats targeting Eastern European and Asian retail preferences for tangy flavor profiles.
Leading the category by volume: Frozen Vegetables. Expanding most quickly: Dried Vegetables in premium soup ingredient applications.
Packaging Type:
Cost tier stratification separates premium aseptic formats from economy metal cans, with mid-tier plastic and glass occupying private-label and traditional retail channels respectively.
- Tetra Pack:Aseptic carton technology enables preservative-free ambient stability while reducing shipping weight versus metal alternatives. European retail buyers are displacing glass jars in fruit puree applications, driven by logistics efficiency and breakage reduction. Tetra Pack formats combined with high-pressure processing open premium positioning against traditional canning.
- Metal Can:Established infrastructure and lowest unit cost sustain dominance in institutional food service and emergency relief procurement. Metal cans face displacement pressure as EU Green Deal mandates tighten and aseptic alternatives achieve cost parity in vegetable segments.
- Glass Jar:Premium positioning in organic fruit preserves and pickled specialties leverages consumer perception of chemical inertness and reusability.
- Plastic Bag:Flexible packaging dominates frozen vegetable retail formats, offering portion visibility and freezer-space efficiency for household stock-up purchasing.
Volume leadership: Metal Can. Steepest expansion trajectory: Tetra Pack in ambient vegetable segments.
End Use:
Customer type determines specification rigor, with food service demanding consistency certificates and retail requiring extended shelf-life declarations and clean-label positioning.
- Food Service:Commercial kitchens prioritize blast-frozen vegetable formats with standardized plate costs and minimal prep labor. Multi-unit operators in India and the United States are expanding procurement of frozen lines to streamline kitchen operations and reduce skill-dependent processing steps.
- Retail:Supermarket banners require shelf-stable formats aligned with weekly stock-up purchasing patterns, particularly in urban Indian households transitioning from daily fresh-market visits. FSSAI labeling mandates redirect formulation toward no-added-sugar fruit cup products.
- Catering:Event and institutional feeding demands bulk formats with extended hold times and minimal temperature sensitivity.
- Household:Direct-to-consumer channels emphasize convenience packaging sizes and recipe-ready vegetable blends for time-constrained meal preparation.
Leading the category by volume: Food Service. Gaining share fastest: Retail in Indian metropolitan markets.
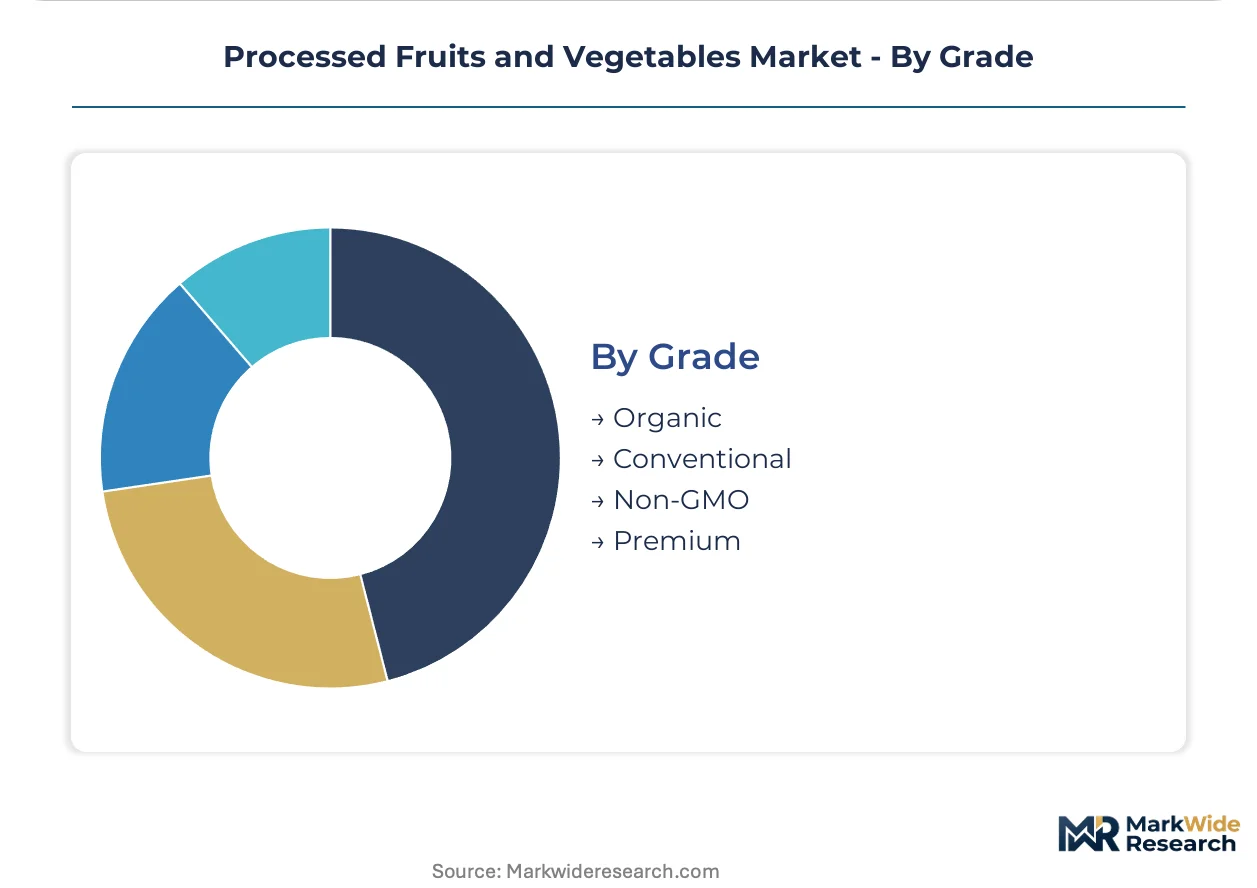
Grade:
Margin concentration follows certification intensity, with organic and premium grades capturing price multiples despite supply constraints from three-year land conversion requirements.
- Organic:Certification prohibits synthetic pesticide and fertilizer use, requiring plantation-level traceability documentation for EU Regulation 396/2005 compliance. European and North American retail shelves sustain expanding margin pools as organic price premiums persist despite supply scarcity.
- Conventional:Standard agricultural inputs and established supply chains enable volume scale and lowest unit cost for price-sensitive institutional channels.
- Non-GMO:Identity preservation from seed to shelf addresses North American consumer preferences and retailer non-GMO verification programs.
- Premium:Grade designation typically combines variety specificity, origin labeling, and superior sensory attributes for specialty retail positioning.
Volume leadership: Conventional. Climbing the fastest: Organic despite three-year conversion period constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for processed fruits and vegetables concentrates in India, where urban households are abandoning daily fresh-market purchasing for weekly stock-up trips to modern retail formats. This shift concentrates volume expansion in ambient and chilled segments across metropolitan clusters. Regulatory tightening in the European Union and supply chain investments in North America complete the triad of regional drivers.
United States
Food service operators drive frozen vegetable procurement to streamline kitchen operations and reduce labor-dependent prep steps. FDA enforcement of Hazard Analysis Critical Control Point protocols elevates compliance costs for imported canned fruit entrants while reinforcing domestic processor advantages. Processing facilities concentrate in California's Central Valley and the Midwest corn belt, where tomato and sweet corn canning infrastructure maintains century-old operational density.
Germany
Retail banners demand extended shelf-life declarations and clean-label positioning for frozen vegetable blends targeting home-cooking experimentation. EFSA pesticide residue benchmarks under EU Regulation 396/2005 directly shape acceptable sourcing regions for packers supplying German supermarkets. The Lower Saxony region hosts concentrated quick-freezing capacity serving both domestic retail and export channels into neighboring Benelux markets.
India
Mumbai and Bangalore metropolitan households are transitioning from loose produce to packaged fruit cups and frozen vegetable mixes in modern-trade baskets. FSSAI packaged food labeling mandates require disclosure of added preservatives and sugar content, redirecting formulation strategies toward clean-label products. Processing clusters in Maharashtra and Gujarat are expanding aseptic packaging lines to capture urban demand concentrated during weekend promotional windows.
Philippines
Mindanao plantation belts supply the global canned pineapple trade through backward-integrated operations controlling raw material quality from field to can. Typhoon exposure and port congestion risks concentrate procurement volatility for buyers dependent on this geography. Davao-based processing infrastructure maintains thermal processing capacity that serves both North American retail and Asian food service channels.
France
Supermarket private-label buyers adopt high-pressure processing technology for chilled smoothie and soup lines at accelerating pace. EU Green Deal residue mandates push processors toward certified organic lines and captive growing operations to secure shelf placement in premium retail channels. The Provence-Alpes-Côte d'Azur region hosts specialized fruit puree operations leveraging aseptic flexible packaging for ambient distribution.
Processed Fruits and Vegetables Market Vendor Landscape
Backward integration into plantation operations dominates the current landscape as processors seek supply security amid tightening residue thresholds. The market structure tiers across multinational conglomerates with integrated supply chains, mid-scale regional packers serving private-label contracts, and specialized organic operators constrained by three-year land conversion requirements. Strategic archetypes include plantation-integrated tropical fruit processors, quick-freezing specialists targeting food service channels, and aseptic technology adopters repositioning against metal can incumbents. M&A activity and capacity expansion in controlled-environment greenhouse operations represent the dominant competitive moves.
Among plantation-integrated operators, Dole Food Company and Del Monte Foods exemplify the captive supply archetype, leveraging field-level control to manage raw material quality and residue compliance. Nestlé occupies a position within the R&D-intensive frozen vegetable tier, competing through formulation innovation for European retail channels. These three entities represent contrasting strategic postures: tropical fruit vertical integration versus temperate vegetable quick-freezing specialization versus multinational portfolio diversification.
| Leading Market Players |
|---|
| General Mills |
| Del Monte Foods |
| Dole Food Company |
| B&G Foods |
| Nestlé |
| Conagra Brands |
| ADM |
| Seneca Foods Corporation |
| The Kraft Heinz Company |
| Others |
Supply Flow & Price Mechanics
Family-owned plantation operators in Mindanao and Central Thailand anchor tropical fruit processing, their concentrated ownership patterns enabling disciplined contracting that resists spot-market volatility while preserving margin pools for integrated canners.
Pricing Analysis
Volume leadership in metal-canned pineapple and mango concentrates runs on thin margins anchored to commodity spot indices, while aseptic carton and frozen premium lines capture pricing multiples through certification premiums and clean-label positioning. Price differentiation centers on organic grade status and EU Regulation 396/2005 compliance tier, with residue-tested lots commanding shelf-access premiums in German and French retail. Pricing pressure stems from weather-driven input volatility in Philippine pineapple belts, compressing processor margins during typhoon seasons. Institutional food service channels exhibit highest price sensitivity, while European retail private-label buyers prioritize specification consistency over unit cost.
Supply Chain Analysis
Seasonal labor availability in Maharashtra and Gujarat processing corridors constrains aseptic packaging line throughput during peak mango and tomato harvest windows. Raw material sourcing draws from Mindanao pineapple plantations, Moroccan greenhouse vegetable operations, and Egyptian frozen pea cultivation belts. Single-source vulnerability concentrates in Philippine canned fruit infrastructure exposed to typhoon disruption and port congestion. Distribution runs through cold-chain networks maintaining minus eighteen degree Celsius integrity for frozen vegetable lines, with ambient cannery products leveraging conventional trucking to food service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The processed fruits and vegetables sector sits in a packaging-transition phase, with aseptic carton and high-pressure processing technologies displacing legacy metal can formats across ambient vegetable and fruit puree segments.
For Market Incumbents: Cement supply security through backward integration into controlled-environment greenhouse operations in Morocco and Egypt, securing EFSA-compliant sourcing as EU Green Deal residue thresholds tighten. Expand aseptic packaging capacity in Indian processing clusters to capture urban household format shifts from fresh-market purchasing. Prioritize HACCP documentation infrastructure to defend against FDA enforcement elevating compliance barriers for imported canned fruit entrants.
For New Entrants and Emerging Players: The mid-tier price gap between premium organic lines and economy conventional cans opens white-space targeting in India's underpenetrated processed fruit cup segment, where FSSAI labeling mandates redirect formulation toward no-added-sugar clean-label products. Target ethnic cuisine-specific frozen vegetable blends for European retail channels showing unmet demand for home-cooking experimentation. Pursue private-label manufacturing contracts with German and French supermarket banners seeking residue-compliant sourcing alternatives.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale aseptic technology adopters in Indian and Southeast Asian geographies where capital constraints limit independent scaling. Long-term viability hinges on five-to-ten year positioning around preservative-free ambient stability convergence. Monitor EU maximum residue limit revision schedules as inflection indicators for supply exclusion risk and premium channel access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Greenhouse Operations | Secures EFSA-compliant vegetable sourcing for EU retail access amid tightening residue mandates. |
| Aseptic Packaging Line Expansion | Captures urban Indian demand shifting from fresh markets to shelf-stable packaged formats. |
| High-Pressure Processing Adoption | Enables preservative-free ambient distribution previously requiring refrigerated cold chains. |
| Organic Certification Investment | Unlocks premium price multiples despite three-year land conversion supply constraints. |
| Private-Label Manufacturing Partnerships | Provides volume anchor for mid-scale processors serving German and French retail banners. |
Methodological Framework
Document review covered FDA warning letters, EFSA scientific opinions on pesticide residues, FSSAI packaged food notifications, and trade customs data, complemented by interviews with frozen vegetable procurement directors at multi-unit food service operators, aseptic packaging line engineers, plantation agronomists in Mindanao, and category buyers at German retail banners. Secondary sources included EU Regulation 396/2005 amendments, industry association processing statistics, and company facility registration filings. Bottom-up volume modeling triangulated against top-down demand aggregation across preservation method, packaging format, and grade segmentation.
Cross-referencing historical volume trajectories against panel input from supply chain stakeholders informed the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, packaging technology, end-use channel, and certification grade tier. CAGRs derived from curve-fitting approaches applied to shipment data and capacity expansion announcements. Forecast inputs incorporated EU Green Deal implementation pacing, Indian cold-chain infrastructure buildout rates, and Philippine typhoon frequency patterns.
Inputs from plantation operators and retail procurement managers were available through the study window; gaps in real-time residue testing data and private-label contract terms introduce uncertainty bands around premium tier volume assumptions. Forecasts reflect documented regulatory trajectories and technology adoption curves. Material deviation in EU MRL enforcement intensity, Indian modern-trade expansion pacing, or aseptic packaging cost parity achievement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Frozen Vegetables Market