
 True Wireless Stereo Earbuds Market | 2026-2036
True Wireless Stereo Earbuds Market Size, Share, and Industry Trends Forecast 2026-2036
True Wireless Stereo Earbuds Market Intelligence
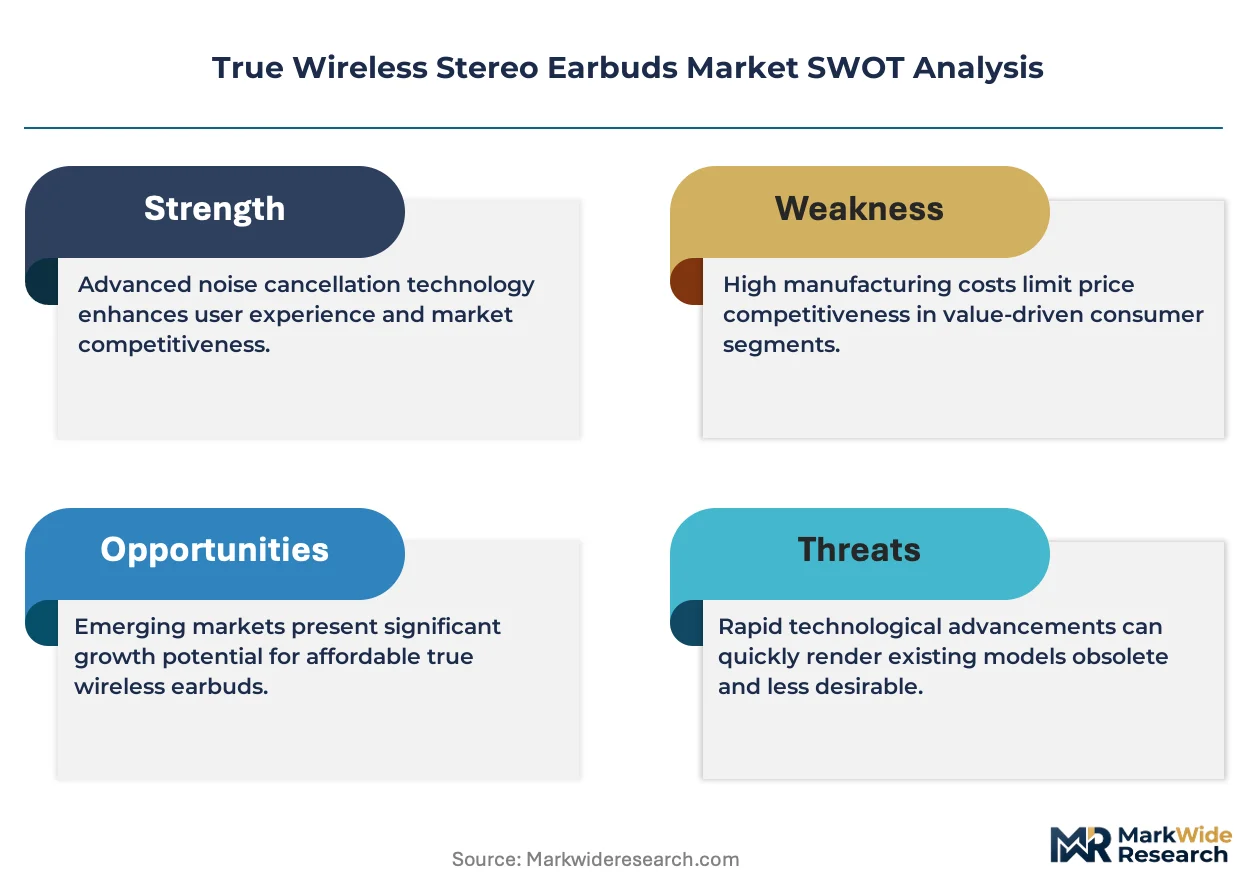
The premium-commodity split in true wireless stereo earbuds is repositioning around active noise cancellation fidelity and codec support rather than basic Bluetooth connectivity alone. Apple leverages its H-series chip architecture and ecosystem lock-in to sustain pricing power at the top tier. Xiaomi competes through manufacturing scale and channel control that anchors its dominance in emerging markets. Sony differentiates via LDAC codec leadership and audiophile-grade tuning that occupies a distinct premium niche.
True wireless stereo earbuds are compact audio devices housing independent left and right drivers with integrated batteries, Bluetooth SoCs, and MEMS microphones, manufactured through precision injection molding and surface-mount assembly for sub-5 gram per-unit weights. Their primary commercial purpose is to deliver untethered stereo audio for mobile communication, entertainment, and voice assistant interaction. In-ear form factors lead volume shipments due to portability and passive isolation, while noise-cancelling variants command the deepest margin pools as component costs for feedforward microphones and DSP algorithms remain elevated. Bluetooth connectivity dominates the protocol landscape, though USB-C charging interfaces are displacing proprietary pogo-pin solutions as standardization reduces SKU complexity for brands.
The FCC governs radio frequency emissions and Specific Absorption Rate limits for devices sold in the United States, while the EU Radio Equipment Directive mandates interoperability and safety testing for CE-marked products across European markets. China's MIIT enforces SRRC certification that shapes which Bluetooth modules and antenna designs gain market access. Stakeholders must monitor evolving battery transportation regulations and right-to-repair mandates that could force modular designs and impact cost structures.
Market Dynamics
Bluetooth Low Energy Audio technology is compressing power consumption benchmarks while fragmenting codec ecosystems, forcing manufacturers to choose between interoperability breadth and proprietary optimization depth.
Growth Catalysts
- LE Audio protocol stack:The new broadcast audio capability enables Auracast deployments in public venues, creating institutional demand channels beyond consumer retail. Fitness centers and transit authorities are piloting assisted listening applications.
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting assembly capacity to Gujarat and Tamil Nadu, reducing landed costs for brands serving price-sensitive South Asian consumers.
- MEMS microphone integration:Advanced silicon microphones with integrated DSP cores are enabling feedforward ANC in mid-tier price bands, expanding the addressable market for noise cancellation.
Market Restraints
- Lithium-ion cell volatility:Cobalt and lithium carbonate price swings compress margin predictability for battery-dependent form factors, particularly affecting sub-$50 retail tiers where component cost ratios are highest.
- FCC SAR testing timelines:Specific Absorption Rate certification for new antenna configurations adds 8-14 weeks to product launch cycles, constraining rapid iteration strategies.
- Wired earphone substitution persistence:USB-C and 3.5mm alternatives retain preference among latency-sensitive mobile gamers and professional audio monitoring applications.
Strategic Opportunities
- Hearing health integration:FDA OTC hearing aid regulations are enabling software-defined amplification features that blur boundaries between consumer audio and medical device categories.
- India tier-2 urbanization:Smaller cities like Indore, Kochi, and Lucknow are outpacing metro smartphone penetration growth, creating whitespace for localized distribution partnerships.
- LE Audio + Auracast convergence:Broadcast audio and hearing accessibility standards are merging, opening institutional procurement channels in education and hospitality verticals.
Industry Challenges
- RF engineering talent scarcity:Antenna design and Bluetooth coexistence optimization require specialized expertise concentrated among semiconductor vendors, limiting in-house capability building for emerging brands.
- Right-to-repair compliance complexity:EU battery regulations mandating user-replaceable cells conflict with IPX waterproofing requirements, forcing industrial design compromises.
- Codec licensing fragmentation:Qualcomm aptX, Sony LDAC, and Samsung SSC proprietary stacks create royalty stacking and interoperability testing burdens for multi-platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | True Wireless Stereo Earbuds Market |
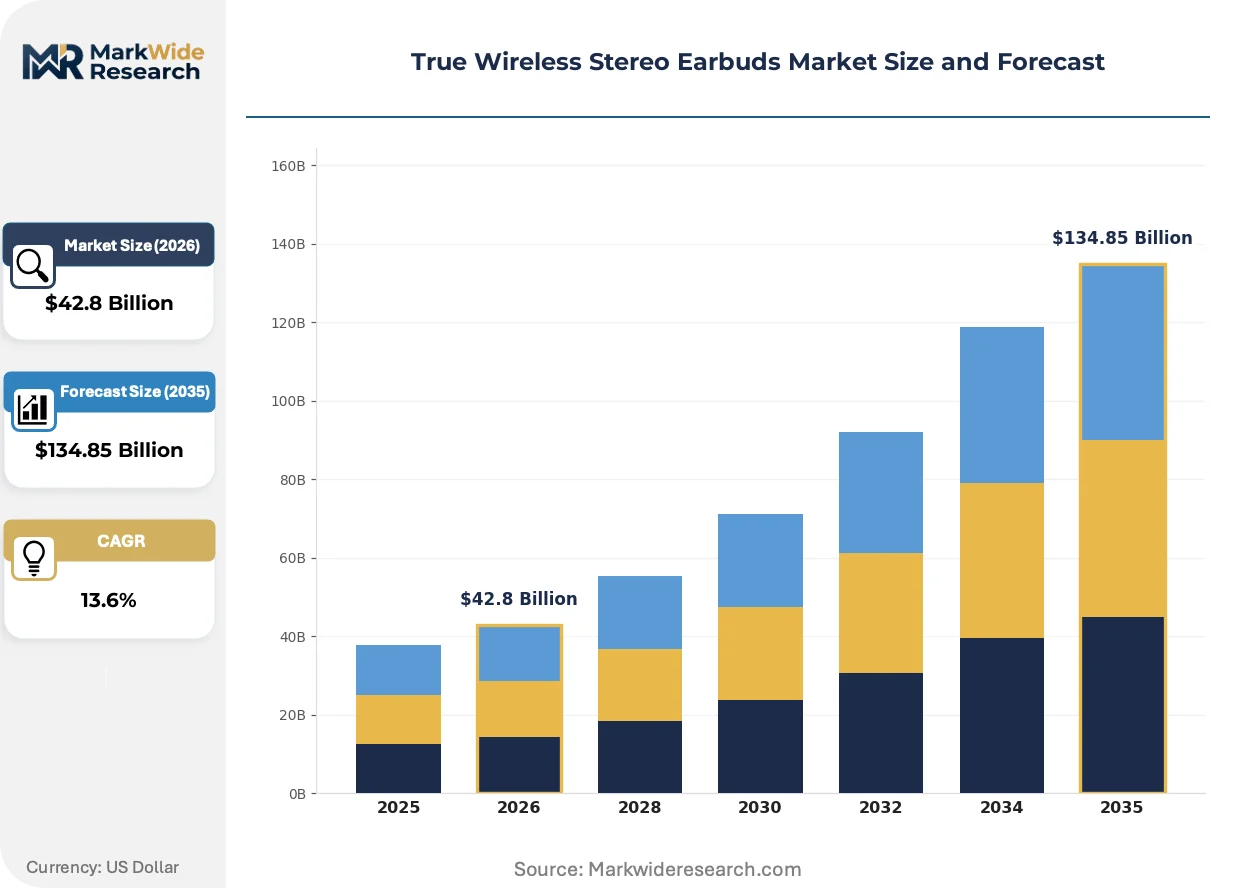
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, On-Ear, Over-Ear, Noise Cancelling Connectivity: Bluetooth, NFC, Wired, USB-C End User: Audio Enthusiasts, Casual Users, Fitness Lovers, Gamers Feature: Water Resistance, Voice Assistance, Touch Control, Battery Life |
| Companies Covered | Apple, Samsung Electronics, Sony Corporation, Bose Corporation, Jabra, Xiaomi Corporation, Sennheiser Electronic, Skullcandy, Anker Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
True Wireless Stereo Earbuds Market Strategic Shifts & Innovations
Codec sovereignty battles and broadcast audio standardization are reconfiguring competitive moats around intellectual property rather than manufacturing scale alone.
Auracast broadcast audio is electrifying accessibility infrastructure deployment. The technology enables direct-to-ear streaming in theaters, airports, and places of worship without intermediary hardware. Hearing aid manufacturers and cochlear implant developers are adopting LE Audio receivers at accelerated cadences. This convergence is compressing the traditional assistive listening device market while expanding total addressable volume for consumer earbud vendors.
EU battery regulations under the Ecodesign for Sustainable Products Framework are mandating replaceable cell architectures and standardized charging interfaces. Manufacturers must redesign internal layouts to accommodate user-accessible battery compartments without compromising acoustic chamber volumes. Premium noise-cancelling variants face the steepest engineering trade-offs given their space-constrained designs.
Enterprise procurement of TWS devices for hybrid workforces is displacing individual consumer purchasing in North American and Western European corporate technology budgets. IT departments are standardizing on single-vendor fleets with centralized device management, unbundling retail packaging and warranty terms. This shift is most visible in financial services and professional services verticals where video conferencing quality directly affects client-facing operations.
True Wireless Stereo Earbuds Market Segmentation
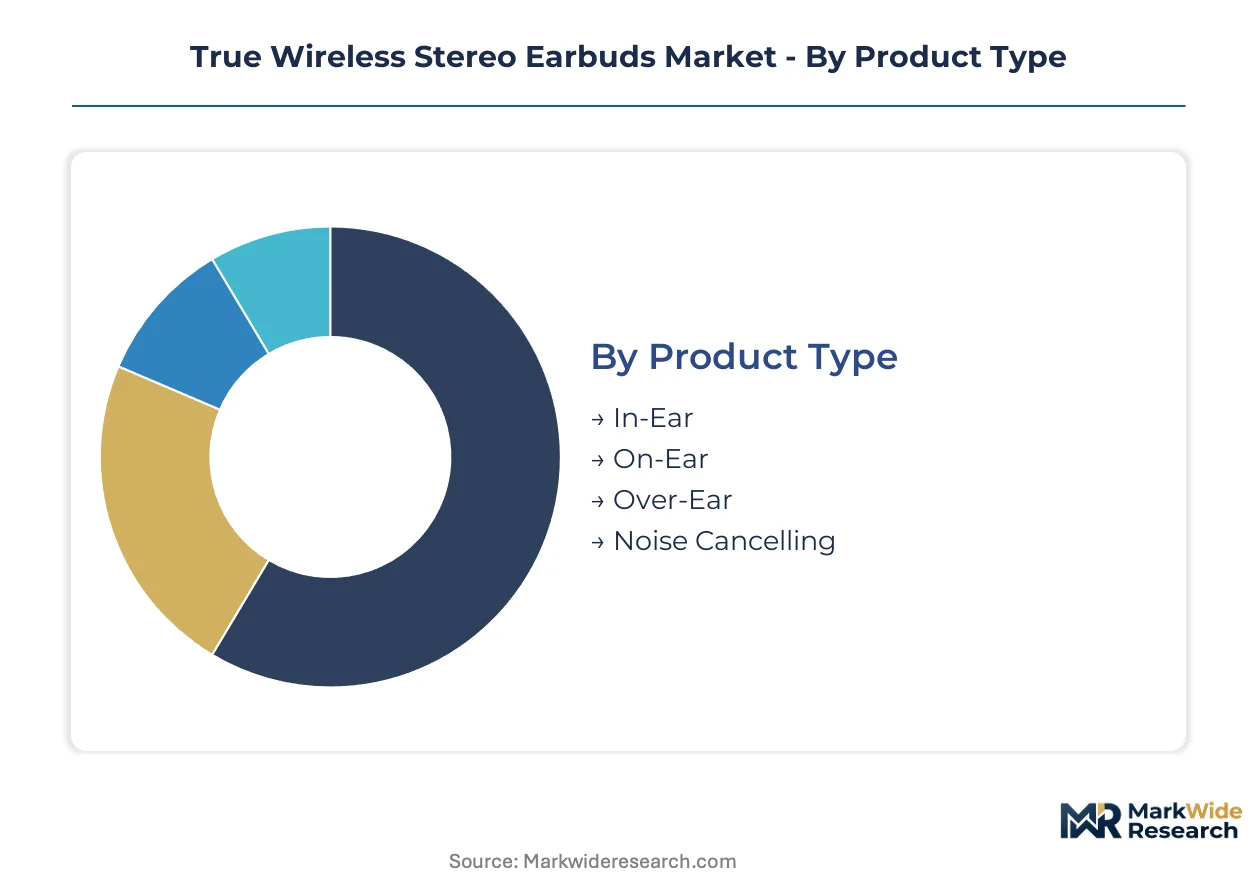
True wireless stereo earbuds fragment across form factor, protocol, user behavior, and functional specification axes. Each segmentation dimension carries distinct margin profiles and supply chain requirements that reshape vendor positioning strategies.
Product Type:
Form factor engineering determines acoustic chamber geometry, driver selection, and passive isolation performance.
- In-Ear:Compact housings with 6mm-11mm dynamic drivers or balanced armature arrays seal directly within the ear canal. Demand concentrates among smartphone ecosystem users in India and China where portability dominates purchase criteria alongside aggressive sub-$50 retail pricing.
- Noise Cancelling:Hybrid feedforward-feedback architectures integrate multiple MEMS microphones with dedicated DSP cores for adaptive ambient suppression. Corporate procurement in United States financial services verticals drives institutional volume as IT departments standardize on ANC-equipped fleets for open-office productivity.
- On-Ear:Supra-aural designs with 30mm-40mm drivers trade isolation for situational awareness. Urban commuters in European cycling corridors favor this balance of audio immersion and environmental monitoring.
- Over-Ear:Circumaural enclosures accommodate larger 40mm-50mm beryllium or biocellulose drivers with extended battery capacities. Audiophile-grade tuning targets LDAC codec users seeking uncompressed wireless transmission.
In-Ear leads on scale; Noise Cancelling leads on momentum.
Connectivity:
Protocol selection shapes interoperability breadth, latency performance, and royalty cost structures for bill-of-materials optimization.
- Bluetooth:Dominant protocol stack spanning Classic Audio and Low Energy Audio specifications with SBC, AAC, aptX, and LDAC codec support. Smartphone ecosystem penetration in China and India anchors volume concentration as OEM bundled sales displace standalone retail.
- USB-C:Digital audio transmission via USB Audio Class protocols enables lossless playback and charging convergence. Gaming peripheral manufacturers leverage this for latency-sensitive tournament applications.
- NFC:Tap-to-pair functionality accelerates device association for accessibility-focused user segments. Hearing aid companion apps integrate NFC for simplified pairing workflows.
- Wired:3.5mm and USB-C passive connections persist among professional audio monitoring and latency-critical mobile gaming niches where wireless protocol overhead introduces unacceptable delay.
Bluetooth leads on scale; USB-C leads on momentum.
End User:
Usage context determines durability requirements, acoustic tuning priorities, and feature weighting in product development roadmaps.
- Casual Users:Generalist listeners prioritizing smartphone ecosystem compatibility and voice assistant integration over audiophile specifications. Mass-market retail channels in India tier-2 cities like Indore and Lucknow drive expansion as smartphone penetration deepens.
- Fitness Lovers:Sweat-resistant IPX4+ rated designs with secure fit mechanisms and heart rate sensor integration. Gym chain partnerships and marathon event sponsorships accelerate category visibility.
- Audio Enthusiasts:Codec-sensitive buyers demanding LDAC, aptX Adaptive, or lossless wireless transmission with customizable EQ profiles. Premium tier pricing sustains elevated margin pools despite lower shipment volumes.
- Gamers:Sub-60ms latency requirements drive proprietary 2.4GHz dongle adoption alongside Bluetooth dual-mode operation. Esports tournament standards influence feature prioritization.
Casual Users leads on scale; Fitness Lovers leads on momentum.
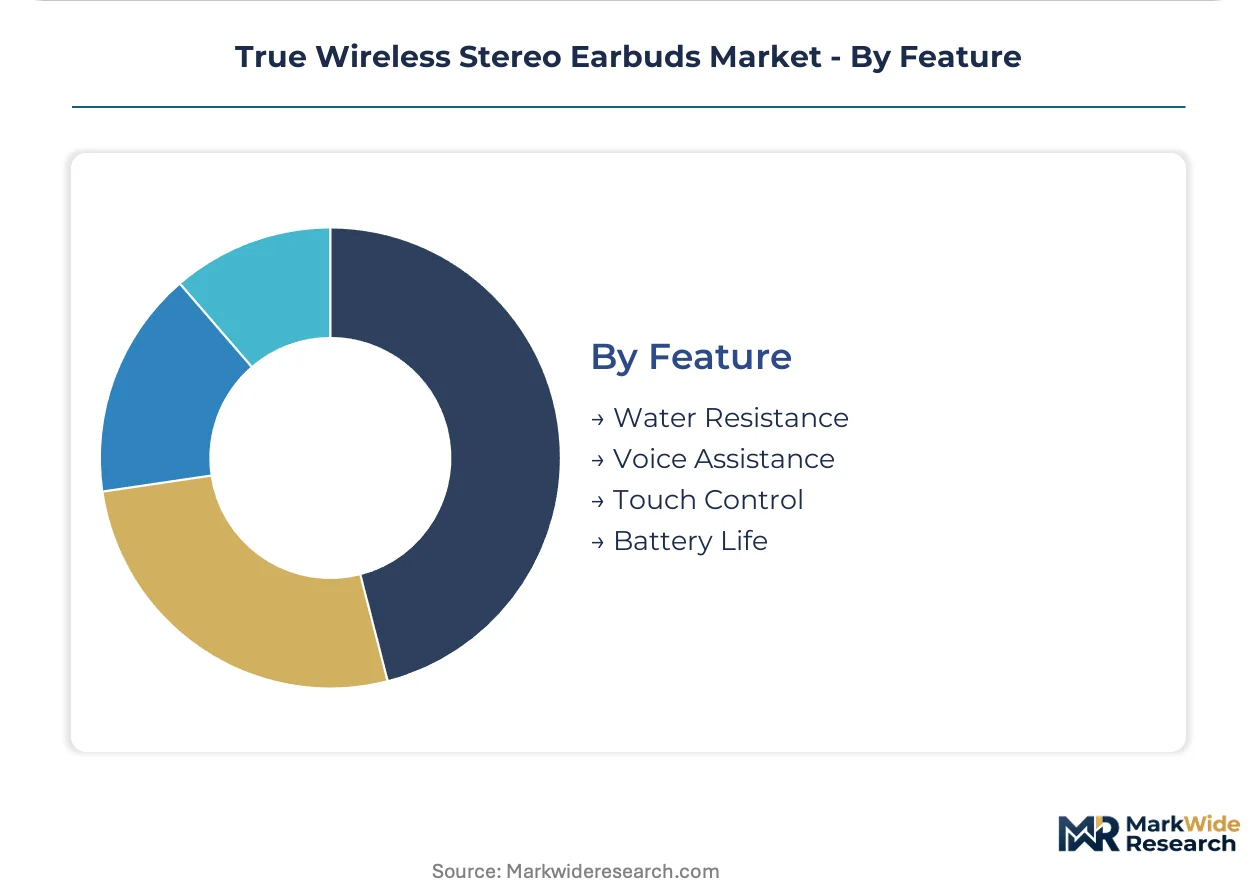
Feature:
Capability integration defines competitive differentiation as core audio performance commoditizes across mid-tier price bands.
- Battery Life:Cell capacity and power management IC efficiency determine uninterrupted playback duration. Commuter rail users in Japan and Germany prioritize multi-day endurance over rapid charging convenience.
- Water Resistance:IPX4 through IPX7 ingress protection ratings enable sweat and rain exposure without failure. Fitness application demand in humid climates drives specification escalation.
- Voice Assistance:Wake-word recognition and natural language processing offload to smartphone hosts or execute locally on embedded DSP cores. Smart home integration expands use cases beyond audio consumption.
- Touch Control:Capacitive surface gestures for playback, volume, and call management replace physical buttons for aesthetic minimalism. Gesture learning curves create user experience fragmentation.
Battery Life leads on scale; Water Resistance leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI-driven manufacturing expansion contrasts with the United States' premium consumption concentration, revealing divergent growth mechanics across major economies.
United States
Enterprise procurement from financial services and professional services verticals drives institutional volume for noise-cancelling variants. FCC SAR certification requirements extend product launch timelines by 8-14 weeks. Austin and Seattle tech corridors host headquarters operations for ecosystem-integrated vendors.
China
Smartphone ecosystem bundling displaces standalone retail as the dominant channel for Bluetooth-enabled shipments. MIIT enforces SRRC certification that filters eligible Bluetooth modules and antenna designs. Shenzhen and Dongguan manufacturing clusters execute precision injection molding and surface-mount assembly for sub-5 gram units.
India
Tier-2 urbanization in Indore, Kochi, and Lucknow outpaces metro smartphone penetration growth. Production-linked incentives attract assembly capacity to Gujarat and Tamil Nadu. Chennai and Ahmedabad facilities reduce landed costs for brands serving price-sensitive South Asian consumers.
Germany
Commuter rail users prioritize multi-day battery endurance over rapid charging convenience. EU Radio Equipment Directive mandates interoperability and safety testing for CE-marked products. Berlin and Munich serve as distribution hubs for LDAC codec-optimized audiophile-grade inventory.
Japan
Urban cycling corridors generate demand for on-ear designs balancing audio immersion with environmental monitoring. METI standards influence power efficiency benchmarks for Bluetooth Low Energy Audio implementations. Tokyo and Osaka retail channels emphasize compact in-ear form factors for portability-focused consumers.
True Wireless Stereo Earbuds Market Key Industry Players
Top-tier vendors anchor premium pricing through ecosystem lock-in and proprietary silicon architectures, while mid-tier competitors exploit manufacturing scale and channel control. The vendor base stratifies across three tiers: ecosystem-integrated specialists, manufacturing-scale generalists, and component-technology licensors. Dominant competitive moves include strategic partnerships for codec licensing and geographic expansion into PLI-subsidized assembly jurisdictions.
Among ecosystem-integrated specialists, Apple and Samsung Electronics occupy positions defined by captive silicon development and smartphone bundling leverage. Sony Corporation exemplifies the component-technology licensor archetype through codec standard influence. Xiaomi Corporation represents manufacturing-scale generalists competing through landed cost optimization in emerging markets.
| Leading Market Players |
|---|
| Apple |
| Samsung Electronics |
| Sony Corporation |
| Bose Corporation |
| Jabra |
| Xiaomi Corporation |
| Sennheiser Electronic |
| Skullcandy |
| Anker Innovations |
| Others |
Cost & Logistics Intelligence
RF engineering talent concentration in Shenzhen and Dongguan compresses labor-cost differentials between premium noise-cancelling tiers and entry-level Bluetooth SKUs, widening pricing spreads as brands arbitrage design sophistication against assembly economics.
Pricing Analysis
Bundled smartphone ecosystem sales dominate volume, while unbundled retail commands brand premiums. Three-tier pricing structure across premium, standard, and economy levels separates LDAC codec audiophile SKUs from mid-tier MEMS microphone ANC variants and sub-$50 entry units. Price differentiation rests on certification grade—FCC SAR testing for US market access versus MIIT SRRC compliance for China—and ecosystem integration depth. Pricing pressure stems from lithium-ion cell volatility compressing margin predictability at the economy tier. Casual users in India tier-2 cities exhibit highest price sensitivity; corporate procurement in US financial services verticals shows lowest.
Supply Chain Analysis
Bluetooth SoC supply rests on Taiwanese fabless design houses and South Korean foundry capacity, with precision injection molding concentrated in Dongguan and surface-mount assembly scaling through Gujarat PLI facilities. Key inputs span cobalt-bearing lithium-ion cells, MEMS microphone wafers from Bosch and Knowles, and biocellulose driver membranes from Japanese specialty suppliers. Single-source vulnerability concentrates around H-series chip architectures and proprietary codec DSP cores. Distribution runs through smartphone OEM bundled channels in China and India, direct-to-consumer retail in Germany and Japan, and enterprise IT procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through LE Audio protocol adoption reducing power management IC costs and FDA OTC hearing aid regulations enabling premium-tier software-defined amplification features.
For Market Incumbents: Anchor ecosystem lock-in through H-series or equivalent captive silicon architectures that sustain pricing power against Xiaomi manufacturing-scale challengers. Defend against right-to-repair compliance complexity by modularizing battery compartments ahead of EU Ecodesign mandates. Prioritize backward integration into MEMS microphone wafer supply to secure feedforward ANC component access. For New Entrants and Emerging Players: India's PLI scheme in Gujarat and Tamil Nadu opens a window for landed cost optimization serving price-sensitive South Asian consumers. Target tier-2 urbanization whitespace in Indore, Kochi, and Lucknow where smartphone penetration outpaces metro saturation. Pursue Auracast broadcast audio deployments in fitness centers and transit authorities as institutional demand channels bypassing retail competition. For Investors and Strategic Acquirers: Smartphone ecosystem vendors are the most active acquirer in this space, seeking codec IP and hearing health integration capabilities. Long-term viability hinges on LE Audio plus Auracast convergence expanding addressable volume beyond consumer retail into accessibility infrastructure. Watch FDA OTC hearing aid regulatory enforcement as inflection indicator for medical device category blurring.| Strategic Initiative | Industry Significance |
|---|---|
| LE Audio Protocol Adoption | Broadcast audio capability opens institutional procurement channels in transit and hospitality verticals. |
| PLI Manufacturing Expansion | Gujarat and Tamil Nadu assembly capacity reduces landed costs for South Asian market entry. |
| Hearing Health Integration | FDA OTC regulations enable software-defined amplification blurring consumer and medical device boundaries. |
| Codec Sovereignty Investment | LDAC or aptX Adaptive licensing builds defensive moats against SBC commoditization in mid-tiers. |
| Enterprise Fleet Standardization | IT department procurement in financial services displaces individual consumer purchasing for ANC variants. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from Bluetooth SoC product managers, MEMS microphone procurement leads at tier-1 earbud OEMs, RF engineering directors, retail category buyers, and enterprise IT fleet managers. Secondary validation drew from FCC equipment authorization databases, MIIT SRRC certification filings, EU Radio Equipment Directive technical documentation, and PLI scheme beneficiary disclosures. Bottom-up shipment modeling and top-down smartphone ecosystem penetration analysis triangulated volume estimates.
Segment-weighting approaches distributed value across form factor, connectivity protocol, end-user archetype, and feature integration dimensions. CAGR derivation incorporated Bluetooth Low Energy Audio adoption curves, India's PLI capacity buildout timelines, and enterprise procurement shift trajectories. Modeling captured feedforward ANC component cost erosion, lithium-ion cell price volatility scenarios, and Auracast infrastructure deployment pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt supply disruption or right-to-repair mandate acceleration. Forecasts reflect documented assumptions on LE Audio protocol stack maturity and PLI scheme continuity. Regulatory timeline slippage in FCC SAR certification or EU battery replaceability enforcement could revise trajectory. A small set of named triggers—Auracast venue deployment velocity, FDA OTC hearing aid enforcement clarity, and India tier-2 smartphone penetration saturation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Gaming Mouse & Keyboards Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Gaming Keyboard Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Notebook Market
Consumer Electronics
Ereader Market