
 Orthopedic Footwear Market | 2026-2036
Orthopedic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Orthopedic Footwear Market Analytics
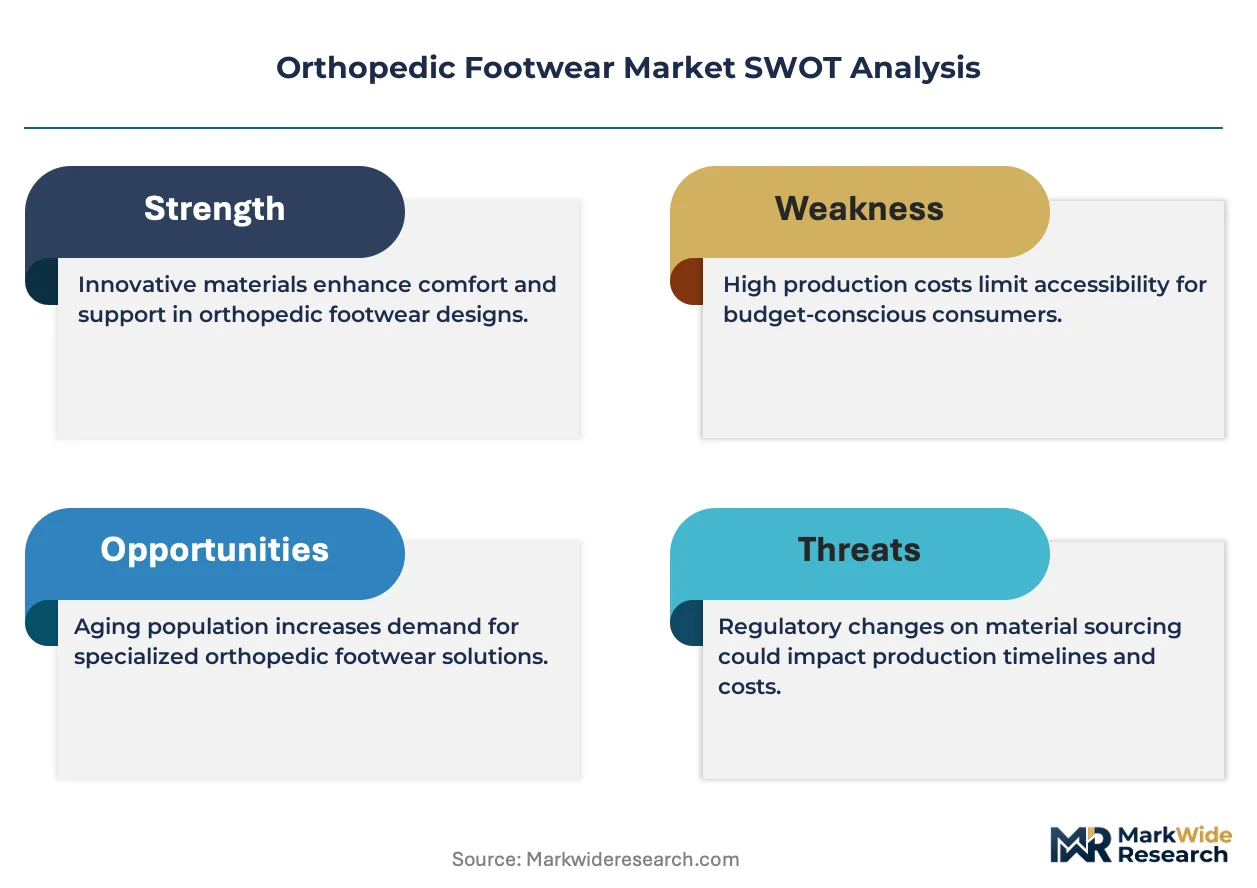
REACH compliance is restructuring material sourcing and testing protocols for European orthopedic footwear imports. Orthofeet leverages vertically integrated manufacturing to control cost escalation from certification requirements. New Balance competes through athletic orthopedic crossover designs that bridge performance and medical functionality. Propet Footwear anchors its position in Medicare-reimbursable diabetic shoe channels across the United States.
Orthopedic footwear denotes therapeutic shoes engineered with biomechanical support structures, custom-moldable insoles, and pressure-relief geometries to treat or prevent foot pathologies including diabetes-related ulcers, plantar fasciitis, and arthritic deformities. Construction typically integrates multi-density EVA midsoles, seamless interior linings, and extra-depth toe boxes to accommodate orthotic inserts while redistributing plantar pressure away from high-risk zones. Diabetic shoes command the largest revenue pool within product type segmentation due to chronic disease prevalence and insurance reimbursement structures, while athletic orthopedic footwear represents the fastest-expanding category as sports medicine protocols normalize preventive bracing. Seniors dominate age group demand structurally, though pediatric orthopedic correction via early-intervention programs is gaining clinical traction in specialized channels.
The FDA classifies diabetic and custom-molded orthopedic shoes as Class I or II medical devices, subjecting manufacturers to quality system regulations and 510(k) notification pathways for novel pressure-offloading mechanisms. The EU Medical Device Regulation and CE marking requirements enforce clinical evidence standards for therapeutic claims, while Japan's PMDA and METI coordinate reimbursement listing procedures that determine market access for imported orthopedic products. Stakeholders must monitor evolving reimbursement codes in Medicare and national health systems, as coverage determinations directly dictate patient out-of-pocket exposure and manufacturer volume forecasts across priority markets.
Market Dynamics
EU MDR compliance deadlines are forcing orthopedic footwear manufacturers to restructure clinical evidence portfolios and quality management systems ahead of notified body capacity constraints.
Growth Catalysts
- Diabetes prevalence trajectories:Chronic disease management protocols in the United States and Japan now mandate annual foot screening, expanding reimbursable prescription volumes for therapeutic footwear through Medicare and Japan's Ministry of Health, Labour and Welfare fee schedules.
- REACH material certification:European chemical safety registrations for polyurethane foams and synthetic leathers are streamlining cross-border supply chains by eliminating redundant national testing regimes across Germany, France, and Italy.
- 3D printing adoption:Selective laser sintering of nylon midsoles is compressing custom orthotic production cycles from weeks to days in podiatric clinics across Australia and the Netherlands.
Market Restraints
- Ethylene-vinyl acetate price volatility:Petrochemical feedstock fluctuations directly compress midsole gross margins for manufacturers without captive resin supply agreements.
- Notified body bottlenecks:EU MDR designation delays for orthopedic footwear class IIa devices are extending time-to-market by 14-18 months for novel pressure-offloading mechanisms.
- Over-the-counter insole substitution:Mass-market gel and memory foam inserts priced at one-tenth prescription equivalents capture mild pathology cases before clinical referral.
Strategic Opportunities
- Pediatric early intervention:School-based screening programs in South Korea and Taiwan are creating referral pipelines for corrective footwear before skeletal maturity.
- Telehealth prescription pathways:Remote gait analysis via smartphone video is enabling direct-to-patient fitting in rural United States counties lacking podiatrist density.
- Green public procurement:EU Green Deal sustainable product criteria will favor footwear with recycled content and solvent-free adhesives in hospital and municipal tender awards.
Industry Challenges
- Biomechanist talent scarcity:The intersection of footwear design and clinical gait analysis lacks accredited training programs, forcing manufacturers to poach from academic research labs.
- Legacy ERP integration:Medical device quality system software from the 1990s cannot interface with modern 3D scanning platforms, requiring parallel manual documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthopedic Footwear Market |
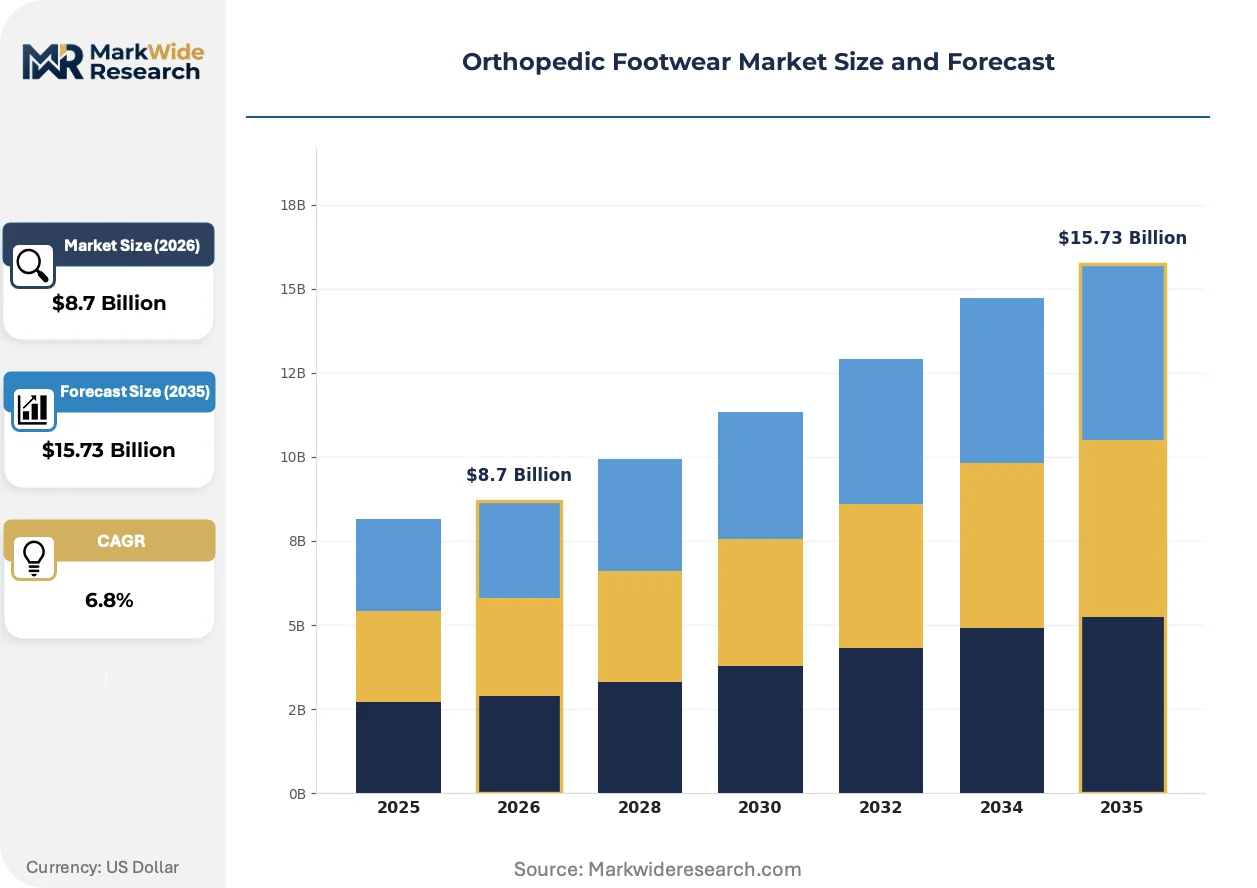
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diabetic Shoes, Athletic Footwear, Sandals, Boots Age Group: Children, Adults, Seniors, Teens Material: Leather, Synthetic, Fabric, Rubber Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Orthofeet, Apex Foot Health Industries, New Balance, Vionic Group, Propet Footwear, Dr. Comfort, DARCO International, Drew Shoe, Aetrex Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthopedic Footwear Market Evolving Landscape
Digital manufacturing and regulatory digitization are compressing product development cycles while fragmenting traditional wholesale channels into direct clinical relationships.
Pressure-mapping insole sensors paired with smartphone gait analysis is rewriting how diabetic foot ulcer risk gets stratified and monitored outside clinical settings. Medicare Advantage plans in Florida and Arizona are piloting remote patient monitoring reimbursement for continuous plantar pressure data. This telemetry infrastructure is enabling outcomes-based contracts between payers and footwear suppliers that tie reimbursement to ulcer prevention rates.
EU MDR Article 10 clinical evaluation requirements are mandating systematic literature reviews and post-market surveillance for all therapeutic footwear with pressure-reduction claims. German notified bodies are rejecting legacy predicate devices that lack prospective biomechanical studies, forcing redesigns of established extra-depth shoe platforms. Manufacturers with pre-2021 CE marks face portfolio triage decisions as recertification costs exceed revenue for niche sizes.
Hospital supply chain consolidation is concentrating orthopedic footwear procurement through integrated delivery networks that demand sole-source contracts with 30-day inventory guarantees. Group purchasing organizations in Texas and California are unbundling fitting services from product pricing, pressuring independent pedorthists to join employed clinic models. This channel compression favors manufacturers with direct-to-clinic logistics infrastructure over traditional wholesale distributors.
Orthopedic Footwear Market Segmentation
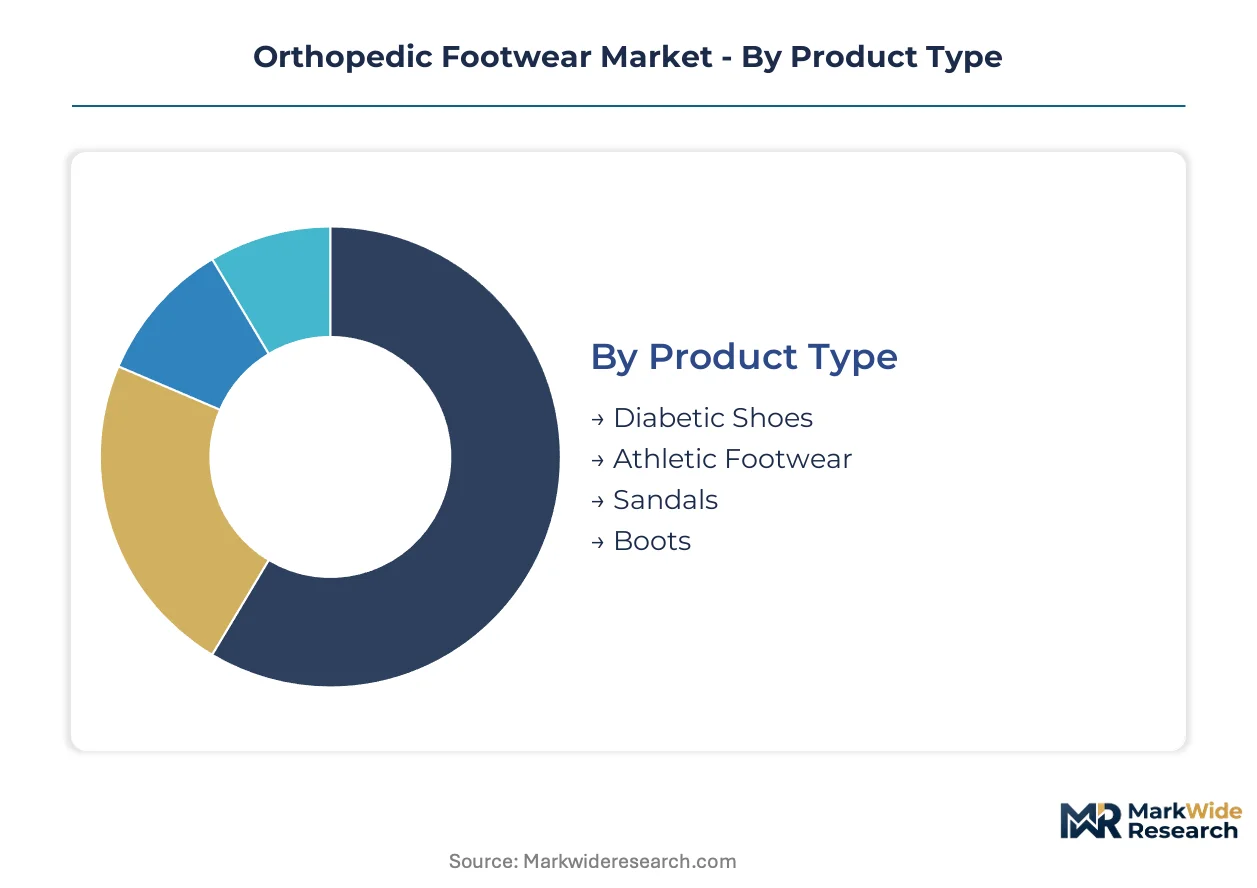
Orthopedic footwear segmentation reveals how clinical reimbursement pathways, material compliance regimes, and channel consolidation reshape procurement decisions across patient populations. Distinct upgrade cycles govern each category—from annual diabetic shoe replacements to multi-year pediatric correction timelines.
Product Type:
Replacement cycles vary dramatically by pathology severity and insurance authorization schedules, with chronic conditions demanding more frequent footwear turnover than preventive applications.
- Diabetic Shoes:Extra-depth construction with seamless interiors and pressure-relief insoles accommodates neuropathic foot deformities. Medicare and Japan's MHLW fee schedules drive prescription volumes in the United States and Japanese home-care settings, where annual foot screening mandates expand reimbursable eligibility.
- Athletic Footwear:Biomechanical support structures bridge sports medicine protocols and recreational use, featuring multi-density midsoles and motion-control geometries. Podiatric clinics in Australia and the Netherlands are adopting 3D-printed custom variants as preventive bracing normalizes among active aging populations.
- Sandals:Open-toe therapeutic designs with adjustable strap systems serve warm-climate diabetic patients and post-operative recovery cases.
- Boots:Ankle-stabilizing constructions with rigid shanks address arthritic deformities and trauma rehabilitation in institutional settings.
Diabetic shoes sit at the top of the volume ranking, with athletic footwear climbing the fastest as sports medicine protocols expand preventive prescribing.
Age Group:
Cost tier differentiation separates segments, with pediatric custom molding commanding premium pricing against standardized senior mass-production.
- Seniors:Structural demand concentration reflects aging demographics in Germany, Japan, and the United States, where Medicare and statutory health insurance absorb out-of-pocket costs for therapeutic footwear. Chronic disease prevalence and fall-prevention protocols sustain replacement cycles.
- Children:Early-intervention programs in South Korea and Taiwan generate referral pipelines for corrective footwear before skeletal maturity, with school-based screening expanding addressable incidence.
- Adults:Occupational and sports-related pathologies drive mid-market purchasing, often without full insurance coverage.
- Teens:Growth-spurt-related gait abnormalities and sports injuries create episodic demand concentrated in athletic and academic medical centers.
Seniors dominate absolute volume, while pediatric segments gain share fastest through early-intervention program expansion.
Material:
Supply concentration for certified inputs determines which material segments can scale under REACH and FDA biocompatibility requirements.
- Leather:Full-grain and nubuck constructions with moisture-wicking properties serve premium diabetic and arthritic segments. Italian and Portuguese tanneries with REACH-compliant chrome-free processing anchor European supply chains for hospital procurement.
- Synthetic:Polyurethane and microfiber alternatives offer seamless molding for pressure-relief geometries at lower unit costs. ECHA registration requirements for phthalate-free formulations are restructuring Asian supplier qualification.
- Fabric:Breathable mesh and knit uppers accommodate edema and temperature-sensitive neuropathies in warm climates.
- Rubber:Outsole-dominant applications provide slip resistance and shock absorption for institutional and outdoor use cases.
Leather maintains volume leadership in premium channels, with synthetic materials expanding most quickly as cost-sensitive procurement and vegan preferences reshape specifications.
Distribution Channel:
Customer type fragmentation—clinical prescription versus direct consumer purchase—determines which channels capture margin versus volume.
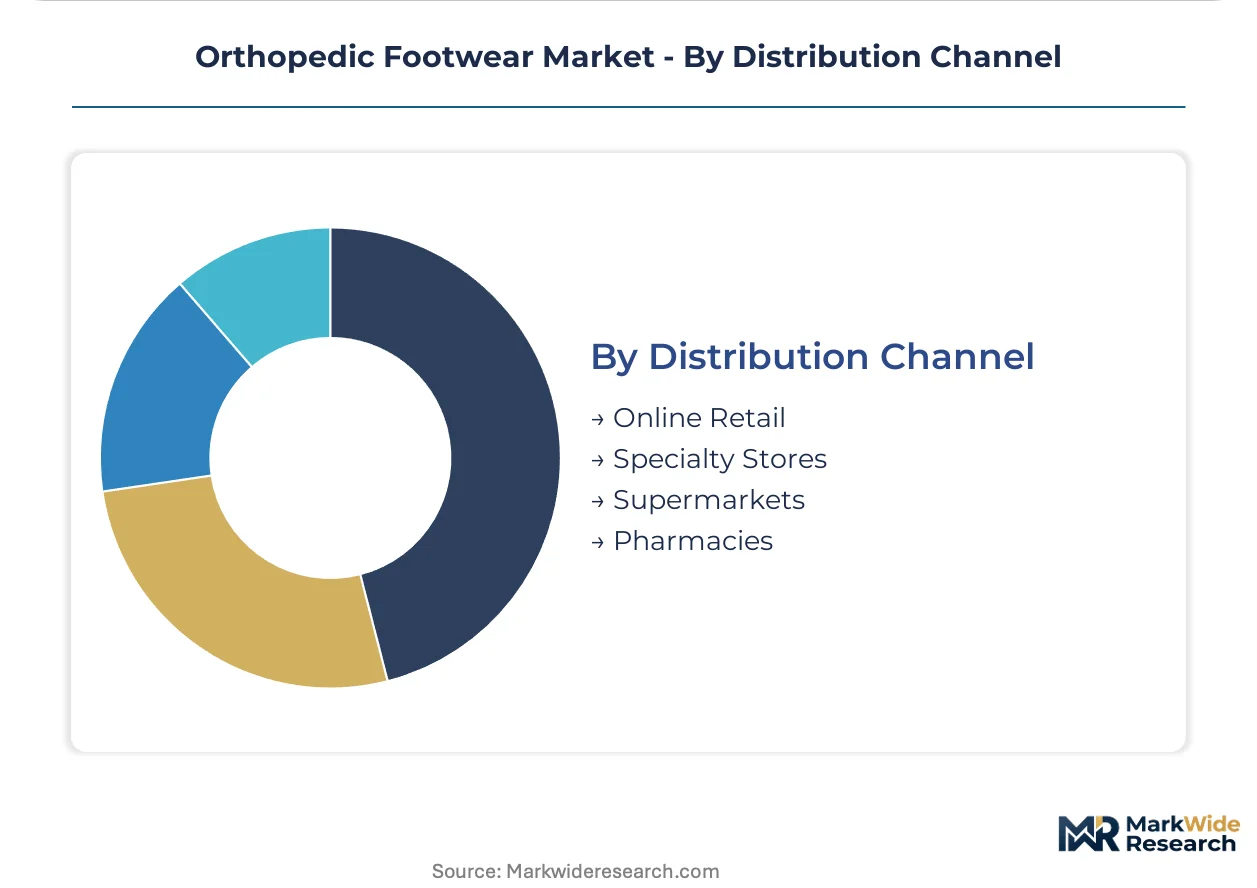
- Specialty Stores:Pedorthist-staffed fitting services with 3D scanning and gait analysis equipment dominate Medicare-reimbursable transactions. Independent operators in Texas and California face consolidation pressure from integrated delivery network contracting.
- Online Retail:Direct-to-patient platforms with remote sizing algorithms and telehealth prescription pathways are penetrating rural United States counties lacking podiatrist density. Smartphone gait analysis integration enables remote fitting validation.
- Pharmacies:Retail clinic partnerships and durable medical equipment counters capture convenience-driven refill purchases for established patients.
- Supermarkets:Mass-market gel insoles and basic supportive footwear serve mild pathology cases before clinical referral, though therapeutic claims remain restricted.
Specialty stores hold the volume advantage in reimbursed segments, with online retail gaining share fastest through telehealth integration and rural market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic footwear manufacturing traces its therapeutic foundations to post-war German pedorthic engineering, with subsequent scaling in the United States through Medicare reimbursement mechanisms established in the 1990s.
United States
Medicare Part B coverage for therapeutic shoes drives prescription volumes among diabetic populations, with annual foot screening mandates expanding eligible patient pools. FDA Class II medical device classification enforces quality system regulations and 510(k) notification pathways for novel pressure-offloading designs. Florida and Arizona Medicare Advantage plans pilot remote patient monitoring reimbursement, creating outcomes-based contracting opportunities for suppliers.
Germany
Aging demographics and statutory health insurance absorption of therapeutic footwear costs sustain replacement cycles for arthritic and diabetic segments. EU MDR Article 10 clinical evaluation requirements mandate systematic literature reviews for pressure-reduction claims, with German notified bodies rejecting legacy predicate devices lacking prospective biomechanical studies. Bavarian pedorthic workshops cluster around Munich, adapting extra-depth shoe platforms for recertification compliance.
Japan
Ministry of Health, Labour and Welfare fee schedules determine reimbursable prescription volumes for home-care diabetic footwear. PMDA and METI coordinate reimbursement listing procedures that gate market access for imported orthopedic products. Tokyo and Osaka medical device distribution hubs concentrate procurement decisions for hospital supply chains.
United Kingdom
NHS England commissioning frameworks for diabetic foot care services create institutional demand for therapeutic footwear in clinical pathways. MHRA recognition of EU MDR certificates maintains transitional market access while domestic UKCA marking requirements phase in. London and Manchester integrated care systems consolidate procurement through sole-source contracts with inventory guarantees.
Australia
Medicare Benefits Schedule subsidies for podiatry services indirectly support therapeutic footwear prescribing in rural counties lacking specialist density. TGA medical device regulations align with EU MDR clinical evidence standards for pressure-offloading claims. Sydney and Melbourne podiatric clinics adopt selective laser sintering of nylon midsoles, compressing custom orthotic production cycles.
Orthopedic Footwear Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive manufacturing and direct clinical channel control. Market concentration remains moderate, with Medicare-reimbursable diabetic shoe segments showing tighter procurement consolidation than athletic orthopedic crossover categories. Three archetypes dominate: vertically integrated therapeutic specialists, athletic footwear incumbents with medical line extensions, and direct-to-patient digital platforms with telehealth integration. Capacity expansion in certified resin compounding and notified body queue positioning represent the dominant competitive moves as EU MDR deadlines approach.
Among vertically integrated therapeutic specialists, Orthofeet exemplifies the archetype through in-house production control over certification cost escalation. New Balance occupies a position bridging athletic performance and medical functionality, representing the incumbent crossover strategy. Propet Footwear anchors the Medicare-reimbursable channel focus, sitting within the diabetic shoe reimbursement specialization tier. These three company structures illustrate how geographic origin and organizational form map to distinct competitive positioning vectors in therapeutic footwear procurement.
| Leading Market Players |
|---|
| Orthofeet |
| Apex Foot Health Industries |
| New Balance |
| Vionic Group |
| Propet Footwear |
| Dr. Comfort |
| DARCO International |
| Drew Shoe |
| Aetrex Worldwide |
| Others |
Value Network & Pricing Analysis
Pedorthic engineering talent clusters in Bavaria and Portugal's northern industrial belt, with labor-cost differentials between these European centers and Asian manufacturing zones driving 40-60 point spreads between premium custom-molded and mass-produced economy tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs orthopedic footwear procurement. Price differentiation rests on certification grade—FDA Class II and EU MDR CE marking command 25-35 point premiums over unclassified wellness products—and customization depth from stock sizing to full biomechanical modeling. Cost compression in the economy tier is intensifying because ethylene-vinyl acetate feedstock volatility passes through to midsole suppliers without captive resin agreements. Medicare-reimbursable diabetic shoe buyers exhibit lowest price sensitivity due to statutory coverage, while direct-to-consumer athletic crossover purchasers negotiate aggressively on comparable athletic brand benchmarks.
Supply Chain Analysis
Single-source vulnerability sits with Italian and Portuguese tanneries for REACH-compliant chrome-free leather processing. Manufacturing concentrates in China for synthetic upper molding, Vietnam for EVA midsole injection, and Germany for final custom assembly and quality certification. Raw material dependencies include petroleum-derived polyurethane foams, nylon powders for selective laser sintering, and medical-grade adhesives meeting ISO 10993 biocompatibility. Tariff exposure on Chinese footwear components threatens margin stability for manufacturers without alternative Southeast Asian tooling. Distribution runs through pedorthist-staffed specialty stores for reimbursed prescriptions, with direct-to-patient platforms capturing growing rural and telehealth-authorized volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU MDR compliance costs in Germany and manufacturing scale economics in Vietnam, with regulatory differential creating 18-24 month time-to-market advantages for Southeast Asian producers serving non-European markets.
For Market Incumbents: Anchor market position through backward integration into certified resin compounding to neutralize EVA price volatility and notified body queue positioning ahead of EU MDR recertification deadlines. Defend against direct-to-patient digital platforms by locking exclusive fitting service contracts with integrated delivery networks in Texas and California. Prioritize capacity addition in Vietnam for synthetic upper production to maintain margin buffers against European labor inflation. For New Entrants and Emerging Players: Begin with pediatric early-intervention programs in South Korea and Taiwan, where school-based screening creates referral pipelines before competitive consolidation. Target telehealth prescription pathways in rural United States counties lacking podiatrist density, leveraging smartphone gait analysis for remote fitting validation. Pursue white-label manufacturing partnerships with Bavarian pedorthic workshops seeking Asian production scale for non-EU markets. For Investors and Strategic Acquirers: Athletic footwear incumbents with medical line extensions are the most active acquirer in this space, seeking biomechanical design capabilities and Medicare reimbursement expertise. Five-to-ten year viability favors vertically integrated specialists with captive manufacturing and direct clinical channel control over pure-brand licensors. Acquisition target archetype: mid-cap therapeutic specialists with EU MDR pre-certification and established GPO contracts. Signal to watch: Medicare Advantage remote patient monitoring reimbursement expansion in Florida and Arizona as outcomes-based contracting inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Notified body queue positioning determines 14-18 month competitive lead for pressure-offloading innovations. |
| Backward Integration into Resin Compounding | Captive EVA supply neutralizes petrochemical feedstock volatility compressing midsole gross margins. |
| Telehealth Platform Integration | Smartphone gait analysis enables Medicare-reimbursable remote fitting in podiatrist-scarce rural counties. |
| Pediatric Early-Intervention Partnership | School-based screening programs in South Korea and Taiwan generate pre-skeletal-maturity referral pipelines. |
| Integrated Delivery Network Contracting | Sole-source agreements with Texas and California GPOs lock out wholesale distributor competition. |
Research Methodology
Direct dialogue with pedorthic clinic operators, hospital purchasing committee members, biomedical engineers at notified bodies, GPO contracts managers, and Medicare reimbursement specialists grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU MDR notified body designation records, CMS Medicare fee schedule data, and hospital procurement databases. Bottom-up patient population modeling and top-down reimbursement volume analysis triangulated market sizing.
Segment-level projections across product type, age group, material certification grade, and distribution channel fed into analytical framework spanning the projection horizon. CAGRs derived from diabetes prevalence trajectories, statutory screening mandate expansion, and 3D printing adoption curves in podiatric clinics. Industry-specific forecast inputs included Medicare Advantage remote patient monitoring pilot results and EU Green Deal sustainable procurement criteria implementation timelines.
Several conditions sit outside the modeled scope, including unpredictable EU MDR notified body capacity constraints, ethylene-vinyl acetate commodity price shocks, and wholesale distributor bankruptcy cascades from IDN consolidation pressure. Forecasts reflect documented assumptions on reimbursement code stability and REACH material certification continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Ankle Boots Market
Footwear
Cowgirl Boots Market
Footwear
Refurbished Sneaker Market
Footwear
Sandals Market
Footwear
Football Shoes Market
Footwear
Gypsy Jazz Shoes Market
Footwear
US Slip Resistant Shoes Market
Footwear
Tactical Footwear Market
Footwear
North America Footwear Market
Footwear
South America Athletic Footwear Market
Footwear
Equestrian Footwear Market
Footwear
Premium Shoes Market
Footwear
Duck Boots Market
Footwear
Running Shoes Market
Footwear
Wedge Boots Market
Footwear
Indian Footwear Market