
 Middle East and Africa E-Commerce Footwear Market | 2026-2036
Middle East and Africa E-Commerce Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa E-Commerce Footwear Market Insights
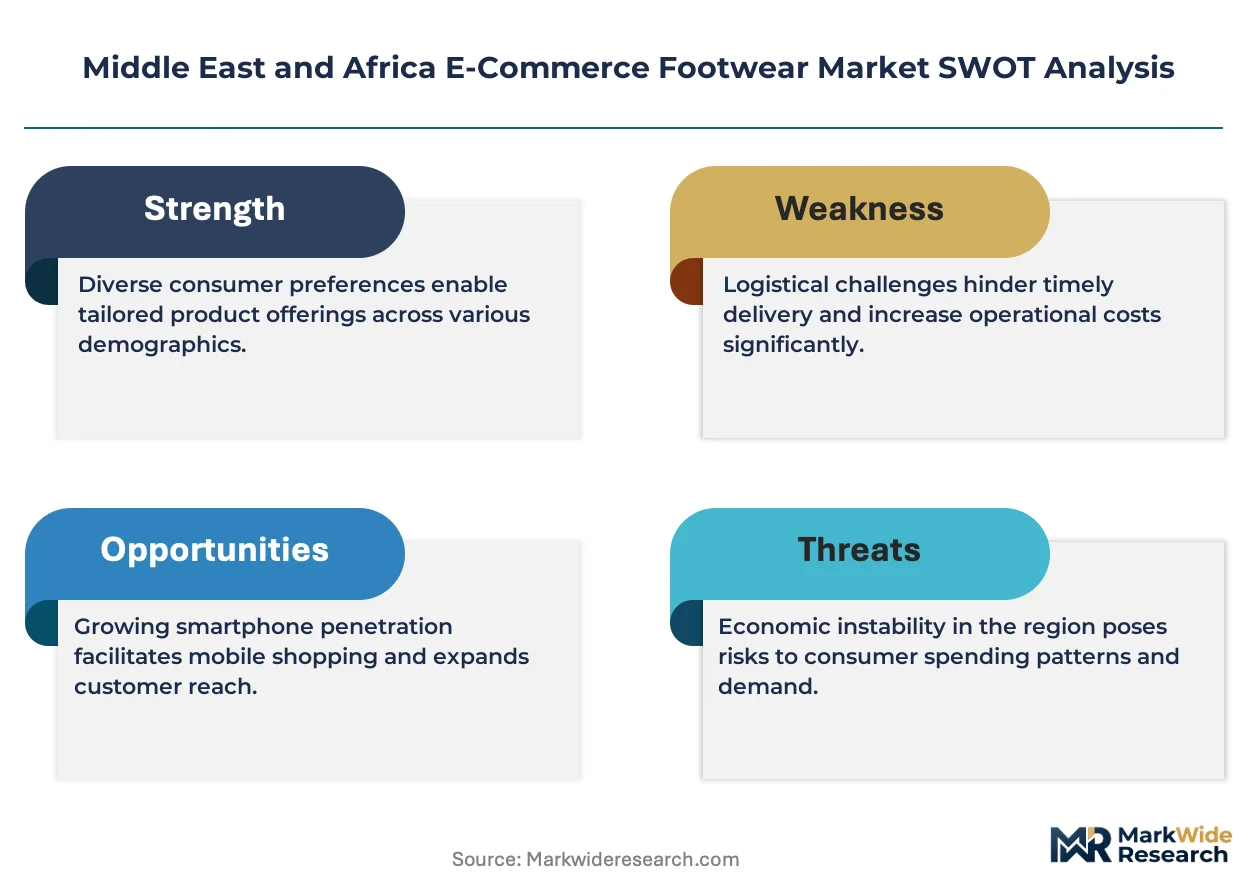
South Africa's last-mile delivery infrastructure is fragmenting as courier networks expand beyond Johannesburg and Cape Town. Nike Inc. leverages its direct-to-consumer app ecosystem to bypass traditional retail intermediaries. Adidas AG anchors its regional presence through localized Arabic-language storefronts. Namshi competes aggressively on fashion-forward assortments tailored to Gulf style preferences.
E-commerce footwear encompasses digitally transacted closed-toe and open-toe apparel designed with leather uppers, synthetic mesh uppers, or rubberized soles for protection, locomotion, and fashion expression across consumer and athletic applications. Sports shoes with EVA midsole cushioning dominate volume throughput due to gym culture proliferation across Gulf urban centers. Casual footwear captures expanding margin pools as remote work normalization sustains demand for versatile styling. Luxury positioning within brand positioning segments commands premium realization through limited-edition drops and influencer collaboration models.
SAMR in Saudi Arabia and the UAE's Telecommunications and Digital Government Regulatory Authority enforce consumer protection standards governing return policies and product authenticity verification for online footwear transactions. South Africa's Consumer Protection Act mandates disclosure of material composition and country-of-origin labeling, elevating compliance costs for cross-border sellers. Stakeholders must monitor evolving VAT collection obligations across fragmented national tax regimes as digital economy frameworks mature.
Market Dynamics
Mobile-first commerce infrastructure is restructuring how footwear reaches consumers across Gulf Cooperation Council states, compressing traditional retail intermediaries while elevating platform-native fulfillment expectations.
Growth Catalysts
- SAMR Licensing Framework:Saudi Arabia's streamlined digital retail licensing under SAMR reduces market entry friction for cross-border footwear sellers. New entrant approval timelines have compressed materially.
- EVA Midsole Adoption:Sports shoes with EVA cushioning dominate volume throughput as gym culture proliferates across Gulf urban centers. Athletic applications now anchor category demand.
- Dubai Logistics Cluster:The emirate's advanced fulfillment infrastructure enables same-day delivery expectations that lock in consumer loyalty and elevate switching costs for competing platforms.
Market Restraints
- Synthetic Input Volatility:Petrochemical-derived mesh uppers face feedstock cost swings that compress margin pools for value-tier positioning. Producers lack pricing power to pass through spikes.
- Last-Mile Fragmentation:South Africa's courier networks remain concentrated around Johannesburg and Cape Town, leaving secondary metros with unreliable delivery windows and elevated return rates.
- Authenticity Verification Burden:UAE's Telecommunications and Digital Government Regulatory Authority mandates product authentication protocols that inflate compliance overhead for marketplace operators.
Strategic Opportunities
- Nairobi E-Commerce Penetration:Kenya's capital exhibits underdeveloped digital footwear retail relative to smartphone penetration metrics. Early platform entrants capture uncontested demand.
- Arabic Localization Gap:Fashion-forward assortments tailored to Gulf style preferences remain underserved by Western-centric catalogues. Native-language storefronts unlock conversion lift.
- VAT Harmonization Tailwind:Evolving digital economy tax frameworks across national regimes create compliance clarity that favors scaled operators with dedicated fiscal infrastructure.
Industry Challenges
- Return Logistics Complexity:Consumer protection standards governing footwear return policies strain reverse supply chains. SAMR and South Africa's Consumer Protection Act impose divergent material disclosure requirements.
- Composition Labeling Compliance:Country-of-origin and material composition mandates elevate documentation burdens for cross-border sellers. Multi-jurisdiction SKU management requires specialized regulatory technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa E-Commerce Footwear Market |
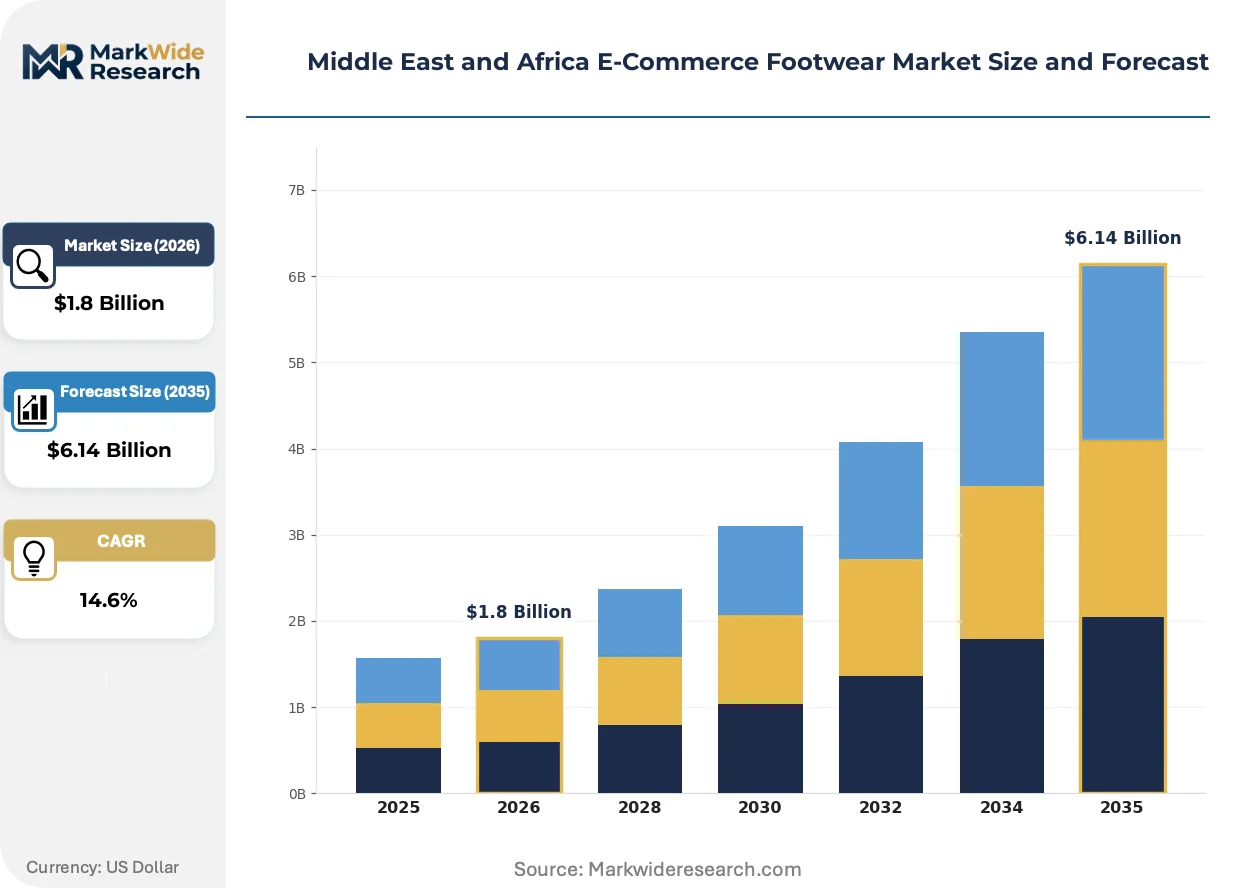
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Shoes, Casual Footwear, Formal Shoes, Sandals Consumer Demographics: Men, Women, Children, Youth Sales Channel: Online Retailers, Brand Websites, Marketplaces, Social Media Platforms Brand Positioning: Luxury, Mid-Range, Budget, Premium |
| Companies Covered | Nike Inc., Adidas AG, Puma SE, Skechers USA, Inc., LVMH Moët Hennessy Louis Vuitton, Jumia, Namshi, Noon.com, Ounass, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa E-Commerce Footwear Market Trends and Innovations
Three converging forces are restructuring value capture in Middle East and Africa digital footwear: immersive commerce interfaces, regulatory digitization, and behavioral platform migration.
Virtual try-on technology is virtualizing the fit-assurance function historically performed by physical retail. Gulf-based young adult consumers adopt augmented reality sizing tools at accelerating rates, particularly for limited-edition drops where return friction is highest. This compression of the purchase confidence gap is enabling direct-to-consumer models to bypass traditional fitting-room intermediaries entirely.
South Africa's Consumer Protection Act enforcement is tightening material disclosure standards for synthetic leather and rubberized sole compositions. Cross-border sellers now face elevated documentary requirements that delay customs clearance and inflate landed costs. Premium positioning segments absorb these overheads most readily, while value-tier operators retreat from formal import channels.
Remote work normalization has compressed the distinction between athletic and casual footwear categories. Buyers across Dubai and Riyadh now prioritize versatile styling that transitions across home, gym, and limited social settings. This behavioral pivot elevates margin pools for hybrid-design products while pressuring single-use athletic inventory.
Middle East and Africa E-Commerce Footwear Market Segmentation
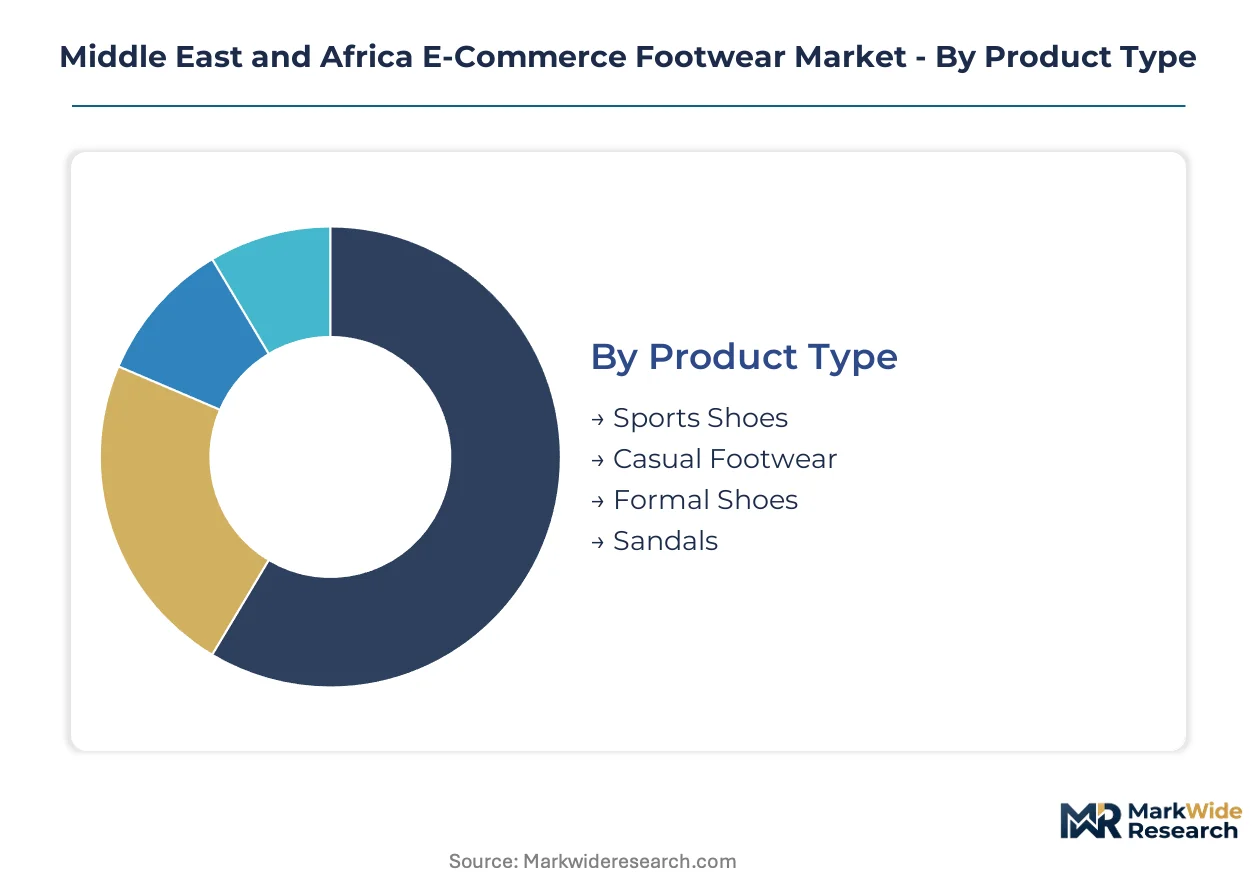
Segmentation in Middle East and Africa digital footwear reveals how purchase behavior fragments across price sensitivity, platform loyalty, and cultural styling requirements. Understanding these divisions enables targeted inventory allocation and localized marketing spend.
Product Type:
Application focus determines material specifications, cushioning technologies, and seasonal demand patterns across the region's climate zones.
- Sports Shoes:EVA midsole cushioning and breathable synthetic mesh uppers dominate construction. Volume concentrates in Saudi Arabia and UAE gym culture clusters where athletic lifestyle adoption drives repeat purchase frequency.
- Casual Footwear:Versatile styling bridges home, remote work, and social settings with leather or canvas uppers. Demand in Dubai and Riyadh elevates margin pools as consumers prioritize cross-occasion utility over single-purpose designs.
- Formal Shoes:Leather uppers with rubberized or leather soles serve professional and ceremonial occasions across Gulf corporate environments.
- Sandals:Open-toe designs with synthetic or leather straps address regional climate adaptation and traditional styling preferences.
Sports shoes hold installed capacity. Casual footwear is rotating up the share rankings.
Consumer Demographics:
Customer type shapes sizing assortment, price band distribution, and platform engagement patterns across mobile-first commerce infrastructure.
- Men:Work and athletic applications drive bulk purchasing with lower return rates. Saudi Arabia's young adult male segment anchors volume throughput through brand-direct app ecosystems.
- Women:Fashion-forward assortments with higher SKU diversity and seasonal refresh cycles elevate basket values. UAE-based consumers exhibit strongest platform loyalty when Arabic-language interfaces are available.
- Children:Rapid size turnover creates replacement-driven demand with price-sensitive parent purchasers across South African metros.
- Youth:Limited-edition drops and influencer collaboration models concentrate engagement in Gulf urban centers with highest smartphone penetration.
Men's segment holds installed capacity. Women's segment is climbing the fastest.
Sales Channel:
Volume concentration varies by fulfillment infrastructure maturity and regulatory compliance burden across national digital economy frameworks.
- Online Retailers:Curated assortments with established logistics partnerships enable reliable delivery windows. Dubai-based operators leverage same-day fulfillment infrastructure to lock consumer loyalty.
- Brand Websites:Direct-to-consumer models bypass marketplace commissions and capture first-party data. Nike and Adidas anchor regional presence through localized Arabic storefronts with virtual try-on integration.
- Marketplaces:Aggregated demand pools with authentication overhead imposed by UAE's Telecommunications and Digital Government Regulatory Authority.
- Social Media Platforms:Influencer-driven discovery with embedded checkout functionality concentrates among Gulf youth demographics.
Online retailers hold installed capacity. Brand websites are gaining share fastest.
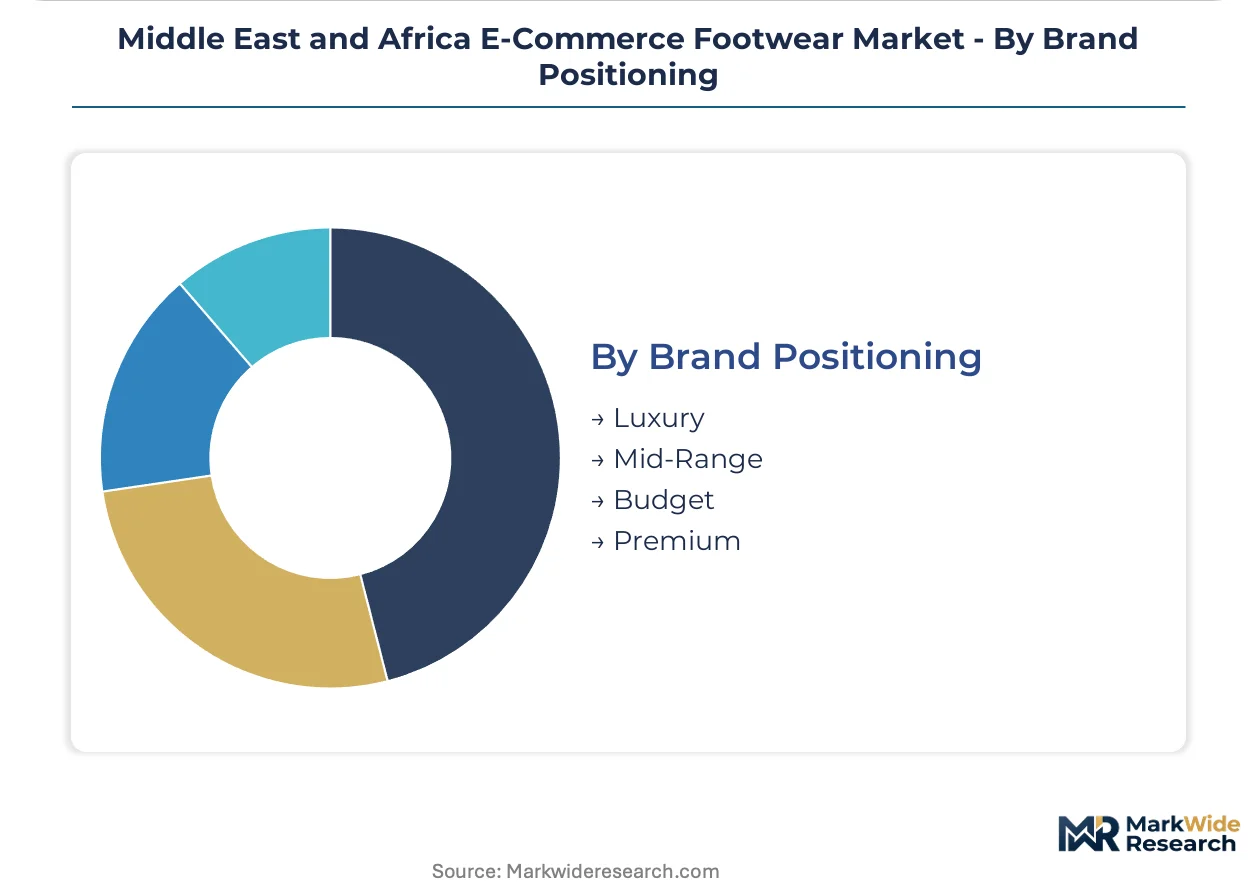
Brand Positioning:
Cost tier alignment determines margin structure, marketing intensity, and supply chain complexity for cross-border fulfillment operations.
- Luxury:Limited-edition drops and scarcity-driven release calendars command premium realization. Dubai's logistics cluster enables rapid fulfillment of high-value inventory with elevated security protocols.
- Premium:Technology-forward specifications with athlete endorsement anchoring sustain price positioning above mid-tier alternatives.
- Mid-Range:Balanced quality-price positioning captures broad Gulf consumer base with moderate SKU breadth requirements.
- Budget:Synthetic mesh constructions face petrochemical feedstock volatility that compresses margin pools. South African value-tier operators struggle with last-mile fragmentation outside Johannesburg and Cape Town corridors.
Mid-range holds installed capacity. Luxury is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital footwear fulfillment infrastructure concentrates in Gulf urban clusters where logistics investment outpaces African market development. SAMR licensing compression in Saudi Arabia and Dubai's same-day delivery capabilities anchor regional throughput. Secondary African metros remain underserved by reliable courier networks.
United Arab Emirates
Dubai's logistics cluster enables same-day delivery expectations that lock consumer loyalty for platform operators. MOHAP and the Telecommunications and Digital Government Regulatory Authority enforce product authentication protocols that inflate compliance overhead for marketplace entrants. The emirate's fulfillment infrastructure supports luxury limited-edition drops with elevated security protocols.
Saudi Arabia
Young adult consumers drive mobile-first footwear purchases through brand-direct app ecosystems across Riyadh and Jeddah. SAMR's streamlined digital retail licensing compresses new entrant approval timelines materially. The regulatory framework reduces market entry friction for cross-border sellers while mandating consumer protection standards on return policies.
South Africa
Johannesburg and Cape Town anchor courier network concentration, leaving secondary metros with unreliable delivery windows. The Consumer Protection Act mandates material composition and country-of-origin labeling that elevates documentation burdens for cross-border sellers. Last-mile fragmentation outside primary corridors elevates return rates for value-tier operators.
Kenya
Nairobi exhibits underdeveloped digital footwear retail relative to smartphone penetration metrics, creating uncontested demand for early platform entrants. The country's national communications regulator oversees mobile commerce standards without specialized footwear authentication requirements. Urban logistics networks remain nascent compared to Gulf infrastructure benchmarks.
Middle East and Africa E-Commerce Footwear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower fulfillment footprints. The vendor base spans global sportswear conglomerates, regional fashion aggregators, and pure-play marketplace operators. Three archetypes dominate: brand-direct DTC platforms, multi-brand fashion aggregators, and horizontal e-commerce marketplaces. Geographic expansion and Arabic localization anchor competitive moves.
Among global sportswear conglomerates, Nike Inc. and Adidas AG exemplify the brand-direct archetype through localized Arabic storefronts. Namshi occupies a position within the regional fashion aggregator tier. These entities represent divergent approaches to bypassing traditional retail intermediaries.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Puma SE |
| Skechers USA, Inc. |
| LVMH Moët Hennessy Louis Vuitton |
| Jumia |
| Namshi |
| Noon.com |
| Ounass |
| Others |
Pricing and Supply Chain Analysis
Dubai's Jebel Ali logistics corridor compresses freight costs for Gulf-bound inventory while amplifying price differentiation between same-day-capable operators and standard-delivery alternatives. This infrastructure asymmetry concentrates supply chain power among platforms with bonded warehousing access, forcing value-tier sellers to absorb margin erosion or exit premium service zones.
Pricing Analysis
SAMR's consumer protection mandates dictate the pricing tier structure across Saudi digital footwear retail, embedding compliance overhead that stratifies offerings across premium, standard, and economy levels. Price differentiation rests on authentication certification depth and Arabic-language storefront investment, with luxury positioning absorbing regulatory costs most readily. Pricing pressure intensifies in budget tiers as petrochemical feedstock volatility compresses synthetic mesh margins. Value-tier buyers in South African secondary metros exhibit highest price sensitivity; Gulf youth segments demonstrate lowest sensitivity for limited-edition releases.
Supply Chain Analysis
Extended payment terms from Chinese and Vietnamese manufacturers dominate supplier-financing arrangements, stretching working capital cycles for mid-range operators. Geographic supply concentration centers on China for synthetic mesh uppers, Vietnam for EVA midsole components, and Italy for luxury leather inputs. Raw material dependencies tether procurement to petrochemical derivatives, natural rubber, and tanned hides. Single-source vulnerability runs through Chinese synthetic textile suppliers. Distribution runs through Dubai's bonded logistics cluster for Gulf markets and Johannesburg courier hubs for South African penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat derives from regulatory entrenchment: SAMR licensing compression and UAE authentication mandates create compliance barriers that favor scaled incumbents with dedicated fiscal and legal infrastructure.
For Market Incumbents: Build switching-cost moats through same-day fulfillment infrastructure lock-in across Dubai and Riyadh. Deepen vertical integration into last-mile courier networks to defend against marketplace disintermediation. Invest in Arabic-language virtual try-on technology to elevate platform-native engagement stickiness. Threat: Jumia and Noon.com horizontal expansion into fashion verticals.
For New Entrants and Emerging Players: Nairobi's underdeveloped digital footwear retail relative to smartphone penetration metrics represents the most penetrable entry point for platform operators. Kenyan urban logistics gaps favor asset-light marketplace models over capital-intensive fulfillment builds. Target influencer-driven social commerce discovery as the primary go-to-market angle for Gulf youth demographic capture.
For Investors and Strategic Acquirers: Regional fashion aggregators with established Arabic localization and Gulf logistics partnerships represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance scalability across fragmented national tax regimes. Monitor VAT harmonization progress across GCC states as the inflection signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Arabic Localization Investment | Native-language storefronts unlock conversion lift among UAE women consumers with strongest platform loyalty. |
| Same-Day Fulfillment Expansion | Dubai's logistics cluster enables delivery expectations that lock consumer loyalty and elevate switching costs. |
| Virtual Try-On Integration | AR sizing tools compress purchase confidence gaps for limited-edition drops with highest return friction. |
| Direct-to-Consumer Platform Launch | Brand-direct models bypass marketplace commissions and capture first-party behavioral data from Gulf youth. |
| Regulatory Technology Deployment | Multi-jurisdiction SKU management systems absorb SAMR and South African Consumer Protection Act documentation burdens. |
Research Methodology
A spread of perspectives from brand-direct platform executives, third-party logistics operators, SAMR regulatory affairs specialists, and Gulf retail category buyers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through UAE Telecommunications and Digital Government Regulatory Authority filings, Saudi customs trade data, and South African Consumer Protection Act enforcement records. Bottom-up demand modeling from smartphone penetration metrics and gym culture adoption rates triangulated against top-down market sizing from e-commerce platform transaction disclosures.
Demand-supply balance framing anchored the analytical approach across the analysis window. Segmentation dimensions modeled included product type tier, consumer demographic cluster, sales channel format, and brand positioning band. CAGRs derived from logistic curve fitting to mobile commerce penetration trajectories and urban logistics infrastructure investment cycles. Key inputs encompassed EVA midsole adoption rates in Gulf fitness centers and remote work normalization persistence in Dubai and Riyadh corporate environments.
Practitioners should monitor SAMR licensing timeline compression and UAE authentication protocol evolution for early signals of competitive entry barrier shifts. Forecasts embed assumptions regarding smartphone penetration saturation curves and petrochemical feedstock price stability. Macroeconomic volatility in Gulf sovereign wealth flows, regulatory divergence in African digital economy frameworks, or synthetic material substitution breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Running Shoes Market
Footwear
Sandals Market
Footwear
PVC Footwear Market
Footwear
Outdoor Trail Running Shoes Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Cowboy Boots Market
Footwear
Custom Shoes Market
Footwear
Cyber-Shoes Market
Footwear
Indian Footwear Market
Footwear
Europe Footwear Market
Footwear
US Slip Resistant Shoes Market
Footwear
Leather Footwear Market
Footwear
North America Footwear Market
Footwear
Chunky Sneaker Market
Footwear
Lace Up Boots Market