
 Refurbished Computer and Laptop Market | 2026-2036
Refurbished Computer and Laptop Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Computer and Laptop Market Outlook
Capital-intensity divergence between OEM refurbishment programs and marketplace aggregators is redrawing competitive boundaries in the sector. Dell Technologies Inc leverages direct-to-business refurbishment channels to sustain enterprise relationships, while Back Market competes through independent seller verification protocols. Amazon.com Inc anchors consumer volume through integrated logistics and certified pre-owned storefronts.
Refurbished computers and laptops comprise previously owned devices restored to functional specifications through component replacement, diagnostic testing, and cosmetic grading, typically achieving 80-85% of original performance metrics at 40-60% of new-equipment cost. Their primary commercial purpose centers on extending hardware lifecycles for budget-constrained organizations and sustainability-focused procurement policies. Laptops dominate product type revenue due to mobility requirements across corporate and student end user segments, while ISO Certified units command margin premiums over uncertified alternatives in institutional purchasing. Online Marketplaces represent the fastest-expanding distribution channel, though Direct Sales retains higher average transaction values in government and non-profit verticals.
FCC equipment authorization standards govern refurbished device resale in the United States, while the EU WEEE Directive and F-Gas Regulation shape collection targets and cooling system compliance across European refurbishment operations. Energy Star certification requirements influence product eligibility for federal procurement programs administered under U.S. executive sustainability mandates. Stakeholders must monitor evolving right-to-repair legislation in multiple jurisdictions, as repair access provisions directly determine component availability and refurbishment cost structures.
Market Dynamics
Enterprise Scope 3 emissions accounting under the EU Corporate Sustainability Reporting Directive is forcing IT procurement teams to quantify hardware lifecycle carbon, redirecting capital toward certified refurbishment programs and away from new-equipment purchasing.
Growth Catalysts
- CSRD Scope 3 Mandates:EU-based enterprises must report embodied carbon in IT assets, creating procurement pressure for refurbished alternatives with verified lifecycle data.
- Right-to-Repair Legislation:France's repairability index and pending EU-wide repair access laws expand component availability for independent refurbishers.
- Student Mobility Requirements:University IT departments in Germany, the United Kingdom, and the Netherlands source refurbished laptops to meet sustainability procurement targets while managing constrained capital budgets.
Market Restraints
- Component Supply Volatility:Memory and storage chip pricing fluctuations compress refurbishment margins when new-equipment OEMs secure priority allocation.
- Single-Source OEM Dependency:Proprietary firmware locks and diagnostic tool restrictions from original manufacturers limit third-party repair depth for certain laptop models.
- F-Gas Regulatory Compliance:EU F-Gas Regulation phase-down creates certification overhead for cooling system refurbishment in high-performance workstations.
Strategic Opportunities
- B2B Subscription Models:Device-as-a-service contracts incorporating refurbishment cycles generate recurring revenue streams from SME segments previously served by direct purchase.
- ISO 14001-Certified Operations:Environmental management certification unlocks public sector tender eligibility in Germany, France, and Italy where green procurement quotas apply.
- AI-Driven Grading Automation:Computer vision systems for cosmetic and functional assessment reduce labor cost per unit while standardizing quality tiers.
Industry Challenges
- Certification Timeline Compression:Energy Star and EPEAT recertification cycles for refreshed product lines create inventory holding costs and demand forecasting complexity.
- Skilled Diagnostic Labor Scarcity:Component-level repair expertise for motherboard rework and BGA soldering remains concentrated among aging technician cohorts in Eastern European refurbishment hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Computer and Laptop Market |
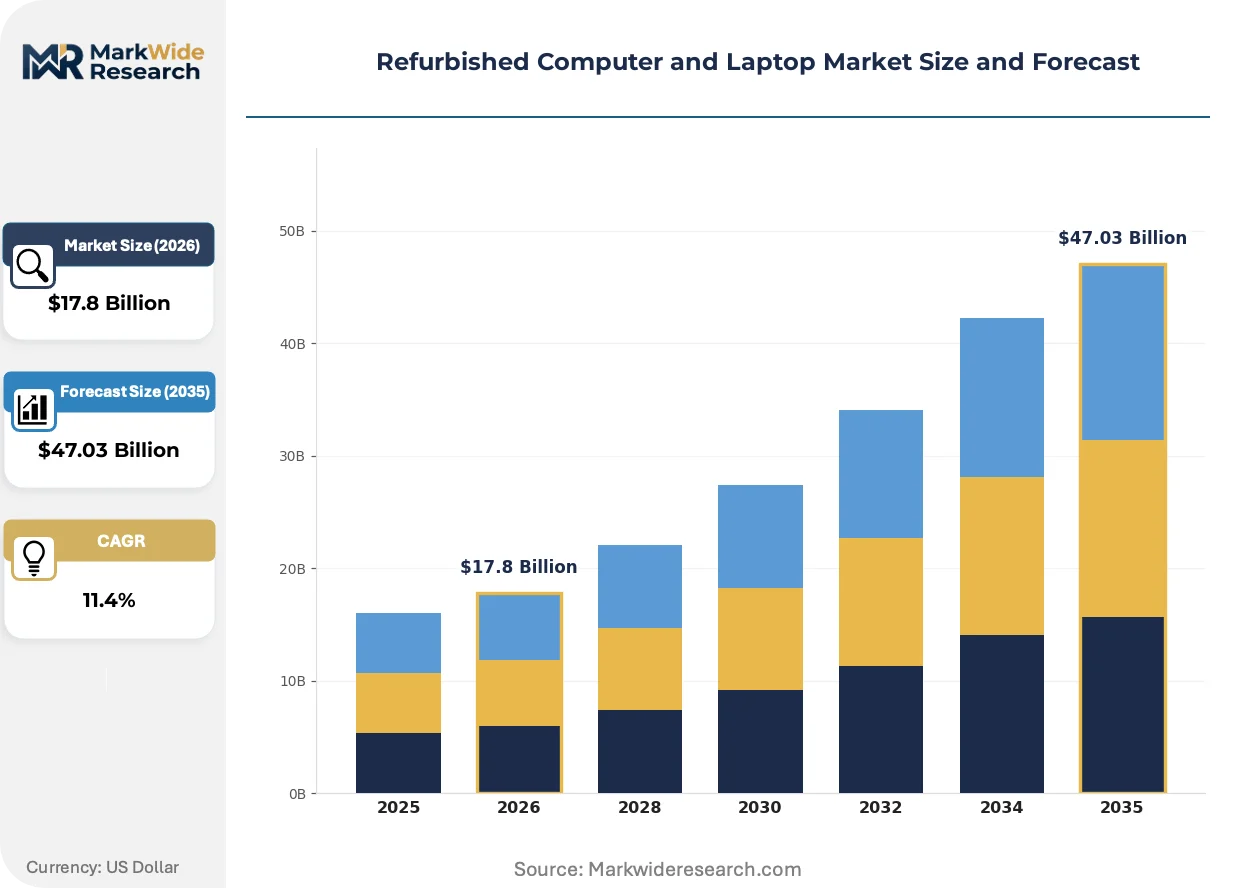
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $47.03 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
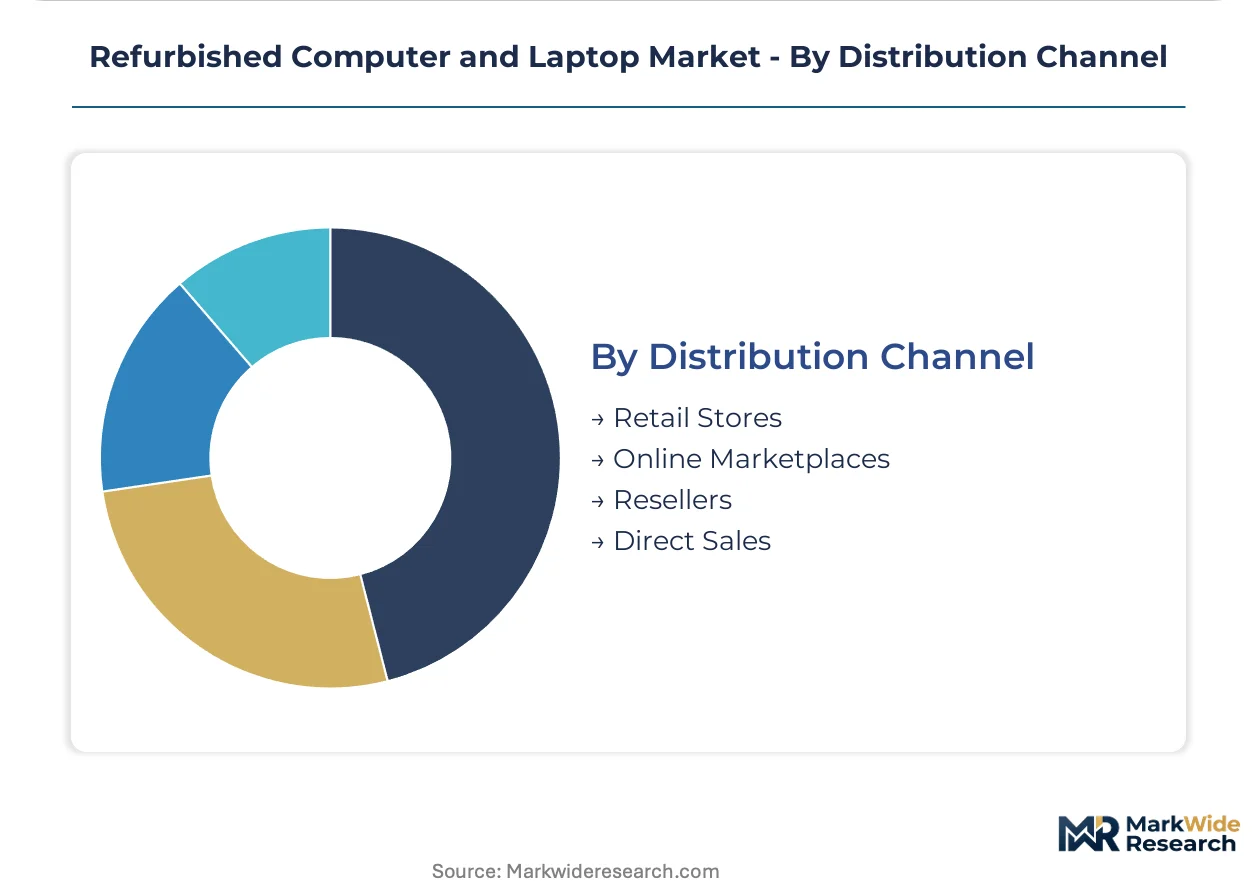
| Segmentation | Product Type: Desktops, Laptops, Notebooks, Workstations End User: Students, Corporates, Non-Profits, Government Certification: ISO Certified, UL Listed, CE Marked, Energy Star Distribution Channel: Retail Stores, Online Marketplaces, Resellers, Direct Sales |
| Companies Covered | Hewlett-Packard Development Company, Walmart Inc, Amazon.com Inc, eBay Inc, Best Buy Co. Inc, Dell Technologies Inc, Lenovo Group Limited, Back Market, Apple Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Computer and Laptop Market Strategic Shifts
Automation in quality grading and blockchain-based provenance tracking are compressing transaction friction between independent refurbishers and institutional buyers. These shifts reduce information asymmetry and enable scale in previously fragmented supply chains.
Automated optical inspection systems for cosmetic grading are supplanting manual technician assessment in high-volume refurbishment facilities. Enterprise IT asset disposition vendors deploy these systems to process thousands of units daily with consistent grading outcomes. This compression of labor input per unit enables margin expansion in price-competitive B2B segments.
The EU WEEE Directive's revised collection targets and extended producer responsibility provisions reshape logistics infrastructure for device recovery. Refurbishment operators must now integrate with formal take-back schemes rather than informal collection networks. Germany's ElektroG implementation imposes strict documentation requirements that favor ISO-certified processors over uncertified competitors.
Enterprise procurement teams now mandate certified pre-owned equipment in RFP specifications, displacing open-market purchasing from uncertified aggregators. Financial services and healthcare verticals in the United Kingdom and the Netherlands lead this specification tightening. This preference compression concentrates volume with operators holding R2 or e-Stewards certification, marginalizing smaller marketplace sellers.
Refurbished Computer and Laptop Market Segmentation

Segmentation in refurbished electronics reveals how certification tiers and channel economics fragment procurement behavior. Buyers optimize across warranty depth, carbon disclosure requirements, and total cost of ownership rather than headline price alone.
Product Type:
FCC equipment authorization and EU WEEE Directive compliance requirements diverge sharply between stationary and mobile form factors, reshaping refurbishment economics.
- Laptops:Portable devices with integrated displays and batteries dominate procurement volume across education and enterprise mobility programs. German universities and Dutch healthcare systems source certified refurbished units to meet CSRD Scope 3 reporting obligations while managing fleet refresh cycles. Battery replacement and hinge mechanism refurbishment constitute the primary cost drivers in quality grading.
- Desktops:Tower and small-form-factor units offer modular component architecture that extends technical lifecycles through successive upgrades. US federal agencies procure Energy Star-certified refurbished desktops under executive sustainability mandates, prioritizing standardized motherboard form factors that simplify spare parts logistics. Corporate call centers in India leverage these units for cost-controlled seat expansion.
- Notebooks:Ultraportable form factors with sealed designs present higher refurbishment complexity due to soldered memory and storage configurations. Apple MacBook and Microsoft Surface device recovery programs concentrate in specialized facilities with proprietary diagnostic tool access.
- Workstations:High-performance units with discrete graphics and ECC memory serve engineering and media production verticals where thermal management refurbishment adds certification overhead under EU F-Gas Regulation.
Laptops handle the majority of throughput; workstations are expanding most quickly on share as AI training workloads extend hardware replacement cycles.
End User:
Procurement sophistication varies dramatically across buyer categories, with institutional RFP specifications now mandating certified pre-owned equipment in place of open-market sourcing.
- Corporates:Enterprise IT asset disposition programs integrate refurbishment into circular economy targets under EU Corporate Sustainability Reporting Directive requirements. Financial services firms in the United Kingdom and technology companies in Ireland specify R2 or e-Stewards certification for data security assurance. Device-as-a-service contracts incorporate refurbishment cycles into recurring revenue structures.
- Students:University IT departments in Germany, the United Kingdom, and the Netherlands balance sustainability procurement quotas against constrained capital budgets through certified refurbished laptop programs. Semester-based refresh cycles create predictable demand seasonality.
- Government:Federal and state agencies in the United States enforce Energy Star and EPEAT certification requirements under executive orders. Procurement contracts favor direct sales channels with established supply chain security clearances.
- Non-Profits:Grant-funded organizations prioritize acquisition cost minimization over certification depth, often sourcing through reseller networks with limited warranty terms. Digital inclusion programs in France and Spain distribute refurbished units to underserved populations.
Corporates command the highest certification premiums; students are gaining share fastest as education sector sustainability mandates tighten.
Certification:
Third-party validation tiers create price stratification that directly determines tender eligibility in public sector procurement.
- ISO Certified:Environmental management system certification under ISO 14001 unlocks public sector tender participation in Germany, France, and Italy where green procurement quotas apply. Certified processors document chain-of-custody for WEEE Directive compliance, commanding margin premiums over uncertified competitors.
- Energy Star:US EPA certification for energy efficiency qualifies refurbished equipment for federal procurement programs and utility rebate schemes. Recertification timelines for refreshed product lines create inventory holding costs that disadvantage smaller operators.
- CE Marked:European conformity marking for safety and electromagnetic compatibility enables cross-border trade within the single market. Technical documentation requirements favor established refurbishment facilities with dedicated compliance staff.
- UL Listed:North American safety certification from Underwriters Laboratories addresses fire and electrical hazard concerns in commercial insurance underwriting. Corporate risk management departments specify UL listing for facility deployment approvals.
ISO Certified operations capture institutional volume; CE Marked units are climbing the fastest as intra-EU trade accelerates.
Distribution Channel:
Channel selection determines average transaction value, warranty depth, and buyer relationship continuity in fragmented supply chains.
- Online Marketplaces:Aggregator platforms with independent seller verification protocols compress transaction friction for price-sensitive consumers. Back Market and Amazon certified pre-owned storefronts standardize grading taxonomies across dispersed supplier bases.
- Direct Sales:Manufacturer-controlled refurbishment channels sustain enterprise relationships through integrated logistics and extended warranty terms. Dell Technologies leverages direct-to-business programs to defend account retention against marketplace competitors.
- Resellers:Regional value-added distributors provide localized technical support and configuration services for SME segments. These intermediaries aggregate inventory from multiple refurbishment sources to meet diverse specification requirements.
- Retail Stores:Physical inspection availability supports consumer confidence in cosmetic grading assessments. Big-box electronics retailers in the United States and specialized circular economy shops in France maintain limited refurbished assortments.
Online Marketplaces handle the majority of unit volume; Direct Sales are expanding most quickly on share as enterprise procurement consolidates with certified operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in refurbished computing hardware tilt toward import-dependent markets with stringent circular economy mandates. Germany and the Netherlands post sustained trade deficits in secondary IT equipment, sourcing volume from UK and US asset recovery programs. Export capacity concentrates in facilities with R2 and e-Stewards certification that satisfy cross-border due diligence requirements.
Germany
Enterprise procurement teams at Deutsche Bank and Siemens drive certified pre-owned laptop volume through ISO 14001-mandated tenders. The ElektroG implementation imposes strict WEEE Directive documentation requirements that favor established processors in Berlin-Brandenburg. Refurbishment clusters in North Rhine-Westphalia handle bulk enterprise asset disposition from Ruhr industrial legacy infrastructure.
United States
Federal agencies under executive sustainability mandates procure Energy Star-certified refurbished desktops through GSA schedules. FCC equipment authorization standards govern interstate resale compliance. Dell Technologies anchors direct-to-business refurbishment capacity in Round Rock, Texas, while Amazon certified pre-owned storefronts aggregate marketplace volume from independent sellers nationwide.
United Kingdom
Financial services firms in London specify R2 certification for data security assurance in IT asset disposition contracts. The UK Environment Agency enforces WEEE regulations with post-Brexit divergence from EU collection targets. Refurbishment operators in the Midlands cluster serve NHS sustainability procurement quotas with ISO-certified laptop programs.
Netherlands
Amsterdam-based circular economy startups partner with university IT departments to meet CSRD Scope 3 reporting obligations through verified refurbishment sourcing. The Dutch national implementation of extended producer responsibility mandates formal take-back scheme integration. Rotterdam logistics hubs facilitate re-export of processed units to German and Belgian institutional buyers.
France
The repairability index mandates disclosure of component accessibility scores for laptops sold in domestic markets. ANSM and CNIL oversight extends to data sanitization protocols in enterprise asset recovery. Refurbishment specialists in the Île-de-France region leverage proximity to Paris-headquartered corporate sustainability teams pursuing circular economy targets.
Refurbished Computer and Laptop Market Competitive Environment
Concentration sits with OEM-controlled refurbishment programs that leverage direct enterprise relationships against marketplace aggregators. The vendor base splits between manufacturer-captive channels and independent platforms with seller verification protocols. Two strategic archetypes dominate: integrated OEM refurbishers with warranty depth and aggregator marketplaces with price compression. Competitive moves center on certification portfolio expansion and geographic seller base densification.
Within the OEM-captive tier, Dell Technologies Inc and Hewlett-Packard Development Company exemplify direct-to-business models with extended warranty terms and integrated logistics. Amazon.com Inc anchors the aggregator archetype through certified pre-owned storefronts that standardize grading taxonomies across dispersed supplier bases. Back Market occupies a position between these poles with independent seller verification protocols that reduce transaction friction for price-sensitive segments.
| Leading Market Players |
|---|
| Hewlett-Packard Development Company |
| Walmart Inc |
| Amazon.com Inc |
| eBay Inc |
| Best Buy Co. Inc |
| Dell Technologies Inc |
| Lenovo Group Limited |
| Back Market |
| Apple Inc |
| Others |
Value Chain & Pricing Dynamics
ISO 14001 environmental management certification gates both supply qualification and price differentiation in institutional procurement, forcing refurbishment operators to absorb compliance overhead while capturing margin premiums in German and French public tenders. Enterprise buyers simultaneously demand verified carbon disclosure and extended warranty terms, compressing uncertified competitors into consumer price tiers.
Pricing Analysis
Enterprise IT procurement teams anchor the three-tier pricing structure across premium, standard, and economy levels, with ISO-certified units commanding substantial premiums over uncertified alternatives in institutional RFPs. Price differentiation rests on certification depth and warranty duration rather than hardware specifications alone. Cost compression in the economy tier intensifies because memory and storage chip volatility erodes refurbishment margins when OEMs secure priority component allocation. Non-profit segments exhibit highest price sensitivity, while financial services firms in the United Kingdom demonstrate lowest sensitivity due to data security mandates.
Supply Chain Analysis
Inventory holding periods for Energy Star and EPEAT recertification cycles extend working capital requirements, creating lead-time disadvantages for smaller operators against Dell Technologies and Hewlett-Packard captive channels. Supply concentrates in the United States, Germany, and the United Kingdom, where asset recovery programs feed refurbishment facilities with enterprise fleet retirements. Raw material dependencies include NAND flash memory, lithium-ion battery cells, and precision hinge mechanisms. Single-source OEM dependency for proprietary diagnostic tools creates vulnerability when manufacturers restrict firmware access. Distribution runs through direct sales channels for government and enterprise verticals, while online marketplaces aggregate fragmented consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Device-as-a-service subscription models represent a service-attach opportunity expanding faster than hardware transactions, with recurring revenue streams from SME segments previously served by direct purchase. Warranty extensions and end-of-life asset recovery contracts deepen customer lifetime value beyond initial equipment acquisition.
For Market Incumbents: Consolidate certification portfolios to defend enterprise relationships against marketplace aggregators with price compression tactics. Expand ISO 14001-certified processing capacity in North Rhine-Westphalia to capture German ElektroG-mandated volume. Deepen backward integration into component testing and battery replacement to reduce third-party diagnostic dependency.
For New Entrants and Emerging Players: Lead with AI-driven grading automation to reduce labor cost per unit and standardize quality tiers for price-sensitive student segments. Target Netherlands university IT departments with semester-based refresh cycles and verified carbon disclosure for CSRD Scope 3 compliance. Deploy blockchain-based provenance tracking to reduce information asymmetry with institutional buyers.
For Investors and Strategic Acquirers: The EU Corporate Sustainability Reporting Directive reshapes the acquisition landscape by concentrating procurement volume with certified operators holding documented chain-of-custody capabilities. Long-term viability favors facilities with R2 or e-Stewards certification serving financial services and healthcare verticals. Monitor right-to-repair legislation progression as the signal indicating component availability expansion for independent refurbishers.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | ISO 14001 and R2 certification unlocks German public sector tenders under ElektroG mandates. |
| AI-Driven Quality Grading Deployment | Automated optical inspection reduces labor input per unit in high-volume B2B processing facilities. |
| Device-as-a-Service Launch | Subscription contracts incorporating refurbishment cycles capture SME recurring revenue previously lost to direct purchase. |
| Blockchain Provenance Integration | Immutable chain-of-custody records satisfy enterprise data security requirements in UK financial services procurement. |
| Component-Level Repair Capability Buildout | Motherboard rework and BGA soldering expertise addresses skilled diagnostic labor scarcity in Eastern European hubs. |
Study Parameters
A standing panel of enterprise IT asset disposition managers, refurbishment facility operators, university procurement officers, and compliance auditors provided ongoing calibration across primary research phases. Secondary validation drew from EPA Energy Star certification databases, EU WEEE Directive implementation reports, SEC filings of listed electronics retailers, and German ElektroG compliance documentation. Bottom-up unit economics from refurbishment facilities triangulated against top-down procurement spend estimates from institutional buyers.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across product type, end user category, certification tier, and distribution channel, with additional dimensioning by regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating enterprise fleet refresh cycles, student mobility requirements, and sustainability procurement mandate adoption curves. Forecast inputs included component supply lead times, certification timeline compression effects, and skilled technician cohort demographics.
Forecasts assume regulatory continuity in EU CSRD implementation, US executive sustainability mandates, and German ElektroG enforcement; material policy shifts would require re-modeling. Revision becomes warranted when right-to-repair legislation crosses implementation thresholds or when memory chip pricing volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Nanopresso Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
FMCG Market
Consumer Electronics
Dual Screen Laptops Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
DVD Remote Controls Market