
 Electronics Accessories Market | 2026-2036
Electronics Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Electronics Accessories Market Analysis
Semiconductor packaging engineer shortages in East Asia are unwinding production schedules for advanced charging ICs. Apple Inc. leverages captive silicon design to buffer against foundry bottlenecks, while Anker Innovations sustains aggressive SKU proliferation through Shenzhen-based vertical integration. Samsung Electronics anchors premium wireless charging pad output with in-house coil manufacturing capacity.
Electronics accessories encompass passive and active peripheral components that extend, protect, or enhance host device functionality, typically incorporating copper alloy conductors, lithium-ion or gallium nitride power semiconductors, and thermoplastic polyurethane or polycarbonate enclosures fabricated through injection molding and PCB surface-mount assembly. Cables and chargers generate the largest revenue pools due to universal replacement cycles, though screen protectors command higher per-unit margins in premium tiers. Fast charging and wireless features now attract disproportionate engineering investment as OEMs differentiate through power delivery speeds and magnetic alignment ecosystems.
REACH substance restrictions in Europe and the EU Ecodesign for Sustainable Products Regulation constrain halogenated flame retardants and mandate repairability disclosures, while the US FCC governs electromagnetic interference certification for wireless accessories. India's BIS compulsory registration order for electronic goods blocks non-compliant imports at ports, forcing pre-certification investments. Stakeholders must monitor how fragmented national charger standard mandates reshape regional product portfolios and inventory complexity.
Market Dynamics
Semiconductor packaging bottlenecks in East Asia are compressing production schedules for gallium nitride charging ICs, forcing accessory manufacturers to redesign power architectures around available foundry capacity rather than optimal performance specifications.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandates repairability disclosures and material traceability, creating certified premium tiers that command price premiums from sustainability-conscious buyers in Germany and France.
- Smartphone refresh compression:Emerging market consumers in India and Indonesia now replace devices every 18-24 months, accelerating cable and charger replacement cycles at faster velocities than host device obsolescence.
- Gallium nitride semiconductors:Enable 65W+ chargers in palm-sized form factors, unlocking new product categories in travel and automotive accessory segments previously constrained by thermal and size limitations.
Market Restraints
- Copper and rare earth price volatility:Coil winding and connector manufacturing face margin compression when London Metal Exchange copper futures swing beyond hedging bandwidths.
- East Asian foundry concentration:Advanced GaN-on-silicon capacity clusters in Taiwan and South Korea, exposing charging IC supply to single-point geopolitical disruptions.
- Wireless charging efficiency ceilings:Qi protocol power transfer losses cap practical charging speeds below 50W, limiting wireless pad displacement of cabled solutions in power-user segments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives covering chargers and cables reduce landed cost disadvantages for domestic assembly versus Shenzhen-sourced imports.
- Magnetic alignment ecosystems:Proprietary coil positioning systems from Apple and competitors create attachment hardware categories with recurring accessory purchase patterns.
- Direct-to-consumer channel expansion:Brand-owned storefronts and subscription replenishment models bypass Amazon and retail distributor margin stacking in North American and European markets.
Industry Challenges
- Electromagnetic compatibility certification backlog:FCC Part 15 testing queues in US laboratories extend wireless accessory launch timelines by 8-12 weeks beyond hardware readiness.
- Multi-standard inventory complexity:Fragmented national charger mandates in Brazil, India, and the EU force SKU proliferation that strains forecasting accuracy and working capital efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronics Accessories Market |
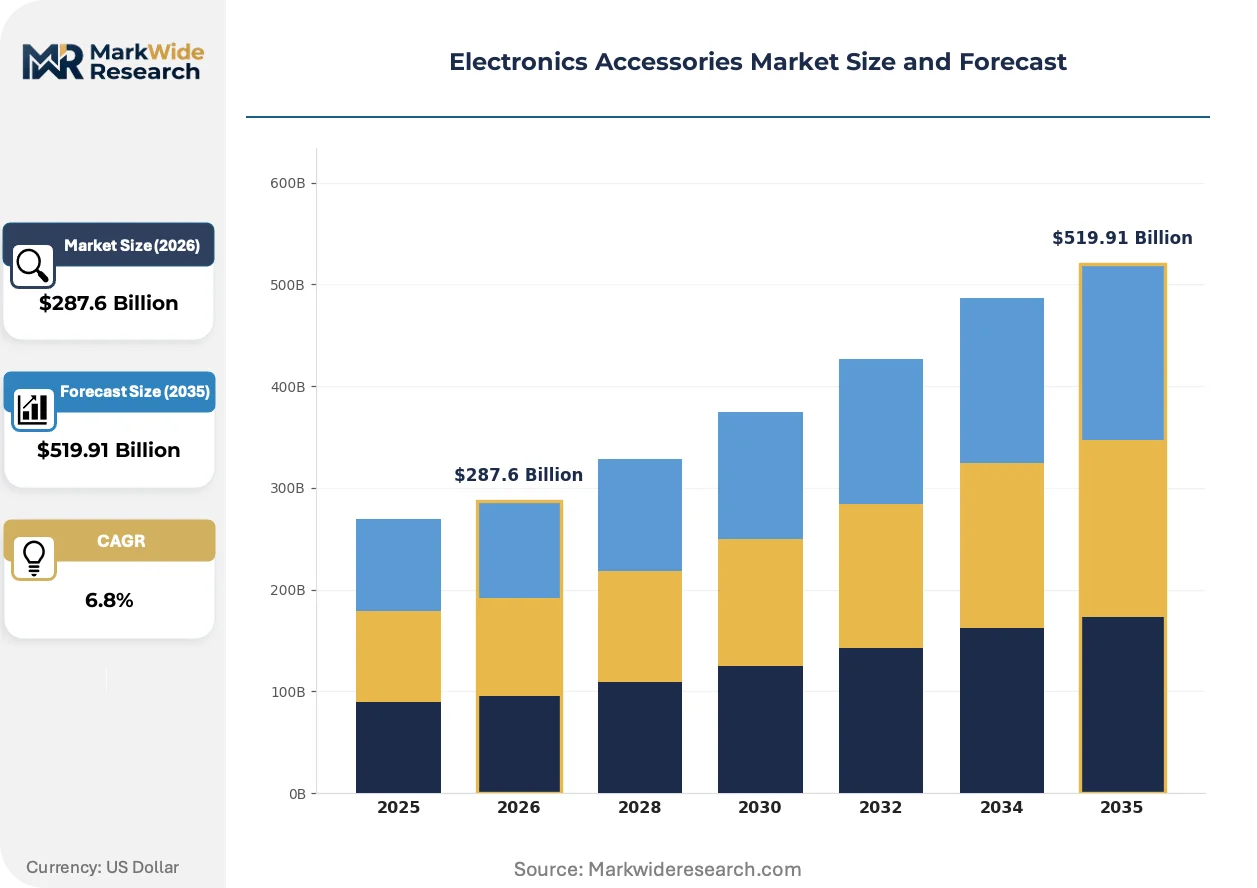
| Market Size in 2026 | $287.6 Billion |
| Market Size in 2035 | $519.91 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Chargers, Cases, Screen Protectors Feature: Wireless, Waterproof, Fast Charging, Noise Cancelling End User: Consumers, Businesses, Education, Healthcare Distribution Channel: Online Retail, Brick-and-Mortar, Distributors, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics, Sony Corporation, Logitech International, Anker Innovations, Belkin International, Bose Corporation, Xiaomi Corporation, HP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronics Accessories Market Emerging Trajectories
Power semiconductor architecture and regulatory material restrictions are jointly rewriting accessory design specifications, while procurement behavior shifts toward certified-sustainable and regionally-compliant sourcing.
Gallium nitride power ICs are displacing silicon MOSFETs in charger designs above 30W output. Premium smartphone OEMs and business-travel accessory buyers now specify GaN-based adapters as standard equipment. This displacement compresses bill-of-materials footprints by 40% while enabling multi-port configurations previously thermally infeasible.
REACH substance restrictions and RoHS recast directives are eliminating halogenated flame retardants from cable jacketing and enclosure plastics. European manufacturers are reformulating thermoplastic polyurethane compounds with phosphorus-based alternatives at higher raw material cost. The B2B procurement channel shows strongest compliance acceleration, with enterprise IT buyers in Germany and the Netherlands now requiring full material disclosure documentation.
Repairability scoring mandates are altering product architecture decisions. Design-for-disassembly requirements in France and forthcoming EU-wide rules force modular cable strain relief and replaceable connector tips. Aftermarket service providers in Paris and Berlin are building certification programs around these repairability tiers, creating preference segmentation that rewards brands with documented spare parts availability.
Electronics Accessories Market Segmentation
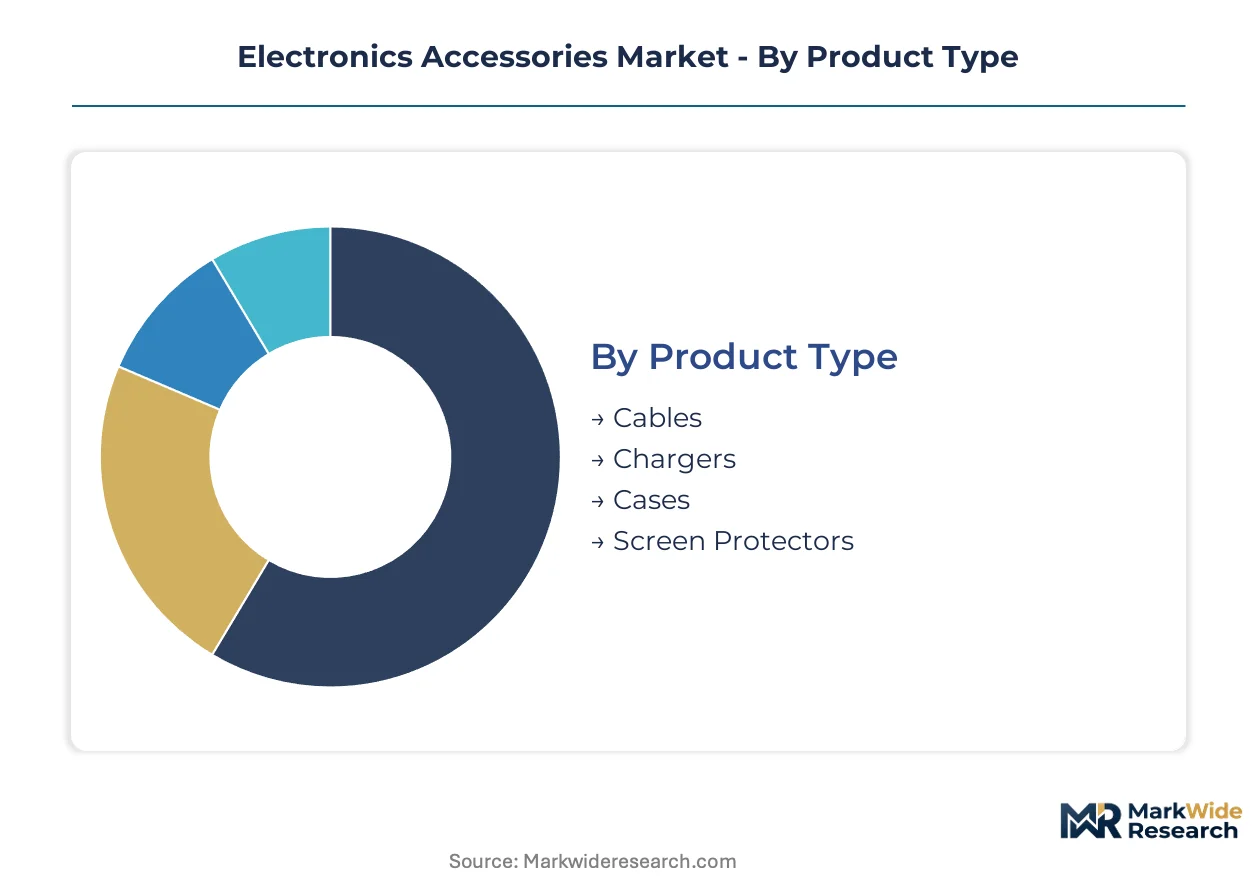
Electronics accessories segment along four intersecting dimensions that determine pricing power, replacement velocity, and channel economics. Product type and feature specifications dominate engineering investment, while end-user identity and distribution channel shape margin capture and working capital intensity.
Product Type:
Substitution pressure runs strongest through charging and connectivity segments, where protocol shifts and connector obsolescence accelerate replacement cycles faster than physical wear.
- Cables:Copper-alloy conductors with thermoplastic polyurethane or braided nylon jacketing terminate in USB-C, Lightning, or proprietary connectors. Demand concentrates in India and Indonesia, where smartphone refresh compression to 18-24 month cycles outpaces cable durability. USB-IF certification requirements and regional connector mandates force SKU proliferation that strains inventory forecasting.
- Chargers:Gallium nitride power semiconductors enable 65W+ output in palm-sized form factors, displacing silicon MOSFETs above 30W specifications. Germany and France show strongest procurement acceleration for GaN-based adapters among business-travel segments, with enterprise IT buyers requiring full material disclosure documentation under REACH substance restrictions.
- Cases:Polycarbonate or thermoplastic polyurethane enclosures fabricated through injection molding provide impact protection and aesthetic customization. Procurement concentrates through Amazon and brand-owned storefronts in North American markets.
- Screen Protectors:Tempered glass or polyethylene terephthalate films with oleophobic coatings command higher per-unit margins in premium tiers. Replacement cycles track screen damage incidence rather than device obsolescence.
Cables retain volume leadership; chargers hold the steepest expansion curve.
Feature:
Cost tier stratification separates premium engineering investments from commoditized baseline specifications, with power delivery and audio cancellation commanding the widest price spreads.
- Fast Charging:Power Delivery and Quick Charge protocol implementations above 30W require GaN semiconductors and thermal management systems. Enterprise procurement in the Netherlands and Germany prioritizes certified adapters with repairability disclosures under EU Ecodesign for Sustainable Products Regulation.
- Wireless:Qi protocol coil assemblies with magnetic alignment systems create attachment hardware categories with recurring purchase patterns. Thermal efficiency ceilings below 50W limit displacement of cabled solutions in power-user segments.
- Waterproof:IP67 or IP68 ingress protection ratings require gasket engineering and hydrophobic coating applications. Outdoor and industrial end-use in construction and field services drives specification requirements.
- Noise Cancelling:Active noise cancellation DSP implementations in headphone and earbud accessories command premium positioning. Business traveler and remote worker segments in France and Germany show strongest adoption velocity.
Fast charging dominates revenue contribution; wireless features gain share fastest in travel and automotive segments.
End User:
Application-driven demand splits between individual replacement cycles and institutional procurement programs with divergent compliance and volume requirements.
- Consumers:Individual replacement purchases driven by device refresh, damage, or aesthetic preference. Direct-to-consumer channels and subscription replenishment models bypass retail distributor margin stacking.
- Businesses:Enterprise IT procurement programs require REACH compliance documentation and repairability scoring. B2B buyers in Germany and the Netherlands mandate full material disclosure and modular design-for-disassembly architectures.
- Education:K-12 and higher education bulk purchasing programs prioritize durability and standardized charging specifications. Volume contracts strain supplier working capital through extended payment terms.
- Healthcare:Medical device accessory requirements demand IEC 60601 compliance for electromagnetic compatibility and isolation. Procurement runs through specialized distributors with regulatory certification capabilities.
Consumers anchor absolute volume; healthcare segments expand most quickly on compliance-driven specification upgrades.
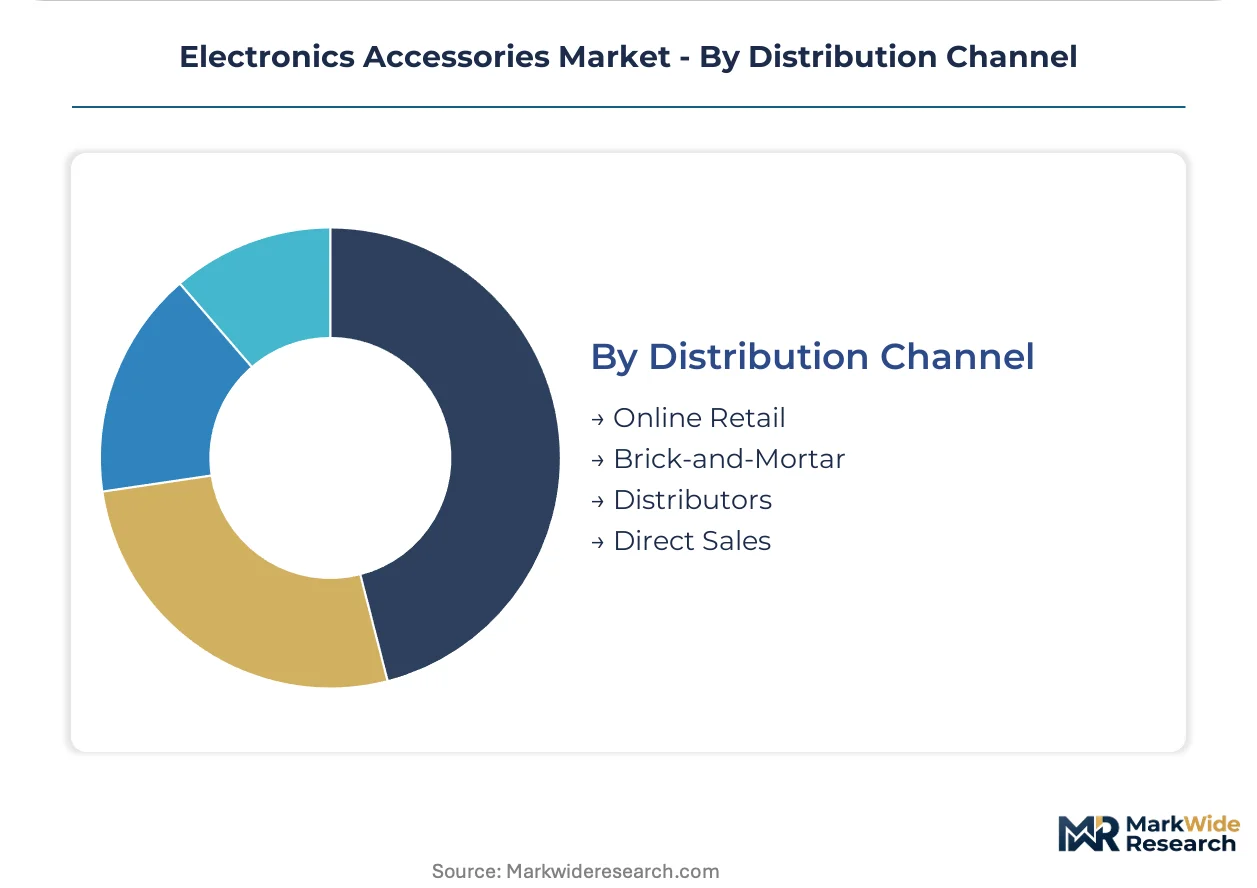
Distribution Channel:
Customer type determines margin capture, with direct relationships preserving pricing power against platform and retail intermediaries.
- Online Retail:Amazon marketplace and regional e-commerce platforms aggregate demand with margin compression through fee structures and price transparency. Inventory velocity requirements strain smaller manufacturers.
- Brick-and-Mortar:Electronics specialty retailers and carrier stores provide tactile evaluation and immediate fulfillment. Shelf space negotiations favor brands with SKU breadth and marketing co-investment.
- Distributors:Ingram Micro and regional wholesalers aggregate institutional demand with credit extension and logistics services. Working capital intensity limits participation to established suppliers.
- Direct Sales:Brand-owned storefronts and subscription replenishment models preserve margin and capture behavioral data. Apple and Anker Innovations sustain aggressive channel investment to reduce platform dependency.
Online retail captures the largest transaction volume; direct sales channels climb the fastest on margin preservation objectives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements in India are redirecting manufacturing investment away from Shenzhen-sourced imports toward domestic assembly operations. The EU Ecodesign for Sustainable Products Regulation is fragmenting product portfolios across Germany and France with repairability mandates. China's MIIT standards and gallium nitride foundry concentration in Taiwan create parallel supply risks for charging IC procurement.
India
Smartphone refresh compression to 18-24 month cycles accelerates cable and charger replacement velocity beyond device obsolescence. The PLI scheme for electronics manufacturing reduces landed cost disadvantages for domestic assembly versus Chinese imports. Tamil Nadu and Karnataka industrial corridors attract Foxconn and Dixon Technologies facilities for charger and cable production serving both domestic demand and export markets.
Germany
Enterprise IT procurement programs prioritize GaN-based adapters with full REACH compliance documentation and material traceability. The EU Ecodesign for Sustainable Products Regulation mandates repairability disclosures that force modular cable strain relief designs. Berlin and Munich aftermarket service providers build certification programs around documented spare parts availability tiers.
United States
FCC Part 15 testing queues extend wireless accessory launch timelines by 8-12 weeks beyond hardware readiness. The Inflation Reduction Act's domestic content provisions create procurement preferences for North American-assembled charging hardware. Austin and Dallas-Fort Worth logistics hubs aggregate direct-to-consumer fulfillment operations bypassing Amazon margin structures.
China
MIIT national charger standard mandates and GB certification requirements fragment export-oriented product portfolios. Shenzhen vertical integration sustains aggressive SKU proliferation through in-house PCB surface-mount and injection molding capacity. Dongguan and Guangzhou coil winding clusters supply magnetic alignment ecosystems for proprietary positioning systems.
France
Repairability scoring mandates alter product architecture toward design-for-disassembly with replaceable connector tips. ANSM and CNIL oversight extends to material disclosure requirements for B2B procurement channels. Paris aftermarket certification programs create preference segmentation rewarding brands with documented spare parts availability and modular strain relief systems.
Electronics Accessories Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive silicon design and in-house coil manufacturing distinguishing premium positioning from contract-dependent competitors. The vendor base compresses around three strategic archetypes: semiconductor-integrated OEMs with captive foundry relationships, Shenzhen-based vertically integrated specialists, and brand-licensed electronics aggregators. Competitive moves concentrate on M&A for GaN semiconductor access and geographic expansion into India PLI-subsidized manufacturing zones.
Within the integrated OEM tier, Apple Inc. and Samsung Electronics exemplify semiconductor-captive positioning with in-house silicon design buffering against foundry bottlenecks. Anker Innovations occupies a position among Shenzhen-based specialists leveraging regional vertical integration for SKU breadth. These three anchors represent divergent responses to East Asian packaging engineer shortages: captive silicon, in-house coil manufacturing, and aggressive supply chain localization respectively.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Sony Corporation |
| Logitech International |
| Anker Innovations |
| Belkin International |
| Bose Corporation |
| Xiaomi Corporation |
| HP Inc. |
| Others |
Supply Flow & Price Mechanics
Inventory compression to 45-60 days of gallium nitride charging IC stock is concentrating pricing power with Taiwan and South Korea foundries while forcing accessory manufacturers into premium tier positioning to recover margin. This lead-time bandwidth directly shapes how brands architect cost recovery across USB-C cable, wireless charging pad, and GaN adapter portfolios.
Pricing Analysis
Price spreads between Shenzhen-sourced and India PLI-assembled chargers now exceed material cost differentials alone, reflecting BIS certification premiums and logistics arbitrage. Three-tier pricing structure across premium, standard, and economy levels stratifies by GaN semiconductor inclusion and REACH compliance documentation, with enterprise IT buyers in Germany and the Netherlands least sensitive to unit cost. Pricing pressure stems from copper and rare earth volatility compressing coil winding margins, while consumer segments in India and Indonesia exhibit highest price elasticity on replacement cable purchases.
Supply Chain Analysis
Taiwan and South Korea anchor gallium nitride-on-silicon wafer fabrication, while China clusters PCB surface-mount assembly and injection molding for thermoplastic polyurethane enclosures. Raw material flows draw from Chilean copper concentrate, Australian rare earth processing, and Saudi petrochemical feedstocks for cable jacketing polymers. Single-source vulnerability concentrates in advanced packaging capacity for charging ICs, with distribution running through Shenzhen wholesale hubs, Ingram Micro regional nodes, and brand-owned direct-to-consumer fulfillment centers in Austin and Dallas-Fort Worth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as gallium nitride semiconductor penetration in charging accessories accelerates replacement velocity beyond host device obsolescence, with business-travel and enterprise IT procurement driving premium tier adoption faster than commoditized baseline segments.
For Market Incumbents: Shield premium positioning by deepening backward integration into coil winding and magnetic alignment system production, countering Shenzhen-based SKU proliferation threats. Prioritize captive GaN semiconductor sourcing partnerships to buffer East Asian foundry bottlenecks, while investing in BIS pre-certification infrastructure to capture India PLI scheme benefits before competitor entry saturates domestic assembly capacity. For New Entrants and Emerging Players: Differentiate on repairability-scored product architectures with modular strain relief and replaceable connector tips, targeting France and Germany enterprise procurement channels where EU Ecodesign for Sustainable Products Regulation mandates create compliance-based preference segmentation. Penetrate the aftermarket service provider ecosystem in Paris and Berlin with documented spare parts availability programs as the primary go-to-market wedge. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because semiconductor-integrated OEMs with captive silicon design will absorb contract-dependent competitors as foundry access becomes the decisive capability. Target acquisition profiles emphasize GaN charging IC design houses and India-based EMS providers with PLI-registered facilities. The signal to watch is FCC Part 15 testing queue compression, which would indicate regulatory capacity expansion enabling faster wireless accessory launch velocity and margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive IC design buffers Taiwan foundry bottlenecks for Anker and Apple tier competitors. |
| India PLI Manufacturing Footprint | Tamil Nadu assembly reduces BIS certification delays versus Shenzhen-sourced import models. |
| Repairability Certification Investment | France ANSM-aligned scoring unlocks enterprise IT procurement preference in EU Ecodesign tiers. |
| Direct-to-Consumer Channel Expansion | Brand-owned storefronts bypass Amazon fee structures and capture behavioral data in North America. |
| Magnetic Alignment Ecosystem Development | Proprietary coil positioning systems create recurring attachment hardware purchase patterns. |
Methodological Framework
The analysis maps charging accessories, connectivity peripherals, protective enclosures, and audio enhancement segments, each validated through procurement directors at enterprise IT departments, category managers at electronics retailers, semiconductor packaging engineers, and regulatory compliance officers across Germany, India, and the United States. Primary interview findings triangulate against customs trade data, BIS registration databases, FCC equipment authorization filings, and EU Ecodesign repairability scoring documentation, with bottom-up SKU-level builds cross-checked against top-down industry association aggregates.
Consistency checks validate volume and value outputs against external benchmarks including semiconductor foundry capacity disclosures, copper futures trading patterns, and regional e-commerce platform transaction velocities across the analysis window. Segmentation models incorporate product type, power delivery specification, end-user procurement program, and distribution channel economics, with CAGRs derived from replacement cycle compression rates, GaN penetration curves, and regulatory compliance cost trajectories rather than extrapolated historical trends.
Decision-makers should treat outputs as directional under sustained gallium nitride foundry concentration and fragmented national charger standard mandates; material deviation in Taiwan geopolitical stability or EU Ecodesign enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in BIS certification queue lengths, REACH substance restriction amendments, and India PLI scheme renewal terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Airport Retailing Consumer Electronics Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Bluetooth Headphones Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
Headphones Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Armenia Consumer Goods Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
4K Television Market
Consumer Electronics
Keycap Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market