
 Fat Free Peanut Butter Market | 2026-2036
Fat Free Peanut Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Free Peanut Butter Market Analytics
Supermarket private-label consolidation is decoupling volume from branded premiums as chain buyers extract slotting concessions and co-manufacturing commitments. The J.M. Smucker Company leverages its Jif manufacturing footprint to sustain cost discipline across retail and foodservice channels. Kraft Heinz Company anchors shelf presence through controlled distribution partnerships with mass-market retailers. Crazy Richard's specializes in single-ingredient positioning, differentiating on clean-label purity against emulsified competitors.
Fat free peanut butter is a spreadable paste produced from defatted roasted peanuts, typically containing less than 0.5 grams fat per serving through mechanical pressing or solvent extraction of peanut oil prior to grinding, formulated for calorie reduction while preserving protein density. The product serves commercial and retail markets targeting macronutrient-controlled diets, sports nutrition protocols, and clinical weight-management programs. Creamy and powdered variants capture disproportionate margin pools as fitness-oriented consumers prioritize mixability and recipe integration over traditional spread formats. Online Retailers represent the fastest-growing distribution channel, displacing conventional supermarket velocity as direct-to-subscription models reduce price transparency.
FDA nutrition labeling standards govern fat-content claims and serving-size declarations, while USDA organic certification requirements influence ingredient sourcing for premium-positioned lines. The F-Gas Regulation in Europe indirectly affects cold-chain logistics costs for temperature-sensitive nut butter distribution. Stakeholders must monitor evolving EPA biofuel mandates that compete for peanut oil offtake and reshape defatting economics.
Market Dynamics
Mechanical pressing and solvent extraction technologies are compressing production economics while FDA nutrient-content claim enforcement tightens formulation constraints across the United States retail landscape.
Growth Catalysts
- Fitness Enthusiast Demand:Protein-forward diet protocols among amateur and professional athletes are pulling defatted peanut butter into sports nutrition regimens as a calorie-controlled protein vehicle.
- USDA Organic Certification:Premium-positioned lines leveraging organic sourcing requirements capture shelf-space premiums in specialty retail channels.
- Mechanical Defatting Advances:Cold-pressing equipment upgrades are improving oil extraction yields without solvent residues, enabling cleaner-label positioning against conventional alternatives.
Market Restraints
- Peanut Oil offtake Competition:EPA biofuel mandates divert peanut oil toward renewable diesel production, raising input costs for defatting operations.
- Emulsification Requirements:Fat-reduced formulations require stabilizer systems to prevent oil separation, adding ingredient complexity and clean-label trade-offs.
- Private-Label Consolidation:Supermarket chain buyers extract slotting concessions that compress branded margin pools and commoditize volume.
Strategic Opportunities
- Direct-to-Subscription Models:Online Retailers bypass conventional supermarket velocity constraints, reducing price transparency and capturing recurring revenue.
- Powdered Format Expansion:Mixable variants integrate into smoothie and baking applications, opening foodservice and clinical weight-management channels.
- European F-Gas Compliance:Cold-chain logistics investments required by EU regulation create barrier-to-entry advantages for compliant exporters.
Industry Challenges
- Co-Manufacturing Coordination:Brands relying on third-party pressing facilities face capacity allocation conflicts during peanut harvest windows.
- Serving-Size Declaration Accuracy:FDA scrutiny of fat-content claims demands precise analytical testing protocols that strain smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Free Peanut Butter Market |
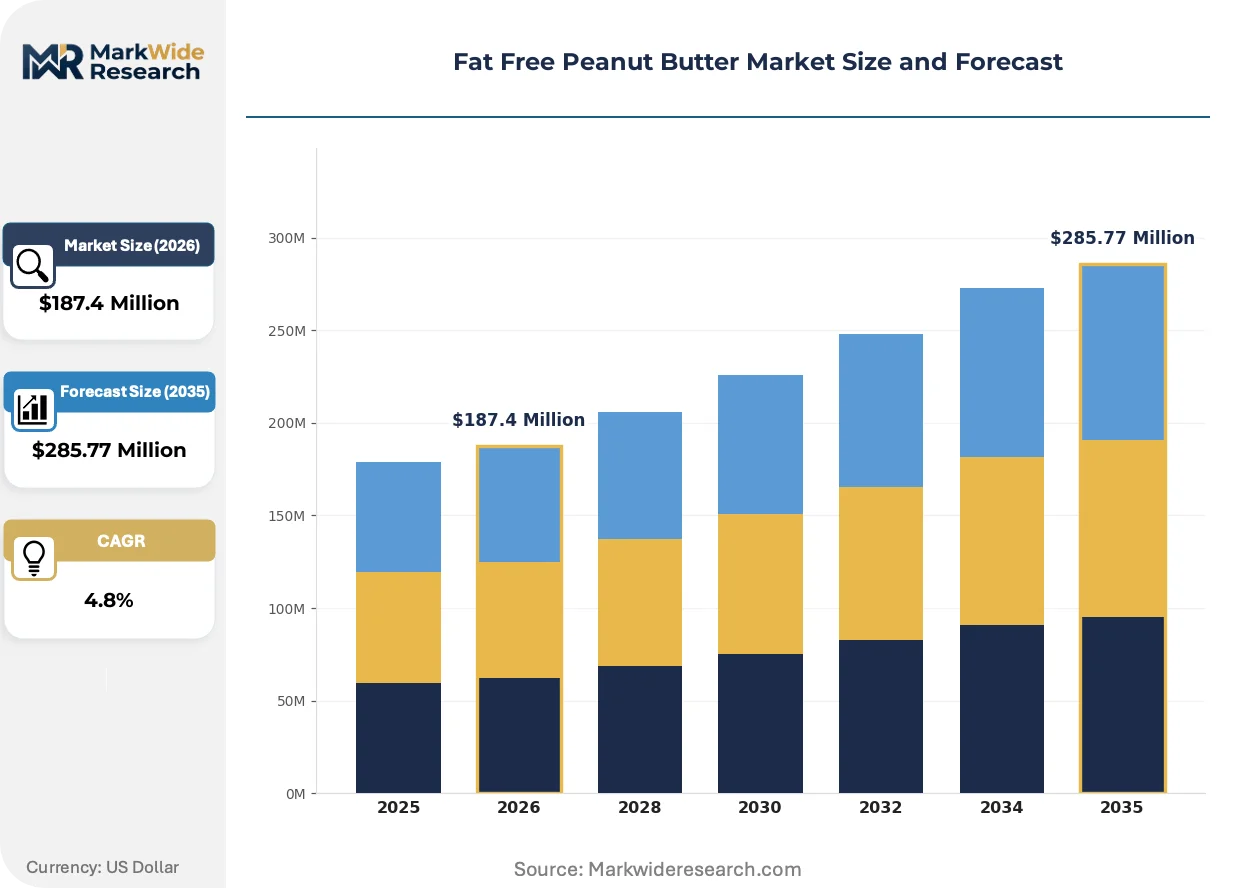
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamy, Crunchy, Spreads, Powdered Packaging Type: Tubs, Pouches, Jars, Sachets Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores End User: Fitness Enthusiasts, Health Conscious Consumers, Weight Watchers, Athletes |
| Companies Covered | The J.M. Smucker Company, Hormel Foods Corporation, Kraft Heinz Company, Conagra Brands, Inc., Once Again Nut Butter, Justin's LLC, PBfit, Crazy Richard's, MaraNatha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Free Peanut Butter Market Evolving Landscape
Formulation science and distribution architecture are converging to reshape how defatted peanut butter reaches calorie-conscious consumers, with technology adoption outpacing regulatory adaptation.
Enzymatic hydrolysis is integrating into premium production lines to improve protein bioavailability without emulsifier additives. Sports nutrition brands are adopting these enzymatically treated variants for post-workout formulations. The technology is integrating protein functionality with clean-label positioning, compressing the trade-off between performance claims and ingredient simplicity.
REACH chemical registration requirements in Europe are tightening scrutiny on solvent residues in imported defatted nut products. Manufacturers must document extraction agent compliance through extended supply chain audits. Powdered variants face the steepest documentation burden, as their higher surface-area-to-volume ratios intensify residue detection sensitivity.
Subscription-based replenishment is displacing conventional supermarket purchase cycles among fitness-oriented households. Direct-to-consumer platforms capture pantry-automation demand while eroding price discovery. This behavioral pivot concentrates most visibly in metropolitan United States markets where specialty retail penetration already normalized premium nut butter purchasing.
Fat Free Peanut Butter Market Segmentation
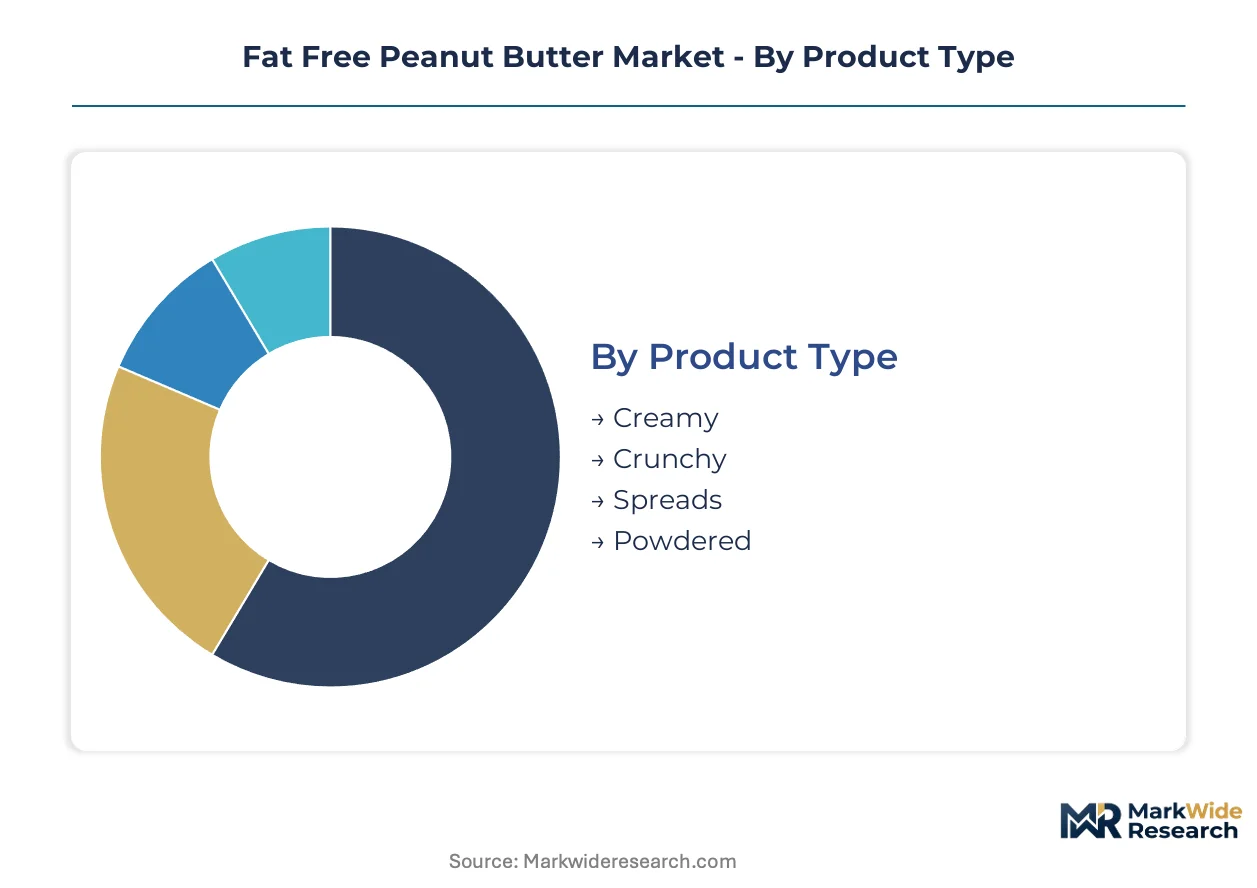
Defatted peanut butter segments diverge sharply between mass-market volume plays and premium-positioned nutrition formats. Understanding where protein density, convenience, and clean-label claims concentrate reveals which product architectures command shelf-space investment.
Product Type:
Volume concentrates in spreadable formats while premium pools accrue to mixable and single-ingredient variants.
- Creamy:Emulsified defatted paste with uniform texture dominates sandwich applications and baking substitutions. Demand clusters in United States metropolitan households pursuing calorie-controlled comfort foods, constrained by stabilizer-system costs that erode clean-label positioning.
- Powdered:Spray-dried or mechanically milled defatted peanut protein with sub-2% residual oil enables smoothie integration and precise macro tracking. Sports nutrition protocols in United States coastal fitness markets pull this format fastest, though reconstitution behavior limits spreadable use cases.
- Crunchy:Textured variant incorporating partially defatted peanut granules for mouthfeel differentiation.
- Spreads:Value-added formulations incorporating flavoring systems or fortification blends targeting children's nutrition and household pantry staples.
Mature deployment sits with Creamy. Newer deployment is concentrated in Powdered.
Packaging Type:
Single-serve portability commands premium pricing while bulk formats anchor household replenishment economics.
- Pouches:Flexible laminate structures with tear-notch dispensing reduce material cost and shipping cube versus rigid alternatives. United States direct-to-subscription platforms favor this format for fitness-oriented auto-replenishment, though oxygen barrier specifications challenge shelf-life claims.
- Jars:Traditional wide-mouth glass or PET containers with lug closures dominate mass-market retail velocity. Supermarket slotting fees in United States conventional grocery channels entrench this format despite higher logistics cost per ounce.
- Tubs:Injection-molded PP containers with snap-fit lids targeting foodservice and institutional volume.
- Sachets:Foil-laminate single-serve packets for travel and portion-controlled clinical diet programs.
Institutional procurement gravitates toward Tubs. Direct-to-consumer expansion is climbing fastest in Pouches.
Distribution Channel:
Physical retail retains replenishment frequency while digital channels capture subscription loyalty and reduced price transparency.
- Online Retailers:Direct-to-subscription platforms and marketplace aggregators bypass conventional slotting economics. United States metropolitan fitness households normalize auto-replenishment here, though last-mile cold-chain requirements for temperature-sensitive emulsified products inflate fulfillment cost.
- Supermarkets:Conventional grocery and mass-market retail chains anchor volume through private-label consolidation. United States chain buyers extract co-manufacturing commitments that commoditize branded differentiation.
- Health Food Stores:Specialty retail with trained staff and sampling infrastructure for clean-label positioning.
- Convenience Stores:Grab-and-go single-serve placement for impulse and travel occasions.
Volume scale rests with Supermarkets. Steepest expansion trajectory belongs to Online Retailers.
End User:
Performance-oriented protocols drive premium formulation while clinical weight management demands precise serving control.
- Fitness Enthusiasts:Amateur and recreational athletes pursuing body recomposition and macro tracking. United States CrossFit and functional fitness communities pull powdered and single-ingredient formats fastest, prioritizing protein-to-calorie ratio over taste optimization.
- Athletes:Professional and competitive sports practitioners with institutional nutrition support. United States collegiate and professional team dietitians specify defatted peanut butter for pre-workout energy and post-workout recovery protocols.
- Health Conscious Consumers:General wellness seekers reducing saturated fat intake without eliminating peanut flavor.
- Weight Watchers:Clinical and commercial diet program participants requiring precise portion measurement and point-system compatibility.
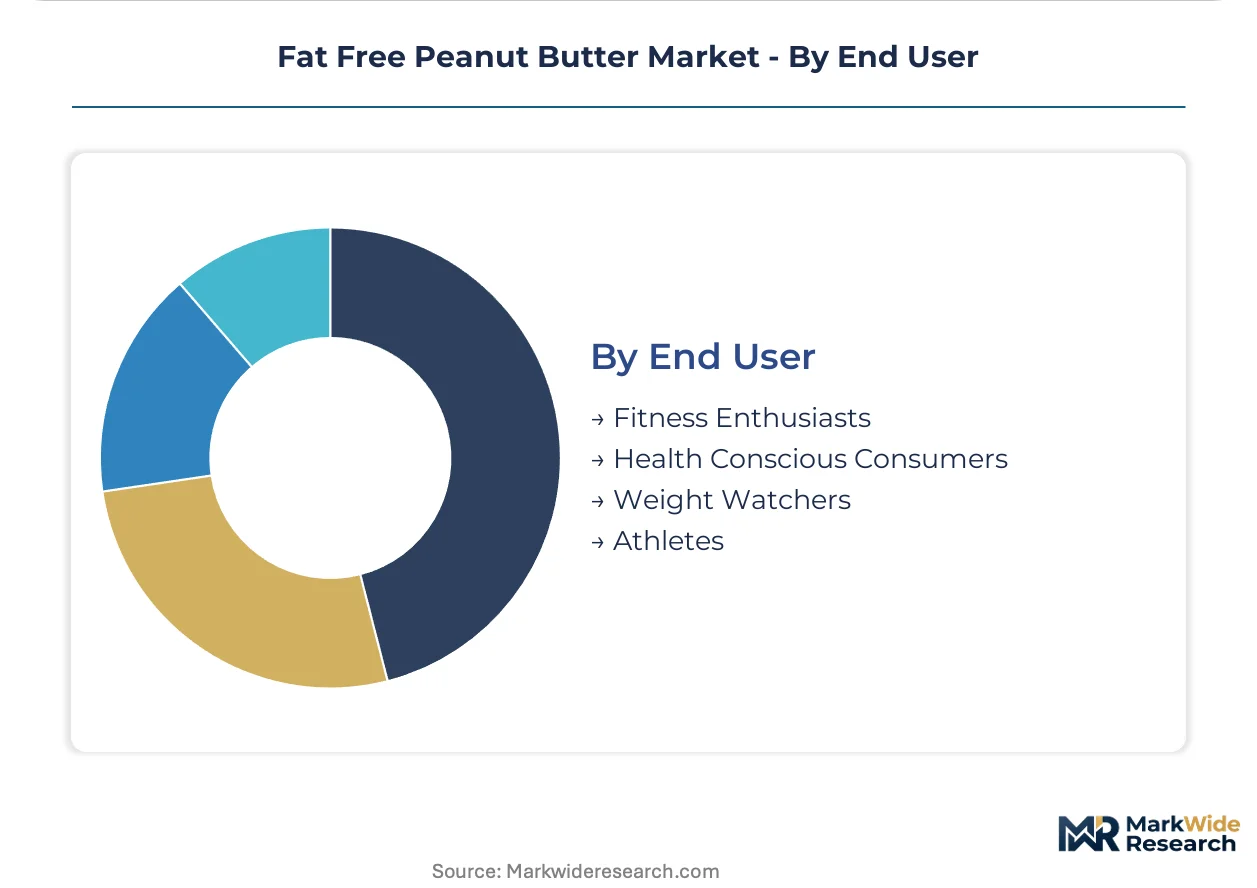
Established penetration centers on Health Conscious Consumers. Gaining share fastest among Fitness Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households account for the deepest health-conscious consumer penetration and specialty retail infrastructure for defatted peanut butter distribution. Fitness-oriented purchasing concentrates in coastal metropolitan markets with established sports nutrition channels. Regulatory frameworks in multiple jurisdictions shape formulation and trade economics.
United States
FDA nutrient-content claim enforcement and USDA organic certification requirements govern product labeling and premium positioning strategies. CrossFit and functional fitness communities in California and New York Metro drive powdered format adoption. The J.M. Smucker Company leverages Jif manufacturing infrastructure to sustain cost discipline across retail and foodservice channels.
Germany
REACH chemical registration requirements tighten scrutiny on solvent residues in imported defatted nut products. ECHA documentation mandates extend supply chain audit burdens for exporters. Berlin and Munich health food retail clusters normalize clean-label nut butter purchasing among protein-forward diet adherents.
United Kingdom
FSA allergen labeling regulations intersect with post-Brexit import certification requirements for nut-based products. London metropolitan fitness studios and sports nutrition retailers anchor demand for single-ingredient and powdered variants. Direct-to-subscription platforms capture pantry-automation demand among urban professional households.
Canada
Health Canada food labeling standards govern fat-content declarations and serving-size accuracy for retail distribution. CFIA import inspection protocols affect cross-border supply chain velocity from United States production facilities. Toronto and Vancouver metropolitan markets concentrate specialty retail and online fitness nutrition purchasing.
Australia
FSANZ nutrition claim standards regulate protein-content and fat-reduction marketing assertions. TGA oversight of therapeutic goods creates compliance boundaries for clinical weight-management product positioning. Sydney and Melbourne urban fitness communities pull powdered and portable-format defatted peanut butter through specialty channels and direct-to-consumer platforms.
Fat Free Peanut Butter Market Competitive Landscape
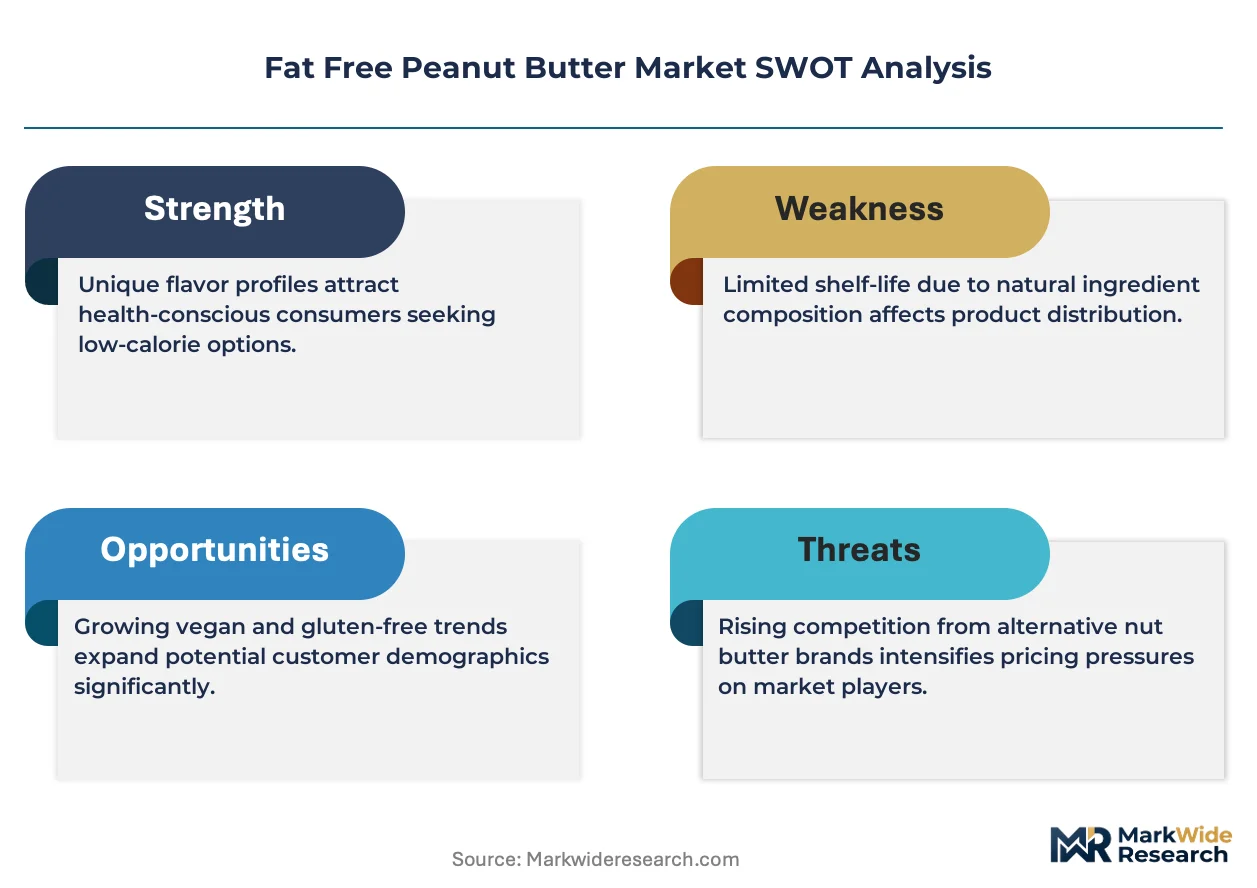
Established producers occupy the standard tier; emerging entrants pursue single-ingredient purity and direct-to-consumer subscription models. The vendor base spans multinational packaged food conglomerates, mid-sized specialty nut butter specialists, and private-label co-manufacturers serving retail chains. Strategic archetypes include scale-driven mass-market suppliers, clean-label purity specialists, and fitness-oriented format innovators. Competitive moves concentrate on co-manufacturing commitments to secure capacity and direct-to-subscription platform development to bypass retail slotting economics.
Within the multinational conglomerate tier, The J.M. Smucker Company and Kraft Heinz Company represent scale-driven infrastructure deployment. Among specialty positioning archetypes, Crazy Richard's exemplifies single-ingredient purity differentiation against emulsified alternatives. These anchors illustrate how cost discipline and clean-label positioning operate as competing vectors for shelf-space allocation and consumer loyalty.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Hormel Foods Corporation |
| Kraft Heinz Company |
| Conagra Brands, Inc. |
| Once Again Nut Butter |
| Justin's LLC |
| PBfit |
| Crazy Richard's |
| MaraNatha |
| Others |
Value Network & Pricing Analysis
Mechanical pressing specialists in Georgia and Alabama command wage premiums that compress margin spreads between premium single-ingredient and standard emulsified tiers. Labor-cost differentials in these peanut-processing clusters translate directly into pricing-tier stratification across retail and foodservice channels.
Pricing Analysis
Volume-mass trade-offs define competitive positioning as private-label consolidation erodes branded premium capture. Three-tier pricing structure across premium organic, standard defatted, and economy private-label levels stratifies by certification grade and stabilizer-system complexity. Cost compression in the standard tier intensifies because EPA biofuel mandates divert peanut oil toward renewable diesel, raising input costs for defatting operations. Health-conscious household buyers in conventional grocery channels exhibit highest price sensitivity, while fitness enthusiasts purchasing through direct-to-subscription platforms accept premium positioning for protein-density claims.
Supply Chain Analysis
Peanut oil offtake rests on United States southeastern shelling and pressing infrastructure concentrated in Georgia, Alabama, and Texas. Raw material dependencies include runner peanut varietals, food-grade stabilizer systems, and oxygen-barrier packaging laminates. Single-source vulnerability concentrates in mechanical pressing capacity allocation during harvest windows, when third-party facility commitments conflict across multiple brand clients. Distribution runs through direct-to-subscription platforms and conventional retail chains, with cold-chain logistics requirements for emulsified products inflating last-mile fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical pressing capacity constraints prop pricing power across the standard and premium tiers, as harvest-season bottlenecks limit defatting throughput expansion.
For Market Incumbents: Deploy co-manufacturing commitment leverage to secure pressing capacity allocation ahead of harvest windows. Anchor shelf presence through controlled distribution partnerships with mass-market retailers facing private-label consolidation pressure. Backward integration into peanut shelling operations in Georgia and Alabama reduces input cost volatility from oil offtake competition. For New Entrants and Emerging Players: Clinical weight-management dietitians represent an underserved buyer archetype requiring precise portion measurement and point-system compatibility. Powdered format penetration in foodservice channels offers white-space expansion beyond saturated retail spread markets. Launch through direct-to-subscription platforms bypasses supermarket slotting economics and captures recurring revenue from metropolitan fitness households. For Investors and Strategic Acquirers: Re-rating potential sits with clean-label purity specialists given FDA scrutiny tightening formulation constraints on emulsified competitors. Long-term viability centers on brands controlling single-ingredient positioning and enzymatic hydrolysis capabilities. Watch EPA biofuel mandate adjustments as the inflection indicator for defatting input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription auto-replenishment captures pantry-automation demand from CrossFit communities in California and New York Metro. |
| Enzymatic Hydrolysis Investment | Protein bioavailability enhancement enables clean-label positioning against stabilizer-dependent emulsified alternatives. |
| USDA Organic Certification Pathway | Premium shelf-space premiums in specialty retail channels justify input cost premiums from organic peanut sourcing. |
| Cold-Press Equipment Upgrade | Mechanical defatting yield improvements reduce solvent residue documentation burdens under REACH requirements. |
| Co-Manufacturing Partnership | Capacity allocation security during harvest windows protects margin structure against private-label volume commoditization. |
Research Methodology
Document review covered FDA enforcement actions, USDA organic certification databases, and EPA biofuel mandate filings, complemented by interviews with plant managers at peanut pressing facilities, category buyers at mass-market retailers, sports nutrition brand formulation scientists, and cold-chain logistics coordinators. Secondary validation drew from customs trade data, SEC 10-K filings of packaged food conglomerates, and Nielsen retail audit records. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Segment-level projections across product type, packaging format, distribution channel, and end-user archetype fed into analytical framework construction over the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating fitness enthusiast penetration rates, organic certification adoption trajectories, and direct-to-subscription platform growth curves. Forecast inputs included peanut harvest yield variability, solvent extraction technology diffusion patterns, and cold-chain logistics cost inflation.
Revisions become necessary when EPA biofuel mandate adjustments, FDA nutrient-content claim enforcement shifts, or mechanical pressing capacity expansion materialize. Forecasts reflect documented assumptions about harvest yield stability and subscription platform adoption curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Macadamia Nut Market
Nuts and Seeds
Pistachios Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Tiger Nuts Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
North America Peanut Butter Market
Nuts and Seeds
Peanuts Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Asia-Pacific Cashew Market
Nuts and Seeds
Pecans Market