
 Baru Nuts Market | 2026-2036
Baru Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Baru Nuts Market Analysis
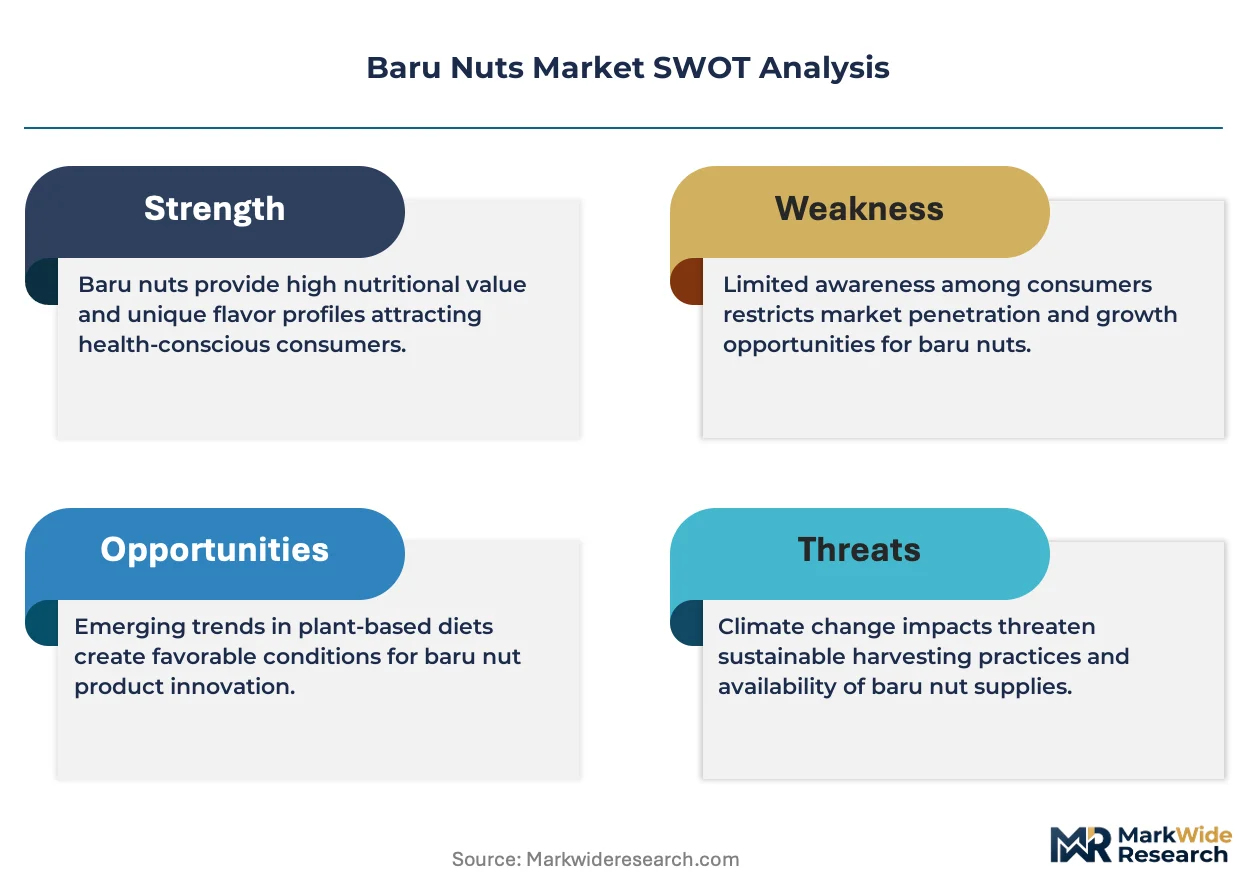
The gap between premium single-origin baru nuts and commodity-grade supply is expanding. Baru Baron leverages direct Cerrado sourcing relationships to control origin narratives. Mondelez International competes through scaled processing infrastructure. Brukas anchors its position in specialty retail channels across Western Europe.
Baru nuts are seeds of Dipteryx alata, a leguminous tree native to Brazil's Cerrado biome, containing approximately 25% protein and 40% lipid content by dry weight, with industrial applications spanning food fortification, cold-pressed oil extraction, and nut butter formulation. Raw nuts occupy the highest margin tier due to minimal processing overhead and strong organic certification premiums. Powdered nuts represent the fastest-growing product type as protein isolate demand from nutraceutical formulators accelerates. The health supplements application commands pricing power through clinical positioning around satiety and mineral density claims.
Brazil's MAPA enforces phytosanitary certificates for wild-harvested baru nut exports, while the EU EFSA Novel Food catalogue governs market access for unprocessed kernels in member states. REACH compliance shapes cosmetic-grade oil formulations destined for European personal care manufacturers. Stakeholders must track evolving Novel Food authorization pathways and Cerrado deforestation-linked sourcing disclosure requirements to secure long-term market positioning.
Market Dynamics
Wild-harvest supply concentration in Brazil's Cerrado biome creates persistent origin authentication pressure, while EU Novel Food authorization delays compress first-mover advantage windows for new entrants seeking European market access.
Growth Catalysts
- EFSA Novel Food Pathways:Approved baru nut kernel applications in the EU Novel Food catalogue unlock shelf-space expansion across German and Dutch natural food retail chains.
- Protein Isolate Demand:Nutraceutical formulators in North American health supplement manufacturing are accelerating procurement of powdered baru nut protein for satiety-positioned formulations.
- MAPA Phytosanitary Modernization:Brazil's streamlined export certificate processing for wild-harvested Dipteryx alata is reducing customs clearance friction for Cerrado-origin shipments.
Market Restraints
- Climate-Dependent Wild Harvest:Baru nut yields fluctuate with Cerrado rainfall patterns, creating raw material volume uncertainty for processors without multi-year supplier contracts.
- Novel Food Authorization Timelines:EFSA's 18-24 month safety assessment window for unprocessed kernel applications delays revenue recognition for European market entrants.
- Competing Tree Nut Proteins:Almond and pumpkin seed protein isolates benefit from established supply chains and lower unit economics in North American protein fortification applications.
Strategic Opportunities
- Cosmetic-Grade Oil Expansion:REACH-compliant cold-pressed baru oil formulations are penetrating European personal care manufacturing as sustainable emollient alternatives to palm-derived ingredients.
- Direct-to-Consumer Subscription Models:Specialty nut brands are bypassing conventional retail slotting fees through curated delivery services targeting mineral-density-conscious consumers in metropolitan France and Belgium.
- Organic Certification Premium Capture:IFOAM-accredited Cerrado harvesting cooperatives command 35-50% price multiples over conventional supply in Scandinavian natural food channels.
Industry Challenges
- Traceability Infrastructure Investment:Blockchain-enabled origin verification systems require substantial capital deployment from mid-sized processors seeking EU deforestation regulation compliance.
- Wild Harvest Labor Pool Constraints:Seasonal collector retention in Brazil's interior states competes with expanding soy and cattle operations for rural workforce availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baru Nuts Market |
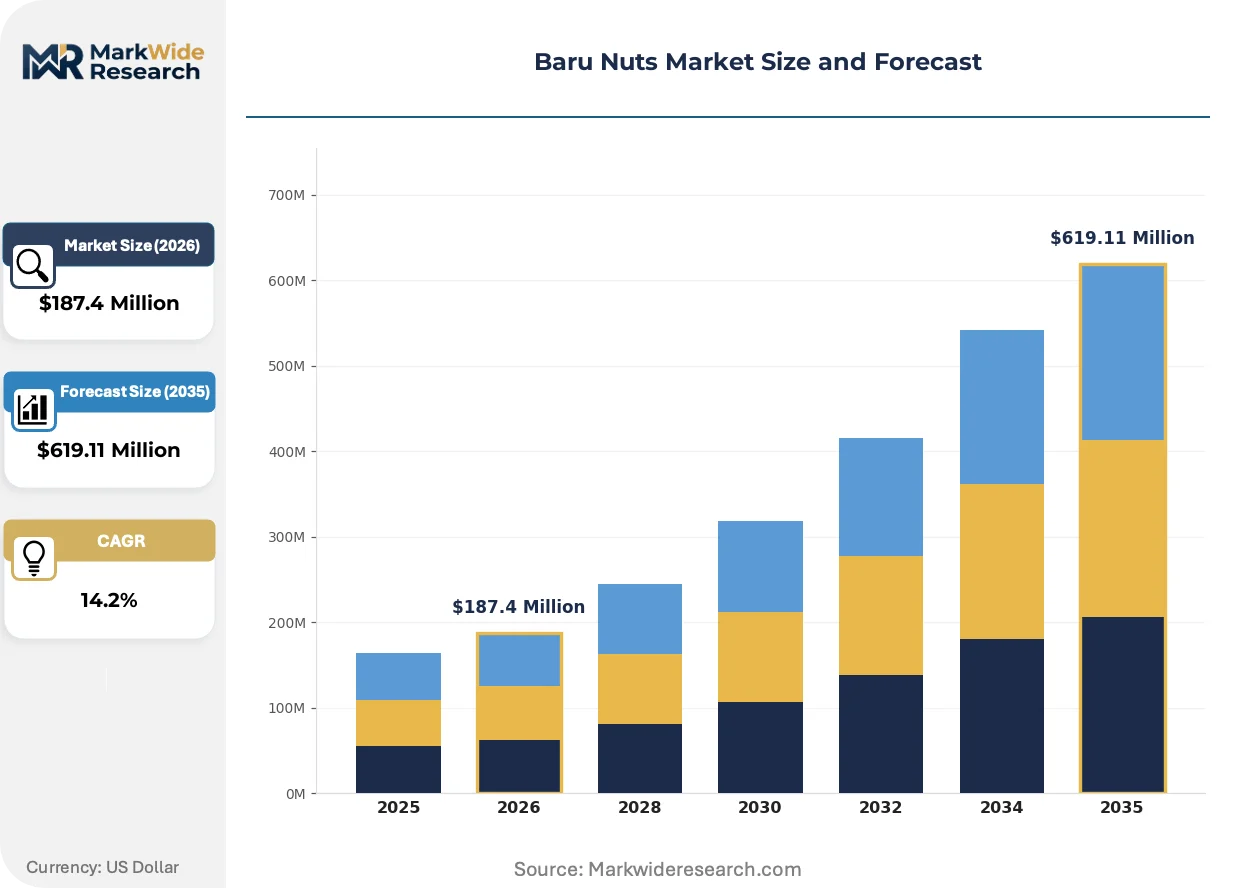
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Nuts, Processed Nuts, Powdered Nuts, Oil End User: Food Industry, Nutraceuticals, Cosmetics, Retail Consumers Application: Baking, Snacks, Health Supplements, Culinary Uses Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Baru Baron, Mondelez International, Brukas, The J.M. Smucker Company, Kraft Heinz Company, Brazil Barn Group, BioBrazil Botanicals, Blue Diamond Growers, Atina Ativos Naturais, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baru Nuts Market Emerging Trajectories
Processing technology fragmentation is compressing capital barriers between artisanal and industrial-scale baru nut transformation, while regulatory data requirements are reshaping competitive entry costs across jurisdictions.
Supercritical CO2 extraction equipment is modularizing downstream oil processing capabilities for mid-cap processors previously constrained by batch-scale limitations. Brazilian equipment fabricators are deploying containerized extraction units to Cerrado-adjacent processing cooperatives, enabling on-site oil production without centralized facility investment. This distributed processing architecture is compressing transportation costs for remote harvesting collectives while preserving volatile compound profiles in cosmetic-grade output.
EFSA's evolving Novel Food data requirements for traditional foods from third countries are extending authorization timelines for unprocessed baru kernel applications. The regulator's expanded toxicological study demands for allergen cross-reactivity assessment are increasing dossier preparation costs for Brazilian export consortia. German and Dutch import distributors are responding by prioritizing pre-authorized processed derivatives over raw kernel shipments to mitigate regulatory hold risk.
Certification-driven preference rotation is displacing conventional origin claims in European procurement decisions. French and Belgian retail buyers are mandating Cerrado biome deforestation-free verification through satellite monitoring partnerships as a condition of supplier qualification. This audit burden is favoring vertically integrated Cerrado operators with captive harvesting territories over aggregator-dependent traders in competitive tender processes.
Baru Nuts Market Segmentation
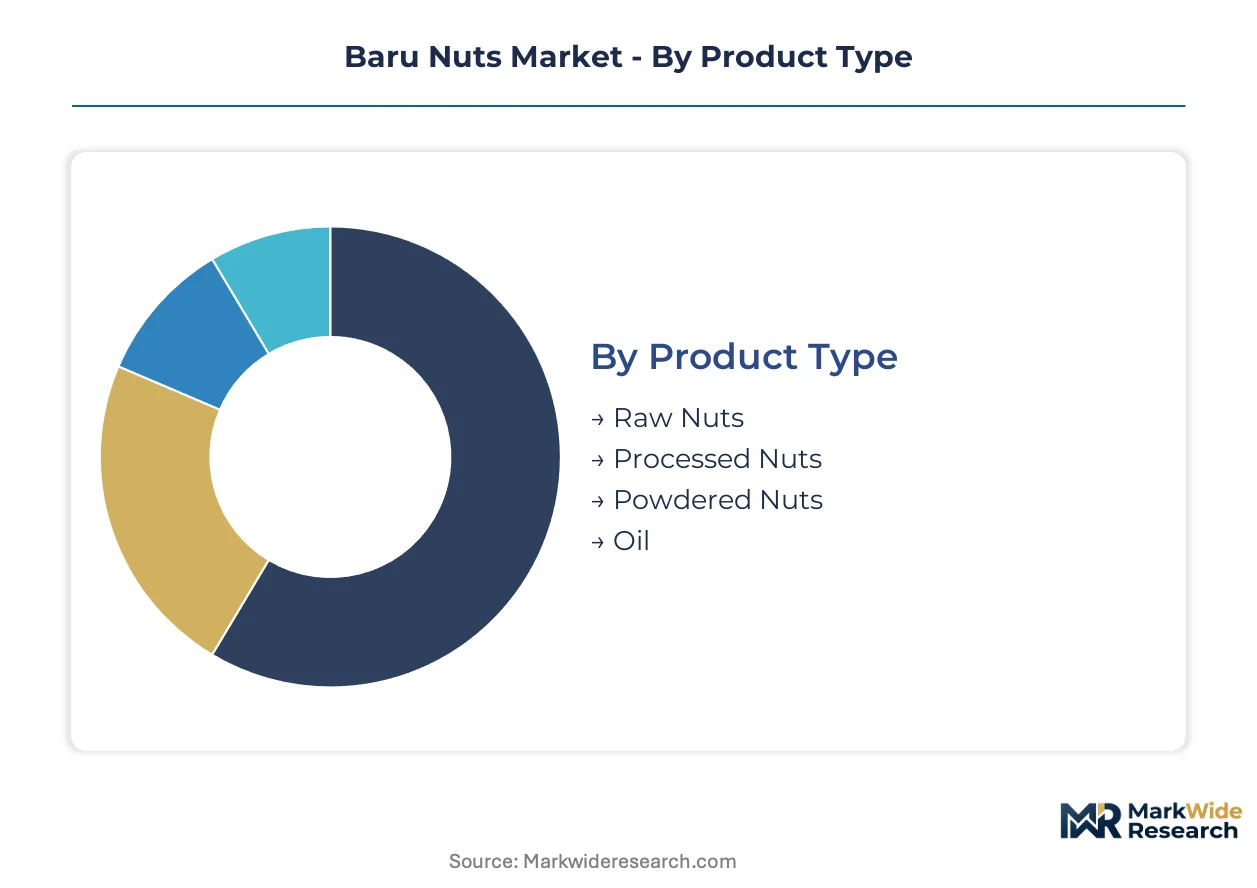
Baru nut processors face divergent margin profiles across transformation stages, from wild-harvest collection through pharmaceutical-grade protein isolation. Segmentation reveals where capital deployment concentrates and which specifications command procurement premiums in regulated import markets.
Product Type:
Processing intensity defines the technology frontier, with extraction methods determining volatile compound retention and cosmetic-grade certification eligibility.
- Raw Nuts:Unprocessed Dipteryx alata kernels retain full nutritional density with approximately 25% protein and 40% lipid content. Scandinavian natural food channels pay IFOAM-accredited cooperatives 35-50% premiums for organic-certified Cerrado origin with blockchain-verified deforestation-free status.
- Powdered Nuts:Protein isolate formulators in North American nutraceutical manufacturing drive accelerating procurement for satiety-positioned supplement formulations. EFSA Novel Food authorization delays for unprocessed kernels push demand toward pre-authorized processed derivatives in German and Dutch import channels.
- Processed Nuts:Roasted and flavored variants target snack applications with shorter shelf-life requirements than raw inventory.
- Oil:Cold-pressed extraction yields cosmetic-grade emollients competing with palm-derived alternatives in REACH-compliant European personal care manufacturing.
Raw nuts lead on scale; powdered nuts lead on momentum.
End User:
Customer sophistication tiers separate commodity volume purchasers from specification-driven formulators with regulatory compliance mandates.
- Nutraceuticals:Clinical positioning around mineral density and satiety claims commands pricing power through health supplement manufacturing procurement. EFSA's expanded toxicological study demands for allergen cross-reactivity assessment increase dossier preparation costs for Brazilian export consortia seeking European market access.
- Food Industry:Fortification applications in baking and snack manufacturing absorb volume from established supply chains with lower unit economics than pharmaceutical-grade specifications.
- Cosmetics:European personal care manufacturers source REACH-compliant baru oil as sustainable emollient alternatives, with French and Belgian buyers mandating satellite-monitored deforestation-free verification.
- Retail Consumers:Direct-to-consumer subscription models in metropolitan France and Belgium bypass conventional retail slotting fees for mineral-density-conscious households.
Nutraceuticals capture the steepest expansion trajectory; food industry retains volume dominance.
Application:
Formulation requirements dictate processing standards and certification burdens across finished goods categories.
- Health Supplements:Protein isolate demand concentrates in North American manufacturing with clinical-grade positioning requirements. Supercritical CO2 extraction equipment modularization enables mid-cap processors to meet pharmaceutical specifications without centralized facility investment.
- Snacks:Roasted and flavored nut applications compete with almond and pumpkin seed alternatives on established supply chain economics in North American protein fortification markets.
- Baking:Nut flour and butter formulations serve gluten-free and paleo-positioned product lines in European natural food retail.
- Culinary Uses:Whole kernel and oil applications in restaurant and home cooking segments face price sensitivity versus conventional tree nut alternatives.
Health supplements command margin premiums; snacks absorb procurement volume.
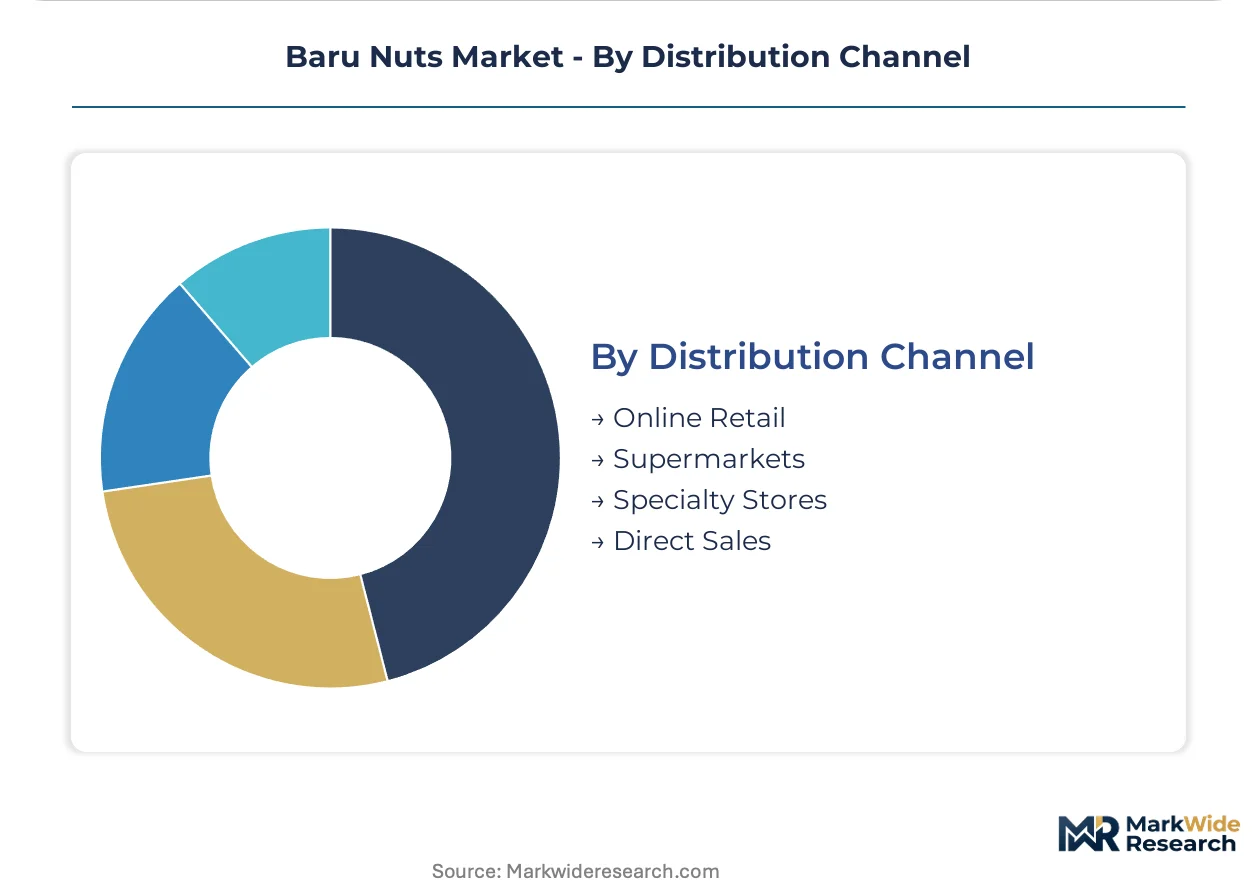
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition economics across geographic markets.
- Specialty Stores:German and Dutch natural food retail chains prioritize EFSA Novel Food catalogue authorization status for shelf-space allocation, with deforestation-free verification becoming mandatory qualification criteria.
- Online Retail:Subscription services targeting metropolitan France and Belgium enable specialty brands to bypass conventional retail slotting fees while building direct customer relationships.
- Supermarkets:Mass retail placement requires scale economies and consistent supply volumes that wild-harvest Cerrado sourcing struggles to guarantee across rainfall-dependent yield cycles.
- Direct Sales:Harvesting cooperatives and vertically integrated processors sell bulk quantities to industrial formulators with multi-year contracting requirements.
Specialty stores anchor premium positioning; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild-harvest collector networks in Brazil's interior states anchor global baru nut supply, while European nutraceutical formulators and North American health supplement manufacturers concentrate import demand.
Brazil
MAPA phytosanitary certificate modernization for Dipteryx alata exports is reducing customs clearance friction for Cerrado-origin shipments. The Goiás-Tocantins harvesting corridor supplies raw kernels to domestic processors in São Paulo state. Containerized supercritical CO2 extraction units are deploying to cooperatives in Minas Gerais, enabling distributed oil production without centralized facility investment.
Germany
EFSA Novel Food catalogue authorization status determines shelf-space allocation in natural food retail chains across Berlin and Hamburg. The country's national pharmaceutical regulator enforces REACH compliance for cosmetic-grade oil formulations entering personal care manufacturing. Düsseldorf-based import distributors are prioritizing pre-authorized processed derivatives over raw kernel shipments to mitigate regulatory hold risk.
United States
FDA dietary supplement facility registration requirements shape procurement patterns for powdered baru nut protein isolates. Health supplement manufacturers in California and New York accelerate procurement for satiety-positioned formulations. The FDA's food facility registration database tracks importers handling wild-harvested Cerrado-origin inventory.
Netherlands
Rotterdam port customs authorities enforce EFSA Novel Food documentation for unprocessed kernel shipments entering European distribution. Dutch natural food retail chains mandate satellite-monitored deforestation-free verification as a supplier qualification condition. Amsterdam-based specialty importers are building direct relationships with IFOAM-accredited Cerrado cooperatives to secure organic-certified supply.
France
ANSM cosmetic ingredient safety assessments govern baru oil applications in Paris-based personal care formulation laboratories. Direct-to-consumer subscription services in metropolitan Paris and Lyon bypass conventional retail slotting fees for mineral-density-conscious households. French retail buyers are mandating Cerrado biome deforestation-free verification through satellite monitoring partnerships.
Baru Nuts Market Vendor Landscape
Top-tier vendors anchor premium single-origin positioning, while commodity-grade processors compete on scaled infrastructure. The vendor base stratifies across three tiers: vertically integrated Cerrado operators with captive harvesting territories, mid-cap processors with modular extraction capabilities, and aggregator-dependent traders serving bulk industrial accounts. Dominant competitive moves include backward integration into wild-harvest collection networks and geographic expansion through EFSA pre-authorized product portfolios.
Among Brazil-based operators, Baru Baron and Atina Ativos Naturais represent vertically integrated archetypes with direct Cerrado sourcing relationships controlling origin narratives. Mondelez International exemplifies the scale-driven multinational segment competing through centralized processing infrastructure and established distribution reach.
| Leading Market Players |
|---|
| Baru Baron |
| Mondelez International |
| Brukas |
| The J.M. Smucker Company |
| Kraft Heinz Company |
| Brazil Barn Group |
| BioBrazil Botanicals |
| Blue Diamond Growers |
| Atina Ativos Naturais |
| Others |
Supply Flow & Price Mechanics
Cerrado wild-harvest baru nut spot indices cascade through three distinct pricing tiers based on certification status and processing depth. IFOAM-accredited organic kernels command substantial premiums in Scandinavian natural food channels, while conventional grades face compression from almond and pumpkin seed protein alternatives in North American nutraceutical procurement.
Pricing Analysis
Certification-bundled versus unbundled supply splits the market into premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects organic accreditation, blockchain traceability, and deforestation-free verification status. Price differentiation intensifies as EFSA Novel Food authorization delays push German and Dutch buyers toward pre-authorized processed derivatives over raw kernel shipments. Cost compression in conventional grades is intensifying because established tree nut proteins offer lower unit economics for formulators. Industrial nutraceutical buyers exhibit highest price sensitivity; specialty retail channels in metropolitan France and Belgium show lowest.
Supply Chain Analysis
Direct-to-industrial-formulator channels handle bulk powder and oil procurement from Brazilian cooperatives, while specialty retail distribution runs through Amsterdam-based importers and German natural food chains. Supply concentrates in Brazil's Goiás-Tocantins-Minas Gerais corridor, with secondary processing nodes in São Paulo state and Rotterdam port customs zones. Raw material flows draw from wild-harvest collector networks, supercritical CO2 extraction equipment, and containerized oil processing units. Single-source vulnerability persists around Cerrado rainfall-dependent yields and seasonal labor pool competition from soy and cattle operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baru nuts market functions as a stable compounder anchored by irreversible protein diversification trends in North American health supplement manufacturing. EFSA regulatory clarity and MAPA export modernization provide predictable expansion mechanics.
For Market Incumbents: Anchor deforestation-free verification capabilities through satellite monitoring partnerships demanded by French and Belgian retail buyers. Deepen backward integration into Cerrado harvesting cooperatives to secure organic-certified supply volumes. Invest in modular supercritical CO2 extraction deployment to preserve volatile compound profiles for cosmetic-grade output.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting mineral-density-conscious households in metropolitan France and Belgium. White-space exists in REACH-compliant cosmetic-grade oil formulations for European personal care manufacturing. Prioritize EFSA pre-authorized processed derivatives to bypass Novel Food authorization timelines blocking raw kernel competitors.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated Cerrado operators with captive harvesting territories and IFOAM-accredited cooperative relationships. Five-to-ten-year viability rests on sustained protein isolate demand from nutraceutical formulators and cosmetic-grade oil penetration. Monitor EFSA Novel Food catalogue expansion for unprocessed kernel applications as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Harvesting Cooperatives | Captive Cerrado supply secures organic certification premiums and deforestation-free verification compliance. |
| EFSA Pre-Authorized Product Portfolio Expansion | Processed derivatives bypass Novel Food delays blocking raw kernel competitors in German and Dutch channels. |
| Modular Supercritical CO2 Extraction Deployment | Containerized units enable mid-cap processors to meet pharmaceutical specifications without centralized facility investment. |
| Satellite-Monitored Deforestation-Free Verification | French and Belgian retail buyers mandate this audit burden as supplier qualification condition. |
| Direct-to-Consumer Subscription Launch | Specialty brands bypass conventional retail slotting fees while building customer relationships in metropolitan France and Belgium. |
Methodological Framework
Direct dialogue with wild-harvest cooperative managers, nutraceutical procurement directors, EFSA regulatory consultants, and specialty retail category buyers grounded the qualitative foundation. Secondary validation drew from MAPA phytosanitary export records, EFSA Novel Food catalogue filings, EU deforestation regulation drafts, and IFOAM organic certification databases. Bottom-up collector network assessments and top-down import volume triangulation calibrated supply-side estimates.
Segment-level projections across raw kernel, powdered protein, processed nut, and oil product types informed the analytical framework throughout the forecast period. Modeled dimensions included organic versus conventional certification tiers, nutraceutical versus food industry versus cosmetics end-use applications, and specialty retail versus online versus direct sales channel splits. CAGRs derived from historical procurement volume trajectories, EFSA authorization pipeline velocity, and North American protein isolate demand curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Cerrado drought frequency, EFSA toxicological study requirement expansion, and competing tree nut protein price erosion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Spain Fox Nuts Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Global Edible Nuts Market
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Organic Almond Oil Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Low Fat Nut Butter Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
South America Nut-Based Spread Market
Nuts and Seeds
Nuts and Nut Products Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Europe Cashew Market