
 Europe Cashew Market | 2026-2036
Europe Cashew Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cashew Market Foresight
Premium private-label buyers is bifurcating from commodity-oriented food processors across the European cashew landscape. Seeberger leverages its German roasting heritage to dominate the snack segment with specialized flavor profiles. August Töpfer & Co. (ATCO) anchors its position through long-standing West African sourcing relationships that sustain volume reliability. Rhumveld Winter & Konijn competes aggressively on organic certification coverage across Benelux retail channels.
Cashews comprise the kidney-shaped seeds of Anacardium occidentale, typically containing 46-48% fat and 18% protein by weight, with commercial grades determined by kernel size (W-180 through W-320) and whiteness index. The nuts undergo steam-roasting or dry-roasting to activate flavor compounds and reduce moisture to sub-5% levels for shelf stability. Roasted cashew nuts command the widest margin pool as European consumers prioritize convenience and premium snacking formats over raw ingredient purchases. Cashew butter represents the fastest-growing product type as plant-based spreads displace dairy alternatives in German and Scandinavian retail assortments. Bulk packaging still occupies the largest volume share, though resealable bags are accelerating as Aldi and Lidl expand private-label nut lines.
EFSA maintains strict aflatoxin thresholds for tree nuts entering European ports, while the EU Deforestation Regulation imposes geolocation traceability requirements on cashew supply chains from Côte d'Ivoire and Ghana. ECHA's REACH framework governs processing aids and packaging material compliance for roasted and flavored variants. Stakeholders must monitor how EUDR implementation timelines reshape origin documentation costs and whether smaller West African processors can meet digital traceability mandates without losing market access.
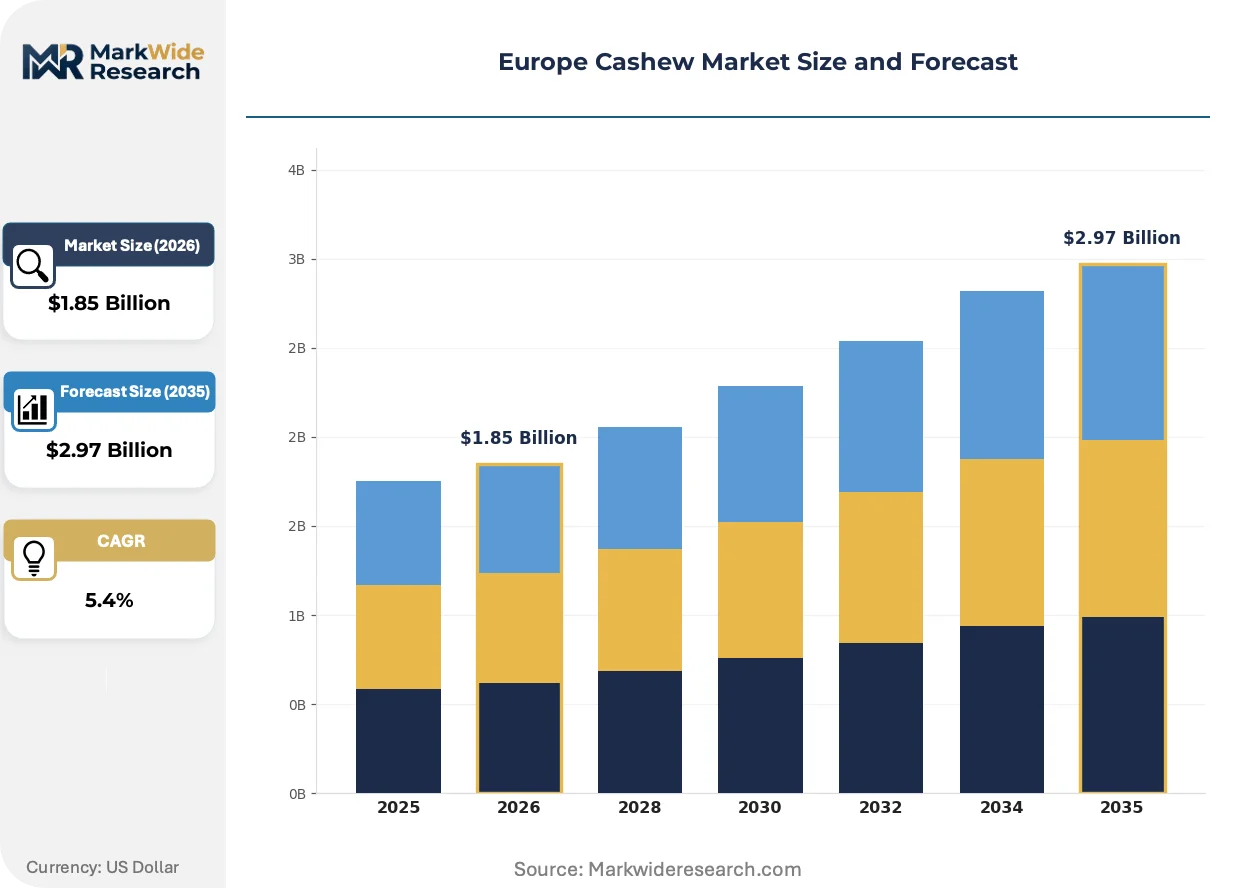
Market Dynamics
The EU Deforestation Regulation is forcing cashew importers to rebuild traceability infrastructure from farm level to European ports, transforming sourcing economics for processors serving German and Dutch retail channels.
Growth Catalysts
- Plant-based spread demand:Cashew butter gains shelf space in German and Scandinavian supermarkets as dairy alternatives lose favor among flexitarian consumers seeking clean-label options.
- EUDR traceability mandates:The EU Deforestation Regulation creates competitive advantage for early-compliant processors with geolocation-verified West African supply chains.
- Private-label premiumization:Aldi and Lidl expand resealable nut lines, pulling roasted cashew volumes from bulk formats into higher-margin branded-equivalent packaging.
Market Restraints
- Raw nut price volatility:Côte d'Ivoire and Ghana supply concentration exposes processors to weather-driven crop failures and currency fluctuation in West African franc zones.
- Aflatoxin compliance costs:EFSA maximum residue limits require expensive pre-shipment testing and rejected cargo risk at Rotterdam and Hamburg entry points.
- Kernel size scarcity:Premium W-180 grade availability tightens as Vietnamese processors compete for the same West African raw nut pool.
Strategic Opportunities
- Polish retail underpenetration:Discount chains Biedronka and Lidl Poland lack premium nut mix depth, creating first-mover space for EUDR-compliant suppliers.
- Organic certification arbitrage:Rhumveld Winter & Konijn's Benelux organic coverage model replicates across France where retailer sustainability scorecards reward certified sourcing.
- Steam-roasting automation:Convergence of optical sorting and IoT moisture control enables consistent flavor batching at smaller scale, lowering entry barriers for regional roasters.
Industry Challenges
- Digital traceability talent gap:West African cooperatives lack GIS technicians to meet EUDR geolocation requirements, requiring European processor investment in farmer-facing technology transfer.
- REACH compliance timeline:ECHA's evolving processing aid approvals delay new flavor coating introductions by 12-18 months versus non-European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cashew Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cashew Nuts, Roasted Cashew Nuts, Cashew Butter, Cashew Milk End User: Food Industry, Snack Manufacturers, Confectionery, Retail Consumers Packaging Type: Bulk Packaging, Retail Packs, Vacuum Sealed, Resealable Bags Distribution Channel: Supermarkets, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Aldebaran Commodities, Catz International, Rhumveld Winter & Konijn, Houz International BV, Alamir Trading, August Töpfer & Co. (ATCO), Märsch Importhandels, Seeberger, Bruckmann GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cashew Market Shifts & Advancements
Processing technology and regulatory compliance are converging to separate capital-intensive operators from commodity traders across the European cashew value chain.
Optical kernel sorting is bifurcating quality tiers in European roasting facilities. Machine vision systems grade by whiteness index and defect density at 400 kernels per minute. Mid-size German processors deploy this technology to capture private-label contracts that commodity traders cannot service. The capability gap is compressing margins for manual-sorting dependent operators while enabling premium pricing for certified defect-free supply.
EFSA's tightened aflatoxin sampling protocols reshape import inspection economics. The regulation mandates risk-based testing frequencies tied to origin country compliance history. Processors with consistent clean cargo records from Côte d'Ivoire gain expedited clearance at Rotterdam. Non-compliant shipments face detention costs that erase roasting margins.
Resealable flexible packaging displaces rigid containers in Scandinavian convenience retail. Mondelez and Orkla pilot high-barrier pouches with nitrogen flush that extend shelf life without preservatives. German discounters replicate the format for private-label lines, compressing traditional canister suppliers' volume share. The shift rewards packaging converters with vertical form-fill-seal capacity and food-grade film sourcing relationships.
Europe Cashew Market Segmentation
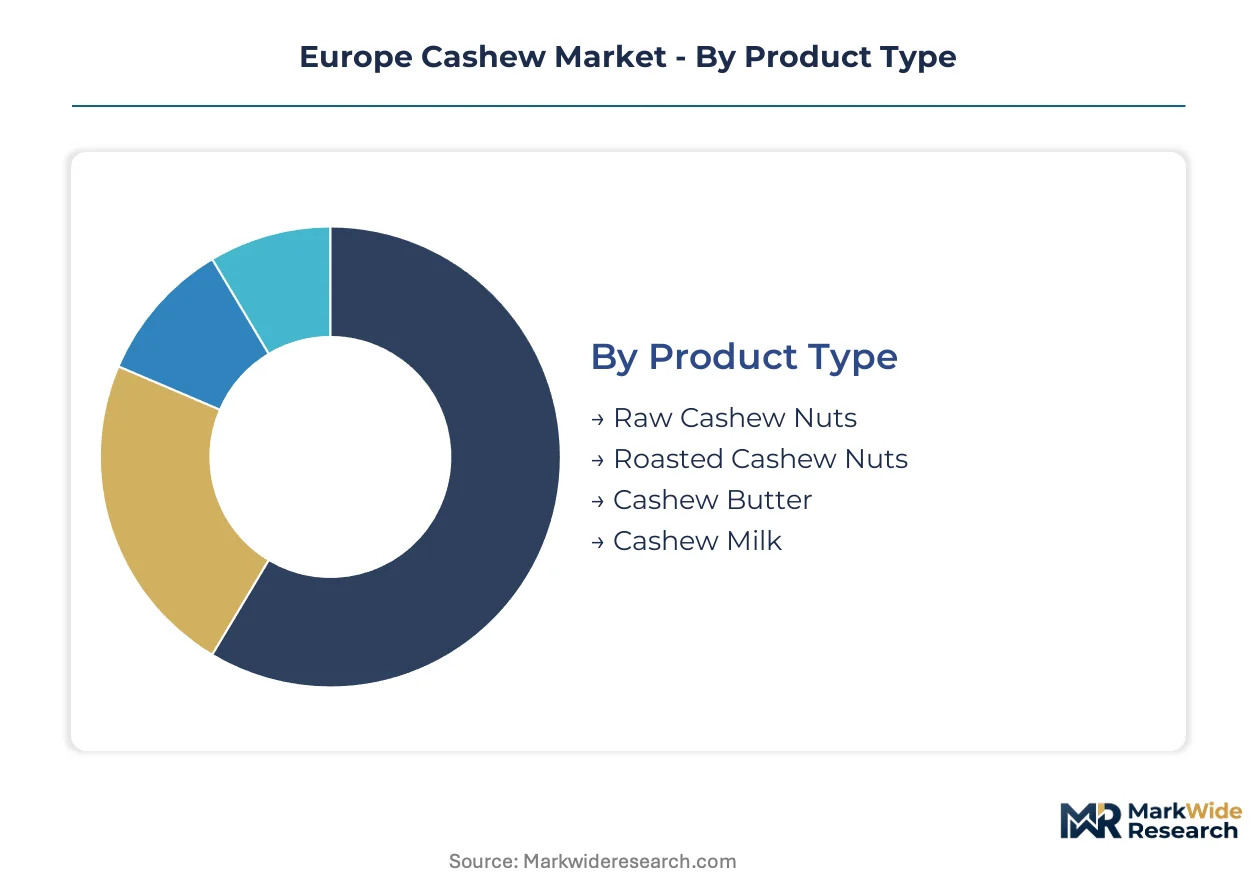
Segmentation in the European cashew market reflects divergent compliance burdens and margin structures. EUDR traceability requirements hit raw nut imports hardest, while processed formats face EFSA aflatoxin thresholds and ECHA REACH obligations. Understanding these regulatory tiers helps processors allocate capital across roasting, packaging, and distribution infrastructure.
Product Type:
EFSA maximum residue limits and ECHA processing aid approvals create sharply different compliance cost profiles across formats. Roasted variants face dual jurisdiction from food safety and chemical regulation frameworks.
- Raw Cashew Nuts:Unprocessed kernels enter European ports with W-180 through W-320 grading based on kernel count per pound. German and Dutch importers concentrate procurement here for in-house roasting operations that control flavor profiles and margin capture.
- Roasted Cashew Nuts:Steam-roasted or dry-roasted kernels with sub-5% moisture content activate Maillard flavor compounds. Snack manufacturers across Germany and the Netherlands prioritize this format for premium nut mixes, though EFSA sampling protocols add clearance risk at Rotterdam and Hamburg.
- Cashew Butter:Plant-based spreads displace dairy alternatives in German and Scandinavian retail assortments. Clean-label positioning drives shelf space gains in flexitarian-heavy demographics.
- Cashew Milk:Beverage-format cashew derivatives serve lactose-intolerant consumers and barista-style coffee applications. Nordic markets show particular penetration in oat-milk-dominated dairy alternatives.
Roasted cashew nuts handles the majority of throughput; cashew butter is expanding most quickly on share.
End User:
Volume concentration versus value extraction splits sharply across customer types. Food processors optimize for input cost stability while snack manufacturers chase premium positioning.
- Food Industry:Ingredient buyers in bakery and prepared meals seek W-320 grade consistency for cost-controlled formulations. Long-term contracting dominates procurement patterns to hedge West African supply volatility.
- Snack Manufacturers:German roasting specialists like Seeberger command private-label and branded shelf space through specialized flavor profiles. Aldi and Lidl expansion into resealable nut lines pulls volume from bulk formats into higher-margin packaged goods.
- Confectionery:Chocolate enrobing and praline applications require specific fat content and kernel integrity. Belgian and Swiss processors maintain quality premiums through selective sourcing.
- Retail Consumers:Direct purchasing concentrates in French and UK premium supermarkets. Organic certification arbitrage from Rhumveld Winter & Konijn's Benelux model is replicating across French retail sustainability scorecards.
Food industry moves the largest absolute tonnage; snack manufacturers capture the steepest margin expansion.
Packaging Type:
Packaging format selection determines shelf-life extension chemistry and ECHA REACH compliance scope for materials and processing aids.
- Bulk Packaging:Industrial totes and fiber drums serve food manufacturers with internal roasting and repackaging capabilities. Cost efficiency remains paramount despite EUDR documentation requirements per shipment.
- Retail Packs:Standard pouches and canisters occupy mainstream supermarket positioning. German discounters are compressing traditional canister suppliers' volume share through private-label replication.
- Vacuum Sealed:Oxygen exclusion extends shelf life without preservative additives. Scandinavian convenience retail pilots this format for premium positioning.
- Resealable Bags:High-barrier pouches with nitrogen flush technology from Mondelez and Orkla are displacing rigid containers. Vertical form-fill-seal capacity and food-grade film sourcing relationships determine converter competitiveness.
Bulk packaging retains volume leadership; resealable bags are gaining share fastest.
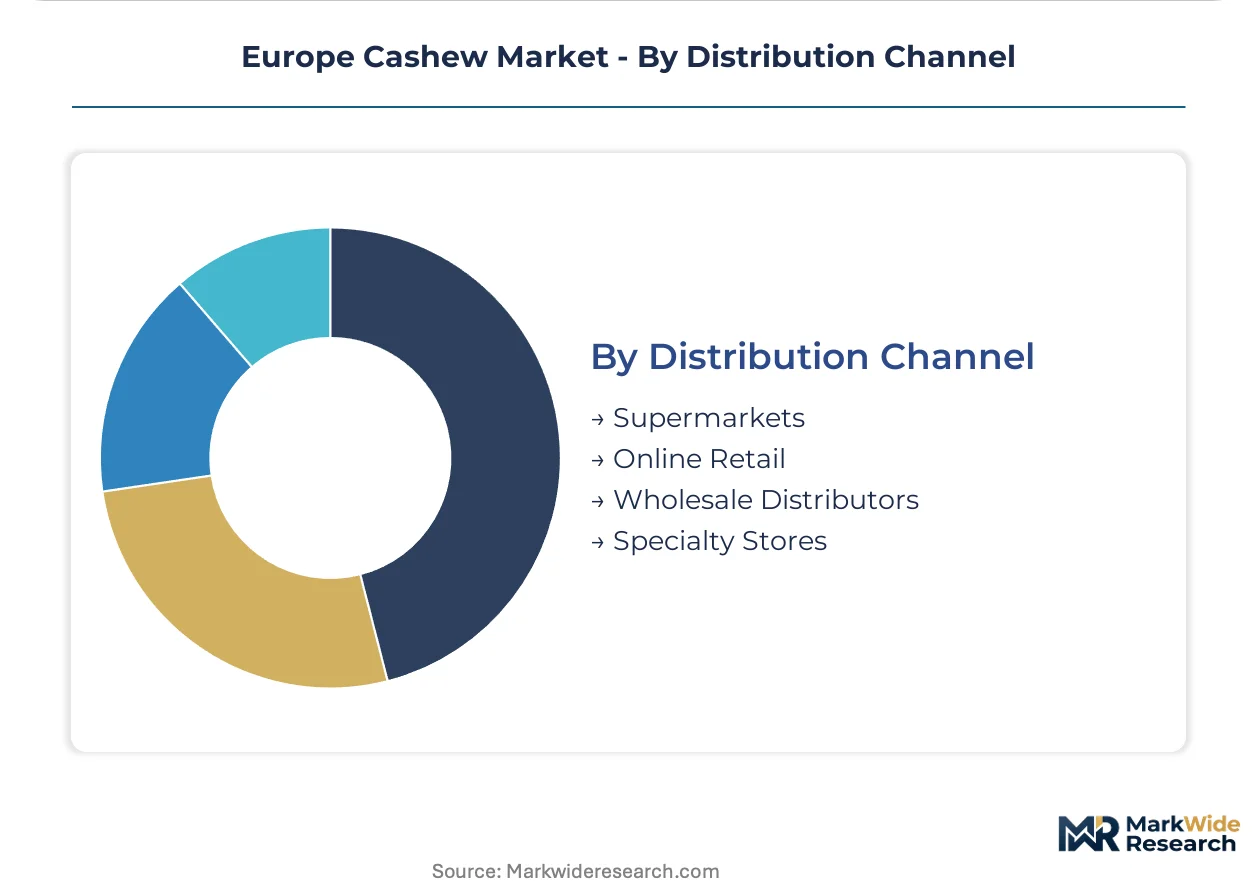
Distribution Channel:
Channel selection intersects with EUDR geolocation verification timing and EFSA risk-based inspection frequencies at point of entry.
- Supermarkets:Aldi and Lidl private-label expansion drives roasted cashew volume concentration. Resealable format adoption accelerates as discounters replicate Scandinavian convenience innovations.
- Online Retail:Direct-to-consumer channels serve specialty organic and flavored variants. Subscription models gain traction in UK and German urban markets.
- Wholesale Distributors:Rotterdam and Hamburg-based importers with consistent clean cargo records from Côte d'Ivoire gain expedited EFSA clearance. Non-compliant shipments face detention costs that erase roasting margins.
- Specialty Stores:Premium organic and fair-trade positioning concentrates in French and UK independent retail. Sustainability certification transparency commands price premiums.
Supermarkets dominate throughput; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
West African origin dependence concentrates import infrastructure at Rotterdam and Hamburg, where EUDR-compliant processors are consolidating procurement relationships ahead of enforcement deadlines. German and Dutch handling facilities now absorb over half of European cashew kernel volume.
Germany
Snack manufacturers in Bavaria and North Rhine-Westphalia drive roasted cashew demand through Aldi and Lidl private-label expansion. EFSA's tightened aflatoxin sampling protocols favor importers with consistent clean cargo records from Côte d'Ivoire. Hamburg's port infrastructure anchors the largest European roasting cluster, where mid-size processors deploy optical sorting to capture premium private-label contracts.
Netherlands
Rotterdam's warehousing and re-export hub status attracts West African raw nut consolidation before distribution to German and Scandinavian markets. EUDR geolocation traceability requirements are reshaping documentation costs for Côte d'Ivoire and Ghana shipments. Rhumveld Winter & Konijn's organic certification coverage across Benelux retail channels is replicating into French sustainability scorecards.
France
Paris and Lyon metropolitan areas concentrate retail consumer demand for premium organic and fair-trade positioning. The country's national food safety regulator enforces EFSA maximum residue limits with risk-based inspection frequencies tied to origin compliance history. Île-de-France specialty stores command price premiums for certified transparent sourcing.
United Kingdom
London and Southeast England urban markets show traction for direct-to-consumer online retail and subscription models. EUDR implementation timelines are compressing smaller West African processor market access as digital traceability mandates tighten. Midlands-based food manufacturers seek W-320 grade consistency for cost-controlled bakery formulations.
Poland
Biedronka and Lidl Poland discount chains lack premium nut mix depth, creating first-mover space for EUDR-compliant suppliers entering Warsaw and Kraków retail corridors. The country's food safety authority applies EU-harmonized aflatoxin thresholds with developing risk assessment infrastructure. Baltic port alternatives are emerging for processors seeking Rotterdam congestion avoidance.
Europe Cashew Market Competitive Landscape
Concentration sits with mid-size roasting specialists and commodity traders serving distinct compliance tiers. German and Dutch importers with established West African relationships capture volume reliability premiums, while organic-certified operators extract margin from sustainability-scored retail channels. Two archetypes dominate: heritage roasting houses with flavor specialization and volume traders with origin consolidation. Competitive moves center on EUDR pre-compliance investments and private-label contract capture from Aldi and Lidl expansion.
Within the heritage roasting tier, Seeberger leverages German flavor specialization, while August Töpfer & Co. (ATCO) anchors volume reliability through long-standing West African sourcing relationships. Among organic-certified traders, Rhumveld Winter & Konijn exemplifies the sustainability-scored positioning that is replicating across French retail. These three occupy distinct competitive spaces: flavor-driven premiumization, origin-locked volume security, and certification-arbitraged retail access.
| Leading Market Players |
|---|
| Aldebaran Commodities |
| Catz International |
| Rhumveld Winter & Konijn |
| Houz International BV |
| Alamir Trading |
| August Töpfer & Co. (ATCO) |
| Märsch Importhandels |
| Seeberger |
| Bruckmann GmbH |
| Others |
Supply & Pricing Matrix
EFSA aflatoxin thresholds gate both supply qualification and price differentiation simultaneously, as processors with consistent clean cargo records from Côte d'Ivoire command expedited clearance premiums at Rotterdam and Hamburg while non-compliant shipments face detention costs that erase roasting margins entirely.
Pricing Analysis
REACH compliance dictates the pricing tier structure across roasted and flavored variants, with ECHA processing aid approvals delaying new flavor introductions by 12-18 months versus non-European markets and compressing margins for smaller operators. Three-tier pricing structure across premium, standard, and economy levels stratifies by kernel grade and organic certification status, with W-180 scarcity intensifying cost compression in the premium tier as Vietnamese processors compete for the same West African raw nut pool. Bulk ingredient buyers in the food industry exhibit the highest price sensitivity, while snack manufacturers capturing Aldi and Lidl private-label contracts show greater tolerance for premium positioning.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor raw cashew kernel supply for European roasting operations, with the two countries feeding the majority of import volume through Rotterdam and Hamburg port infrastructure. Vietnamese processors compete aggressively for premium W-180 grades, creating dual-source tension for European importers seeking kernel size consistency. Single-source vulnerability concentrates in West African franc zone currency exposure and weather-driven crop failures. Distribution runs through Rotterdam's warehousing and re-export hub before final delivery to German, Dutch, and Scandinavian retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Aldi and Lidl expand private-label nut lines, consolidating procurement leverage among a shrinking pool of discount retail giants that now dictate packaging format and EUDR compliance standards across the European cashew landscape.
For Market Incumbents: Shield margin position by accelerating EUDR pre-compliance investments in geolocation-verified West African supply chains before enforcement deadlines tighten, while deploying optical sorting automation to capture private-label contracts that commodity-dependent manual sorters cannot service. Backward integration into farmer-facing technology transfer addresses the digital traceability talent gap threatening cooperative market access.
For New Entrants and Emerging Players: Organic certification fast-tracks access to French retail sustainability scorecards where Rhumveld Winter & Konijn's Benelux model is replicating, creating first-mover space in an underpenetrated premium channel. Target Polish retail corridors where Biedronka and Lidl Poland lack premium nut mix depth, leveraging EUDR-compliant sourcing as a competitive wedge against established commodity traders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across steam-roasting automation and optical sorting infrastructure, favoring processors with deployed machine vision systems over manual-sorting-dependent operators. The viable acquisition archetype combines established West African sourcing relationships with EUDR-compliant traceability infrastructure. The signal to watch is EFSA risk-based inspection frequency adjustments tied to origin country compliance history.
| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Traceability Infrastructure Investment | Geolocation-verified supply chains from Côte d'Ivoire secure expedited Rotterdam clearance and retail access. |
| Optical Sorting Automation Deployment | Machine vision systems grading 400 kernels per minute capture private-label contracts beyond commodity trader reach. |
| Organic Certification Coverage Expansion | Benelux organic models replicating across French sustainability scorecards extract margin from certification-arbitraged retail channels. |
| Resealable Flexible Packaging Adoption | High-barrier nitrogen-flush pouches displace rigid containers as Aldi and Lidl expand private-label nut lines. |
| Polish Retail Market Entry | EUDR-compliant suppliers gain first-mover positioning in Warsaw and Kraków corridors lacking premium nut mix depth. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings across the European cashew value chain. Conversations with cashew importers, roasting facility operators, retail category buyers, and West African cooperative managers combined with EFSA guidance documents, ECHA REACH registration databases, EU customs trade data, and SEC filings from publicly traded snack manufacturers. Bottom-up volume modeling from kernel grade throughput and top-down value triangulation from retail pricing audits converge on segment-level estimates.
Sensitivity analysis stress-tests projections across alternative EUDR implementation timelines and aflatoxin compliance cost scenarios. Segmentation dimensions span product type, end user category, packaging format, and distribution channel, with kernel size grading and organic certification status as industry-specific stratifiers. CAGRs derive from historical volume trajectories adjusted for regulatory inflection points and private-label expansion rates. Modeled inputs include West African crop yield variability, Vietnamese processor competition intensity, and discounter shelf space allocation shifts.
The analysis sits within stated boundaries; outcomes outside sustained EUDR enforcement, stable West African supply relations, or consistent EFSA sampling protocols would require recalibration. Forecasts reflect assumptions regarding regulatory compliance cost pass-through and retail consolidation trajectories. Recalibration cycles align with material shifts in EU deforestation regulation enforcement, EFSA maximum residue limit revisions, and major discounter private-label expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Betel Nuts Market
Nuts and Seeds
Horse Chestnut Seed Extract Market
Nuts and Seeds
Thailand Fox Nuts Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Butyrospermum Parkii Market
Nuts and Seeds
Global Almond Powder Market
Nuts and Seeds
Nut Products Market
Nuts and Seeds
United States Nuts Market
Nuts and Seeds
Almond Extract Market
Nuts and Seeds
Cashew Nut Butter Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Hazelnut Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Almond Kernels Market
Nuts and Seeds
Almond Oil Market