
 Saudi Arabia Nuts Market | 2026-2036
Saudi Arabia Nuts Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Nuts Market Analytics
Multi-source procurement among Saudi distributors is repositioning how international nut suppliers secure shelf space in the Kingdom. Olam Group leverages its integrated origination network across almond and cashew belts to maintain consistent supply to Saudi importers. BAJA anchors its position through specialized roasting and packaging facilities tailored to Gulf consumer preferences. Mondelez International competes by extending its snack portfolio with nut-inclusive products calibrated for Middle Eastern taste profiles.
Nuts comprise shelled or shelled tree nuts and groundnuts, typically containing 45-75% lipid content by dry weight, processed through drying, blanching, roasting, or pasteurization for direct consumption or ingredient use. Almonds dominate product type volumes due to versatile application across confectionery and dairy alternatives, while pistachios command premium positioning in gift and seasonal segments. Wholesale channels still handle the largest tonnage, though online retail is gaining velocity as Saudi logistics infrastructure matures and cold-chain reliability improves for temperature-sensitive varieties.
SFDA mandates strict aflatoxin thresholds and nutritional labeling compliance for all packaged nuts entering Saudi distribution, while SASO enforces packaging material standards that affect import eligibility. These frameworks elevate compliance costs for smaller exporters but create barrier effects that favor established suppliers with dedicated quality assurance systems. Stakeholders must monitor evolving halal certification requirements and water-scarcity policies affecting nut cultivation in source countries, as both factors will reshape long-term sourcing economics and supplier selection criteria.
Market Dynamics
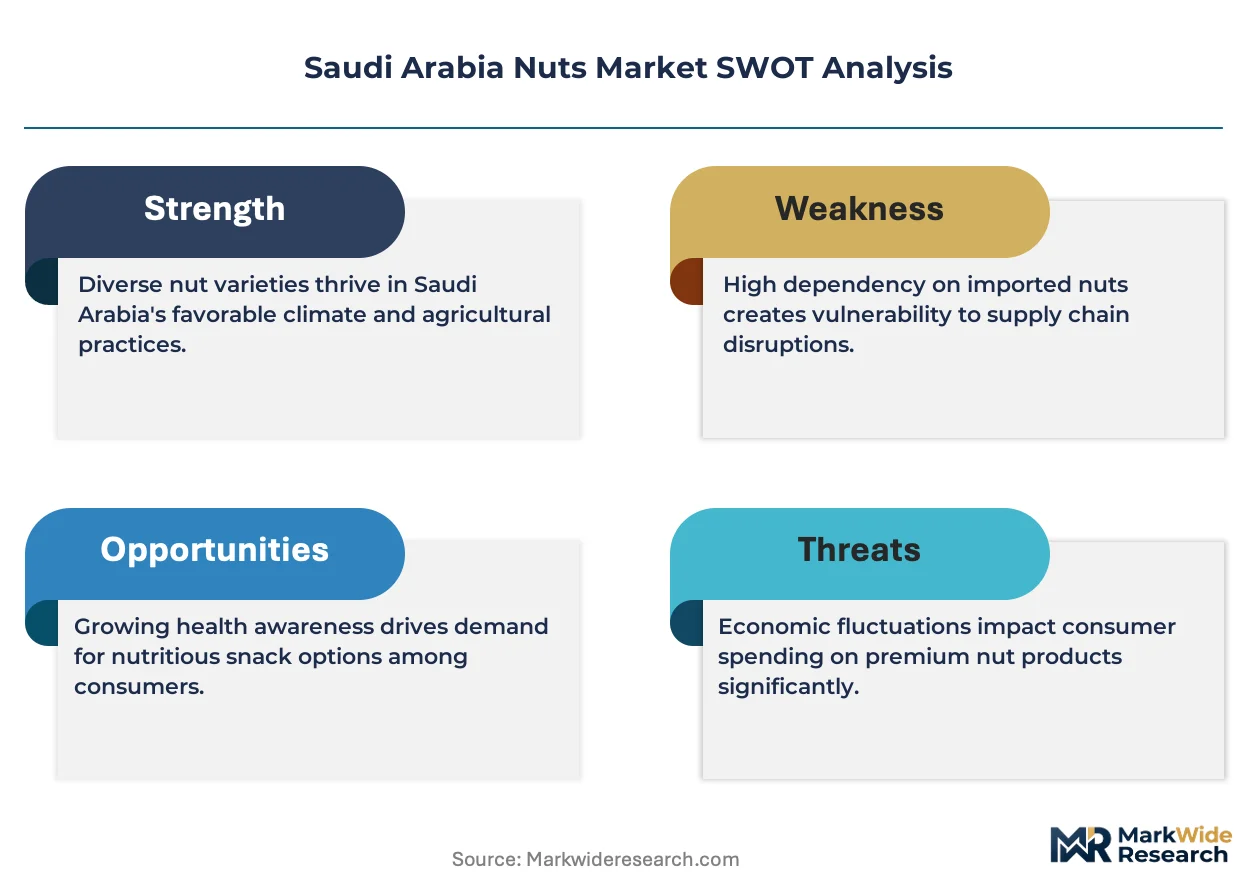
SFDA's tightened aflatoxin thresholds and nutritional labeling mandates are restructuring supplier economics, favoring integrated processors with captive laboratory infrastructure over fragmented traders.
Growth Catalysts
- Protein substitution wave:Saudi food service operators are reformulating menus with nut-based alternatives as consumer preference shifts away from processed meat snacks.
- SFDA allergen disclosure mandates:Standardized labeling requirements are consolidating shelf access for compliant packagers who invested early in traceability systems.
- Roasting technology upgrades:Fluidized bed and infrared roasting systems are improving yield recovery rates and flavor consistency for premium positioning.
Market Restraints
- California almond concentration:Overreliance on Central Valley sourcing exposes Saudi importers to drought-driven price volatility and shipping backlogs.
- SASO packaging material standards:Strict polymer and barrier-layer specifications disqualify lower-cost Asian suppliers lacking certified conversion capabilities.
- Seed oil substitution:Sunflower and rapeseed spreads are capturing price-sensitive segments in institutional bakery applications.
Strategic Opportunities
- Eastern Province penetration:Dammam and Khobar retail corridors remain underdeveloped relative to Riyadh and Jeddah, offering first-mover positioning for cold-chain operators.
- Direct-to-hospitality channels:Hotel and airline catering procurement is consolidating toward specialized distributors bypassing traditional wholesale layers.
- SFDA digital traceability incentives:Early adoption of blockchain-backed origin documentation qualifies suppliers for expedited customs clearance and preferred retailer listings.
Industry Challenges
- Halal certification complexity:Multi-jurisdictional slaughter and processing standards create documentation bottlenecks for mixed-origin nut butters.
- Cold-chain capex intensity:Pistachio and macadamia varieties require continuous temperature control from port to retail, demanding refrigerated warehousing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Nuts Market |
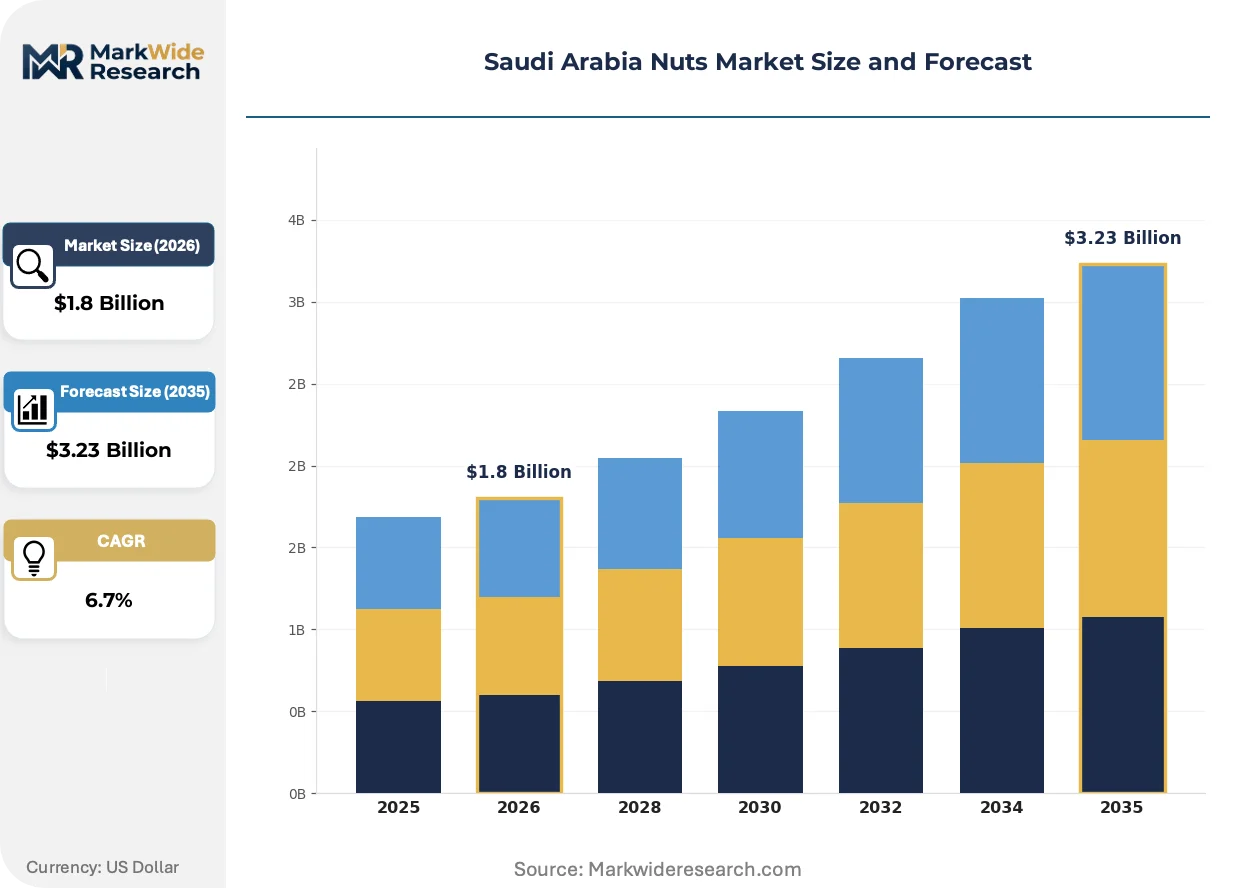
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almonds, Cashews, Pistachios, Walnuts Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale End User: Households, Food Service, Confectionery Manufacturers, Snack Producers Packaging Type: Bags, Tins, Bulk, Vacuum Sealed |
| Companies Covered | Hormel Foods, Diamond Foods, BAJA, Treehouse Foods, Mariani Nut Company, Mondelez International, Kraft Heinz, Bunge Limited, Olam Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Nuts Market Evolving Landscape
Processing automation and regulatory digitization are compressing quality assurance timelines while consumer-facing packaging innovations are redefining portion control and occasion-based consumption.
Modified atmosphere packaging with oxygen scavengers and nitrogen flushing is unifying shelf-life extension across temperature-variable retail environments. Saudi supermarket chains are adopting these systems for private-label nut lines to reduce shrinkage. The technology is unifying previously separate ambient and chilled supply chains into single distribution networks.
SFDA's implementation of electronic submission for nutritional claims and allergen declarations is accelerating compliance verification cycles. Roasters and importers are restructuring quality departments around digital documentation workflows. Small-scale traders without dedicated regulatory affairs staff face exclusion from modern retail procurement.
Snackification of nut consumption is fragmenting traditional bulk purchasing patterns. Single-serve and portion-controlled formats are displacing family-size bags in convenience retail and vending channels. Riyadh's office district food service operators are driving this shift through grab-and-go program expansion.
Saudi Arabia Nuts Market Segmentation
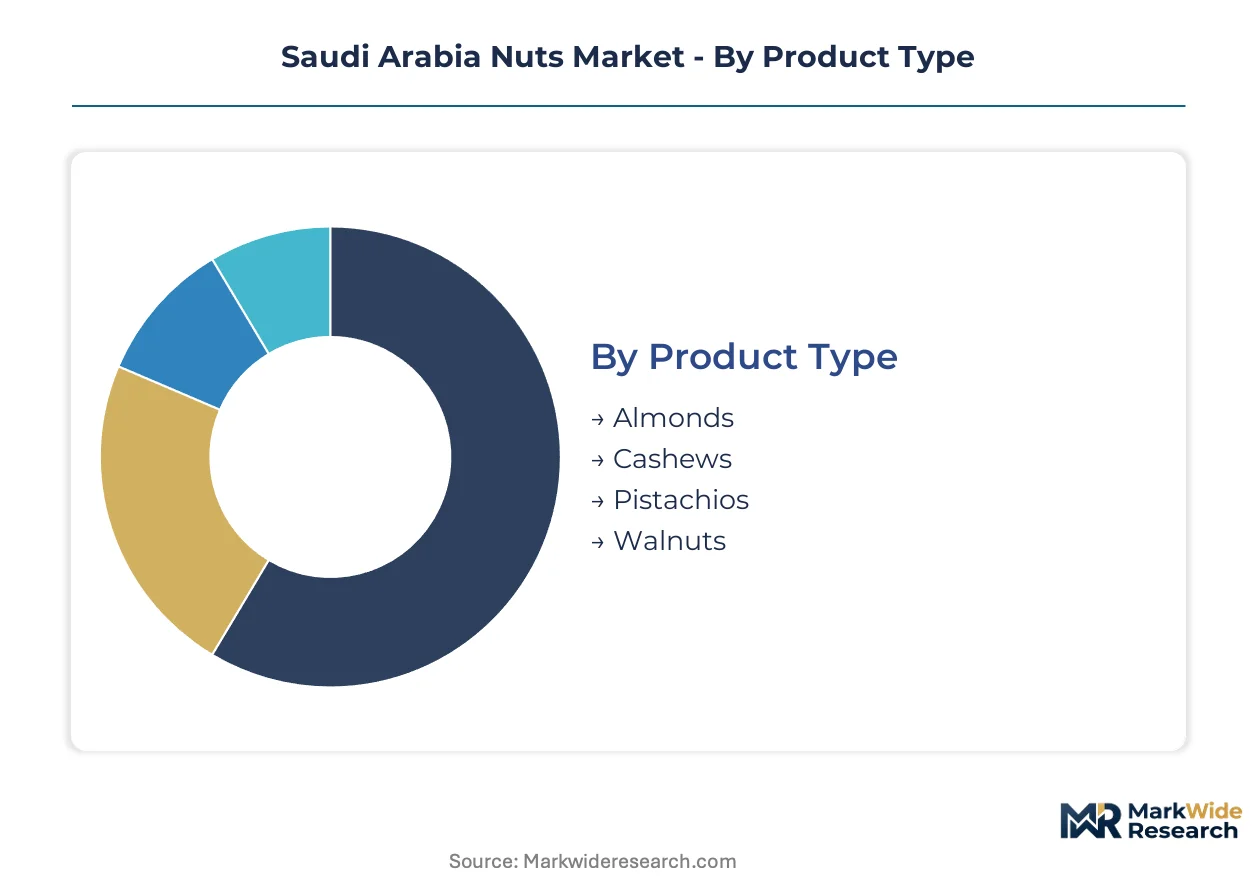
Supply chain configuration across Saudi Arabia's nut market varies sharply by segment, with procurement patterns and margin structures diverging between commodity bulk formats and precision-packaged retail SKUs. Understanding these fault lines reveals where distributors can capture value as SFDA compliance costs reshape competitive access.
Product Type:
Almonds concentrate sourcing risk in California's Central Valley while pistachios fragment across Iran, Turkey, and domestic Saudi cultivation trials.
- Almonds:These tree nuts contain 45-55% lipid content by dry weight with versatile application across dairy alternatives and confectionery bases. Demand concentrates in Riyadh's modern retail corridors where health-conscious consumers substitute almonds for processed snacks, though California drought cycles expose importers to price volatility.
- Pistachios:Premium-positioned nuts with 50-60% fat content and distinctive green kernel coloration prized in gift packaging. Demand clusters in Jeddah's seasonal retail peaks and hospitality procurement channels, where Iranian supply disruptions have elevated Turkish and US-origin positioning.
- Cashews:Kidney-shaped nuts processed through steam-shelling to preserve kernel integrity, dominating snack bar and trail mix applications.
- Walnuts:High omega-3 content varieties sourced primarily from Chile and California, penetrating bakery ingredient channels and premium nut butter formulations.
Today's leader: Almonds. Tomorrow's challenger: Pistachios.
Distribution Channel:
Channel economics in Saudi Arabia split between high-volume wholesale tonnage and margin-accretive direct-to-consumer formats requiring cold-chain investment.
- Supermarkets:Hypermarket and supermarket chains in Riyadh and Jeddah anchor volume throughput for family-size formats. Private-label expansion at Panda, Carrefour, and Tamimi is consolidating procurement toward integrated suppliers with captive roasting capacity and SFDA-compliant labeling systems.
- Online Retail:E-commerce velocity is accelerating as Saudi logistics infrastructure matures, with temperature-controlled last-mile delivery unlocking premium pistachio and macadamia segments previously confined to physical retail.
- Specialty Stores:Roaster-retailers in upscale Jeddah and Riyadh districts command premium positioning through small-batch processing and origin storytelling.
- Wholesale:Traditional bulk channels still handle largest absolute tonnage for food service and confectionery manufacturer procurement, though margin compression favors scale operators.
Supermarkets currently dominate value capture. Online retail is climbing the fastest.
End User:
End-use fragmentation in Saudi Arabia creates diverging specification requirements, from loose bulk for industrial processors to precision-portioned formats for grab-and-go consumption.
- Households:Direct consumer purchase concentrates in modern retail and emerging e-commerce channels, with single-serve and portion-controlled formats displacing traditional bulk buying in Riyadh office districts.
- Food Service:Hotel and airline catering procurement is consolidating toward specialized distributors bypassing wholesale layers, demanding consistent roast profiles and halal certification documentation.
- Confectionery Manufacturers:Industrial buyers source pasteurized nut pastes and diced formats for chocolate and bakery integration, with aflatoxin thresholds and particle size specifications governing supplier selection.
- Snack Producers:Reformulation of protein bars and savory mixes is expanding almond and cashew inclusion as Saudi consumers shift from processed meat snacks.
Food service offers the steepest margin expansion trajectory. Household penetration still represents the largest volume pool.
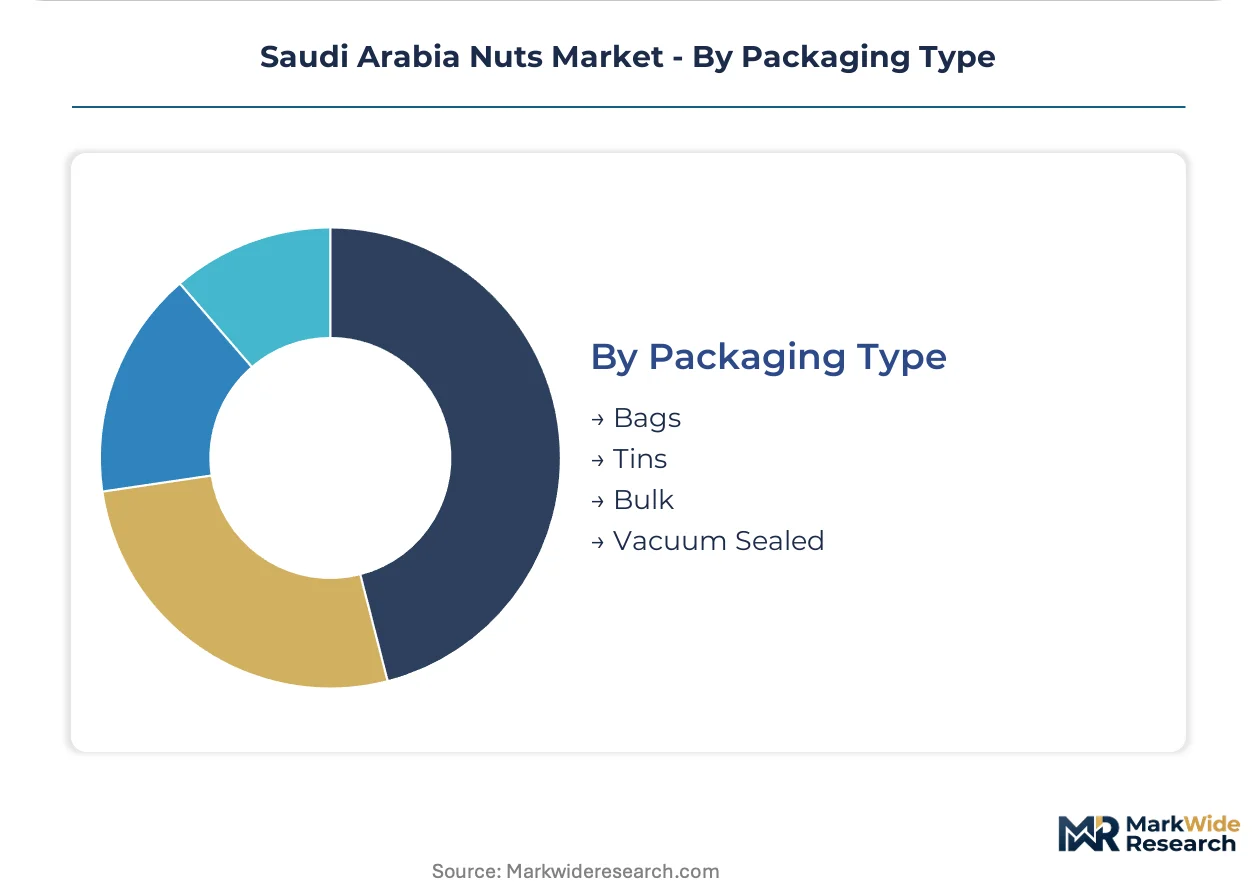
Packaging Type:
Packaging economics in Saudi Arabia are restructuring around SASO material standards and shelf-life extension technologies that unify previously separate supply chains.
- Bags:Flexible film formats with oxygen scavengers dominate mass-market retail, with modified atmosphere technologies reducing shrinkage for private-label lines.
- Tins:Metal canister formats command gift segment positioning, particularly for pistachio assortments during Ramadan and Eid purchasing peaks.
- Bulk:Loose formats for food service and industrial procurement minimize per-unit packaging cost but require rigorous aflatoxin screening and rapid inventory turnover.
- Vacuum Sealed:Barrier-layer packaging with nitrogen flushing extends shelf life for premium varieties, qualifying products for extended retail distribution in Eastern Province corridors.
Vacuum sealed formats are gaining share fastest. Bags retain the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's retail corridor anchors Saudi Arabia's nut consumption, with Jeddah's hospitality procurement and the Eastern Province's emerging logistics hubs diversifying geographic demand concentration.
Riyadh
Health-conscious consumers in Riyadh's office districts are shifting toward protein-rich nut snacks as meal replacements. SFDA's allergen disclosure mandates are consolidating shelf access for compliant packagers who invested early in traceability systems. The King Abdullah Financial District and Tahlia Street retail clusters are driving single-serve format velocity through grab-and-go program expansion.
Jeddah
Jeddah's hospitality sector commands premium pistachio volumes for airline catering and hotel procurement during Ramadan and Eid peaks. SASO packaging material standards are disqualifying lower-cost Asian suppliers lacking certified conversion capabilities. The Al-Andalus and Al-Balad retail corridors maintain specialized roaster-retailers with small-batch processing capabilities.
Eastern Province
Dammam and Khobar retail corridors remain underdeveloped relative to Riyadh and Jeddah, offering first-mover positioning for cold-chain operators. SFDA digital traceability incentives qualify blockchain-backed suppliers for expedited customs clearance at King Abdulaziz Port. The Dammam industrial zone is attracting refrigerated warehousing investment for temperature-sensitive macadamia and pistachio varieties.
Western Region
Makkah and Madinah pilgrimage traffic generates seasonal bulk demand for gift-packaged nut assortments. Halal certification complexity creates documentation bottlenecks for mixed-origin nut butters entering religious tourism retail channels. Taif's emerging agricultural trials are testing domestic pistachio cultivation viability under water-scarcity constraints.
Saudi Arabia Nuts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized roasting and direct-to-hospitality channels. The Saudi market structures around three maturity tiers: integrated global traders with captive origination networks, regional processors with Gulf-tailored packaging capabilities, and multinational snack conglomerates extending portfolio breadth. Three archetypes dominate: scale-driven commodity suppliers, premium-positioned specialty roasters, and brand-leveraged packaged food extenders. Competitive moves concentrate on backward integration into roasting capacity and strategic partnerships with SFDA-compliant logistics operators.
Among integrated global traders, Olam Group exemplifies the scale-driven archetype through its cross-belt origination network. BAJA anchors the regional processor tier with Gulf-specialized facilities. Mondelez International occupies the brand-extension position within multinational packaged food. These three represent distinct competitive vectors: geographic diversification, regional adaptation, and portfolio breadth.
| Leading Market Players |
|---|
| Hormel Foods |
| Diamond Foods |
| BAJA |
| Treehouse Foods |
| Mariani Nut Company |
| Mondelez International |
| Kraft Heinz |
| Bunge Limited |
| Olam Group |
| Others |
Value Network & Pricing Analysis
Captive roasting infrastructure anchors both supply security and margin control for Saudi distributors navigating SFDA compliance costs. Integrated processors with in-house laboratory systems command premium positioning against fragmented traders who face exclusion from modern retail procurement channels.
Pricing Analysis
Input-cost pass-through from California almond belt drought cycles and Iranian pistachio supply disruptions is compressing margins for non-integrated importers. Three-tier pricing structure across premium gift assortments, standard retail formats, and economy bulk channels stratifies by certification grade and cold-chain reliability. Pricing pressure stems from seed oil substitution in institutional bakery segments. Food service operators show lowest price sensitivity due to menu reformulation requirements, while wholesale bulk buyers face intensifying cost compression.
Supply Chain Analysis
SASO packaging material standards and halal certification mandates are reshaping sourcing toward suppliers with certified conversion capabilities and multi-jurisdictional documentation systems. Geographic supply concentrates in California for almonds, Turkey and Iran for pistachios, and Vietnam for cashews. Raw material dependencies rest on aflatoxin-compliant raw nut stocks, oxygen-scavenger film technologies, and nitrogen flushing equipment. Single-source vulnerability runs through California Central Valley drought exposure. Distribution runs through King Abdulaziz Port cold-chain corridors into Riyadh and Jeddah retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's nut market compounds steadily as protein substitution in food service creates durable demand expansion. SFDA regulatory tightening reinforces incumbent positioning while raising barriers for fragmented competitors.
For Market Incumbents: Cement shelf access through early blockchain traceability adoption qualifying for SFDA expedited clearance and preferred retailer listings. Expand captive roasting capacity in Dammam industrial zones to capture Eastern Province first-mover positioning. Defend against seed oil substitution threats by deepening hospitality channel relationships with consistent halal documentation. For New Entrants and Emerging Players: The premium-economy price gap in Eastern Province retail corridors offers white-space positioning for cold-chain operators with refrigerated warehousing investment. Target Dammam and Khobar underdeveloped corridors before incumbent footprint solidifies. Pursue direct-to-hospitality procurement bypassing wholesale layers through specialized roast profile capabilities. For Investors and Strategic Acquirers: Roll-up economics work for regional roaster-retailers with Gulf-tailored packaging capabilities because SFDA compliance costs are consolidating procurement toward integrated suppliers with dedicated quality assurance systems. Acquisition targets should demonstrate captive laboratory infrastructure and SASO-certified material sourcing. Watch SFDA digital traceability incentive expansion as inflection signal for expedited customs clearance qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Unlocks premium pistachio and macadamia segments in Eastern Province corridors. |
| Blockchain Traceability Adoption | Qualifies suppliers for SFDA expedited customs clearance and preferred listings. |
| Direct-to-Hospitality Channel Development | Bypasses wholesale margin compression through specialized airline and hotel procurement. |
| Modified Atmosphere Packaging Integration | Unifies ambient and chilled supply chains while reducing private-label shrinkage. |
| Halal Certification Documentation Systems | Resolves multi-jurisdictional bottlenecks for mixed-origin nut butter formulations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with Saudi importers, roasting facility operators, SFDA regulatory affairs specialists, and supermarket category buyers with secondary validation. Secondary sources included SFDA regulatory filings, SASO packaging standards documentation, Saudi Customs trade data, and cold-chain logistics operator disclosures. Bottom-up segment modeling and top-down market sizing triangulated volume and value estimates.
Segment-weighting across product type, distribution channel, end user, and packaging format dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of protein substitution patterns, retail channel evolution, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated California drought cycle correlation and Iranian supply disruption probability.
Caveats apply where California water policy shifts, Iranian trade sanction modifications, or SFDA aflatoxin threshold revisions could materially shift the outlook. Forecasts reflect assumptions around cold-chain infrastructure buildout pace and hospitality procurement consolidation trends. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Rubus Idaeus (Raspberry) Seeds Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Brazil Nuts Market
Nuts and Seeds
Chestnut Market
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Macadamia Butter Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Walnut-Based Spreads Market
Nuts and Seeds
Europe Nut-Based Spreads Market
Nuts and Seeds
Reduced Fat Peanut Butter Market
Nuts and Seeds
Nutmeg Butter Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Global Peanut Meal Market
Nuts and Seeds
Edible Peanut Powder Market
Nuts and Seeds
Vietnam Cashew Market