
 Decision Intelligence Market | 2026-2036
Decision Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Decision Intelligence Market Analysis
Mid-market manufacturers is reorganizing procurement priorities around real-time decision intelligence platforms that compress operational response cycles. FICO leverages decades of risk-scoring infrastructure to anchor credit-decision workflows across North American banks. Palantir Foundry dominates defense and intelligence-sector deployments with federated data architectures that sustain classified analytics pipelines. Taktile specializes in no-code decisioning layers that extend fintech underwriting velocity without engineering bottlenecks.
Decision intelligence fuses data engineering, behavioral science, and machine learning into systems that automate, augment, or explain complex choices under uncertainty. These platforms typically ingest multi-source structured and unstructured data, apply probabilistic models or neural architectures, and render recommendations through rule engines or natural language interfaces for operational, financial, or clinical decision-makers. Cloud-based deployment leads solution delivery by removing capital-intensive infrastructure barriers, while hybrid configurations capture regulated industries requiring data residency controls. Predictive modeling and workflow automation concentrate margin pools where recurring platform fees compound with usage-based inference pricing.
The EU AI Act classifies many decision intelligence applications as high-risk systems, mandating conformity assessments, human oversight protocols, and traceability documentation before market access. In the United States, the SEC scrutinizes algorithmic trading and lending decisions for fairness disclosures, while the FDA governs clinical decision-support tools as Software as a Medical Device when diagnostic outputs direct patient care. Stakeholders must monitor divergence between European ex-ante compliance frameworks and American sectoral enforcement patterns to avoid fragmented product architectures.
Market Dynamics
The EU AI Act's high-risk system classification is compressing vendor compliance timelines while healthcare providers accelerate diagnostic platform deployments to reduce clinical decision latency. This regulatory-demand tension is restructuring competitive positioning around explainability infrastructure and human-in-the-loop validation protocols.
Growth Catalysts
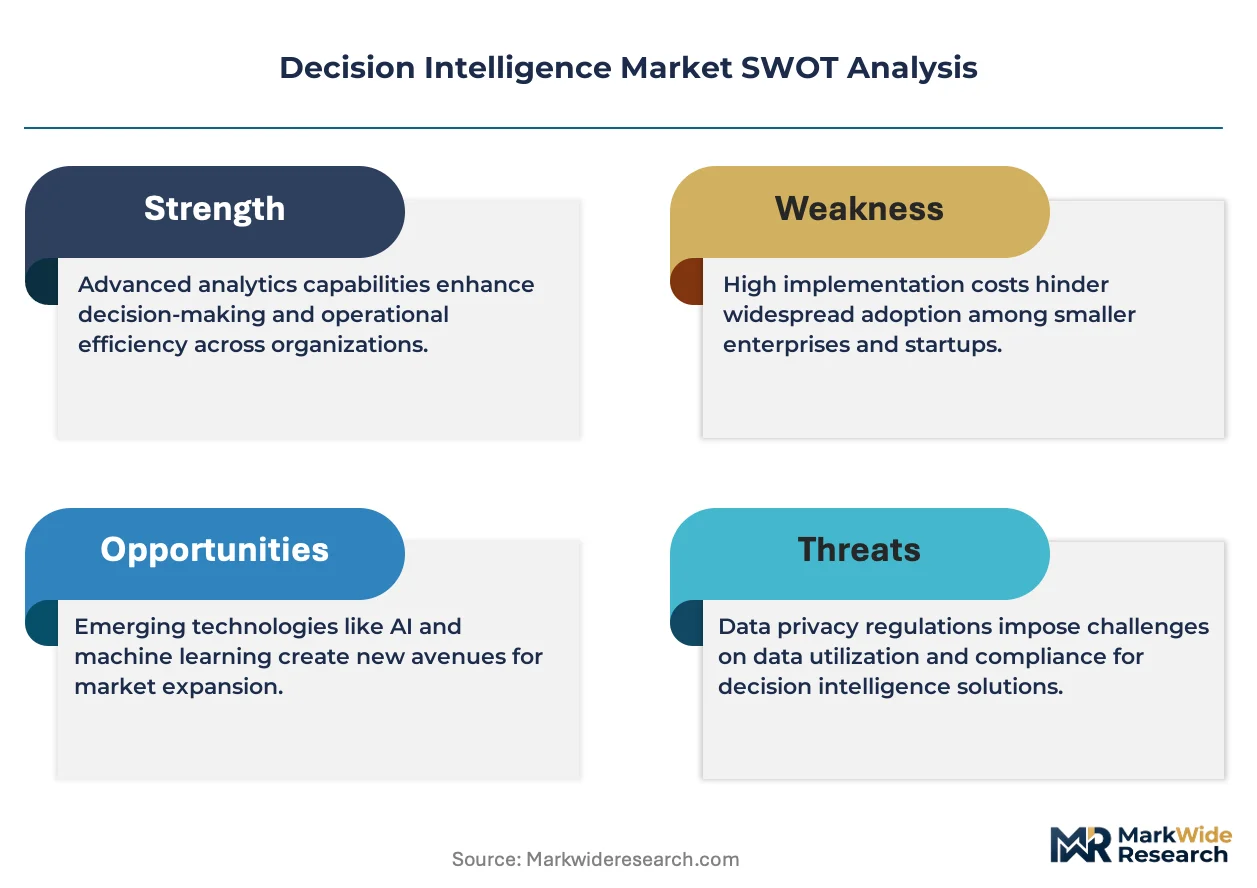
- EU AI Act Conformity Mandates:Automated decision systems deployed in Europe must complete conformity assessments and maintain traceability documentation, creating sustained demand for governance tooling and audit-ready platforms.
- Healthcare Diagnostic Velocity:Providers in Germany and the United States are integrating AI-driven platforms to compress triage-to-treatment intervals for time-critical conditions.
- Industrial Supply Chain Optimization:German manufacturers are embedding real-time decision intelligence into procurement workflows to synchronize multi-tier supplier responses with demand fluctuations.
Market Restraints
- Algorithmic Transparency Costs:The EU AI Act's explainability requirements impose documentation and human oversight infrastructure costs that disproportionately burden mid-market platform vendors.
- Data Residency Fragmentation:Regulated industries requiring sovereign data controls face hybrid deployment complexity across European national implementations of GDPR and sector-specific frameworks.
- Clinical Validation Timelines:FDA Software as a Medical Device pathways for diagnostic-directed outputs extend commercialization cycles for healthcare-focused decision intelligence products.
Strategic Opportunities
- Defense and Intelligence Federated Architectures:Classified analytics pipelines sustain premium platform deployments with multi-year contract structures and specialized security clearances.
- Fintech No-Code Underwriting Layers:Credit-decision velocity extensions without engineering bottlenecks capture mid-market financial services migrating from legacy rule engines.
- Cloud-Native Inference Pricing Models:Usage-based pricing layered atop recurring platform fees captures margin expansion as customer inference volumes scale with operational embedding.
Industry Challenges
- Behavioral Science Talent Scarcity:The fusion of machine learning with choice architecture and cognitive bias modeling requires hybrid skill sets concentrated in academic and specialized consulting channels.
- Legacy System Integration Friction:Enterprise ERP and clinical data warehouse architectures resist real-time ingestion pipelines, forcing expensive middleware development or data lake reconstruction.
- Cross-Border Compliance Architecture:Divergence between European ex-ante frameworks and American sectoral enforcement patterns fragments product roadmaps and inflates engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decision Intelligence Market |
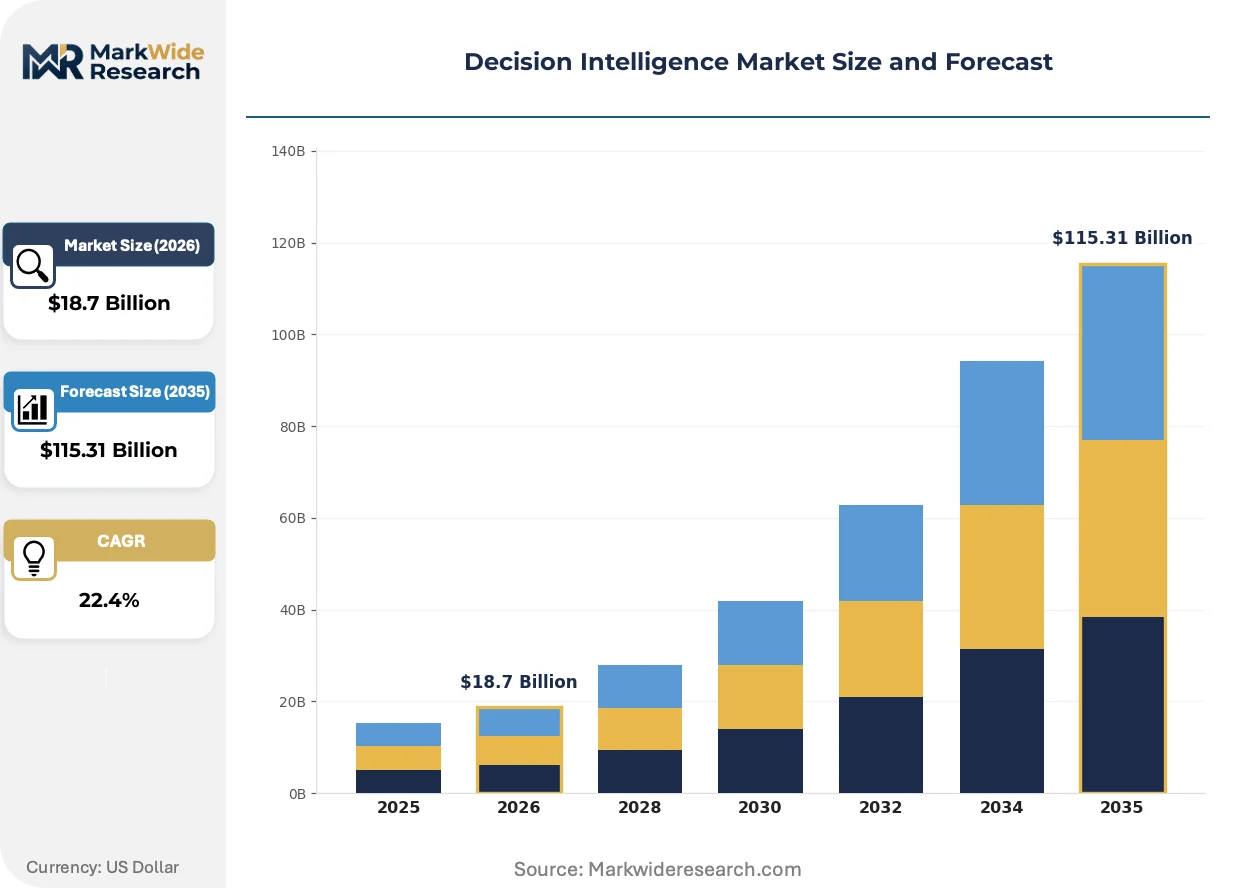
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Cloud End User: Retail, Healthcare, BFSI, Manufacturing Solution: Analytics, Machine Learning, Predictive Modeling, Workflow Automation Industry Vertical: Telecommunications, Energy, Transportation, Education |
| Companies Covered | Decisions, Taktile, FICO, Palantir Foundry, Inrule, Pega, Nected, Stravito, Aera Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decision Intelligence Market Emerging Trajectories
Explainable AI architectures are decomposing black-box decision systems into auditable component layers. This technical reconfiguration is reshaping how platforms demonstrate compliance, compress implementation timelines, and differentiate in procurement evaluations.
Neural-symbolic hybrid architectures are decomposing monolithic prediction models into interpretable rule-neural ensembles. Healthcare providers in Germany are piloting these systems for diagnostic triage where clinical staff require causal reasoning traces. The structural consequence is compressing regulatory review cycles while elevating platforms with built-in explanation generation over opaque alternatives.
The EU AI Act's high-risk system classification is mandating conformity assessment bodies and standardized technical documentation before market access. Industrial manufacturers deploying automated supply chain decisions face mandatory human oversight protocols and traceability requirements. European vendors are responding by embedding governance modules natively, while non-EU platforms accelerate localization partnerships to maintain market presence.
Subscription-to-usage hybrid pricing is displacing perpetual license structures in enterprise procurement. Mid-market manufacturers in Germany now evaluate platforms on marginal inference cost rather than upfront capital commitment. This behavioral shift is most visible in financial services underwriting, where fintech challengers unbundle decision engines from core banking systems and optimize for per-transaction economics.
Decision Intelligence Market Segmentation
Decision intelligence platforms fragment across deployment architectures, end-user requirements, and solution capabilities that determine compliance burdens and integration complexity. Segmentation reveals where vendor margins concentrate and which configurations face displacement from substitute technologies.
Deployment:
Cloud-native configurations face substitution pressure from sovereign data requirements and latency-sensitive edge deployments that bypass centralized infrastructure.
- On-Premise:Dedicated hardware installations within client data centers sustain classified analytics pipelines and FDA-validated clinical environments where data residency is non-negotiable. German industrial manufacturers and US defense contractors anchor demand here due to ITAR and GDPR Article 48 transfer restrictions.
- Cloud-Based:Fully managed SaaS delivery removes capital barriers for mid-market fintech challengers compressing underwriting cycle times. European vendors embed EU AI Act governance modules natively to preempt conformity assessment delays.
- Hybrid:Split architectures partition sensitive inference workloads on-premise while scaling compute-intensive training to public cloud. Healthcare providers in Germany pilot these configurations for diagnostic triage where patient data cannot exit national boundaries.
- Multi-Cloud:Orchestrated deployments across AWS, Azure, and GCP reduce vendor lock-in for enterprises with existing enterprise agreements. Financial services firms leverage this flexibility to optimize per-transaction inference economics.
Cloud-Based deployments anchor the volume base while Hybrid configurations gain share at the steepest rate as regulated industries seek sovereignty without sacrificing elasticity.
End User:
Procurement priorities diverge sharply between latency-sensitive clinical environments and batch-oriented manufacturing workflows.
- Healthcare:Diagnostic-directed platforms require FDA Software as a Medical Device validation when outputs direct patient care. German hospitals compress triage-to-treatment intervals for stroke and sepsis protocols using real-time decision layers.
- BFSI:Credit-decision velocity drives adoption of no-code underwriting engines that unbundle from core banking systems. SEC fairness disclosure scrutiny elevates platforms with built-in explainability over black-box alternatives.
- Retail:Demand forecasting and dynamic pricing engines optimize inventory positioning across multi-channel fulfillment networks. Mid-market merchants prioritize per-transaction economics over upfront platform commitments.
- Manufacturing:Real-time procurement synchronization with multi-tier supplier responses captures German industrial demand. EU AI Act high-risk classification for automated supply chain decisions mandates human oversight protocols.
BFSI anchors the volume base while Healthcare gains share at the steepest rate as diagnostic latency reduction becomes a competitive imperative.
Solution:
Margin pools concentrate where recurring platform fees compound with usage-based inference pricing at scale.
- Workflow Automation:Rule-engine orchestration of multi-step operational decisions reduces manual intervention in loan origination and claims processing. Mid-market manufacturers evaluate these platforms on marginal cost per automated decision.
- Predictive Modeling:Probabilistic forecasts of demand, risk, and equipment failure underpin capital allocation and maintenance scheduling. Energy utilities deploy these capabilities for grid stability optimization.
- Machine Learning:Neural architectures for pattern recognition in unstructured data support fraud detection and clinical imaging analysis. Behavioral science talent scarcity constrains deployment velocity.
- Analytics:Descriptive dashboards and diagnostic drill-downs provide operational visibility without predictive capability. Education sector procurement favors these lower-complexity entry points.
Workflow Automation anchors the volume base while Predictive Modeling gains share at the steepest rate as manufacturers embed forward-looking capabilities into procurement systems.
Industry Vertical:
Technology readiness and data maturity determine adoption sequencing across regulated and deregulated sectors.
- Telecommunications:Network optimization and churn prediction drive deployment of real-time decision layers at the edge. 5G infrastructure investments create data pipelines for automated capacity planning.
- Energy:Grid balancing and renewable intermittency management require predictive models with sub-second inference latency. German utilities anchor European demand for these capabilities.
- Transportation:Route optimization and predictive maintenance compress operational costs for logistics providers and fleet operators. FAA scrutiny of automated dispatch systems elevates explainability requirements.
- Education:Student retention and adaptive learning platforms remain early-stage with limited procurement budgets. Institutional data fragmentation constrains training data quality.
Telecommunications anchors the volume base while Energy gains share at the steepest rate as grid decarbonization accelerates investment in predictive balancing technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act's high-risk system classification is accelerating vendor localization around Frankfurt's data center corridor, where compliance infrastructure clusters alongside industrial automation demand.
United States
Defense and intelligence agencies sustain federated data architectures through classified analytics pipelines anchored in Northern Virginia's cloud corridor. The SEC scrutinizes algorithmic lending decisions for fairness disclosures, elevating explainability requirements in credit-decision workflows. New York's financial services sector concentrates no-code underwriting platform adoption among mid-market fintech challengers.
Germany
Industrial manufacturers embed real-time procurement synchronization into multi-tier supplier networks across Bavaria and Baden-Württemberg. The EU AI Act mandates human oversight protocols for automated supply chain decisions, compressing vendor compliance timelines. Stuttgart's automotive clusters pilot neural-symbolic hybrid architectures for diagnostic triage where clinical staff require causal reasoning traces.
United Kingdom
Financial services firms in the City of London unbundle decision engines from core banking systems to optimize per-transaction inference economics. The FCA's operational resilience requirements intersect with EU AI Act extraterritorial effects for firms serving European clients. Cambridge's AI research corridor supplies behavioral science talent for choice architecture and cognitive bias modeling.
France
Healthcare providers in the Île-de-France region compress triage-to-treatment intervals for stroke protocols using AI-driven diagnostic layers. ANSM and CNIL oversight creates layered compliance requirements for clinical decision-support tools processing patient data. Paris-Saclay's research cluster anchors public-private partnerships for explainable AI architectures.
India
IT services exporters in Bengaluru and Hyderabad build decision intelligence capabilities for North American and European financial services clients. RBI guidelines on algorithmic lending transparency create domestic demand for audit-ready platforms. Mumbai's banking sector concentrates credit-decision velocity investments among private sector lenders.
Decision Intelligence Market Vendor Landscape
Concentration sits with established risk-scoring infrastructure providers and defense-sector federated data specialists. The vendor base spans three tiers: legacy analytics incumbents with compliance-ready platforms, no-code challengers targeting underwriting velocity, and classified-sector specialists sustaining multi-year government contracts. Strategic moves center on embedding governance modules natively for EU AI Act conformity and unbundling decision engines from core enterprise systems.
Among the established analytics infrastructure providers, FICO and Palantir Foundry exemplify divergent positioning archetypes. FICO occupies a position within credit-decision workflow anchoring across North American banking relationships. Palantir Foundry sits within the defense and intelligence tier where federated architectures sustain classified analytics pipelines. Taktile represents the no-code challenger archetype, extending fintech underwriting velocity without engineering bottlenecks.
| Leading Market Players |
|---|
| Decisions |
| Taktile |
| FICO |
| Palantir Foundry |
| Inrule |
| Pega |
| Nected |
| Stravito |
| Aera Technology |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation cycles for EU AI Act conformity assessments compress vendor pricing power while amplifying procurement leverage for healthcare and industrial buyers negotiating multi-year platform commitments. This lead-time compression concentrates margin pressure on mid-market SaaS providers lacking native governance modules, while enterprise vendors with pre-built compliance infrastructure capture premium pricing tiers.
Pricing Analysis
Volume-discount tiering structures separate enterprise deployments with dedicated inference clusters from mid-market SaaS tiers and usage-based pay-per-decision economy offerings. Three-tier pricing stratification across premium compliance-ready platforms, standard cloud-native configurations, and economy inference-only layers reflects divergent data residency and explainability requirements. Cost compression in standard tiers intensifies as Palantir Foundry and FICO anchor premium positioning with embedded governance. Mid-market manufacturers exhibit highest price sensitivity, prioritizing marginal per-transaction economics over upfront platform commitments.
Supply Chain Analysis
The United States and Germany anchor specialized compute infrastructure for classified analytics pipelines and FDA-validated clinical environments, while India supplies implementation and integration talent for North American and European financial services deployments. Cloud hyperscalers in Northern Virginia and Frankfurt's data center corridor feed from specialized chip architectures and sovereign data center investments. Single-source vulnerability concentrates in EU-based conformity assessment body capacity, creating bottlenecks for non-EU vendors seeking market access. Distribution runs through direct enterprise sales with systems integrator overlays for complex healthcare and defense implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification creates a regulatory inflection that separates compliance-ready platform vendors from displacement-vulnerable challengers, concentrating procurement decisions around explainability infrastructure and audit-ready architectures.
For Market Incumbents: Shield core banking and defense relationships by embedding EU AI Act governance modules natively before conformity assessment deadlines compress competitive windows. Expand vertical integration into specialized behavioral science talent pipelines through Cambridge and Paris-Saclay research partnerships, countering scarcity that constrains neural-symbolic hybrid deployment velocity. For New Entrants and Emerging Players: Differentiate on no-code decisioning layers targeting mid-market fintech challengers in Mumbai and London seeking credit-decision velocity without core banking system unbundling costs. Capture white-space in German industrial procurement synchronization where real-time supplier response optimization lacks incumbent saturation, deploying usage-based pricing to undercut perpetual license structures. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because regulatory divergence between European ex-ante frameworks and American sectoral enforcement patterns fragments product architectures and inflates engineering overhead for sub-scale vendors. Target acquisition archetypes: specialized explainability tooling firms with pre-built audit trail capabilities. Watch for FDA Software as a Medical Device pathway acceleration as inflection signal for healthcare diagnostic platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Native Governance Module Development | EU AI Act conformity assessments require embedded traceability documentation before European market access. |
| Neural-Symbolic Architecture Deployment | German healthcare providers pilot interpretable rule-neural ensembles for stroke triage protocols requiring causal reasoning traces. |
| Behavioral Science Talent Acquisition | Cambridge and Paris-Saclay research corridors supply scarce hybrid skill sets fusing machine learning with choice architecture. |
| Hybrid Cloud Sovereignty Configuration | German utilities and hospitals partition sensitive inference workloads on-premise while scaling training to public cloud. |
| Usage-Based Inference Pricing Launch | Mid-market manufacturers evaluate platforms on marginal per-transaction economics rather than upfront capital commitment. |
Methodological Framework
A spread of perspectives from platform engineering leads at cloud hyperscalers, compliance officers navigating EU AI Act implementation, healthcare CIOs deploying diagnostic decision support, and fintech underwriting heads converged on the working assumptions driving segmentation splits. Primary interviews with defense-sector procurement specialists and industrial automation directors in Bavaria combined with secondary validation from SEC algorithmic fairness disclosures, FDA Software as a Medical Device guidance documents, and ANSM clinical decision-support oversight frameworks. Bottom-up deployment volume estimates triangulated against top-down market sizing from enterprise software spending patterns.
Segmentation dimensions modeled span deployment architecture, end-user vertical, solution capability tier, and regional regulatory cluster across the projection horizon. Cloud-native, hybrid, on-premise, and multi-cloud configurations intersect with healthcare, BFSI, manufacturing, and retail procurement priorities. CAGRs derive from inference volume scaling curves and platform fee compounding dynamics. Forecast inputs include EU AI Act implementation timeline acceleration and FDA validation pathway duration for diagnostic-directed outputs.
Material uncertainties — regulatory enforcement intensity divergence, behavioral science talent pipeline constraints, and legacy ERP integration friction — sit outside the modeled envelope. Forecasts reflect assumptions about conformity assessment body capacity expansion and cloud hyperscaler sovereign data center investment pacing. Recalibration cycles align with material shifts in EU AI Act delegated act publications and FDA guidance document revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market