
 Global Artificial Intelligence in Stadium Market | 2026-2036
Global Artificial Intelligence in Stadium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in Stadium Market Foresight
The divergence between premium and commodity tiers in stadium AI is hardening around real-time inference latency and edge computing density. IBM Corporation leverages its Watson platform to anchor high-end installations requiring sub-50-millisecond response times for facial recognition entry gates. Cisco Systems competes on networking infrastructure that sustains 100,000 concurrent device connections during peak event loads.
Artificial intelligence in stadiums encompasses machine learning models, computer vision systems, and neural networks deployed to process video feeds, sensor data, and transactional information across distributed venue architectures, typically operating on GPU clusters with tensor processing units rated at 100+ teraflops for real-time analytics. Computer vision dominates current deployment value as venues retrofit legacy camera networks with AI-enabled analytics for occupancy counting and perimeter security. Cloud-based deployment grows fastest among mid-tier arenas seeking to avoid capital-intensive server farms, while edge computing captures margin pools in luxury venues demanding localized processing for low-latency fan experiences.
The FCC governs wireless spectrum allocation for stadium IoT mesh networks in the United States, while the EU AI Act imposes risk-classification requirements on automated crowd surveillance systems deployed across European venues. China's MIIT enforces GB standards for facial recognition accuracy in public assembly spaces, shaping product certification requirements for vendors entering that market. Stakeholders must monitor evolving biometric privacy litigation and its chilling effect on facial recognition deployment timelines.
Market Dynamics
Edge computing density requirements are compressing deployment timelines as venues race to localize inference workloads for sub-50-millisecond fan experiences, forcing infrastructure decisions before revenue models mature.
Growth Catalysts
- FIFA tournament cycles:Qatar and Saudi Arabia are accelerating stadium intelligence investments ahead of World Cup and NEOM project milestones, creating concentrated demand spikes for computer vision systems.
- FCC wireless infrastructure guidelines:US venues leverage spectrum allocation rules to deploy dense IoT mesh networks that enable real-time crowd analytics and connected fan services.
- GPU cluster performance thresholds:Venues now specify 100+ teraflop tensor processing capabilities as baseline for real-time video analytics, pulling forward refresh cycles for legacy camera networks.
Market Restraints
- Biometric privacy litigation:Facial recognition deployments face timeline freezes as courts in multiple jurisdictions adjudicate consent frameworks for public assembly surveillance.
- Capital intensity of edge infrastructure:Luxury venues absorbing GPU cluster costs create a two-tier market where mid-tier arenas delay upgrades pending cloud cost reductions.
- EU AI Act risk classification:Automated crowd surveillance systems face heightened compliance burdens in European venues, extending procurement cycles by 12-18 months.
Strategic Opportunities
- Cloud-based deployment models:Mid-tier arenas in Brazil and Mexico are bypassing capital-intensive server farms through subscription-based analytics platforms.
- Neural network compression techniques:Edge-optimized models are enabling inference on existing camera hardware, opening retrofit markets in aging European and North American venues.
- India's smart city infrastructure:Stadium intelligence projects piggyback on municipal digital transformation programs, accessing subsidized fiber and 5G backbone investments.
Industry Challenges
- Computer vision engineering talent scarcity:Venues struggle to recruit specialists capable of calibrating multi-camera networks for occlusion-resistant occupancy counting.
- Legacy analog camera integration:Retrofit projects face signal degradation and synchronization failures when bridging decades-old coaxial infrastructure with AI-enabled analytics backends.
- Cross-jurisdiction certification complexity:Vendors must navigate divergent facial recognition accuracy standards across China's MIIT, EU AI Act, and emerging US state-level biometric laws.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in Stadium Market |
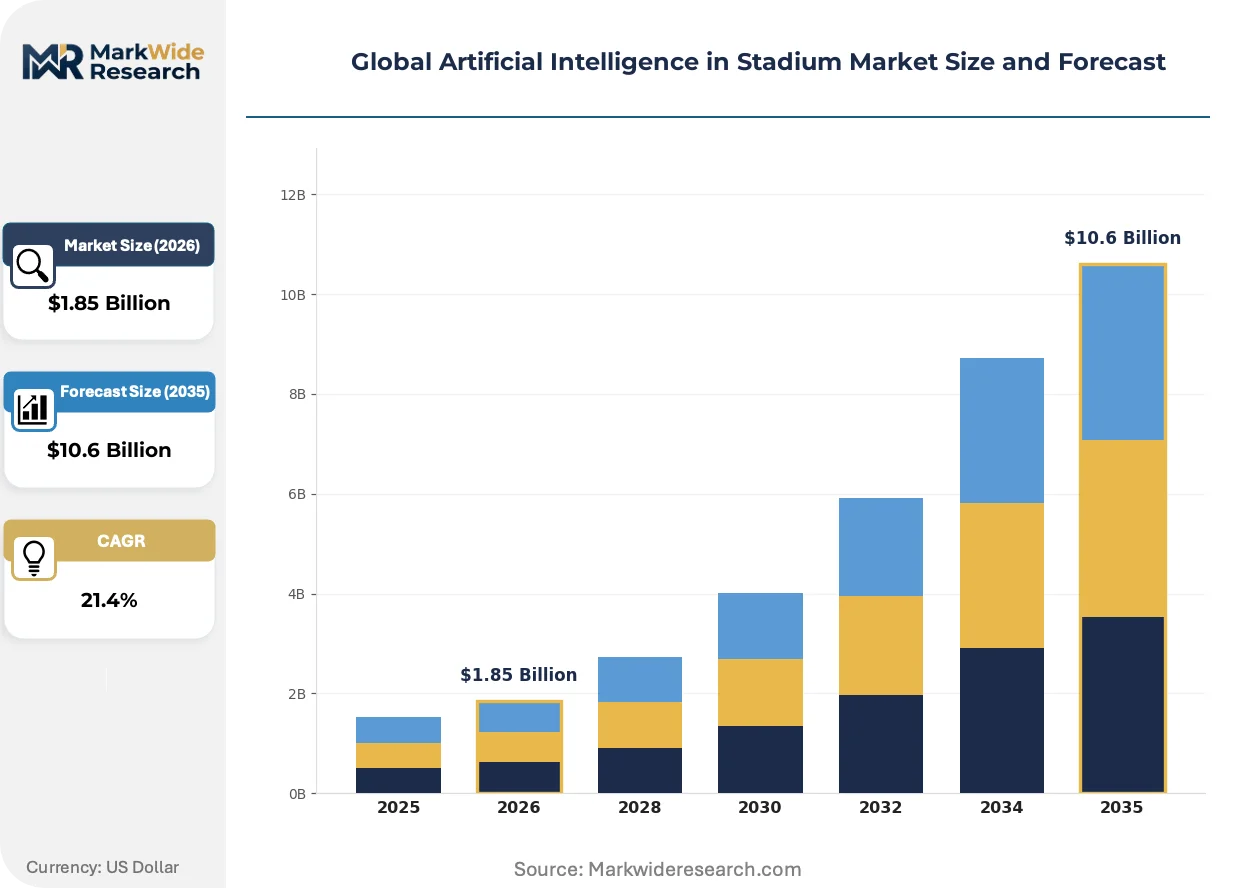
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Computer Vision, Natural Language Processing, Predictive Analytics, Neural Networks Application: Fan Engagement, Security & Surveillance, Crowd Management, Operational Efficiency, Ticketing Optimization Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Sports Venues, Entertainment Arenas, Event Management Companies, Facility Operators |
| Companies Covered | IBM Corporation, Cisco Systems, Intel Corporation, Microsoft Corporation, Ericsson AB, Fujitsu, Huawei Enterprise, Siemens AG, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in Stadium Market Shifts & Advancements
Computer vision architectures are fragmenting between cloud-native and edge-native deployment patterns, with venue operators making irreversible infrastructure bets based on latency requirements rather than total cost of ownership.
Neural network inference acceleration is converging with specialized tensor processing units deployed directly within camera housings. Sports venues in the United States and Germany are piloting these embedded systems for instant crowd density alerts. This convergence is compressing the traditional server room footprint and shifting vendor value capture toward semiconductor suppliers.
The EU AI Act's risk-classification framework for automated biometric identification is forcing European venues to segregate facial recognition data flows from general analytics pipelines. Stadium operators in France and Spain are now procuring dual-architecture systems that isolate high-risk processing. This regulatory architecture is favoring vendors with pre-certified compliance modules over point-solution providers.
Fan experience monetization models are unbundling hardware procurement from software licensing across Middle Eastern and Asian markets. Venue operators in Qatar and Japan are negotiating outcome-based contracts tied to concession throughput and security incident reduction. This shift is most visible in Gulf Cooperation Council countries where sovereign wealth vehicles prioritize operational expenditure structures over capital deployment.
Global Artificial Intelligence in Stadium Market Segmentation
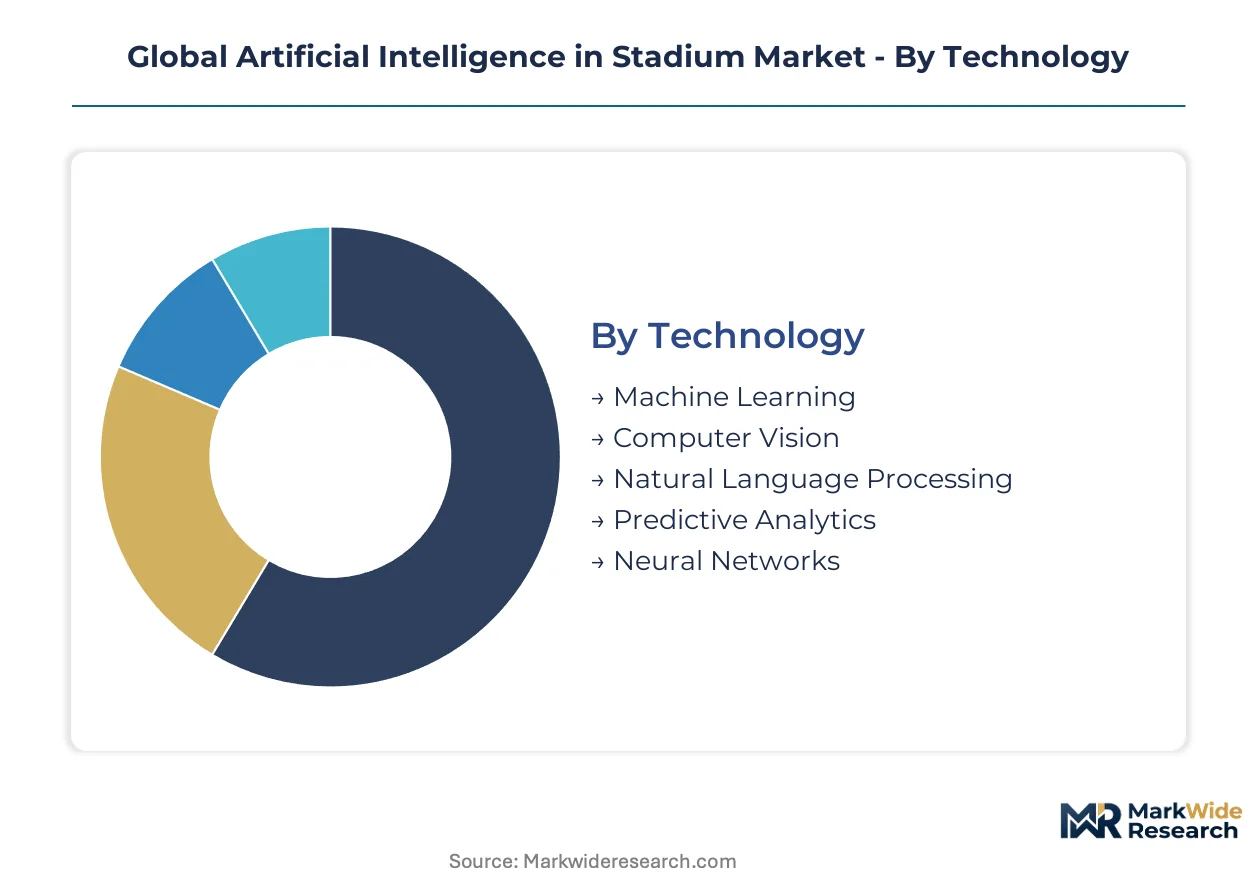
Stadium AI deployments fragment across integration depths, from standalone analytics modules to fully embedded inference engines. Understanding these technology-application-deployment intersections reveals where capital concentrates and which configurations deliver measurable operational returns.
Technology:
Integration depth varies sharply across this dimension, with some technologies operating as standalone platforms while others embed directly into camera hardware and sensor networks.
- Machine Learning:Algorithms process historical attendance patterns, concession sales, and weather data to forecast demand curves for staffing and inventory. Demand clusters in Saudi Arabia and Qatar where new-build venues specify predictive modules for FIFA tournament readiness.
- Computer Vision:Neural networks analyze video feeds for occupancy counting, perimeter intrusion detection, and facial recognition entry gates. Qatar's Lusail Stadium and Saudi Arabia's NEOM projects anchor near-term procurement volumes for multi-camera analytics suites.
- Natural Language Processing:Chatbots and voice interfaces handle fan queries in multiple languages during international events.
- Predictive Analytics:Models anticipate equipment failures in HVAC and lighting systems before match days.
- Neural Networks:Deep learning architectures power real-time video analysis at 100+ teraflop throughput thresholds.
Volume placements concentrate in Computer Vision; the faster expansion belongs to Neural Networks as edge-optimized architectures displace cloud-dependent processing.
Application:
Cost tier stratification separates premium venues investing in integrated security-fan experience platforms from mid-tier arenas prioritizing single-use operational tools.
- Fan Engagement:Personalized content delivery, augmented reality overlays, and dynamic concession routing enhance match-day experiences. Japan's Olympic legacy venues and Germany's Bundesliga stadiums drive demand for immersive technologies that monetize dwell time.
- Security & Surveillance:Biometric entry systems, behavioral anomaly detection, and automated perimeter monitoring protect high-profile events. EU AI Act compliance requirements in France and Spain extend procurement cycles for facial recognition deployments.
- Crowd Management:Real-time density mapping prevents dangerous congestion at exits and concourses.
- Operational Efficiency:Energy optimization and predictive maintenance reduce venue operating expenditures.
- Ticketing Optimization:Dynamic pricing algorithms adjust seat values based on opponent strength and real-time demand.
Capital deployment concentrates in Security & Surveillance; steepest expansion trajectory belongs to Fan Engagement as venues seek post-pandemic revenue recovery mechanisms.
Deployment:
Customer type determines architecture selection, with luxury venues absorbing edge infrastructure costs while mid-tier operators favor subscription-based cloud models.
- Cloud-Based:Subscription analytics platforms eliminate server farm capital expenditure for budget-constrained venues. Brazil and Mexico's mid-tier arenas bypass infrastructure ownership through software-as-a-service arrangements with vendors bearing GPU cluster costs.
- On-Premises:Dedicated server rooms host sensitive biometric data processing for venues prioritizing data sovereignty. Germany's Allianz Arena and Spain's Santiago Bernabéu maintain localized processing to satisfy GDPR and EU AI Act requirements.
- Hybrid:Split architectures process non-sensitive analytics in cloud while retaining biometric inference on-site.
- Edge Computing:Tensor processing units embedded directly in camera housings deliver sub-50-millisecond response times for instant crowd alerts.
Procurement volume concentrates in Cloud-Based deployments; the fastest share gains belong to Edge Computing as latency requirements harden for premium fan experiences.
End User:
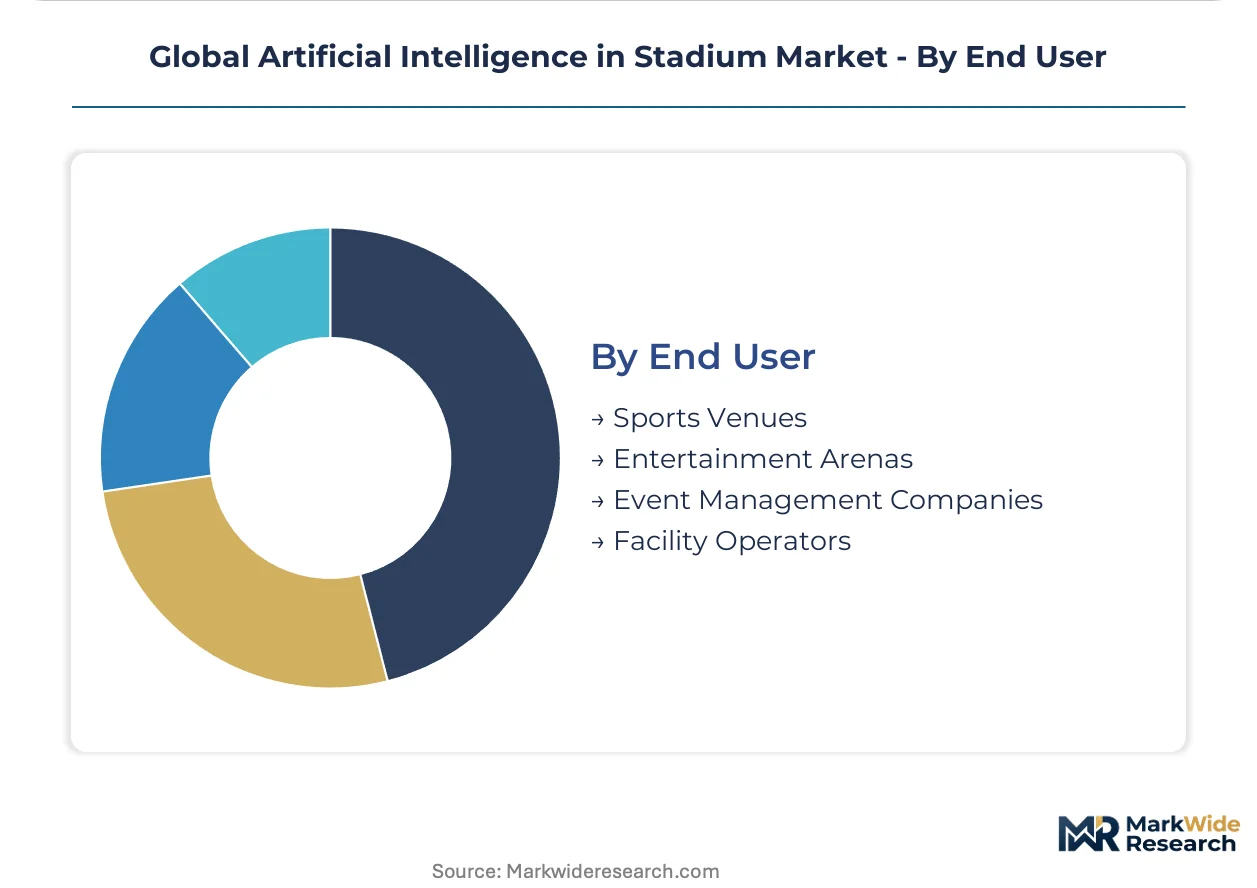
Supply concentration tracks toward sovereign wealth-backed developments in the Middle East and municipal-smart-city integrated projects in Asia.
- Sports Venues:Professional football and baseball stadiums specify integrated AI platforms spanning security, operations, and fan engagement. Qatar's FIFA World Cup infrastructure and Saudi Arabia's NEOM linear city project anchor concentrated demand for turnkey intelligence systems.
- Entertainment Arenas:Concert halls and multipurpose venues deploy flexible analytics for event-type switching. India's smart city initiatives subsidize fiber and 5G backbone investments that stadium intelligence projects piggyback upon.
- Event Management Companies:Temporary installations for tournaments and festivals rent AI-enabled surveillance and crowd analytics.
- Facility Operators:Third-party management firms standardize analytics across portfolios of mixed-use venues.
Investment flow concentrates in Sports Venues; Entertainment Arenas expand most quickly as India's urban digital transformation accelerates venue retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha and Riyadh anchor the concentrated demand surge for stadium intelligence systems, with sovereign wealth-backed developments in Qatar and Saudi Arabia driving procurement volumes for integrated AI platforms ahead of major sporting milestones.
United States
Professional sports venues in Texas and California deploy dense IoT mesh networks under FCC spectrum allocation guidelines for real-time crowd analytics. The FCC governs wireless infrastructure standards that enable 100,000 concurrent device connections during peak event loads. Dallas-Fort Worth and Los Angeles metropolitan clusters concentrate edge computing investments for sub-50-millisecond fan experience applications.
Germany
Bundesliga stadiums in Bavaria and North Rhine-Westphalia specify localized processing architectures to satisfy GDPR and EU AI Act requirements for biometric data handling. The EU AI Act imposes risk-classification burdens on automated crowd surveillance systems, extending procurement cycles by 12-18 months. Munich's Allianz Arena maintains dedicated server rooms for sensitive facial recognition inference.
China
Municipal smart city programs in Beijing-Tianjin-Hebei and Yangtze River Delta regions subsidize fiber and 5G backbone investments that stadium intelligence projects access. MIIT enforces GB standards for facial recognition accuracy in public assembly spaces, shaping vendor certification requirements. Shanghai and Shenzhen venues lead deployment of 100+ teraflop GPU clusters for real-time video analytics.
Japan
Olympic legacy venues in Tokyo and Osaka drive demand for immersive fan engagement technologies that monetize dwell time through augmented reality overlays. METI coordinates digital transformation subsidies that reduce capital barriers for mid-tier arena upgrades. Yokohama and Sapporo stadium clusters prioritize predictive analytics modules for HVAC and lighting system optimization.
India
Stadium intelligence projects in Maharashtra and Karnataka piggyback on municipal smart city infrastructure programs accessing subsidized fiber deployments. TRAI regulates spectrum allocation for venue IoT networks while state governments provide matching funds for digital transformation. Mumbai and Bangalore metropolitan regions concentrate procurement of subscription-based cloud analytics platforms.
Global Artificial Intelligence in Stadium Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software specialists across deployment architecture decisions, with venue operators selecting between GPU cluster ownership and subscription-based service models. The vendor base stratifies around three functional tiers: networking hardware specialists, cloud platform operators, and edge-optimized semiconductor suppliers. Consolidation pressures intensify as procurement cycles compress and certification requirements multiply across jurisdictions. Dominant competitive moves include strategic partnerships between camera manufacturers and AI software vendors, plus geographic expansion through FIFA tournament cycle alignment.
Within the integrated platform tier, IBM Corporation and Cisco Systems occupy anchor positions exemplifying divergent strategic approaches to venue intelligence. IBM's limited liability structure supports high-end installations requiring Watson-platform orchestration, while Cisco's systems specialization addresses networking density challenges at scale. Microsoft Corporation represents the cloud-native archetype, with its corporate structure enabling subscription-based deployment models that bypass capital-intensive server farm requirements for mid-tier venues. These three entities collectively illustrate the market's segmentation between edge-heavy and cloud-preferred customer profiles.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems |
| Intel Corporation |
| Microsoft Corporation |
| Ericsson AB |
| Fujitsu |
| Huawei Enterprise |
| Siemens AG |
| Alphabet Inc. |
| Others |
Supply & Pricing Matrix
Computer vision engineering talent scarcity in California and Germany widens pricing spreads between premium edge-computing installations and commodity cloud-based deployments, as venues absorb GPU cluster costs or defer to subscription models based on labor-intensive calibration requirements.
Pricing Analysis
Outcome-based contracts tied to concession throughput and security incident reduction anchor value-based pricing in Qatar and Saudi Arabia. Three-tier pricing structure across premium, standard, and economy levels separates venues specifying sub-50-millisecond latency from mid-tier arenas accepting cloud-delivered analytics. Price differentiation hinges on certification grade for EU AI Act compliance and edge-computing density requirements. Pricing pressure stems from neural network compression techniques enabling inference on legacy camera hardware, eroding margins for full-stack replacements. Mid-tier venues in Brazil and Mexico exhibit highest price sensitivity, while sovereign wealth-backed developments in the Gulf show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced tensor processing units rated at 100+ teraflops, constraining venue infrastructure timelines when semiconductor foundry capacity tightens. GPU clusters, specialized camera sensors, and fiber-optic backbone equipment draw from concentrated manufacturing bases in China, Germany, and Japan. Supply chain risk centers on tariff exposure for networking hardware crossing multiple jurisdictions during FIFA tournament-driven demand spikes. Distribution runs through systems integrators holding Cisco and IBM certifications, with venue operators procuring turnkey platforms rather than discrete components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework for automated biometric identification erects a compliance moat that favors pre-certified vendors over point-solution providers, raising capital barriers for entrants lacking dedicated regulatory affairs capabilities.
For Market Incumbents: To counter neural network compression techniques eroding full-stack replacement demand, deepen backward integration into edge-optimized semiconductor supply and expand certification investment for dual-architecture systems that isolate high-risk biometric processing from general analytics pipelines.
For New Entrants and Emerging Players: Begin with subscription-based cloud analytics platforms targeting mid-tier arenas in Brazil and Mexico, where capital constraints and municipal smart city subsidies create white-space opportunity outside sovereign wealth-backed premium installations.
For Investors and Strategic Acquirers: Re-rating potential sits with edge-native semiconductor suppliers given convergence of tensor processing units embedded directly in camera housings. Long-term viability favors vendors with pre-certified EU AI Act compliance modules. Watch FIFA tournament procurement cycles as inflection indicators for demand concentration in Qatar and Saudi Arabia.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Semiconductor Development | Embedded tensor processing units in camera housings compress server room footprints for German and US venues. |
| EU AI Act Pre-Certification Investment | Dual-architecture systems that segregate biometric data flows capture procurement cycles in France and Spain. |
| Outcome-Based Contract Structuring | Concession throughput and security incident metrics align vendor compensation with operational results in Gulf markets. |
| Neural Network Compression R&D | Edge-optimized models enabling retrofit on legacy hardware open aging European and North American venue markets. |
| Municipal Smart City Partnership | Piggybacking on subsidized fiber and 5G backbone investments reduces capital barriers in Indian metropolitan regions. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and venue infrastructure procurement databases formed the secondary backbone, combined with primary interviews across stadium technology directors, IoT network engineers, and sports venue procurement managers. Primary fieldwork captured edge-computing deployment timelines and cloud migration decisions across North American, European, and Middle Eastern venues. Bottom-up and top-down triangulation validated vendor revenue allocations and venue capital expenditure patterns.
Bottom-up modeling tracked individual venue installations by technology tier, deployment architecture, and application intensity, while top-down analysis cross-checked against aggregate FIFA tournament investment cycles and municipal smart city budget flows. Segmentation dimensions spanned technology integration depth, deployment model, end-user type, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and refresh cycle compression for legacy camera networks, incorporating GPU performance threshold specifications and latency requirements as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than edge-computing installations where proprietary vendor disclosures remain limited. Forecasts reflect assumptions about tournament cycle timing, biometric privacy litigation trajectories, and semiconductor foundry capacity allocation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
AI-Ready Enterprise Knowledge Graph Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Global Insight Engines Market
Artificial Intelligence (AI)
AI in Retail Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Europe AI Orchestration Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market