
 Hotel Management Software Market | 2026-2036
Hotel Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hotel Management Software Market Analysis
The gap between premium all-in-one suites and stripped-down commodity tools is shifting as mid-market hoteliers reject fragmented point solutions. Cloudbeds leverages multi-property orchestration to sustain cross-portfolio revenue management dominance. SiteMinder anchors its position through deep channel connectivity across online travel agencies. Mews differentiates via API-first architecture that competes with legacy property management system incumbents.
Hotel management software comprises integrated digital platforms that automate front desk operations, reservation handling, billing reconciliation, and guest communication through centralized databases accessible via web or mobile interfaces. These systems serve the commercial purpose of reducing manual administrative burden while enabling real-time pricing adjustments across distribution channels. Cloud-based deployment leads the service type landscape due to lower capital barriers for small hotels, while revenue management functionality captures disproportionate margin pools as hoteliers prioritize dynamic pricing capabilities. Channel management retains structural importance despite maturity, as connectivity to booking engines remains operationally critical.
FDA oversight of hospitality-related health data interfaces, GDPR data localization mandates from European regulators, and PCI-DSS payment security standards collectively shape product development roadmaps and vendor certification requirements. The EU AI Act's risk classification framework for automated guest-facing systems is forcing platforms to embed algorithmic transparency features. Stakeholders must monitor how emerging interoperability standards between property management and smart building systems redefine competitive moats.
Market Dynamics
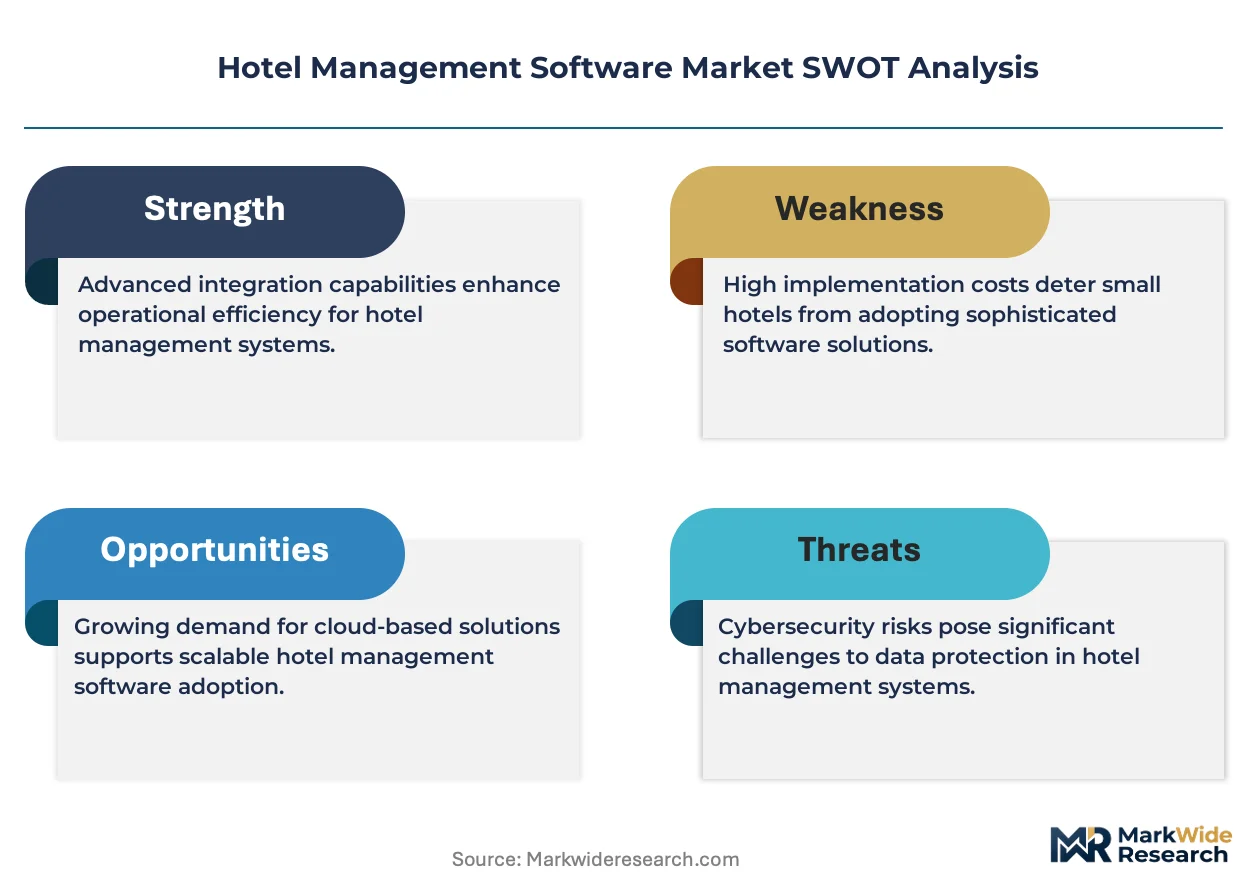
Mid-scale hotel chains are rejecting fragmented point solutions in favor of unified cloud platforms, compressing vendor margins and forcing consolidation among legacy property management system providers.
Growth Catalysts
- GDPR data localization mandates:European regulators require guest data residency, accelerating investment in regional cloud infrastructure by software vendors serving German and French hotel markets.
- Dynamic pricing algorithms:Revenue management modules embedded within integrated suites are automating rate adjustments across online travel agencies, driving replacement demand for standalone channel managers.
- Independent boutique expansion:Small hotel chains in Portugal and Greece are adopting multi-property orchestration tools to centralize operations without enterprise-scale IT departments.
Market Restraints
- PCI-DSS compliance costs:Payment security certification requires ongoing audit expenditure that disproportionately burdens sub-50-room properties evaluating platform migration.
- Legacy system entrenchment:Decades-old on-premise installations at established resorts create data migration friction and contractual lock-in extending 3-5 years.
- Skilled implementation scarcity:Shortage of certified hospitality technology integrators in secondary markets delays deployment timelines and inflates professional services fees.
Strategic Opportunities
- EU AI Act algorithmic transparency:Automated guest-facing systems must embed explainability features, creating first-mover advantage for vendors with pre-built compliance architectures.
- Smart building convergence:Integration between property management platforms and IoT-enabled energy management systems opens new subscription revenue streams in Nordic markets.
- Mobile-first guest journeys:Contactless check-in and digital key distribution capabilities remain underdeployed in Eastern European mid-scale segments.
Industry Challenges
- API standardization delays:Lack of universal interoperability protocols between channel managers and central reservation systems forces costly custom integration work.
- Cybersecurity skill gaps:Hospitality IT teams lack expertise in zero-trust architecture implementation required by emerging insurer mandates for cyber coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hotel Management Software Market |
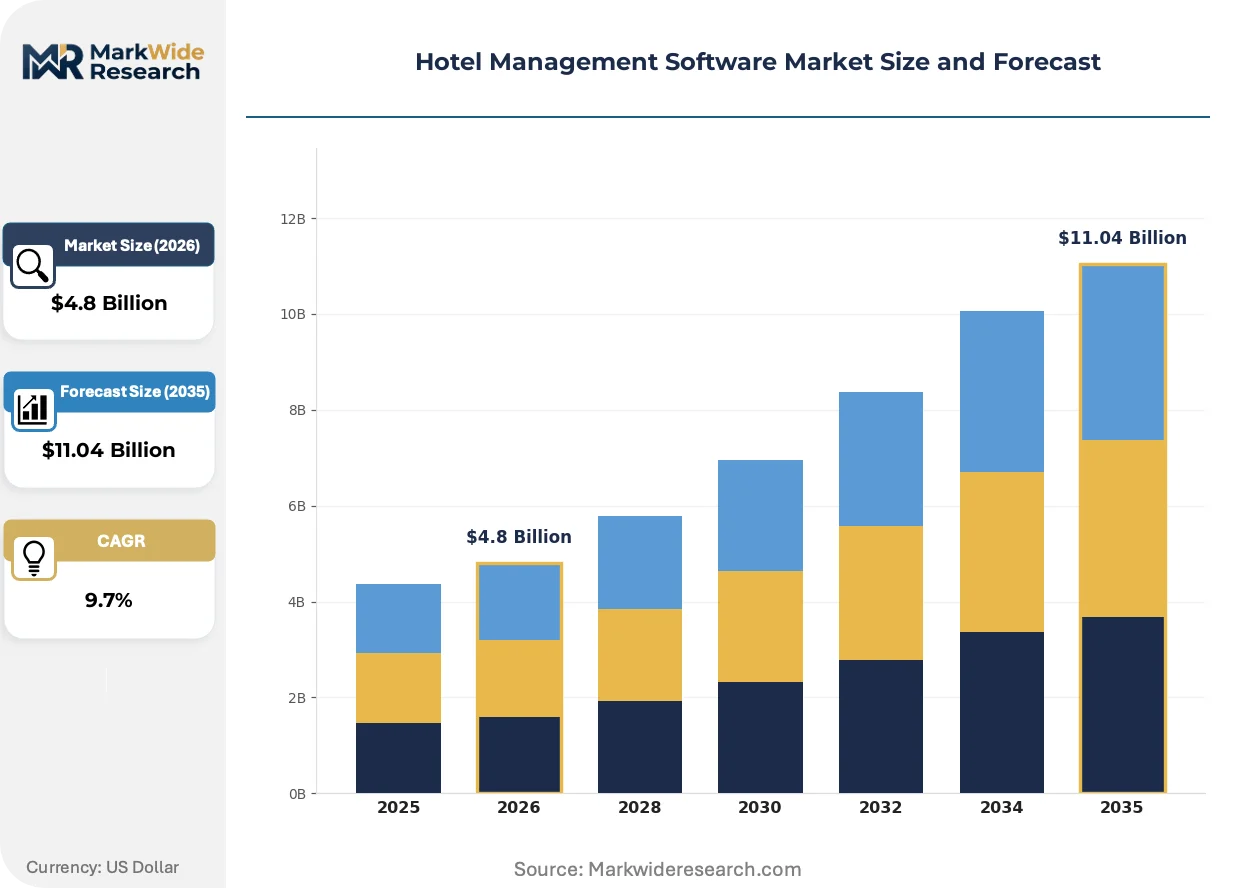
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Multi-tenant Service Type: Property Management, Channel Management, Booking Engine, Revenue Management End User: Small Hotels, Luxury Resorts, Boutique Hotels, Hostels Functionality: Front Desk Management, Housekeeping, Reporting, Customer Relationship Management |
| Companies Covered | Seekda Sphere, RoomRaccoon, Cloudbeds, SiteMinder, Amenitiz, Mews, eZee FrontDesk, eviivo, Oracle Opera Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hotel Management Software Market Emerging Trajectories
Artificial intelligence and embedded connectivity are compressing the functional boundary between property operations and guest-facing services, redefining competitive differentiation.
Machine learning revenue optimization engines are automating demand forecasting and rate parity enforcement across distribution channels. Mid-scale hotel groups in Spain and Italy are deploying these tools within 18-month implementation cycles. The technology is automating previously manual revenue manager workflows, reducing headcount requirements at portfolio-level operations centers.
GDPR Article 44 cross-border data transfer restrictions are forcing vendors to establish EU-based processing infrastructure. This regulatory pressure is elevating operational costs for US-headquartered platforms while creating structural advantage for European-native providers. German hotel associations are negotiating collective certification frameworks to reduce individual compliance burden.
Subscription-based procurement models are displacing perpetual license arrangements among independent properties. Small hotel owners in Austria and Switzerland now prioritize operational expenditure predictability over capital ownership. This shift favors cloud-native vendors with usage-based pricing tiers aligned to seasonal occupancy fluctuations.
Hotel Management Software Market Segmentation
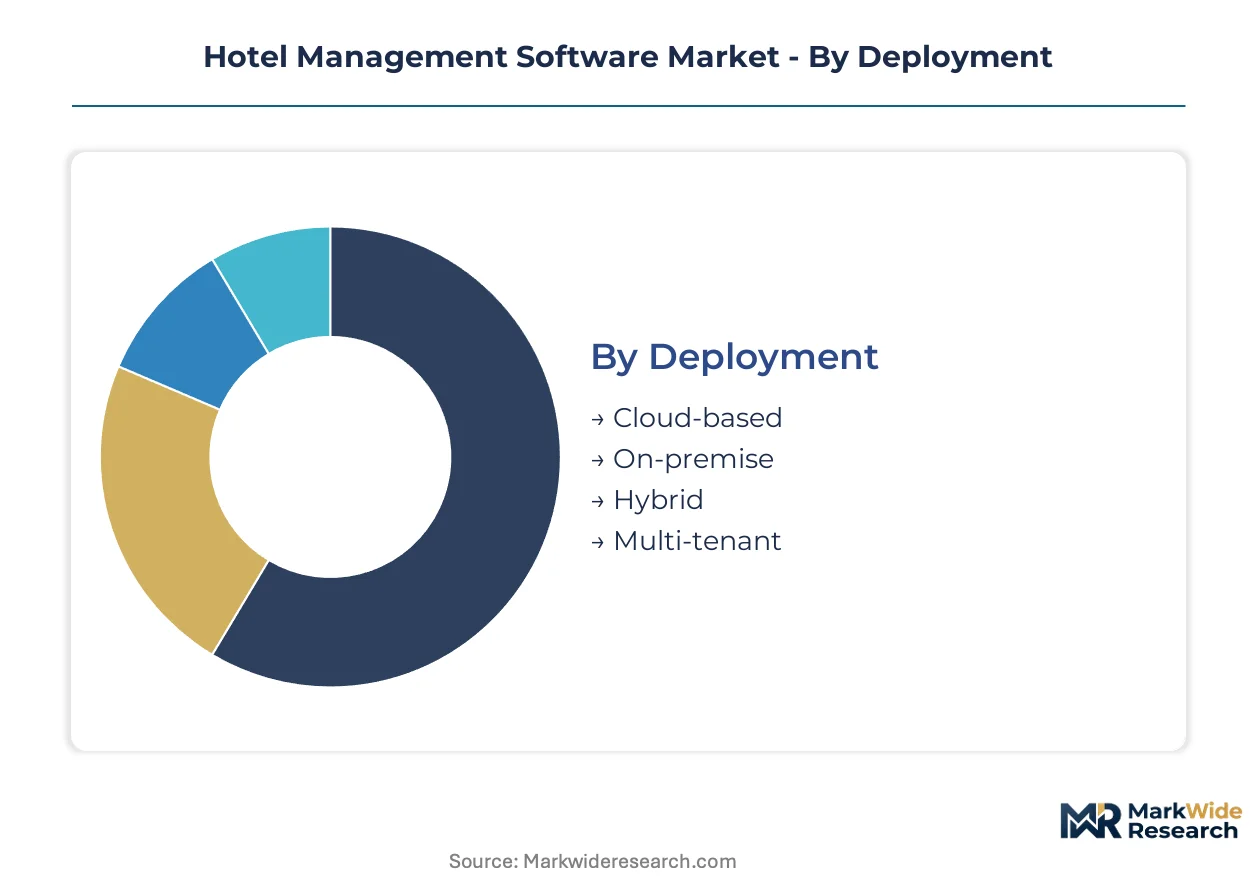
Deployment architecture determines capital efficiency and compliance posture for hotel operators navigating GDPR data residency mandates. Service type selection reflects whether properties prioritize operational consolidation or specialized revenue optimization capabilities.
Deployment:
Cloud infrastructure specifications differentiate vendor competitiveness across European data sovereignty requirements.
- Cloud-based:Web-accessible platforms with automatic updates eliminate server maintenance overhead. German mid-scale chains favor these systems for GDPR-compliant regional hosting that satisfies Article 44 transfer restrictions without on-premise hardware investment.
- On-premise:Locally installed software maintains direct data control within property boundaries. Established Alpine resorts in Switzerland and Austria retain these deployments due to legacy integration with proprietary ski-lift booking systems and conservative IT procurement cycles.
- Hybrid:Split architectures keep sensitive guest data local while pushing analytics workloads to cloud environments. Portuguese boutique collections deploy this model to balance PCI-DSS audit scope reduction with dynamic pricing flexibility.
- Multi-tenant:Shared infrastructure instances serve multiple properties through isolated database partitions. Greek island hotel cooperatives leverage this approach for centralized yield management across dispersed seasonal operations.
Cloud-based deployments lead on scale; multi-tenant configurations are gaining share fastest among independent consortia.
Service Type:
Functional module selection tracks where properties extract measurable ROI from automation investments.
- Property Management:Core platforms integrating reservations, billing, and guest profiles through unified databases. Spanish hotel groups prioritize these systems for housekeeping coordination across multi-property portfolios with centralized operations centers.
- Channel Management:Distribution connectivity layers synchronizing inventory and rates across online travel agencies. Italian coastal properties depend on these tools for rate parity enforcement against booking engine commission erosion.
- Booking Engine:Direct reservation interfaces embedded within property websites. Nordic urban hotels deploy white-label solutions to reduce OTA dependency and capture guest data for loyalty program cultivation.
- Revenue Management:Algorithmic pricing engines forecasting demand patterns and automating rate adjustments. French business hotel clusters invest disproportionately here to compete against automated competitor rate monitoring.
Property Management anchors volume concentration; Revenue Management commands premium pricing expansion.
End User:
Property scale and service positioning shape software procurement priorities and implementation complexity tolerance.
- Small Hotels:Sub-50-room independent properties with limited IT staffing. Austrian family-run establishments select cloud platforms with minimal configuration requirements and predictable monthly subscription structures.
- Luxury Resorts:High-service properties requiring extensive guest preference tracking and bespoke experience orchestration. Swiss alpine destinations integrate spa, dining, and activity reservations through unified guest journey platforms.
- Boutique Hotels:Design-focused independent properties emphasizing differentiated brand expression. Lisbon and Porto operators prioritize API-first systems enabling custom mobile app development for contactless check-in workflows.
- Hostels:Budget accommodations with high bed turnover and communal space management needs. Berlin and Prague operators favor bed-level inventory granularity and automated group booking handling.
Small Hotels dominate transaction volume; Boutique Hotels are expanding procurement fastest as design-led chains multiply.
Functionality:
Operational workflow automation depth determines staff productivity gains and guest satisfaction measurement capabilities.
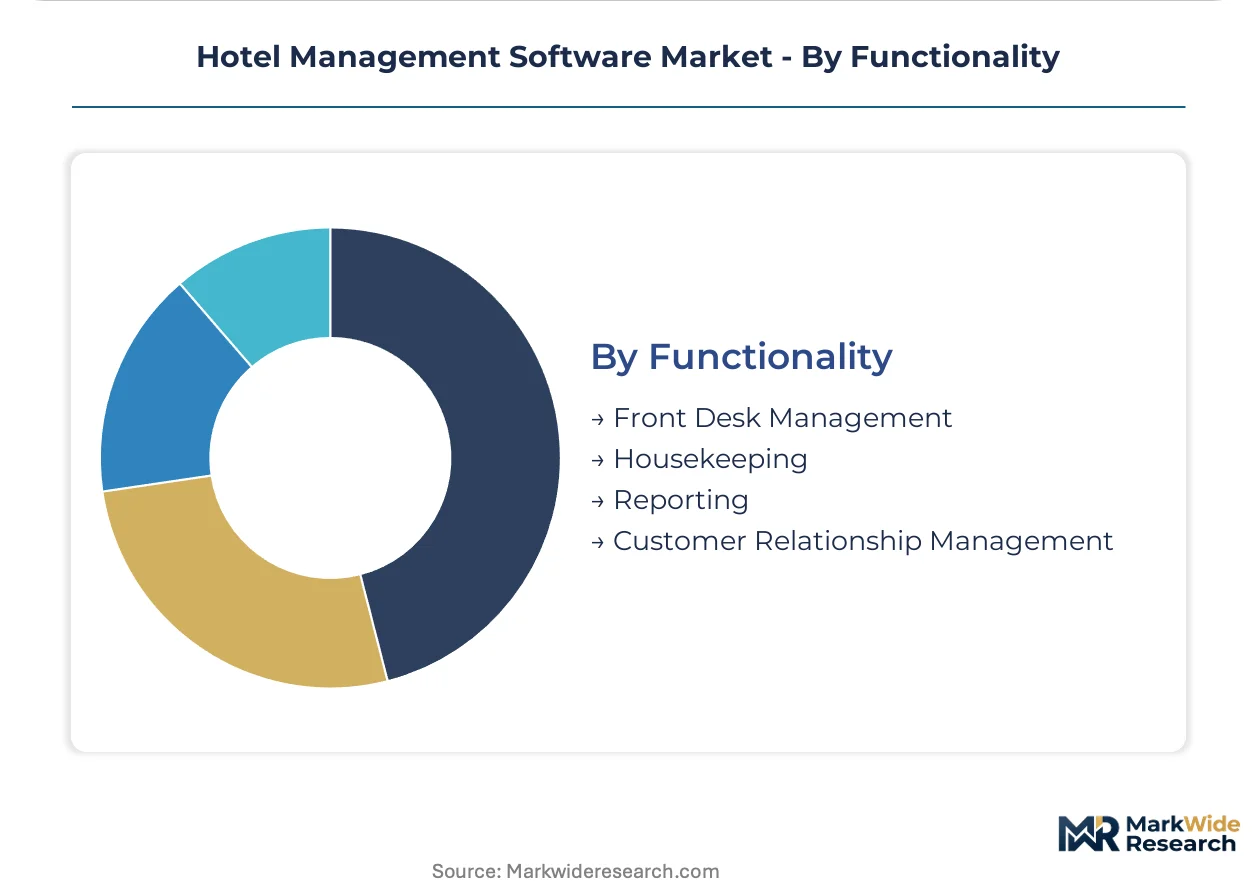
- Front Desk Management:Check-in/check-out processing, room assignment, and payment handling interfaces. Dutch city center properties deploy tablet-based kiosks to reduce reception staffing during low-occupancy periods.
- Housekeeping:Room status tracking, maintenance ticketing, and staff scheduling coordination. Irish country house hotels use mobile-first modules to synchronize turndown service timing with guest dinner reservations.
- Reporting:Financial reconciliation, occupancy analytics, and operational KPI dashboards. Belgian chain operators consolidate these outputs for franchisee performance benchmarking and royalty calculation verification.
- Customer Relationship Management:Guest history storage, preference profiling, and targeted marketing automation. Croatian coastal resorts leverage these capabilities for repeat visitor pre-arrival upselling of boat excursion packages.
Front Desk Management retains the widest installed base; Customer Relationship Management shows the steepest expansion trajectory as direct booking strategies intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany scales mid-scale hotel digitization faster than France, where boutique consolidation lags by roughly two years. The EU AI Act and GDPR Article 44 reshape vendor infrastructure investments across distinct national regulatory enforcement patterns.
Germany
Mid-scale hotel chains in Bavaria and North Rhine-Westphalia drive integrated property management platform procurement. The Federal Data Protection Authority enforces GDPR data localization with particular rigor, forcing US-headquartered vendors to establish Frankfurt-based processing centers. Berlin's hotel technology cluster concentrates implementation specialists serving Central European independent consortia.
France
Business hotel clusters around Paris and Lyon prioritize revenue management automation against OTA commission erosion. The CNIL coordinates with hotel federations on collective GDPR certification frameworks to reduce individual compliance burden. Provence-Alpes-Côte d'Azur resorts integrate spa and dining reservations through unified guest journey platforms.
United Kingdom
London's urban hotel density accelerates mobile-first guest journey deployment including contactless check-in. The Information Commissioner's Office mandates algorithmic transparency documentation for automated pricing systems under emerging AI governance guidance. Edinburgh and Manchester boutique chains adopt API-first architectures for custom mobile app development.
Spain
Coastal properties in Catalonia and Andalusia depend on channel management tools for rate parity enforcement against booking engine commission pressure. Spanish data protection authorities align with EU AI Act risk classification timelines for automated guest-facing systems. Madrid-based hotel groups centralize housekeeping coordination across multi-property portfolios.
Italy
Italian hospitality clusters in Lombardy and Veneto deploy revenue management modules within 18-month implementation cycles. The Garante per la Protezione dei Dati Personale enforces cross-border data transfer restrictions that elevate regional cloud infrastructure requirements. Tuscan agriturismo cooperatives leverage multi-tenant configurations for centralized yield management across dispersed seasonal operations.
Hotel Management Software Market Vendor Landscape
Top-tier vendors anchor integrated cloud suites, while regional specialists occupy API-first and channel-connectivity niches. The market structure compresses toward unified platforms as mid-scale chains reject fragmented point solutions. Three archetypes dominate: legacy property management system incumbents, cloud-native API-first challengers, and distribution-focused connectivity layers. Consolidation pressure forces M&A activity among on-premise heritage providers, while vertical integration into adjacent revenue management modules accelerates.
Among cloud-native challengers, Cloudbeds and Mews exemplify the API-first archetype competing against legacy incumbents. SiteMinder anchors the distribution-focused tier through deep channel connectivity across online travel agencies. These three companies occupy positions that reflect the market's structural shift from fragmented point solutions toward unified orchestration platforms.
| Leading Market Players |
|---|
| Seekda Sphere |
| RoomRaccoon |
| Cloudbeds |
| SiteMinder |
| Amenitiz |
| Mews |
| eZee FrontDesk |
| eviivo |
| Oracle Opera Cloud |
| Others |
Supply Flow & Price Mechanics
Certified hospitality technology integrators in Berlin and Barcelona command wage premiums that compress margins for implementation services, widening the spread between self-service SaaS tiers and white-glove enterprise deployments. Labor-cost differentials between Western European implementation hubs and emerging Eastern European delivery centers create arbitrage opportunities for vendors restructuring professional services networks.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the Hotel Management Software Market. Subscription-based SaaS tiers dominate procurement among independent properties, with pricing stratifying across premium API-first suites, standard integrated platforms, and economy channel-manager-only configurations. Cost compression in the economy tier stems from open-source alternatives and freemium entry points. Small hotel proprietors exhibit acute price sensitivity, while luxury resort operators prioritize customization depth over license expenditure.
Supply Chain Analysis
Cloud infrastructure provision rests on hyperscale data center operators concentrated in Germany, Ireland, and the Netherlands. Software development draws from engineering talent pools in Portugal, Poland, and Romania. API middleware and payment gateway integrations hinge on specialized fintech vendors. Single-source vulnerability concentrates in channel manager connectivity to dominant online travel agencies. Distribution runs through direct vendor sales, regional system integrators, and hospitality technology consultants serving property clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play. GDPR compliance costs in Germany run substantially higher than equivalent regulatory burdens in Portugal, creating margin expansion for vendors with Lisbon-based development centers serving Northern European deployment.
For Market Incumbents: Deepen API-first architecture investments to neutralize Mews and Cloudbeds differentiation. Acquire boutique channel manager specialists in Mediterranean markets before consolidation windows close. Legacy property management system incumbents face displacement from cloud-native challengers; backward integration into revenue management algorithm development defends pricing power.
For New Entrants and Emerging Players: Eastern European mid-scale hotel chains represent the most penetrable buyer archetype. Mobile-first guest journey capabilities remain underdeployed in Budapest and Prague property clusters. White-label booking engine partnerships with regional hospitality consortia offer low-friction market entry without direct enterprise sales infrastructure.
For Investors and Strategic Acquirers: Private equity firms specializing in vertical software are the most active acquirer in this space. Five-to-ten year viability hinges on vendor ability to orchestrate multi-property portfolios rather than single-site installations. Acquisition targets should demonstrate pre-built EU AI Act compliance architectures. Algorithmic transparency mandate enforcement timelines serve as the critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables custom mobile app development for Lisbon boutique hotel contactless check-in workflows. |
| EU AI Act Compliance Architecture | Embeds explainability features for automated revenue management systems before regulatory deadlines. |
| Regional Cloud Infrastructure Expansion | Establishes Frankfurt processing centers satisfying GDPR Article 44 data localization mandates. |
| Revenue Management Module Development | Captures premium pricing from French business hotel clusters competing against OTA rate parity erosion. |
| Smart Building System Partnership | Opens subscription revenue streams through IoT-enabled energy management integration in Nordic markets. |
Methodological Framework
Direct dialogue with hotel technology procurement officers, certified hospitality system integrators, revenue management directors, and property operations executives grounded qualitative insights. Secondary validation drew from SEC filings of listed hospitality technology vendors, EU regulatory filings documenting GDPR enforcement patterns, German hotel association digitization program disclosures, and channel manager connectivity benchmark reports. Bottom-up property-level deployment estimates and top-down vendor revenue aggregation underwent cross-triangulation.
Bottom-up modeling tracked deployment architecture, service type, and end-user scale across national hotel property registers. Top-down analysis validated aggregate vendor revenue disclosures against modeled market size. Segmentation dimensions included deployment model, property size tier, functional module integration complexity, and regional adoption intensity. CAGRs derived from logistic diffusion curves fitted to historical cloud migration patterns and regulatory compliance investment cycles. Forecast inputs incorporated EU AI Act implementation timelines and mid-scale hotel chain consolidation trajectories.
Underlying measurement precision varies by segment; cloud-based deployment estimates carry tighter precision than hybrid architecture projections given vendor disclosure granularity. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and property technology refresh cycles. Cybersecurity incident frequency, OTA commission structure shifts, and hospitality labor market volatility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Computer Software Market
Software & Services
Language Translation Software Market
Software & Services
Sales Training and Onboarding Software Market
Software & Services
India Sports Management Software Market
Software & Services
Global Data Recovery Software Market
Software & Services
Server Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
Test Management Software Market
Software & Services
Global Database Management Software Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Global Online Proofing Software Market
Software & Services
Feedback Management Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Hypervisor Market
Software & Services
Multiexperience Development Platforms Market
Software & Services
Enterprise Performance Management (EPM) Software Market