
 Vanity Mirror Market | 2026-2036
Vanity Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Vanity Mirror Market Analytics
Multi-source component procurement is restructuring supply relationships across the vanity mirror industry. Fresca Bath leverages integrated glass sourcing and metal finishing to control cost volatility. Electric Mirror sustains technology leadership in LED-illuminated systems for hospitality specification channels. Simplehuman differentiates through sensor-activated feature sets targeting premium residential renovation projects.
A vanity mirror is a reflective glass surface, typically silver-backed through chemical deposition, mounted within a frame and often incorporating integrated lighting, magnification, or environmental compensation such as anti-fog heating elements; specifications commonly span 5x to 10x magnification ratios and color-rendering indices above 90 for cosmetic accuracy. Wall-mounted units dominate commercial installations where permanent fixture integration drives replacement cycles, while portable segments capture travel and professional makeup artist demand with rechargeable LED power systems. Metal-framed variants anchor luxury positioning in hospitality procurement, whereas acrylic surfaces compete on weight reduction for shipping-intensive e-commerce channels.
CE marking governs electrical safety for illuminated mirrors entering European distribution, while the EU F-Gas Regulation pressures manufacturers to phase legacy refrigerant-based anti-fog systems toward resistive heating alternatives. The US FDA exercises indirect oversight through cosmetic device adjacent classifications for magnifying mirrors with medical-adjacent claims. Stakeholders must monitor evolving energy-efficiency labeling requirements and raw material disclosure mandates as procurement criteria harden across institutional buyer segments.
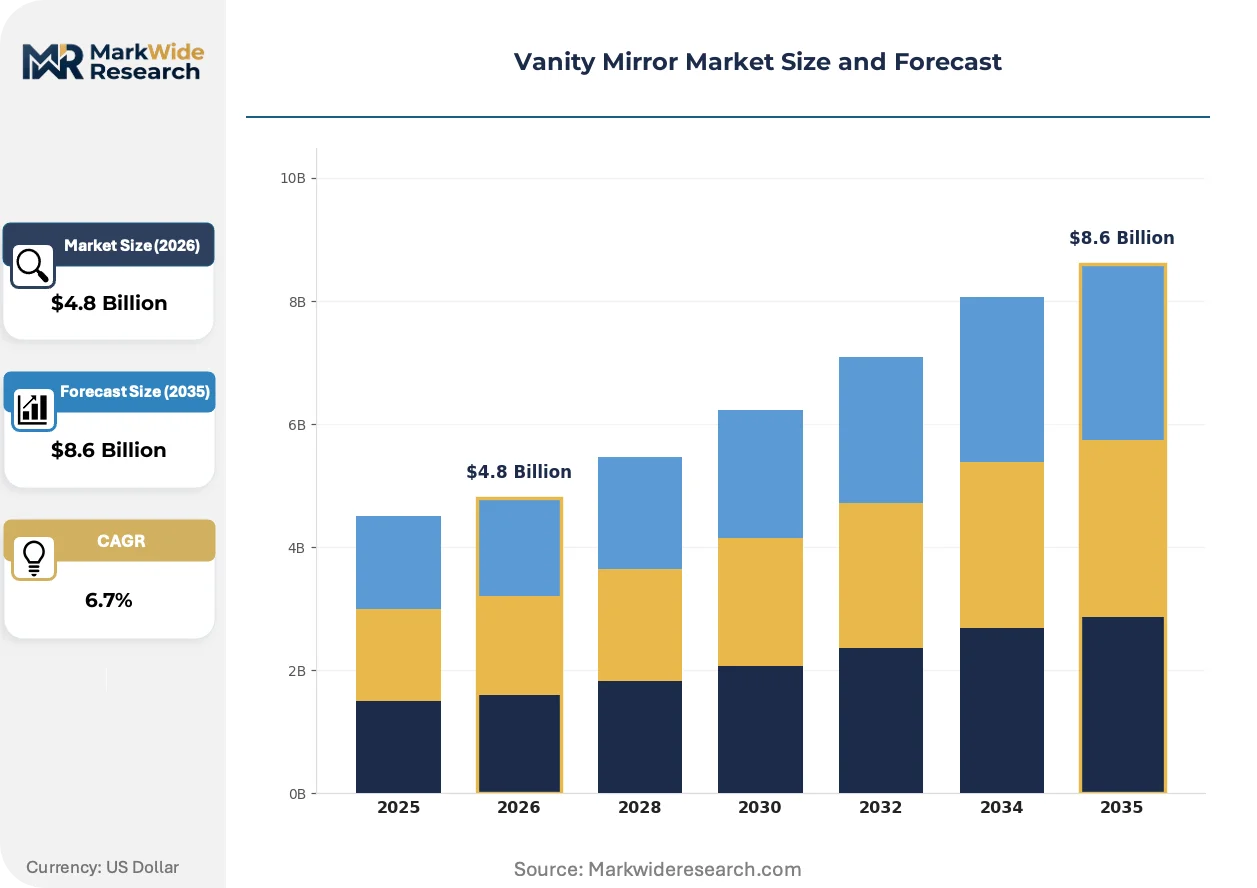
Market Dynamics
Hotel bathroom renovation cycles are compressing from ten-year intervals to five-to-seven-year refresh programs, pulling LED-illuminated mirror demand forward and reshaping manufacturer capacity planning.
Growth Catalysts
- REACH compliance deadlines:European chemical safety mandates for mirror backing adhesives are accelerating reformulation investments, filtering out marginal suppliers and consolidating procurement toward certified manufacturers.
- Hospitality specification channels:Luxury hotel chains in Dubai, Singapore, and Miami are standardizing anti-fog heated mirrors across guest room portfolios, creating predictable replacement pipelines.
- Silver deposition automation:Chemical mirror coating lines in Chinese manufacturing clusters are achieving yield improvements that lower unit costs for export-grade products.
Market Restraints
- Float glass input volatility:Energy-intensive flat glass production faces natural gas price spikes, compressing margin structures for framed mirror assemblers without backward integration into glassmaking.
- Supply concentration in Zhejiang and Guangdong:Domestic manufacturing clusters control seventy percent of global vanity mirror exports, exposing buyers to single-region disruption risks from port congestion or power rationing.
- EU F-Gas Regulation phase-out:Legacy refrigerant-based anti-fog systems face mandatory replacement timelines, stranding inventory for distributors with slow-moving hospitality stock.
Strategic Opportunities
- Professional makeup artist channels:Portable rechargeable LED mirrors with 95+ CRI ratings command price premiums in Los Angeles, London, and Seoul content-creation economies.
- Resistive heating convergence:Integration of thin-film heating elements with IoT-enabled humidity sensors opens specification paths in smart home renovation projects.
- India BIS certification expansion:Mandatory quality standards for electrical luminaires are creating first-mover advantages for LED mirror suppliers establishing testing partnerships.
Industry Challenges
- Optical coating technician scarcity:Silver nitrate deposition processes require specialized clean-room skills that vocational programs in manufacturing regions have not scaled to match demand.
- Multi-certification timelines:Simultaneous UL, CE, and SASO approval processes for illuminated mirrors extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanity Mirror Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Tabletop, Portable, Magnifying Material: Glass, Acrylic, Metal, Wood Feature: LED Illumination, Touch Sensor, Adjustable Angles, Anti-Fog Customer Type: Retail Consumers, Hospitality, Salons, E-Commerce |
| Companies Covered | Fresca Bath, Chende, Duravit, Electric Mirror, Waneway, Moen, Simplehuman, Majestic Mirror & Frame Manufacturer, Jerdon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanity Mirror Market Evolving Landscape
Sensor-activated feature sets are migrating from premium residential segments into mid-market hospitality specifications, compressing the technology diffusion curve.
Thin-film transparent conductive oxide layers are replacing wire-based LED arrays in mirror illumination systems. Boutique hotel designers in Copenhagen and Melbourne specify these for seamless aesthetic integration. This technology is integrating anti-fog heating, dimming control, and proximity sensing into single substrate layers that reduce assembly complexity.
ECHA substance restriction proposals under REACH Annex XVII are targeting cadmium and lead compounds in mirror backing paints. German and French importers are accelerating supplier audits to preempt compliance gaps. Hospitality procurement teams in Madrid and Milan now require full material disclosure documentation as a standard bid prerequisite.
Direct-to-renovator e-commerce platforms are disintermediating traditional lighting showrooms for residential vanity mirror sales. Contractor purchasing in Texas, Florida, and Arizona increasingly routes through specialized online portals offering specification-grade products with digital measurement tools. This channel compression is most visible in North American bathroom remodeling markets where project timelines have shortened.
Vanity Mirror Market Segmentation
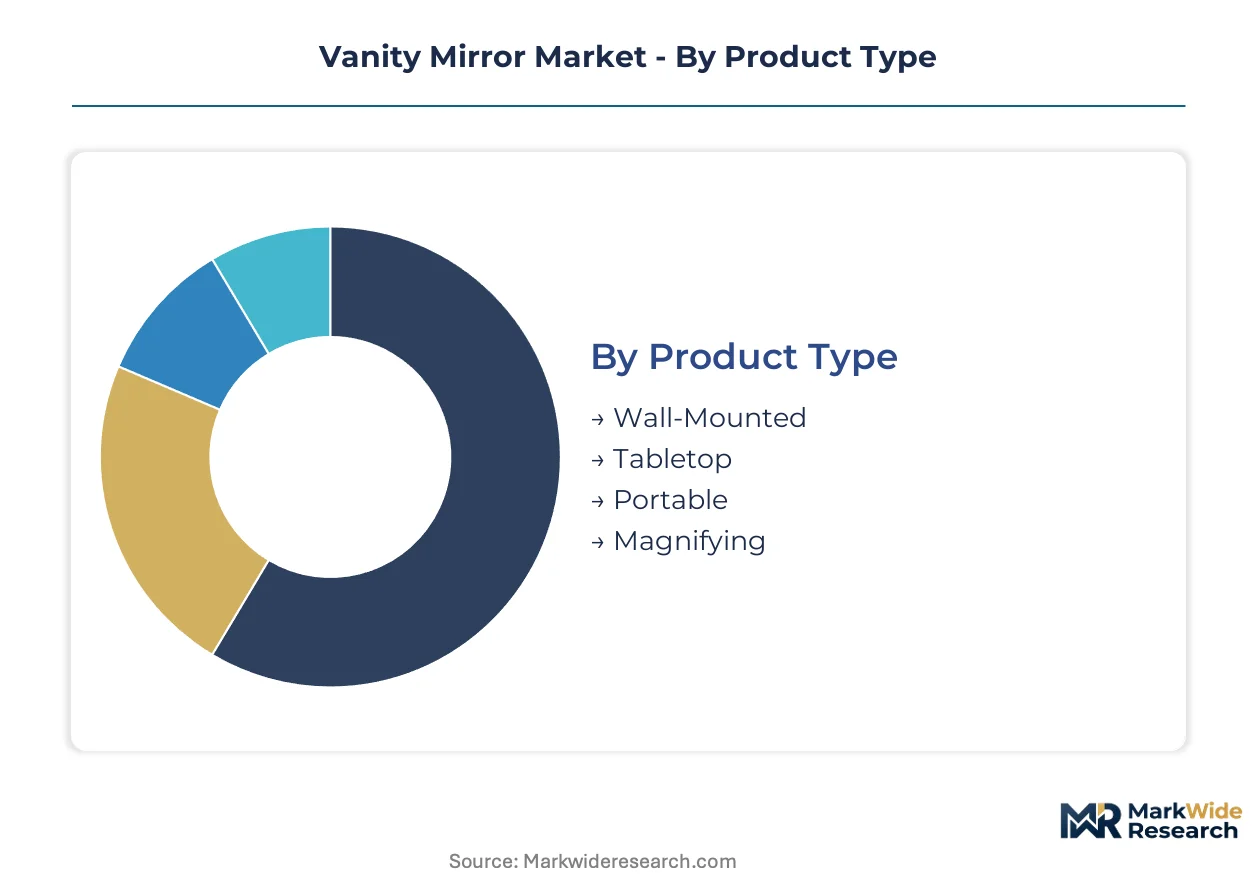
Segmentation in the vanity mirror market reveals how procurement channels, material specifications, and feature integration create distinct competitive arenas. Manufacturers configure production lines differently for hospitality bulk contracts versus portable consumer units. Understanding these divides exposes where margin pools concentrate and which technology investments yield specification advantages.
Product Type:
Supply concentration in Zhejiang and Guangdong manufacturing clusters shapes competitive dynamics across installation formats, with wall-mounted units dominating commercial procurement and portable segments capturing content-creation economies.
- Wall-Mounted:Permanent fixture integration drives replacement cycles in commercial installations. Hospitality procurement in Dubai, Singapore, and Miami standardizes these across guest bathroom portfolios, creating predictable demand pipelines for manufacturers with specification-grade certification.
- Portable:Rechargeable LED power systems with 95+ CRI ratings command price premiums. Demand concentrates among professional makeup artists in Los Angeles, London, and Seoul where content-creation economies prioritize color accuracy for digital capture.
- Tabletop:Residential renovation projects favor these for flexibility in premium bathroom redesigns.
- Magnifying:5x to 10x magnification ratios serve cosmetic accuracy requirements in medical-adjacent applications.
Today's leader: Wall-Mounted. Tomorrow's challenger: Portable.
Material:
Cost tier differentiation separates commodity export production from specification-grade hospitality procurement, with metal and glass anchoring premium positioning and acrylic competing on logistics efficiency.
- Glass:Silver-backed through chemical deposition with color-rendering indices above 90. Float glass input volatility from energy-intensive production compresses margins for assemblers lacking backward integration into glassmaking.
- Metal:Framed variants anchor luxury positioning in hospitality procurement channels. Metal finishing capabilities at Fresca Bath and integrated suppliers control cost volatility through captive supply relationships.
- Acrylic:Weight reduction enables shipping-intensive e-commerce channels competing on logistics cost.
- Wood:Residential segments favor these for aesthetic integration in renovation projects.
Metal and glass command specification premiums. Acrylic gains share fastest in direct-to-renovator channels.
Feature:
Application requirements drive technology convergence, with sensor-activated features migrating from premium residential into mid-market hospitality specifications and anti-fog heating becoming standard in luxury hotel chains.
- LED Illumination:Thin-film transparent conductive oxide layers replace wire-based arrays for seamless aesthetic integration. Boutique hotel designers in Copenhagen and Melbourne specify these, consolidating illumination, heating, and sensing into single substrate layers.
- Anti-Fog:Resistive heating elements integrated with IoT-enabled humidity sensors open smart home specification paths. EU F-Gas Regulation pressures phase-out of legacy refrigerant-based systems toward these alternatives.
- Touch Sensor:Proximity activation migrates from premium residential into standard hospitality specifications.
- Adjustable Angles:Ergonomic positioning serves professional salon and makeup artist workflows.
LED Illumination dominates current procurement. Anti-Fog shows steepest expansion trajectory as regulatory deadlines accelerate.
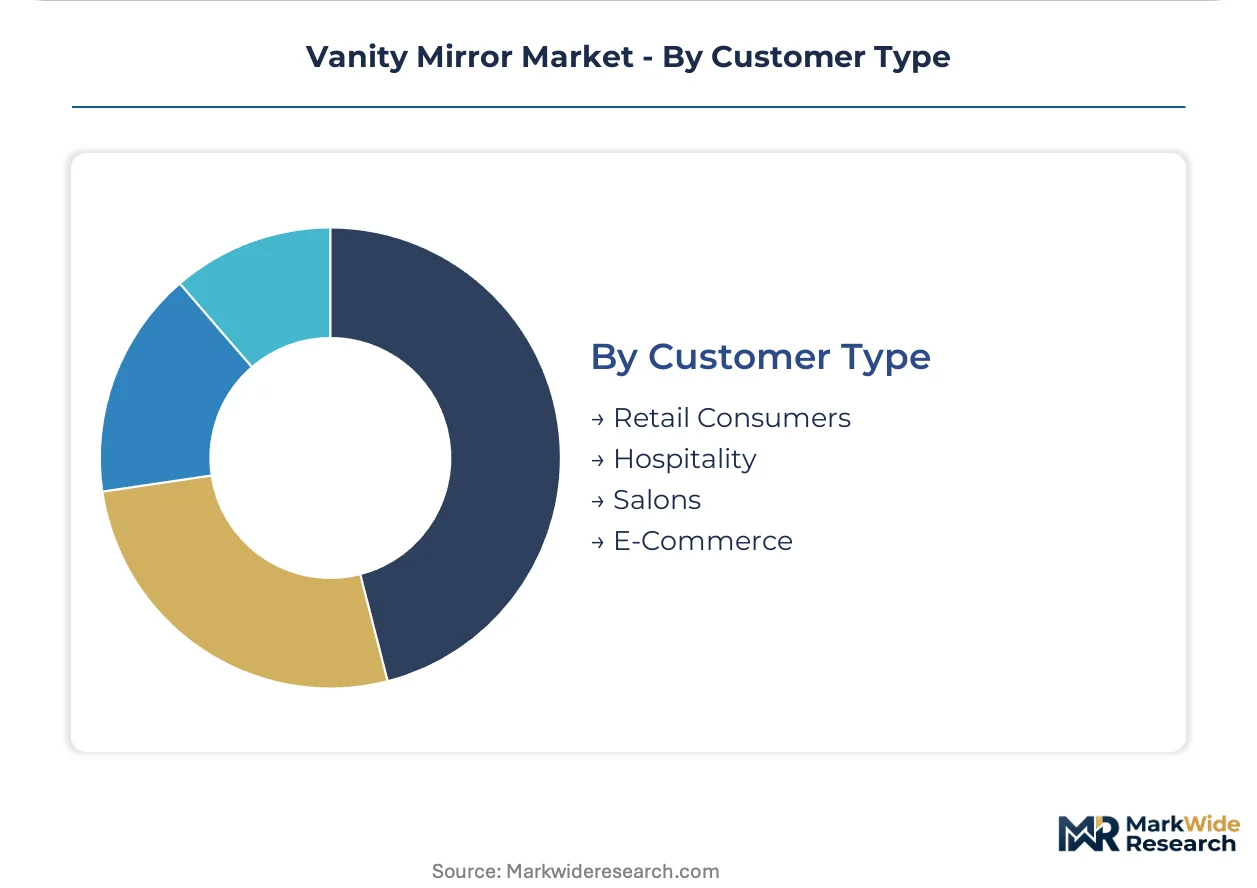
Customer Type:
Volume concentration in hospitality renovation cycles—compressing from ten-year intervals to five-to-seven-year refresh programs—pulls demand forward while e-commerce disintermediation reshapes residential purchasing patterns.
- Hospitality:Luxury hotel chains generate predictable replacement pipelines through standardized portfolio installations. Procurement teams in Madrid and Milan now require full material disclosure documentation as standard bid prerequisites under tightening REACH compliance.
- E-Commerce:Direct-to-renovator platforms disintermediate traditional lighting showrooms. Contractor purchasing in Texas, Florida, and Arizona routes through specialized online portals with digital measurement tools.
- Retail Consumers:Residential renovation demand concentrates in premium sensor-activated feature sets.
- Salons:Professional channels prioritize magnification accuracy and color rendering for cosmetic applications.
Hospitality anchors volume scale. E-Commerce captures the fastest share gains in residential procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang and Guangdong manufacturing clusters anchor global vanity mirror supply, yet demand patterns and regulatory pressures diverge sharply across consuming regions. Procurement channels in hospitality, residential renovation, and professional makeup artist segments create distinct geographic priorities.
United States
Contractor purchasing through Texas, Florida, and Arizona renovation markets routes increasingly through specialized e-commerce portals with digital measurement tools. The FDA exercises indirect oversight through cosmetic device adjacent classifications for magnifying mirrors with medical-adjacent claims. California and New York Metro areas concentrate professional makeup artist demand for portable rechargeable LED systems.
Germany
REACH compliance deadlines from ECHA are accelerating reformulation investments for mirror backing adhesives, filtering procurement toward certified manufacturers. German importers require full material disclosure documentation as standard bid prerequisites. Bavaria and North Rhine-Westphalia host specification-grade distributors serving hospitality renovation projects across Madrid and Milan procurement offices.
China
Domestic manufacturing clusters in Zhejiang and Guangdong supply both local consumers and export channels, controlling seventy percent of global vanity mirror exports. MIIT standards and GB certification requirements govern electrical luminaire safety for domestic distribution. Shanghai and Shenzhen design studios drive boutique hotel specification trends toward thin-film transparent conductive oxide illumination systems.
United Arab Emirates
Luxury hotel chains in Dubai standardize anti-fog heated mirrors across guest room portfolios, creating predictable replacement pipelines. MOHAP product safety requirements align with CE marking standards for electrical luminaires entering Gulf distribution. Abu Dhabi hospitality procurement teams prioritize metal-framed variants for luxury positioning in new construction projects.
India
BIS certification expansion for electrical luminaires creates first-mover advantages for LED mirror suppliers establishing testing partnerships. Residential renovation demand concentrates in Maharashtra and Karnataka urban centers. Delhi-NCR and Mumbai procurement channels show accelerating specification of sensor-activated feature sets in premium bathroom redesigns.
Vanity Mirror Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-activated and IoT-integrated adjacent spaces. The vendor base stratifies across three capability tiers: integrated glass-and-metal fabricators with captive supply relationships, specialist LED illumination technology developers, and portable consumer electronics assemblers. Competitive positioning hinges on certification breadth, hospitality specification relationships, and backward integration into float glass or metal finishing. Primary competitive moves include geographic expansion through distributor partnerships and portfolio diversification into smart home adjacent categories.
Among integrated bathroom fixture specialists, Fresca Bath and Duravit occupy positions representing the metal-and-glass fabrication archetype with captive finishing capabilities. Electric Mirror anchors the LED-illuminated systems tier for hospitality specification channels. Simplehuman exemplifies the sensor-activated feature set archetype targeting premium residential renovation segments. These three patterns—integrated manufacturing, illumination technology leadership, and smart feature differentiation—structure competitive rivalry across procurement channels.
| Leading Market Players |
|---|
| Fresca Bath |
| Chende |
| Duravit |
| Electric Mirror |
| Waneway |
| Moen |
| Simplehuman |
| Majestic Mirror & Frame Manufacturer |
| Jerdon |
| Others |
Value Network & Pricing Analysis
Float glass price volatility cascades through vanity mirror manufacturing tiers, compressing margins for framed assemblers lacking captive float glass production while concentrating pricing power among Zhejiang and Guangdong integrated producers who control seventy percent of global export volume.
Pricing Analysis
Input-cost pass-through from energy-intensive float glass production drives three-tier pricing stratification across premium specification-grade, standard hospitality-contract, and economy export tiers. Price differentiation hinges on certification breadth—simultaneous UL, CE, and SASO approvals command fifteen to twenty percent premiums—and backward integration into metal finishing or glassmaking. Pricing pressure stems from natural gas cost spikes in flat glass manufacturing, forcing margin compression on non-integrated assemblers. Hospitality procurement teams show lowest price sensitivity, prioritizing material disclosure compliance and specification-grade reliability over unit cost.
Supply Chain Analysis
Silver nitrate deposition chemistry rests on Japanese and German specialty chemical producers for high-purity reagents, while aluminum framing and LED driver electronics draw from Chinese domestic manufacturing clusters. Raw material dependencies span float glass, silver nitrate, transparent conductive oxide substrates, and resistive heating elements. Single-region vulnerability concentrates in Zhejiang and Guangdong export hubs, exposing buyers to port congestion and power rationing disruptions. Distribution runs through hospitality specification channels for bulk contract volumes and direct-to-renovator e-commerce portals for residential replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vanity mirror market functions as a stable compounder anchored by compressed hospitality renovation cycles that pull replacement demand forward on predictable five-to-seven-year intervals.
For Market Incumbents: Anticipate REACH Annex XVII cadmium and lead compound restrictions by accelerating supplier audits and reformulation investments before compliance deadlines filter procurement toward certified manufacturers. Deepen backward integration into float glass or metal finishing to defend margin structures against input volatility, while extending certification breadth to capture hospitality specification channels requiring simultaneous UL, CE, and SASO approvals. For New Entrants and Emerging Players: Enter via professional makeup artist channels in Los Angeles, London, and Seoul where 95+ CRI portable rechargeable LED mirrors command price premiums in content-creation economies. Target India's BIS certification expansion for electrical luminaires, where mandatory quality standards create first-mover advantages for testing partnerships. Pursue direct-to-renovator e-commerce platforms with digital measurement tools to bypass traditional lighting showroom intermediaries in Texas, Florida, and Arizona remodeling markets. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated glass-and-metal fabricators possessing captive supply relationships and established hospitality specification channels. Long-term viability over a five-to-ten year window favors producers with resistive heating and IoT sensor integration capabilities as EU F-Gas Regulation phases out legacy refrigerant-based anti-fog systems. Watch thin-film transparent conductive oxide yield improvements as the signal indicating which illumination technology developers can consolidate anti-fog, dimming, and proximity sensing into single substrate layers.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Pre-Positioning | Accelerated supplier audits before ECHA substance restrictions filter procurement toward certified manufacturers. |
| Resistive Heating Technology Migration | Integration of thin-film elements with IoT humidity sensors opens smart home specification paths ahead of F-Gas deadlines. |
| BIS Certification Partnership | Testing relationships with Indian standards bodies create first-mover positioning in mandatory electrical luminaire compliance. |
| Direct-to-Renovator E-Commerce Launch | Digital measurement tools on specialized portals disintermediate traditional lighting showrooms in North American remodeling markets. |
| Transparent Conductive Oxide Scale-Up | Yield improvements in thin-film deposition consolidate illumination, heating, and sensing into single substrate layers for boutique hotel designers. |
Research Methodology
Bottom-up hospitality and residential renovation modeling reconciled against top-down manufacturing cluster tracking forms the analytical core. Primary interviews with hotel procurement directors, bathroom fixture distributors, LED driver engineers, and optical coating technicians combined with secondary validation from customs trade data, hospitality renovation project databases, and ECHA regulatory filings. Triangulation across stakeholder inputs and export statistics from Zhejiang and Guangdong production hubs ensures supply-side coverage.
Historical trendline analysis of replacement cycle compression and specification feature migration informs the projection framework. Segmentation dimensions span installation format, material composition, feature integration, and customer procurement channel across the analysis window. CAGRs derive from fitted growth curves applied to verified base-year volumes, incorporating silver deposition automation yields, REACH compliance investment timelines, and e-commerce channel penetration rates as industry-specific inputs.
The model holds under stable hospitality renovation spending and continued REACH implementation; deviation in energy price spikes or single-region supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions about certification timeline standardization and thin-film technology yield trajectories. A small set of named triggers—ECHA substance restriction acceleration, Zhejiang power rationing recurrence, and India BIS enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Women Intimate Care Products Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Hair Removal Wax Warmer Market
Beauty & Personal Care
Beauty Oils Market