
 Women Intimate Care Products Market | 2026-2036
Women Intimate Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Women Intimate Care Products Market Analytics
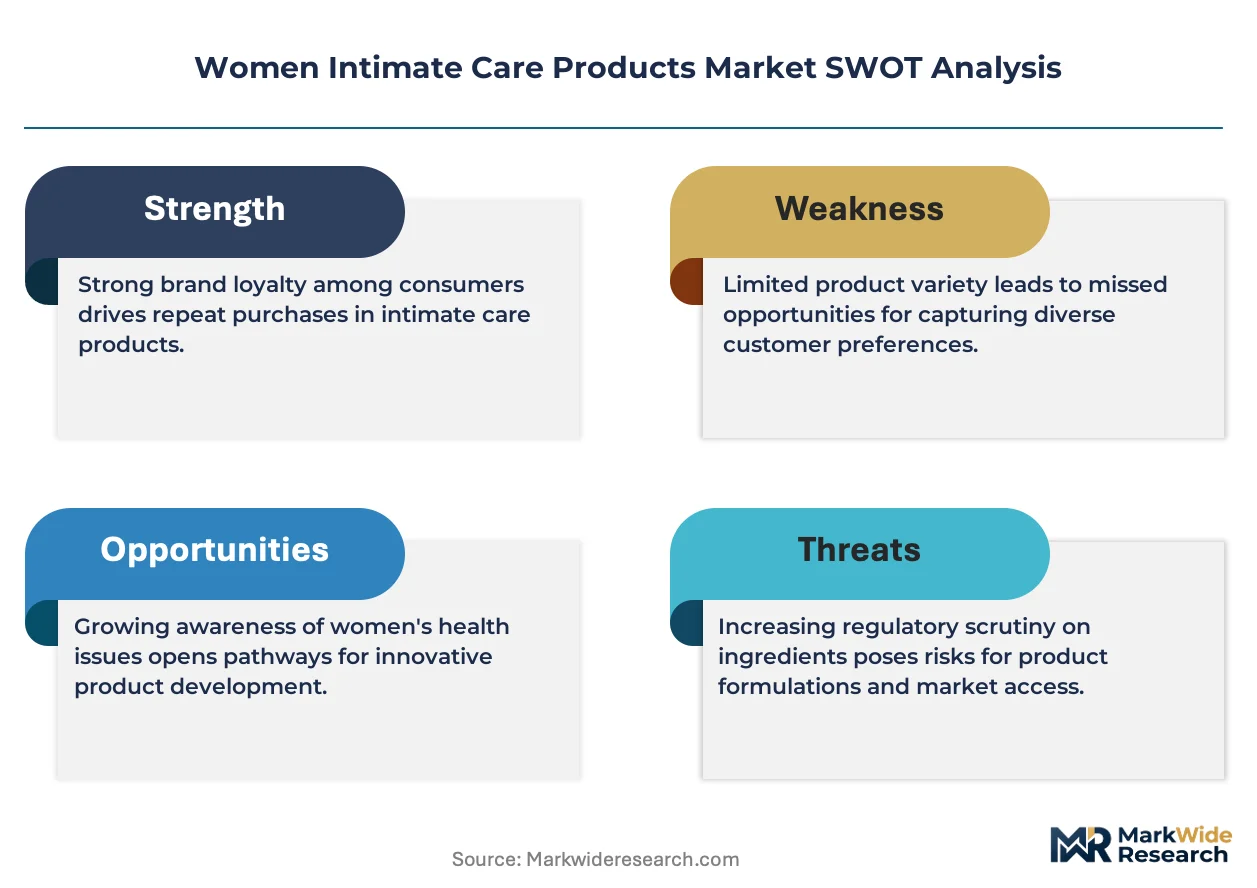
The gap between premium and commodity tiers is recalibrating around ingredient transparency and sustainability credentials rather than basic efficacy claims. Procter & Gamble leverages its massive R&D infrastructure to validate microbiome-friendly formulations through clinical testing. Essity AB anchors its European position with concentrated production of organic cotton-based wipes. Kimberly-Clark Corporation competes through pharmacy channel control and healthcare professional endorsement programs.
Women intimate care products encompass cleansers, moisturizers, deodorants, and refreshers formulated for vulvar and external vaginal use, typically maintaining pH between 3.8 and 4.5 to preserve acid mantle integrity. Their commercial purpose centers on hygiene maintenance, odor management, and comfort enhancement without disrupting native flora. Feminine wash and wipes categories lead volume, though creams and gels capture disproportionate margin pools through dermatological positioning. Liquid and foaming forms dominate shelf space, while spray formats gain traction among fitness enthusiasts seeking portable application. Online retail channels expand fastest, though pharmacies sustain premium price realization through pharmacist recommendation leverage.
The US FDA oversees cosmetic labeling and safety substantiation, while the EU REACH framework restricts specific preservatives and fragrances in intimate applications. Brazil's ANVISA imposes stringent microbial and heavy metal standards that shape export-ready formulation strategies. Stakeholders must monitor evolving state-level chemical disclosure laws in the US and EU Green Deal implementation timelines to anticipate reformulation costs and competitive repositioning requirements.
Market Dynamics
The EU Green Deal's chemical disclosure mandates are forcing wholesale reformulation across intimate care portfolios, compressing timelines for plant-based surfactant validation while redistributing competitive advantage toward suppliers with captive biotech fermentation capacity.
Growth Catalysts
- Gen Z channel migration:Digital-native consumers in Brazil and India bypass traditional pharmacy gatekeepers through direct-to-platform purchasing, collapsing distribution layers.
- REACH Annex XVII expansion:Restrictions on methylisothiazolinone and formaldehyde-releasing preservatives accelerate clean-label R&D investment across European formulators.
- Microbiome testing protocols:At-home vaginal microbiome screening kits create diagnostic-adjacent demand for flora-supporting wash formulations.
Market Restraints
- Organic coconut oil volatility:Philippine and Indonesian supply disruptions transmit directly to surfactant input costs for natural-positioned brands.
- ANVISA registration timelines:Brazil's 18-24 month approval windows for new active ingredients freeze product pipeline velocity for export-focused manufacturers.
- Water-free formulation limits:Technical barriers to stable anhydrous cleansing systems constrain travel-size and sustainability-positioned innovation.
Strategic Opportunities
- Menopausal care white space:Vulvar moisturizers targeting estrogen-depleted tissue remain underdeveloped relative to fertile-age segments in Germany and Japan.
- Subscription pharmacy integration:UK and Netherlands pharmacy chains pilot auto-replenishment models with personalized pH monitoring.
- CSRD reporting alignment:EU corporate sustainability disclosure requirements create procurement preference for suppliers with validated Scope 3 emissions data.
Industry Challenges
- Clinical validation capacity:Dermatological testing backlog at CROs extends go-to-market timelines for microbiome-friendly claims.
- Legacy ERP integration:Batch-level traceability requirements for EU Green Deal compliance strain mid-tier manufacturers' quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Intimate Care Products Market |
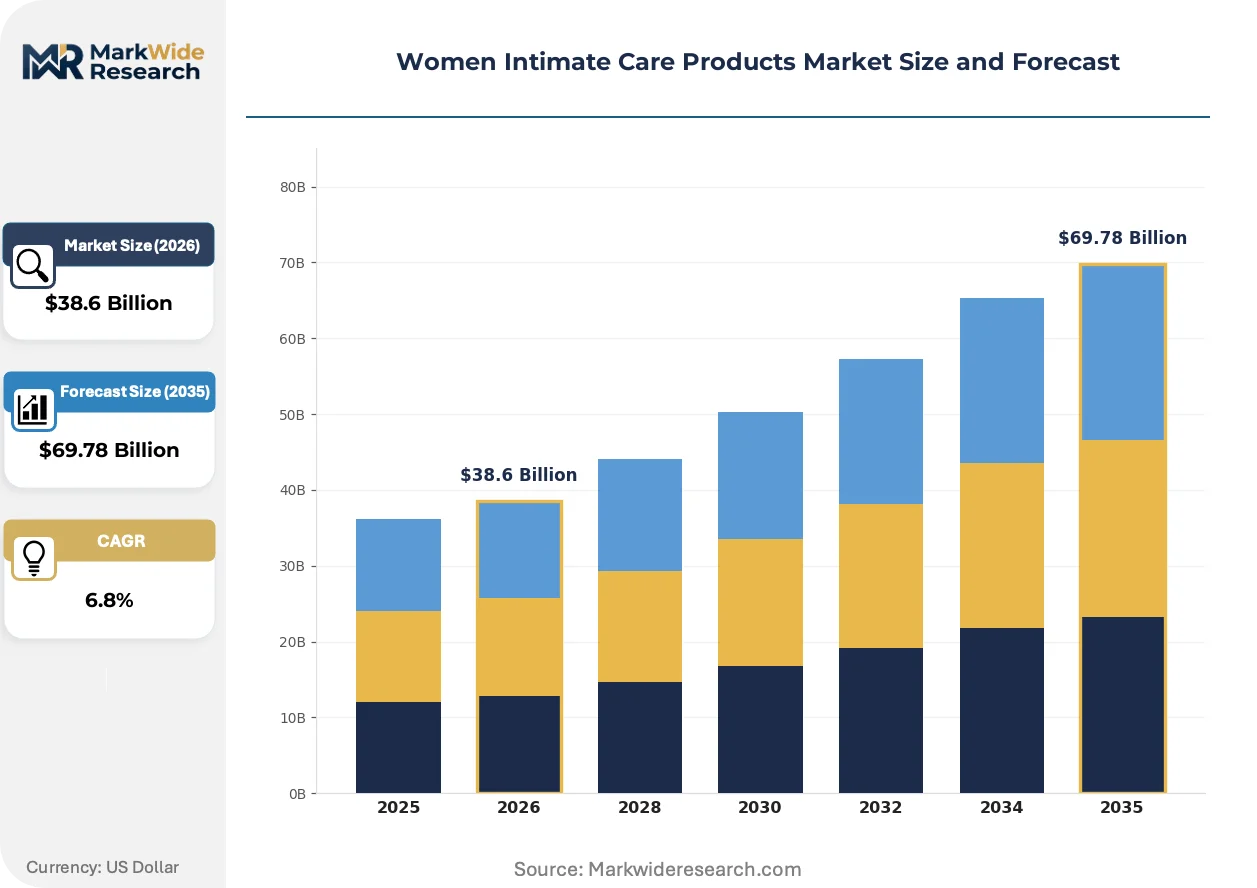
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feminine Wash, Wipes, Creams, Gels Form: Liquid, Solid, Foaming, Spray Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Customer Type: Teenagers, Adults, Seniors, Fitness Enthusiasts |
| Companies Covered | Unicharm Corporation, Essity AB, Procter & Gamble, Church & Dwight, Unilever, Kimberly-Clark Corporation, Edgewell Personal Care, The Honest Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Intimate Care Products Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous recalibration as ingredient transparency demands collide with convenience-oriented consumption patterns.
Biotech-derived biosurfactants from rhamnolipid and sophorolipid fermentation are replacing petroleum-based sulfates in premium intimate washes. Indie brands in South Korea and France are adopting these inputs fastest, compressing the clean-label premium that once justified 40-60% price deltas. This technology is decentralizing formulation expertise from multinational R&D centers toward specialized fermentation startups with direct brand relationships.
REACH authorization requirements for fragrance allergens are expanding disclosure obligations to 100+ substances by 2026. Formulators serving the EU market are stripping complex perfume blends from intimate care SKUs, shifting toward single-note or fragrance-free positioning. The wipes category absorbs the heaviest compliance burden, driving consolidation toward suppliers with in-house toxicology documentation capabilities.
Pharmacy recommendation dependency is eroding as Brazilian and Indian consumers self-diagnose through symptom-checker apps before purchasing. E-commerce platforms capture this intent through search-optimized landing pages, displacing the pharmacist as the primary education node. Urban centers in São Paulo and Mumbai exhibit the sharpest channel-shift velocity, with pharmacy foot traffic for intimate care declining 15-20% annually in premium postcodes.
Women Intimate Care Products Market Segmentation
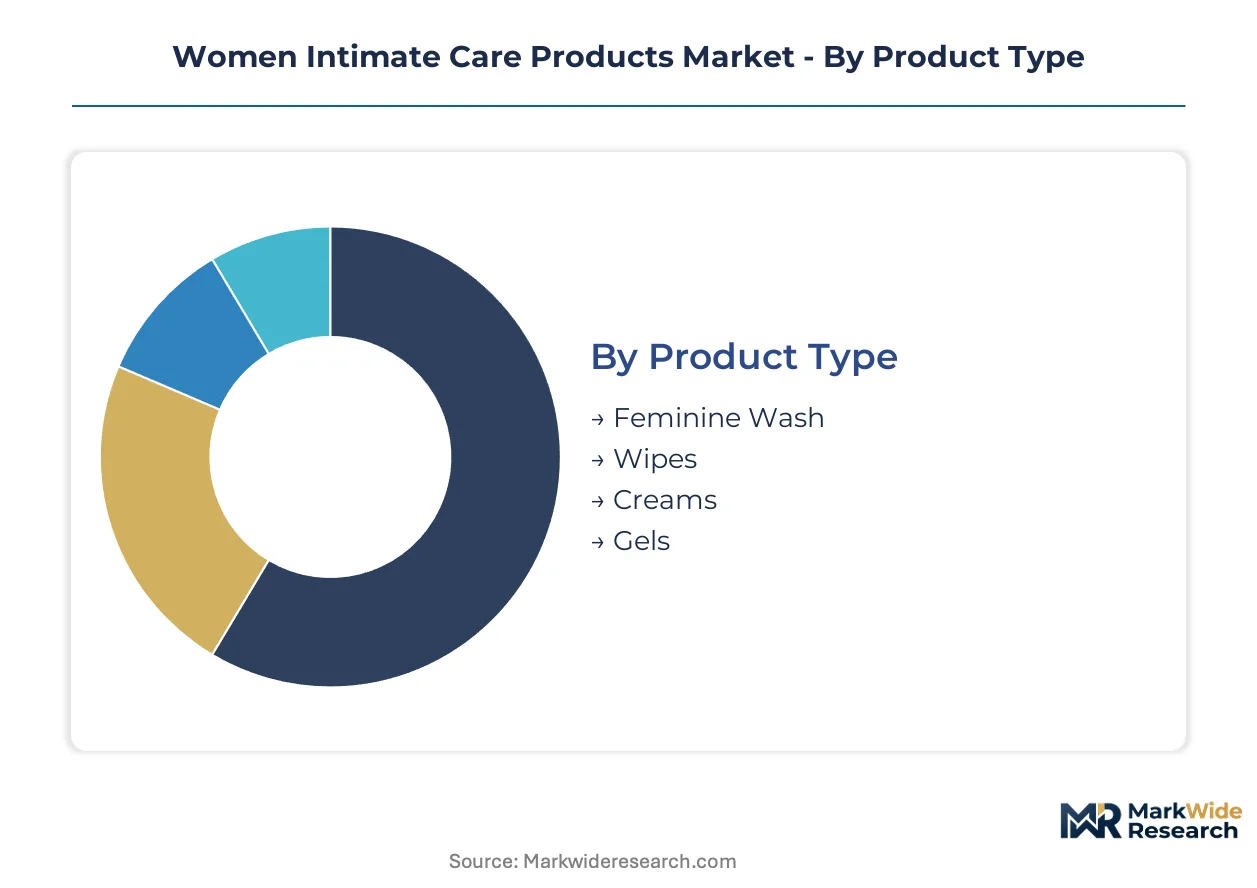
Segmentation in women's intimate care reveals how formulation specificity and channel access determine price realization. Product architecture, physical form, distribution pathway, and life-stage targeting each create distinct margin pools and competitive barriers.
Product Type:
Customization intensity spans from mass-market cleansers to clinically positioned therapeutic formats, with formulation complexity driving tier placement and regulatory burden.
- Feminine Wash:Liquid cleansers formulated to pH 3.8-4.5 with surfactant systems ranging from petroleum sulfates to fermented biosurfactants. Demand concentrates in Brazil and India where tropical humidity and pharmacy channel density sustain above-average per-capita consumption. ANVISA microbial standards and REACH preservative restrictions force dual-track formulation strategies for export-ready manufacturers.
- Wipes:Pre-moistened towelettes using organic cotton or synthetic substrates with preservative systems vulnerable to EU fragrance allergen disclosure expansion. German and French consumers drive premium organic cotton adoption, while price-sensitive Southeast Asian markets favor conventional rayon blends. REACH Annex XVII compliance costs disproportionately burden this segment due to substrate-adhesive-preservative interaction complexity.
- Creams:Barrier-repair formulations targeting menopausal vulvar atrophy and dermatological sensitivity. Japanese and German aging demographics sustain niche premium positioning.
- Gels:Lightweight hydrators with hyaluronic acid or aloe vera bases, popular among fitness enthusiasts for post-workout application without residue.
Most installed capacity flows through Feminine Wash. Expansion is steepest in Wipes.
Form:
Physical state determines packaging requirements, stability challenges, and usage occasion flexibility across travel, home, and gym contexts.
- Liquid:Conventional pourable formats dominating mass-market shelf space with established manufacturing infrastructure and lowest per-unit production cost.
- Solid:Water-free bars and balms addressing sustainability-positioned consumers and carry-on travel restrictions, though anhydrous stability limits formulation breadth.
- Foaming:Pump-dispensed aerated cleansers with enhanced sensorial profile and reduced surfactant concentration per use, commanding 15-25% price premiums in US and UK pharmacy channels.
- Spray:Aerosol and mechanical mist formats gaining traction among Brazilian and Australian fitness segments for portable, no-touch application.
Manufacturing asset base centers on Liquid. Patent filing velocity is highest in Solid.
Distribution Channel:
Channel selection determines education intensity, pricing authority, and customer data capture depth.
- Online Retail:Direct-to-platform and brand-owned storefronts collapsing traditional pharmacy gatekeeper roles in São Paulo and Mumbai. Search-optimized landing pages now intercept self-diagnosing consumers before professional consultation.
- Supermarkets:Mass-market volume placement with limited shelf-space competition and price-promotion dependency eroding margin for non-differentiated entrants.
- Pharmacies:Pharmacist recommendation leverage sustaining premium price realization in European markets, though foot traffic for intimate care declines 15-20% annually in premium urban postcodes.
- Specialty Stores:Clean beauty boutiques and organic retailers curating microbiome-friendly and fermentation-derived formulations for ingredient-transparency-seeking millennials.
Revenue concentration remains in Pharmacies. Customer acquisition cost efficiency is improving fastest in Online Retail.
Customer Type:
Life-stage and lifestyle segmentation dictates hormonal context, skin sensitivity, and usage occasion requirements.
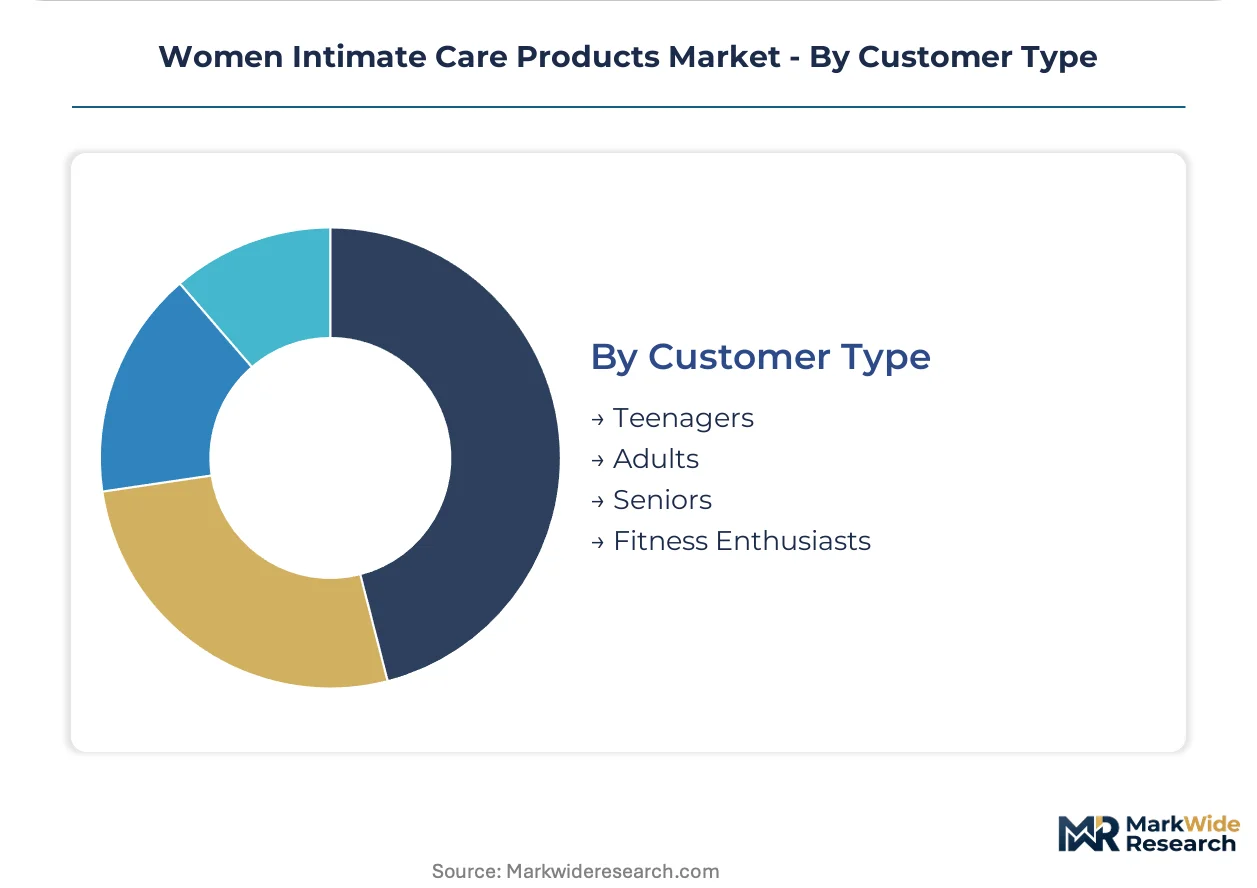
- Teenagers:First-time users requiring gentle, fragrance-minimized introductions with educational packaging addressing common misconceptions.
- Adults:Fertile-age consumers representing volume core with cyclical hormonal variation driving seasonal purchasing patterns.
- Seniors:Estrogen-depleted tissue requiring vulvar moisturizers with ceramide and lipid restoration, a white space in German and Japanese markets relative to investment in fertile-age segments.
- Fitness Enthusiasts:Gym-bag-compatible formats with rapid reapplication convenience and sweat-activated odor management claims.
Current R&D expenditure prioritizes Adults. Unmet need is deepest in Seniors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists and formulation scientists cluster in Germany, Japan, and Brazil, anchoring the industry's technical workforce concentration. These talent pools sustain regional specialization in biosurfactant development, microbiome research, and tropical-climate formulation. Regulatory divergence across FDA, REACH, and ANVISA frameworks forces parallel product development tracks.
United States
Millennial and Gen Z consumers drive e-commerce channel migration for intimate wash and wipe categories. FDA cosmetic labeling requirements and emerging state-level chemical disclosure laws push reformulation toward fragrance-minimized and microbiome-friendly positioning. New Jersey and California host the densest concentrations of contract manufacturers serving DTC brands.
Germany
EU Green Deal implementation accelerates plant-based surfactant adoption among domestic formulators. REACH Annex XVII restrictions on methylisothiazolinone and formaldehyde-releasing preservatives force clean-label R&D investment. The Rhine-Ruhr industrial corridor concentrates fermentation-derived biosurfactant production capacity for export-ready intimate care portfolios.
Brazil
Tropical humidity and pharmacy channel density sustain above-average per-capita consumption of feminine washes and wipes. ANVISA imposes stringent microbial and heavy metal standards with 18-24 month approval timelines for new active ingredients. São Paulo anchors both manufacturing capacity and the sharpest e-commerce channel shift, with pharmacy foot traffic declining 15-20% annually in premium postcodes.
Japan
Aging demographics sustain niche premium positioning for menopausal vulvar moisturizers with ceramide restoration claims. METI oversight and PMDA cosmetic safety frameworks emphasize dermatological testing documentation. The Kanto region around Tokyo concentrates R&D investment in barrier-repair formulations targeting estrogen-depleted tissue.
India
Digital-native consumers bypass traditional pharmacy gatekeepers through direct-to-platform purchasing, collapsing distribution layers. BIS standards and CDSCO cosmetic regulations shape import and domestic manufacturing compliance. Mumbai and Bangalore exhibit the fastest online retail velocity for intimate care, with search-optimized landing pages intercepting self-diagnosing consumers.
Women Intimate Care Products Market Competitive Landscape
Top-tier vendors anchor premium and mass-market tiers, while indie fermentation startups and private-label manufacturers occupy the mid-market and value segments. The vendor base spans multinational consumer goods conglomerates, specialized feminine hygiene pure-plays, and biotech-enabled niche entrants. Three archetypes dominate: R&D-heavy incumbents with clinical validation infrastructure, regional pharmacy channel specialists, and clean-positioned indie brands leveraging direct-to-consumer distribution. Competitive moves center on microbiome-friendly formulation patenting and captive biotech fermentation capacity acquisition.
Within the multinational conglomerate tier, Procter & Gamble, Unilever, and Kimberly-Clark Corporation exemplify scale-driven players with integrated R&D and pharmacy channel control. Essity AB and Unicharm Corporation represent regional specialists with concentrated production in European and Asian markets respectively. Church & Dwight and Edgewell Personal Care occupy positions bridging mass-market distribution and dermatological endorsement strategies. The Honest Company anchors the clean-label indie archetype, while Johnson & Johnson exemplifies healthcare heritage positioning in intimate care adjacent segments.
| Leading Market Players |
|---|
| Unicharm Corporation |
| Essity AB |
| Procter & Gamble |
| Church & Dwight |
| Unilever |
| Kimberly-Clark Corporation |
| Edgewell Personal Care |
| The Honest Company |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
EU Green Deal chemical disclosure mandates gate qualified supply and premium-tier pricing access by forcing reformulation investments that only scaled manufacturers with captive biotech fermentation capacity can absorb. This regulatory filter stratifies the market between REACH-compliant premium portfolios and commodity tiers vulnerable to margin compression from plant-based surfactant validation costs.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription pharmacy models with personalized pH monitoring from transactional e-commerce purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under REACH Annex XVII and ANVISA microbial standards. Cost compression in the standard tier intensifies because biosurfactant input costs transmit directly from Philippine and Indonesian supply disruptions. Price-sensitive Southeast Asian consumers favor economy rayon-based wipes, while German and Japanese buyers accept premium organic cotton positioning.
Supply Chain Analysis
Ocean freight volatility from Southeast Asian surfactant hubs to European formulation centers amplifies working capital requirements for mid-tier manufacturers. Manufacturing concentration centers on Brazil, Germany, and Japan, with raw material dependencies spanning Indonesian coconut oil derivatives, Philippine biosurfactant feedstocks, and German fermentation-derived rhamnolipids. Single-source vulnerability in tropical surfactant supply chains exposes formulators to climate-driven harvest disruptions. Distribution runs through pharmacy chains in European markets and direct-to-platform channels in Brazilian and Indian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Brazil's ANVISA-compliant export-ready manufacturing and Europe's REACH-driven premium pricing, exploiting the 18-24 month registration timeline differential to capture margin in regulated markets.
For Market Incumbents: Hedge against indie fermentation startup disruption by acquiring captive biotech capacity in the Rhine-Ruhr corridor, securing rhamnolipid and sophorolipid supply independence from Philippine coconut oil volatility. Reinforce pharmacy channel control through healthcare professional endorsement programs that resist e-commerce erosion in São Paulo and Mumbai premium postcodes. For New Entrants and Emerging Players: Enter via menopausal vulvar moisturizer white space in Germany and Japan, where estrogen-depleted tissue formulations remain underdeveloped relative to fertile-age investment. Target subscription pharmacy integration in the UK and Netherlands, piloting auto-replenishment models with at-home microbiome screening adjacency to bypass incumbent shelf-space dominance. For Investors and Strategic Acquirers: Roll-up economics work for specialized fermentation startups with direct brand relationships because EU Green Deal compliance is decentralizing formulation expertise from multinational R&D centers. Target acquisition archetypes include South Korean and French indie brands with validated biosurfactant pipelines and existing REACH toxicology documentation. Watch for inflection when ANVISA accelerates approval timelines or EU CSRD reporting requirements trigger procurement preference shifts toward Scope 3-validated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biosurfactant Fermentation | Captive rhamnolipid production insulates Procter & Gamble and Essity AB from Philippine supply disruptions. |
| Direct-to-Consumer Platform Launch | Brazilian and Indian e-commerce expansion collapses pharmacy gatekeeper layers for digital-native Gen Z adoption. |
| Menopausal Care Line Extension | Ceramide-based vulvar moisturizers address unmet need in German and Japanese aging demographics. |
| REACH Annex XVII Compliance Repositioning | Fragrance-free and single-note formulations preempt 2026 allergen disclosure expansion in EU intimate care. |
| Subscription Pharmacy Partnership | UK and Netherlands auto-replenishment pilots with pH monitoring capture recurring revenue from diagnostic-adjacent demand. |
Research Methodology
Direct dialogue with brand managers at multinational consumer goods conglomerates, fermentation startup technical directors, pharmacy chain category buyers, and ANVISA regulatory consultants anchored qualitative insights. Secondary validation drew from customs records of surfactant imports, SEC 10-K filings of listed personal care manufacturers, EU ECHA REACH registration databases, and Nielsen retail audit data for intimate care shelf-space allocation. Bottom-up demand modeling across product type, form, distribution channel, and customer type segments triangulated against top-down macroeconomic drivers.
The analytical lens combined bottom-up unit economics by SKU with top-down category spend penetration curves across the projection horizon. Segmentation dimensions modeled included product architecture complexity, physical form stability requirements, channel education intensity, and life-stage hormonal context. CAGRs were derived from installed capacity utilization rates and channel-shift velocity parameters, with specific inputs for biosurfactant adoption curves and pharmacy foot traffic decline trajectories in São Paulo and Mumbai premium postcodes.
Inputs from ECHA REACH registration databases and ANVISA approval tracking systems were available through the study window; gaps in real-time microbiome testing kit sales correlation data introduce uncertainty bands around diagnostic-adjacent demand forecasts. Forecasts reflect assumptions about EU Green Deal implementation pacing and Brazilian e-commerce penetration ceilings. Stakeholders should weight assumptions against their own operating context and regulatory compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Luxury Cosmetics Market
Beauty & Personal Care
Eyelash Serum Market
Beauty & Personal Care
Home Use Anti-Aging Beauty Device Market
Beauty & Personal Care
Nail Buffers Market