
 Beauty Oils Market | 2026-2036
Beauty Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Beauty Oils Market Analytics
Clean beauty formulation science is fragmenting traditional emulsion chemistry as brands adopt cold-pressed extraction and lipid-delivery systems for active ingredients. L'Oréal S.A. leverages integrated botanical sourcing networks across multiple continents. The Estée Lauder Companies Inc. anchors its prestige portfolio on proprietary fermentation-derived oil technologies. Shiseido Company, Limited specializes in hybrid oil-serum textures targeting East Asian skin barrier concerns.
Beauty oils are lipid-based cosmetic preparations containing triglycerides, essential fatty acids, and lipophilic actives, manufactured through mechanical pressing or solvent extraction and formulated for topical delivery of nourishment, barrier repair, or aromatic benefit. Facial oils lead product type value pools due to premium positioning and concentrated active loads, while plant-based ingredient sources capture structural growth as clean-label procurement displaces mineral and synthetic alternatives. Hair oils retain volume dominance in emerging markets where oiling rituals persist, though skincare applications command higher per-unit margins in North American and European retail.
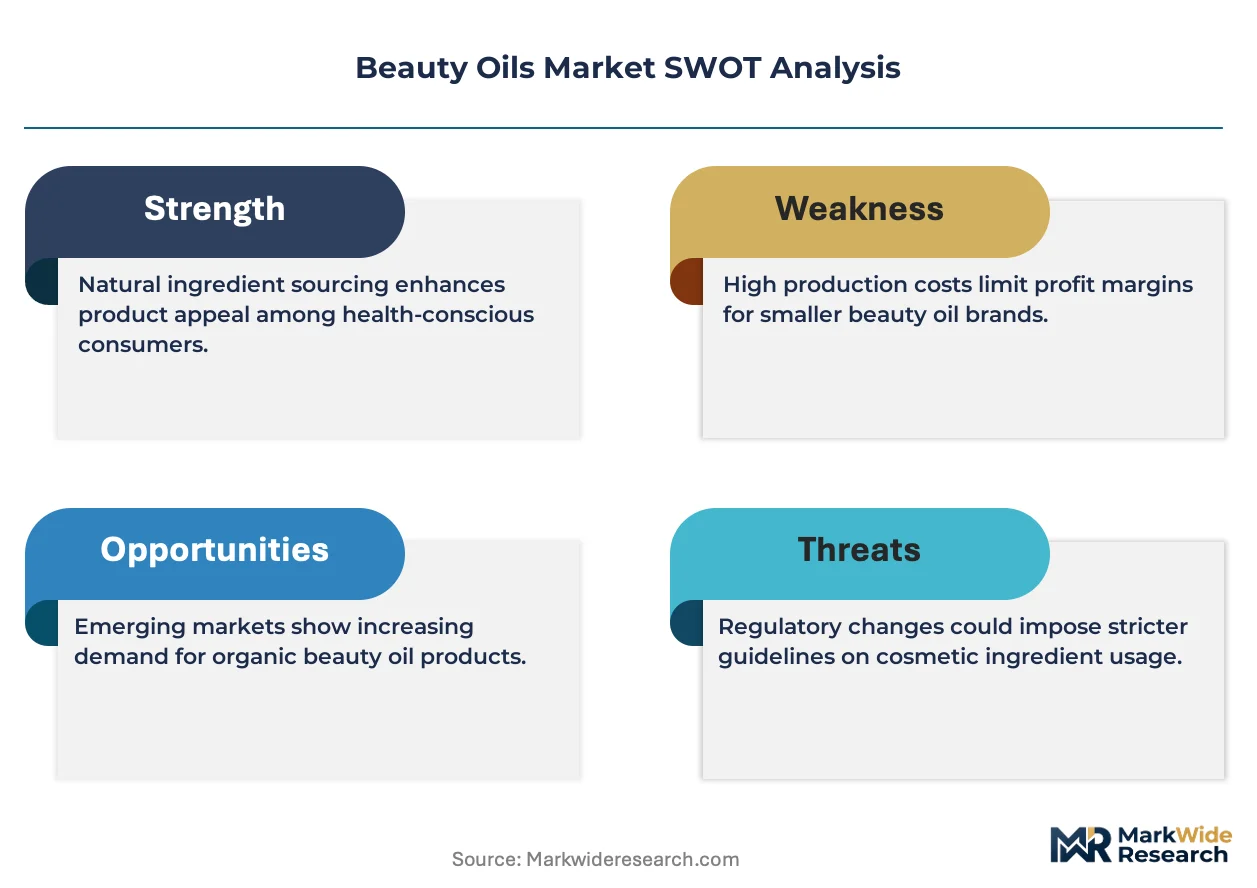
EU REACH and the EU Green Deal constrain petrochemical-derived synthetic oil inputs while incentivizing biodegradable botanical alternatives. The FDA governs cosmetic oil safety substantiation and labeling claims in the United States, creating compliance cost tiers that favor scaled manufacturers with dedicated regulatory affairs functions. Stakeholders must monitor evolving microbiome-friendly claims standards and carbon-footprint disclosure requirements that will reshape supplier qualification criteria and consumer communication strategies.
Market Dynamics
Clean-label procurement mandates are compressing formulation timelines as brands eliminate petrochemical-derived emollients in favor of traceable botanical lipids. Cold-pressed extraction infrastructure requires capital redeployment across supplier networks.
Growth Catalysts
- EU Green Deal biopolicy:REACH incentivizes biodegradable alternatives to synthetic occlusives, accelerating botanical oil adoption in mass-market skincare.
- Direct-to-consumer channel expansion:United States-based digital-native brands bypass traditional retail markups, democratizing facial oil access.
- Fermentation-derived lipids:Precision biotechnology produces squalane and rare fatty acids without agricultural land constraints, stabilizing supply.
Market Restraints
- Raw material volatility:Climate-sensitive crops including argan and marula face harvest fluctuations that destabilize contract pricing.
- Supplier concentration:Moroccan argan cooperatives and Indian amla processing clusters create single-origin dependency risks.
- Regulatory friction:FDA substantiation requirements for barrier-repair claims extend product development cycles by 12-18 months.
Strategic Opportunities
- Microbiome-friendly positioning:Unregulated claim space around skin flora compatibility allows premium pricing before standards crystallize.
- Hybrid oil-serum textures:East Asian consumers drive demand for lightweight lipid vehicles that layer under sunscreen.
- Carbon-footprint disclosure:EU CSRD mandates create first-mover advantage for brands with verified Scope 3 supply chain data.
Industry Challenges
- Formulation chemist scarcity:Lipid-delivery system expertise remains concentrated among legacy cosmetic scientists approaching retirement.
- Cold-press capex requirements:Small-batch mechanical extraction equipment demands facility retrofits that strain mid-tier manufacturer balance sheets.
- Claim substantiation timelines:Clinical testing for anti-aging oil efficacy extends go-to-market schedules beyond seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beauty Oils Market |
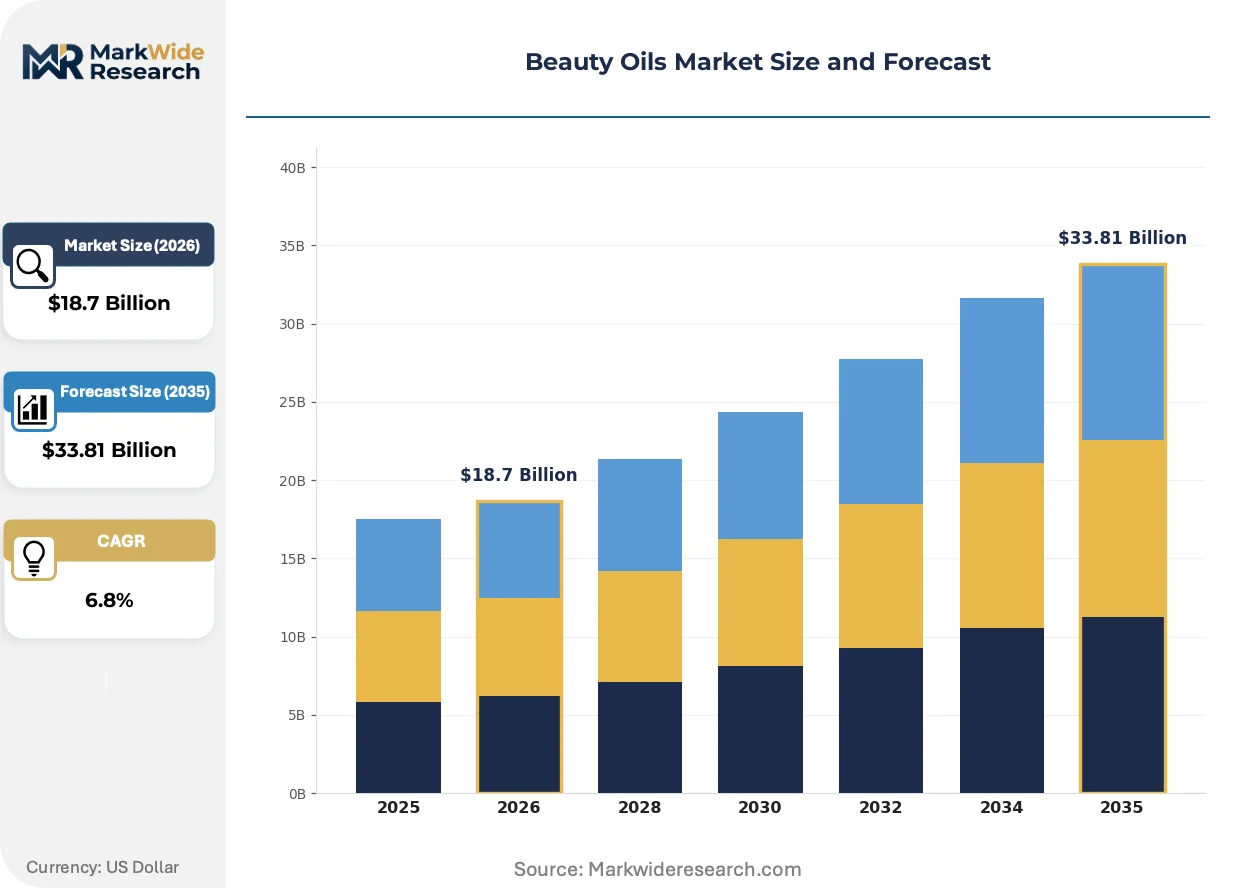
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Oils, Hair Oils, Body Oils, Nail Oils Ingredient Source: Plant-Based, Mineral-Based, Synthetic, Animal-Derived Application: Skincare, Haircare, Aromatherapy, Massage Packaging Type: Bottles, Jars, Sachets, Pumps |
| Companies Covered | L'Oréal S.A., The Estée Lauder Companies Inc., Unilever PLC, Shiseido Company, Limited, The Procter & Gamble Company, Beiersdorf AG, Amorepacific Corporation, Clarins S.A., KOSÉ Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beauty Oils Market Evolving Landscape
Biotechnology is dissolving the boundary between agricultural sourcing and laboratory synthesis. Three concurrent developments are restructuring competitive advantage.
Supercritical CO2 extraction is collapsing the yield gap between artisanal cold-pressing and industrial solvent methods. Prestige skincare houses adopt this technology to preserve heat-sensitive actives while achieving batch consistency. The compression is eliminating the quality-versus-scale tradeoff that previously segmented premium from mass-market oils.
REACH authorization lists are tightening restrictions on petrochemical-derived emollients including certain mineral oil fractions. European formulators reformulate with upcycled fruit seed oils and fermentation-derived alternatives to maintain shelf presence. Hair care applications face the steepest compliance costs due to higher usage volumes of occlusive bases.
Subscription-based replenishment models are capturing facial oil consumers who prioritize routine adherence over retail discovery. United States direct-to-consumer brands deploy algorithmic skin assessments to customize oil blends, displacing department store counter consultations. This behavioral pivot concentrates lifetime value among digitally native operators with robust retention infrastructure.
Beauty Oils Market Segmentation
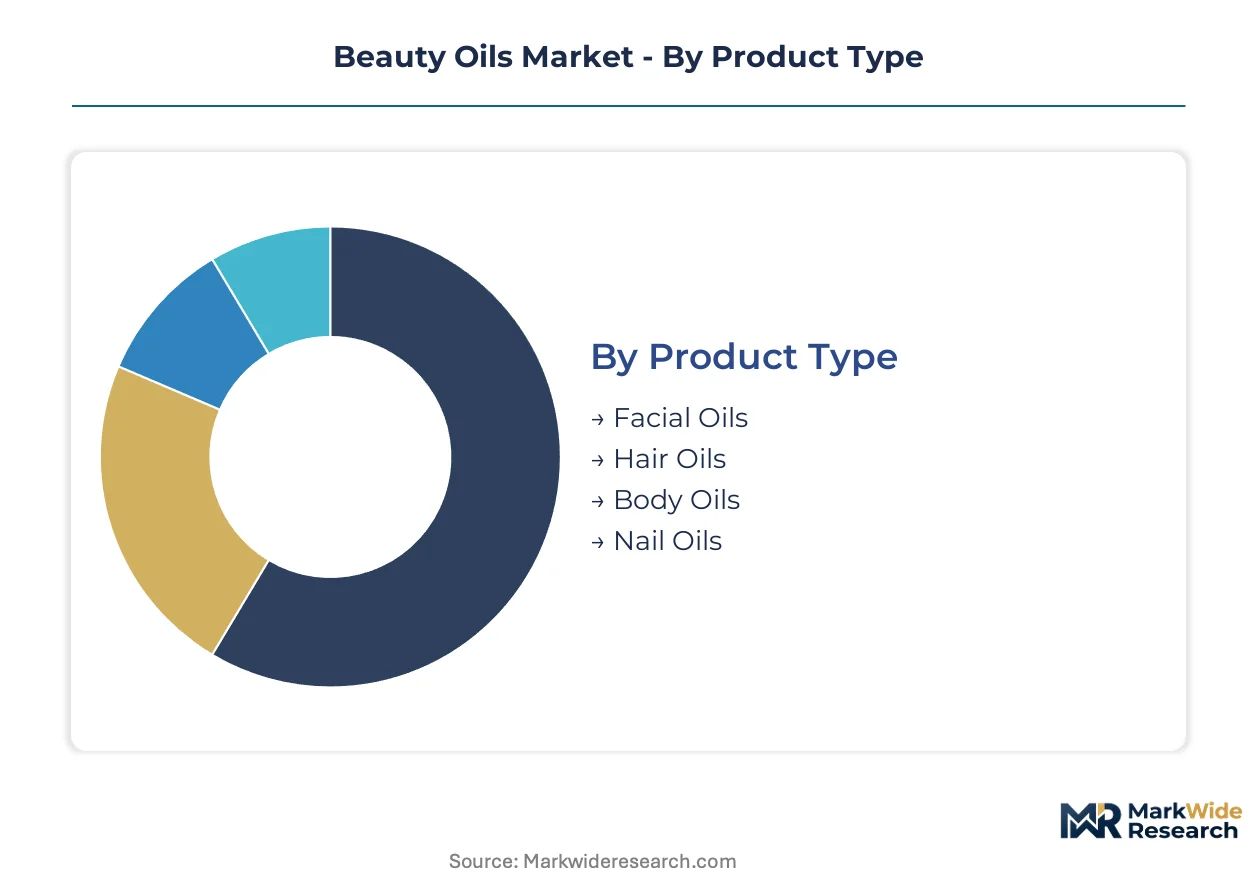
Segmentation in beauty oils reveals how formulation chemistry, ritual tradition, and retail channel economics create divergent margin structures across otherwise similar lipid-based products. Understanding these divides explains why identical raw materials command vastly different price realizations depending on end-use positioning and geographic consumption patterns.
Product Type:
After-sales-service intensity varies dramatically across product types, with facial oils demanding educational support for proper layering techniques while hair oils rely on established cultural knowledge bases that reduce ongoing customer service burdens.
- Facial Oils:Concentrated triglyceride and essential fatty acid formulations designed for barrier repair and active delivery. Demand concentrates in United States direct-to-consumer channels where algorithmic skin assessments drive personalized blend recommendations and subscription retention infrastructure captures lifetime value.
- Hair Oils:Occlusive and penetrating lipid preparations rooted in South Asian and Middle Eastern oiling rituals. Volume dominance persists in India and Saudi Arabia where weekly application traditions sustain mass-market consumption despite lower per-unit margins.
- Body Oils:Sensorial-focused lipid vehicles emphasizing spreadability and fragrance retention for post-shower application.
- Nail Oils:Cuticle conditioning formulations with high vitamin E and jojoba concentrations targeting professional salon supply chains.
Facial oils hold the largest share; momentum sits with hair oils as emerging market purchasing power expands.
Ingredient Source:
Cost tier stratification separates commodity-derived inputs from traceable botanical alternatives, with certification requirements and carbon accounting creating pricing spreads that favor scaled suppliers with verified supply chain documentation.
- Plant-Based:Cold-pressed or CO2-extracted botanical lipids from argan, marula, jojoba, and upcycled fruit seed sources. Demand concentrates in European Union markets where REACH authorization lists and EU Green Deal biopolicy mandate biodegradable alternatives to petrochemical inputs.
- Mineral-Based:Refined petroleum-derived occlusives including paraffin and mineral oil fractions facing steepest compliance costs in hair care applications due to higher usage volumes.
- Synthetic:Laboratory-engineered esters and silicones offering batch consistency and cost stability.
- Animal-Derived:Lanolin, squalene from shark liver, and emu oil serving niche therapeutic and premium positioning segments.
Plant-based sources hold the largest share; fermentation-derived lipids within synthetic categories are climbing the fastest as precision biotechnology stabilizes supply.
Application:
Customer type divergence separates medical-adjacent positioning from wellness lifestyle branding, with regulatory substantiation requirements creating distinct go-to-market pathways and margin profiles.
- Skincare:Barrier repair and anti-aging claims requiring clinical testing and FDA substantiation that extends development cycles. Premium pricing concentrates in prestige retail and medical spa channels.
- Haircare:Conditioning and scalp health applications with lower regulatory barriers but higher volume throughput in mass-market distribution.
- Aromatherapy:Essential oil blends positioned for psychological benefit and ritual use.
- Massage:Professional therapy supply with glide and absorption specifications.
Skincare holds the largest share; aromatherapy is gaining share fastest as wellness positioning expands in direct-to-consumer channels.
Packaging Type:
Volume and margin dynamics favor formats that balance oxidation protection with dispensing precision, with airless systems commanding premiums in facial applications while sachets capture trial and travel occasions.
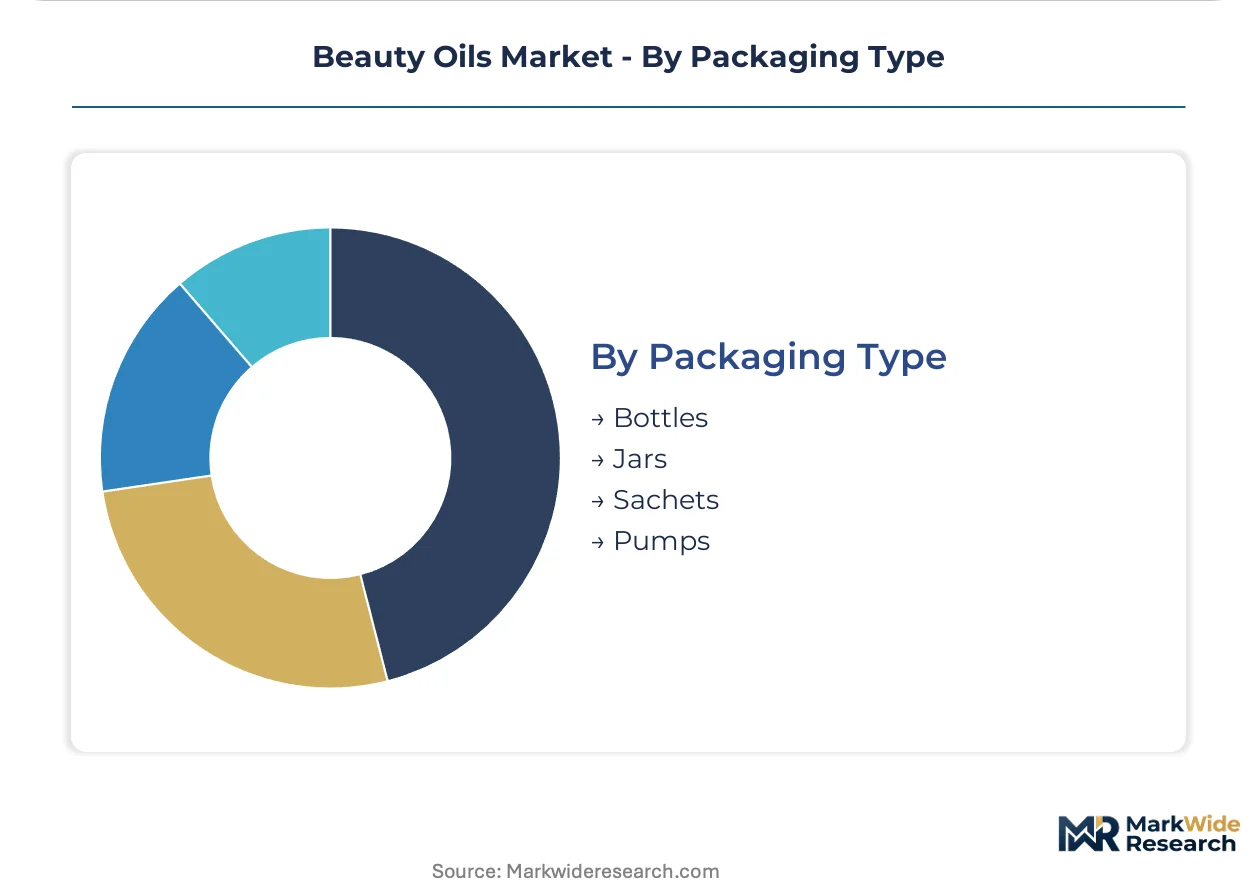
- Bottles:Standard glass or PET containers with dropper or screw-cap closures dominating facial oil prestige positioning.
- Jars:Wide-mouth containers for solid and semi-solid oil balms requiring finger application.
- Sachets:Single-use foil or film packets for sampling, hotel amenities, and emerging market affordability tiers.
- Pumps:Airless and metered-dose systems preventing oxidation and contamination in high-actives formulations.
Bottles hold the largest share; pumps are expanding most quickly as microbiome-friendly and preservative-free claims drive protective packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in beauty oils tilt toward net imports in Western markets while South Asian and North African suppliers anchor raw material outflows. The United States absorbs premium finished formulations. Morocco and India dominate upstream botanical extraction.
United States
Direct-to-consumer digital brands capture facial oil demand through algorithmic skin assessments and subscription retention models. FDA cosmetic safety substantiation requirements create compliance cost tiers favoring scaled manufacturers with dedicated regulatory affairs functions. Brooklyn and Los Angeles host emerging clean-beauty formulator clusters where cold-pressed extraction infrastructure attracts venture capital.
Germany
EU REACH authorization lists and the EU Green Deal accelerate biodegradable botanical oil adoption in mass-market skincare. ECHA compliance documentation requirements compress formulation timelines as brands eliminate petrochemical-derived emollients. Hamburg and Düsseldorf concentrate specialist lipid-delivery system laboratories serving prestige European houses.
India
Hair oiling rituals sustain volume dominance in mass-market consumption despite lower per-unit margins. BIS cosmetic standards and DGFT export incentives shape processing facility investments. Mumbai and Tamil Nadu processing clusters supply amla and coconut derivatives to global formulators seeking traceable botanical documentation.
Japan
Hybrid oil-serum textures target East Asian skin barrier concerns with lightweight lipid vehicles layering under sunscreen. METI guidance on cosmetic ingredient transparency pressures disclosure of fermentation-derived lipid sourcing. Osaka and Tokyo anchor precision biotechnology development for squalane and rare fatty acid production.
Morocco
Argan cooperative networks face single-origin dependency risks as climate-sensitive harvest fluctuations destabilize contract pricing. The country's national agricultural export programs support cold-press facility modernization. Essaouira and Agadir processing clusters supply premium cosmetic-grade argan oil to European and North American prestige brands.
Beauty Oils Market Competitive Landscape
On the supply side, the industry is consolidating around integrated botanical sourcing networks and biotechnology-derived lipid platforms. Prestige skincare houses anchor competitive positioning on proprietary extraction technologies and fermentation capabilities. Three archetypes dominate: legacy conglomerates with multi-continent supply chains, digital-native direct-to-consumer specialists, and regional fermentation biotechnology firms. Capacity expansion in cold-press infrastructure and strategic partnerships for carbon-footprint verification represent the dominant competitive moves.
Within the legacy conglomerate tier, L'Oréal S.A., The Estée Lauder Companies Inc., and Shiseido Company, Limited exemplify divergent sourcing strategies. The Paris-based S.A. structure anchors integrated botanical networks across multiple continents. The New York-incorporated specialist occupies a position centered on proprietary fermentation-derived oil technologies. The Tokyo-based Limited company represents hybrid texture innovation targeting East Asian skin barrier concerns.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| The Estée Lauder Companies Inc. |
| Unilever PLC |
| Shiseido Company, Limited |
| The Procter & Gamble Company |
| Beiersdorf AG |
| Amorepacific Corporation |
| Clarins S.A. |
| KOSÉ Corporation |
| Others |
Value Network & Pricing Analysis
Moroccan argan cooperative networks and Indian amla processing clusters anchor upstream supply, concentrating pricing power among heritage botanical extractors while prestige skincare houses capture downstream margin pools through proprietary fermentation technologies and cold-press extraction infrastructure.
Pricing Analysis
Prestige brand buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on cold-press certification grade and carbon-footprint verification status. Pricing pressure stems from climate-sensitive crop harvest fluctuations destabilizing contract agreements. Direct-to-consumer subscribers demonstrate lowest price sensitivity while mass-market hair oil purchasers in emerging markets exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from European prestige houses now finance Moroccan cooperative facility upgrades and Indian processing cluster modernization. Geographic supply concentrates in Morocco, India, and Japan. Raw material dependencies center on argan kernels, amla fruit, and fermentation-derived squalane feedstocks. Single-origin vulnerability from Moroccan argan cooperatives creates structural risk. Distribution runs through direct-to-consumer subscription platforms and prestige retail counters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward algorithmic direct-to-consumer platforms as subscription retention infrastructure consolidates facial oil demand, fragmenting traditional department store counter influence.
For Market Incumbents: Entrench proprietary fermentation-derived lipid capabilities and captive cold-press extraction infrastructure to defend against biotechnology new entrants. Secure multi-origin botanical sourcing across at least three continents to mitigate climate-driven harvest volatility. Invest in EU CSRD-compliant carbon-footprint verification to maintain shelf presence under tightening disclosure mandates. For New Entrants and Emerging Players: Mid-market hybrid oil-serum textures for East Asian consumers represent the most penetrable entry point, as lightweight lipid vehicles layering under sunscreen remain undersupplied outside prestige tiers. Upcycled fruit seed oil formulations targeting EU Green Deal compliance offer regulatory-aligned positioning. Deploy algorithmic skin assessment tools to bypass retail markups and capture subscription lifetime value. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed direct-to-consumer brands possessing robust retention infrastructure but limited upstream supply control. Five-to-ten-year viability favors platforms integrating biotechnology-derived lipid production with verified Scope 3 documentation. Watch for FDA substantiation requirement clarifications on microbiome-friendly claims as inflection signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extraction Capacity Expansion | Moroccan and Indian facility upgrades secure premium-grade botanical supply for REACH-compliant formulations. |
| Fermentation-Derived Lipid Scale-Up | Precision biotechnology platforms in Japan and Germany stabilize squalane supply without agricultural land constraints. |
| Carbon-Footprint Verification Program | EU CSRD-compliant Scope 3 documentation creates first-mover advantage in prestige retail channels. |
| Direct-to-Consumer Platform Integration | Algorithmic skin assessments and subscription retention infrastructure displace department store counter economics. |
| Hybrid Texture R&D Investment | Lightweight oil-serum vehicles address East Asian skin barrier concerns and sunscreen layering rituals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, EU REACH authorization filings, and SEC disclosures from listed cosmetic conglomerates. Formulation chemists, procurement leads at prestige houses, cold-press facility operators, and direct-to-consumer brand founders provided stakeholder perspective. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs include product type segmentation, ingredient source tier, application channel, and packaging format dimensions. Modeled variables span facial oil subscription retention rates, hair oil ritual adherence patterns, and fermentation capacity buildout timelines. CAGRs derive from regression analysis of historical premium skincare pricing elasticity and biotechnology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or agricultural commodity price volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline adherence and climate stability for Mediterranean and South Asian crop regions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
US Natural Personal Care Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
South America Bath and Shower Products Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
China Electric Face Cleanser Market