
 Europe Cosmeceuticals Market | 2026-2036
Europe Cosmeceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cosmeceuticals Market Foresight
Subscription-based replenishment programs for active-ingredient regimens is consolidating recurring revenue models across European cosmeceutical brands. L'Oréal SA leverages its dermatological science platform to sustain prescription-adjacent credibility. Beiersdorf AG anchors its position through pharmacy-centric distribution in German-speaking markets. Estée Lauder Companies Inc. competes via prestige-clinic partnerships that blur retail and professional channels.
Cosmeceuticals occupy the regulatory interstice between cosmetics and pharmaceuticals, typically incorporating bioactive concentrations of retinoids, peptides, or hyaluronic acid at 0.3-2% potency thresholds to deliver measurable skin-biology modulation without requiring drug approval. Their primary commercial purpose bridges consumer aspiration with clinically validated outcomes, commanding price premiums over mass cosmetics while avoiding pharmaceutical development timelines. Anti-aging formulations command the largest revenue pool among product types, though acne treatment segments attract younger demographics with higher lifetime value potential. Peptide-based ingredient platforms are gaining fastest among dermatologist-directed channels, while hyaluronic acid remains the volume anchor across supermarket and online retail tiers.
EMA guidelines on borderline product classification interact with REACH chemical safety protocols and the EU Cosmetics Regulation to create a compliance architecture that favors established formulators with dedicated regulatory affairs teams. France's ANSM and Germany's BfArM enforce divergent notification timelines that fragment market entry speed across the region's two largest economies. Stakeholders must monitor evolving EU Green Deal requirements for biodegradability and microplastic-free formulations, as these standards will reshape ingredient sourcing decisions and reformulation costs ahead of enforcement deadlines.
Market Dynamics
EU Cosmetics Regulation (EC) No 1223/2009 ingredient disclosure mandates are compressing formulation timelines while elevating compliance costs, forcing cosmeceutical brands to restructure R&D pipelines around pre-validated active ingredient platforms.
Growth Catalysts
- Medical-aesthetic corridor expansion:Dermatology clinics from Berlin to Munich are professionalizing skincare protocols, creating institutional demand for prescription-adjacent retinoid and peptide formulations.
- REACH chemical safety alignment:Standardized safety data requirements across EU member states reduce redundant testing burdens for established formulators with dedicated regulatory affairs infrastructure.
- Subscription replenishment models:Recurring revenue architectures for active-ingredient regimens lock in consumer lifetime value while smoothing manufacturing demand curves.
Market Restraints
- Hyaluronic acid supply concentration:Fermentation-derived sodium hyaluronate production clusters in Chinese biotech hubs, exposing European formulators to input cost volatility and geopolitical supply risk.
- Borderline classification friction:EMA guidelines on pharmaceutical-cosmetic boundaries interact divergently with France's ANSM and Germany's BfArM notification timelines, fragmenting product launch velocity.
- Biodegradable surfactant substitution pressure:EU Green Deal microplastic-free mandates force reformulation away from established polymer-based delivery systems before cost-competitive alternatives achieve scale.
Strategic Opportunities
- Poland and Czech Republic pharmacy channel penetration:Underdeveloped professional skincare infrastructure in Central European markets offers first-mover positioning for clinic-grade peptide platforms.
- AI-driven skin diagnostics convergence:Integration of smartphone-based dermal imaging with personalized regimen algorithms opens direct-to-consumer channels bypassing traditional retail gatekeepers.
- CSRD sustainability reporting alignment:Mandatory corporate disclosure on environmental impact creates procurement preference for cosmeceutical suppliers with verified biodegradability credentials.
Industry Challenges
- Cosmetic toxicologist talent scarcity:Specialized expertise in EU Cosmetics Regulation safety assessment dossiers commands premium compensation, constraining mid-tier brand expansion.
- Clinical validation capex intensity:Substantiation of bioactive claims requires dermatological testing protocols that compress margin structures for sub-scale competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cosmeceuticals Market |
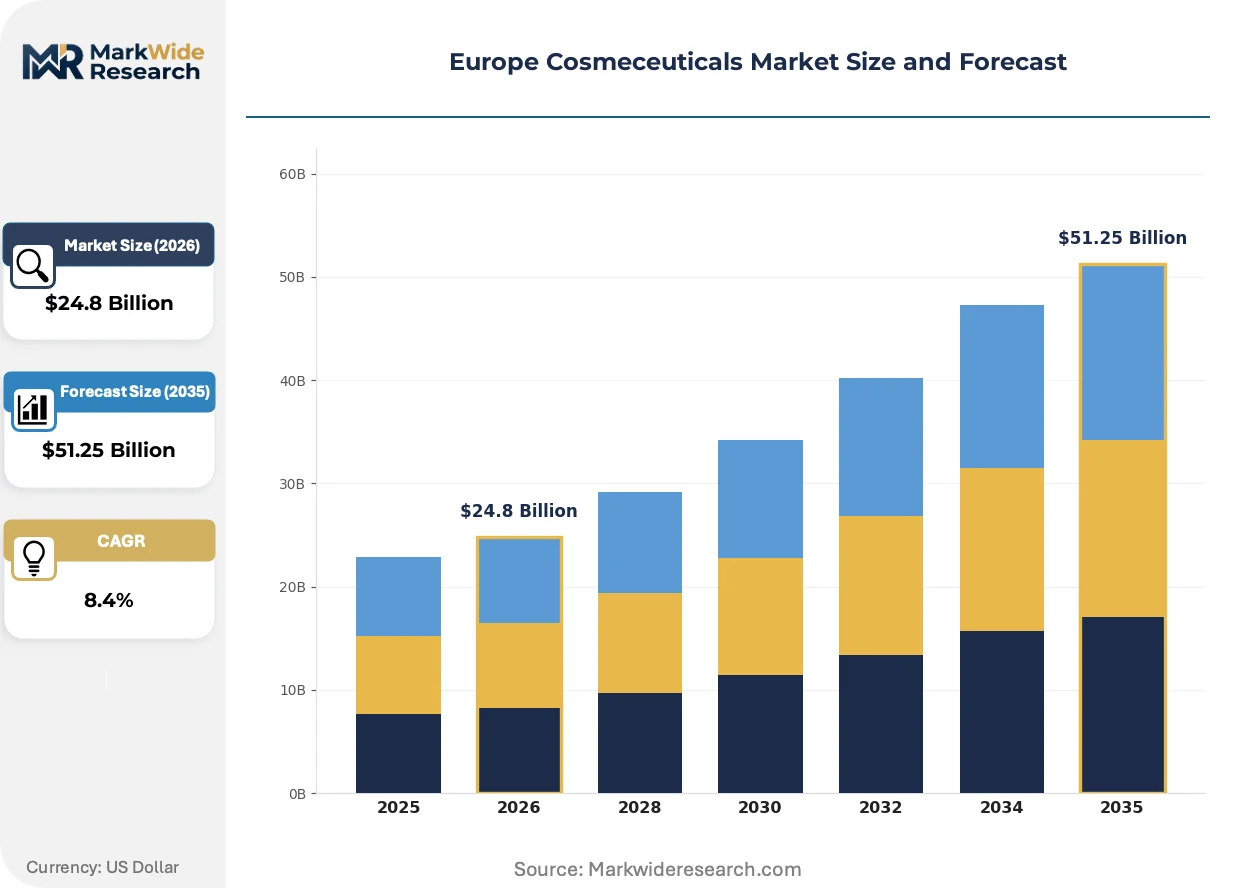
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Aging, Moisturizers, Serums, Acne Treatment Ingredient Type: Botanical Extracts, Peptides, Retinoids, Hyaluronic Acid Distribution Channel: Online Retail, Pharmacies, Specialty Stores, Supermarkets End User: Women, Men, Dermatologists, Spas |
| Companies Covered | L'Oréal SA, Beiersdorf AG, Estée Lauder Companies Inc., Pierre Fabre Dermo-Cosmétique, Galderma S.A., Unilever PLC, Procter & Gamble Company, Shiseido Co. Ltd, Johnson & Johnson Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cosmeceuticals Market Shifts & Advancements
Formulation science is pivoting from mass-market compatibility toward precision delivery systems that modulate skin biology at measurable thresholds, while regulatory architecture and procurement patterns undergo parallel restructuring.
Encapsulated retinoid delivery systems using lipid nanoparticle carriers are decentralizing potency distribution across epidermal layers, enabling higher active concentrations without irritation penalties. Dermatology clinics in France and Germany are adopting these platforms at accelerated cadence for pre- and post-procedure protocols. The technology is decentralizing competitive advantage from mass-market scale toward clinical credibility and professional endorsement networks.
REACH registration requirements for novel cosmetic ingredients are tightening safety data obligations, extending new active substance approval timelines. Established formulators with existing substance dossiers capture disproportionate pipeline access while challengers face capitalized compliance barriers. Peptide-based innovation platforms face the most acute timeline compression, driving consolidation around pre-registered ingredient libraries.
Pharmacy-centric replenishment programs are displacing supermarket and department store cosmeceutical purchasing across German-speaking markets. Clinic-adjacent subscription models lock consumers into 90-day active ingredient cycles with professional monitoring touchpoints. This channel rotation is most visible in Bavaria and Baden-Württemberg, where pharmacy chains have integrated diagnostic consultation into skincare retail workflows.
Europe Cosmeceuticals Market Segmentation
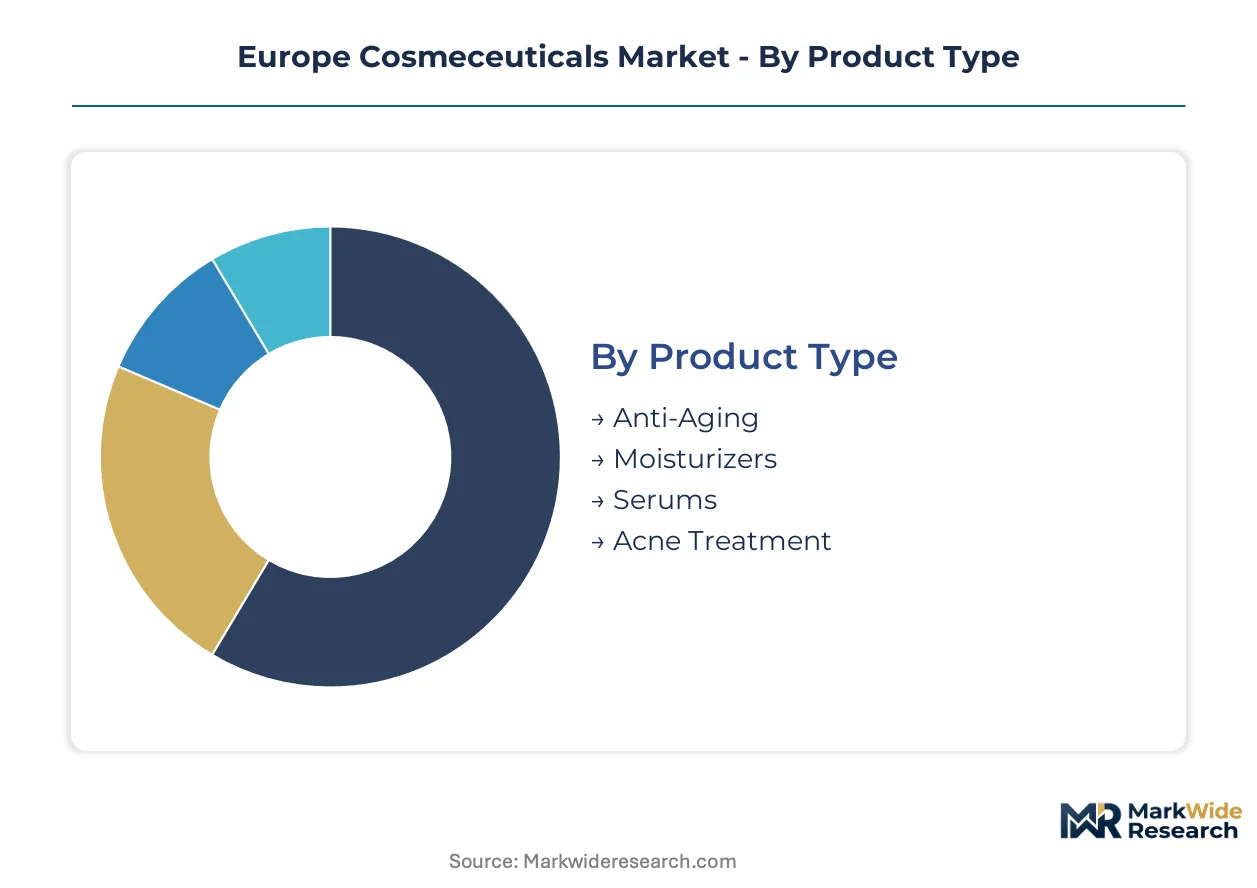
Segmentation in Europe's cosmeceutical market reveals how formulation science, channel economics, and professional endorsement networks allocate margin capture across competing business models. Distinct consumer archetypes and procurement pathways demand tailored positioning strategies.
Product Type:
Supply concentration in active-ingredient manufacturing favors categories with validated bioactive platforms and established dermatological credibility.
- Anti-Aging:Retinoid and peptide formulations targeting collagen synthesis and cellular turnover command premium positioning in clinic-adjacent channels. German dermatology practices from Berlin to Munich anchor institutional demand for prescription-strength retinoid protocols.
- Acne Treatment:Salicylic acid and adapalene-based regimens attract younger demographics with extended lifetime value potential. French pharmacy chains prioritize these SKUs for their consultation-driven retail workflows.
- Moisturizers:Barrier-repair formulations with ceramide complexes dominate volume across supermarket tiers.
- Serums:Concentrated active delivery vehicles concentrate margin in specialty retail and online direct-to-consumer channels.
Today's leader: Anti-Aging. Tomorrow's challenger: Acne Treatment.
Ingredient Type:
Cost tier differentiation separates fermentation-derived biotech inputs from botanical extraction supply chains with divergent capital intensity profiles.
- Hyaluronic Acid:Fermentation-derived sodium hyaluronate at multiple molecular weights anchors volume production across all retail tiers. Chinese biotech hub concentration exposes European formulators to input cost volatility and geopolitical supply risk.
- Peptides:Signal peptides and carrier peptides require specialized solid-phase synthesis capabilities that limit supplier bases. REACH registration timelines for novel sequences compress innovation pipelines toward pre-registered ingredient libraries.
- Retinoids:Encapsulated delivery systems using lipid nanoparticle carriers enable higher potency thresholds without irritation penalties.
- Botanical Extracts:EU Green Deal biodegradability mandates favor domestically sourced plant actives with verified supply chain credentials.
Volume anchor: Hyaluronic Acid. Margin expansion engine: Peptides.
Distribution Channel:
Customer type stratification determines whether procurement emphasizes professional consultation, convenience, or price transparency.
- Pharmacies:German-speaking markets lead pharmacy-centric replenishment programs with integrated diagnostic consultation. Bavaria and Baden-Württemberg chains lock consumers into 90-day active ingredient cycles.
- Online Retail:AI-driven skin diagnostics and personalized regimen algorithms bypass traditional retail gatekeepers. Direct-to-consumer subscription models concentrate recurring revenue for peptide-based platforms.
- Specialty Stores:Prestige positioning depends on clinic partnerships that blur professional and retail boundaries.
- Supermarkets:Mass-market hyaluronic acid moisturizers compete on shelf presence and promotional velocity.
Channel maturity leader: Pharmacies. Disruption vector: Online Retail.
End User:
Application context determines whether procurement emphasizes clinical outcomes, experiential positioning, or maintenance convenience.
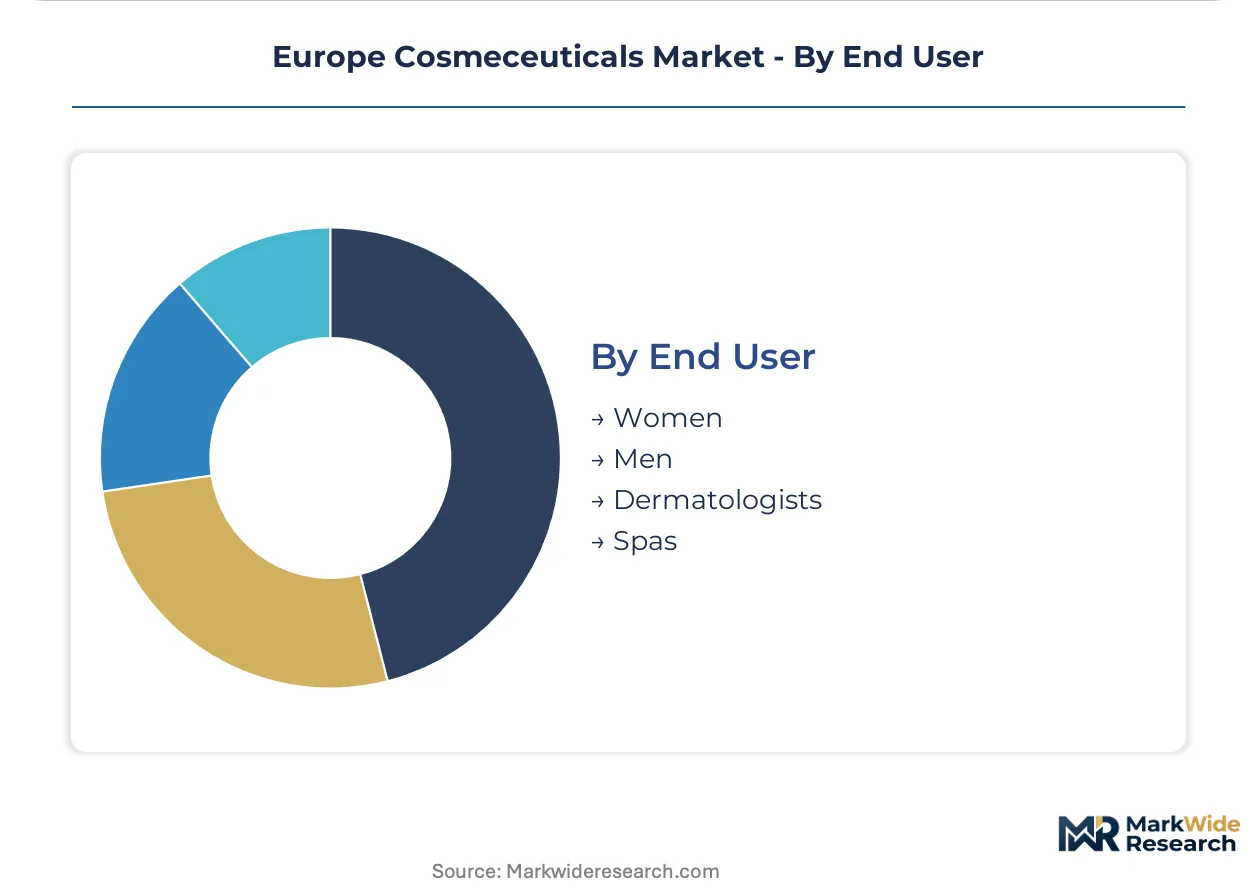
- Women:Core demographic across all product categories with established replenishment behavior and channel loyalty.
- Dermatologists:Professional gatekeepers drive adoption of encapsulated retinoid systems and peptide platforms for pre- and post-procedure protocols in French and German clinics.
- Men:Underpenetrated segment with emerging demand for simplified regimens in Central European markets.
- Spas:Experiential channels favor sensorial formulations with immediate perceptible effects over long-term bioactive modulation.
Established revenue base: Women. Professional credibility anchor: Dermatologists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy-centric distribution networks contrast with France's dermatology clinic density, yet both anchor distinct pathways for professional-grade cosmeceutical penetration across the continent.
Germany
The medical-aesthetic corridor linking Berlin to Munich drives institutional demand for prescription-adjacent retinoid protocols. BfArM notification timelines for borderline products compress launch velocity for novel peptide formulations. Bavaria and Baden-Württemberg pharmacy chains integrate diagnostic consultation into 90-day replenishment cycles.
France
Dermatology clinics in Paris and Lyon professionalize pre- and post-procedure skincare, creating captive demand for encapsulated delivery systems. ANSM enforces divergent ingredient disclosure mandates from German counterparts, fragmenting compliance architecture. The Île-de-France cluster concentrates formulation R&D alongside L'Oréal's dermatological science platform.
United Kingdom
London's prestige retail and clinic hybrid channels blur professional and consumer boundaries for peptide-based regimens. MHRA post-Brexit regulatory divergence from EU Cosmetics Regulation creates parallel compliance tracks. Southeast England's direct-to-consumer logistics hubs enable AI-driven skin diagnostics with personalized algorithm deployment.
Italy
Lombardy's pharmaceutical manufacturing base supplies active-ingredient platforms to Mediterranean markets. REACH registration requirements for novel cosmetic ingredients extend approval timelines for domestic formulators. Milan's aesthetic medicine clusters adopt pharmacy-centric replenishment models from German-speaking markets.
Poland
Warsaw and Krakow pharmacy channels remain underdeveloped for professional skincare infrastructure, offering first-mover positioning for clinic-grade peptide platforms. EU Green Deal biodegradability mandates reshape ingredient sourcing decisions ahead of enforcement deadlines. Central European price sensitivity favors hyaluronic acid volume anchors over premium retinoid tiers.
Europe Cosmeceuticals Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmacy-centric formulators capturing recurring revenue while clinic-direct platforms concentrate margin through professional endorsement. The vendor base organizes around three tiers: multinational science platforms with dedicated regulatory affairs infrastructure, mid-cap regional specialists with channel-specific positioning, and private-label contract manufacturers serving supermarket and online retail tiers. Consolidation pressures favor established players with pre-registered REACH substance dossiers. Competitive moves center on M&A for peptide synthesis capabilities and strategic partnerships with dermatology clinic networks.
Among French-headquartered science platforms, L'Oréal SA and Pierre Fabre Dermo-Cosmétique exemplify the prescription-adjacent credibility archetype through dermatological research integration. Beiersdorf AG anchors the German pharmacy-centric distribution model with its GmbH structure signaling embedded regional infrastructure. Galderma S.A. occupies a position bridging pharmaceutical development timelines with cosmetic market access, representing the borderline product classification specialist tier. These three entities collectively illustrate how geographic origin and corporate form signal divergent strategic postures toward regulatory complexity and channel control.
| Leading Market Players |
|---|
| L'Oréal SA |
| Beiersdorf AG |
| Estée Lauder Companies Inc. |
| Pierre Fabre Dermo-Cosmétique |
| Galderma S.A. |
| Unilever PLC |
| Procter & Gamble Company |
| Shiseido Co. Ltd |
| Johnson & Johnson Inc. |
| Others |
Supply & Pricing Matrix
Pharmacy chain procurement concentration across German-speaking markets anchors subscription-based pricing models that smooth demand volatility while locking in recurring revenue streams for active-ingredient regimens.
Pricing Analysis
Capacity additions in Chinese biotech hubs are reshaping price floors for fermentation-derived sodium hyaluronate, compressing margins on volume-tier moisturizers while peptide synthesis bottlenecks sustain premium positioning for dermatologist-directed platforms. Three-tier pricing structure across premium clinic-grade, standard pharmacy-tier, and economy supermarket levels separates encapsulated retinoid systems from basic hyaluronic acid formulations. Cost compression in mass-market tiers is intensifying because Chinese supply expansion outpaces European demand growth. Supermarket buyers exhibit highest price sensitivity; dermatology clinics demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes compounds input expense uncertainty for European formulators dependent on offshore biotechnology inputs. Fermentation-derived sodium hyaluronate production clusters in Chinese biotech hubs; peptide solid-phase synthesis capabilities concentrate in Switzerland and South Korea; botanical extraction supply chains draw from Provence and Andalusia. Raw material dependencies span sodium hyaluronate fermentation feedstock, amino acid precursors for peptide synthesis, and lipid nanoparticle carrier compounds. Single-source vulnerability in Chinese hyaluronic acid supply exposes formulators to geopolitical disruption. Distribution runs through pharmacy-centric replenishment programs in German-speaking markets, online direct-to-consumer platforms, and clinic-direct professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's cosmeceutical market functions as a stable compounder, with subscription replenishment architectures generating predictable recurring revenue that dampens cyclical exposure across economic conditions.
For Market Incumbents: Deepen regulatory affairs infrastructure to capture disproportionate pipeline access as REACH timelines compress for novel peptide sequences. Prioritize backward integration into encapsulated delivery system manufacturing to defend margin position against contract manufacturer pricing power. Acquire pre-registered ingredient libraries to neutralize challenger access to accelerated formulation pathways. For New Entrants and Emerging Players: EU Green Deal biodegradability mandates in Central and Eastern Europe open a window for domestically sourced botanical active platforms that bypass established supply chain concentrations. Target Poland and Czech Republic pharmacy channels where professional skincare infrastructure remains underdeveloped. Deploy AI-driven skin diagnostics as direct-to-consumer entry mechanism bypassing retail gatekeeper control. For Investors and Strategic Acquirers: Pharmaceutical companies seeking cosmetic market access without drug development timelines are the most active acquirer in this space, driving valuation premiums for borderline product classification specialists. Focus on mid-cap peptide synthesis capabilities with existing REACH dossiers as acquisition target archetype. Watch for BfArM-ANSM regulatory convergence as inflection indicator for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capability Acquisition | REACH registration timelines favor incumbents with pre-validated active ingredient libraries over challengers. |
| Pharmacy Channel Integration | Bavarian and Baden-Württemberg chains demonstrate how diagnostic consultation locks consumers into 90-day cycles. |
| Encapsulated Delivery System Investment | Lipid nanoparticle carriers enable higher retinoid potency without irritation penalties in clinic protocols. |
| AI-Driven Diagnostics Platform Launch | Smartphone-based dermal imaging bypasses traditional retail gatekeepers for direct-to-consumer peptide regimens. |
| Biodegradable Formulation Transition | EU Green Deal microplastic-free mandates reshape ingredient sourcing ahead of enforcement deadlines. |
Research Methodology
Direct dialogue with dermatology clinic directors, pharmacy chain procurement managers, cosmetic toxicologists, and regulatory affairs specialists at established formulators grounded qualitative insights in operational reality. Secondary validation drew from EMA borderline product guidelines, ANSM and BfArM notification databases, EU Cosmetics Regulation (EC) No 1223/2009 compliance filings, and REACH substance dossier records. Bottom-up demand modeling across product type, ingredient platform, distribution channel, and end-user segments triangulated against top-down market sizing from trade flow analysis.
Segment-level value projections across the analysis window reflect econometric relationships between dermatology clinic density, pharmacy channel penetration rates, and subscription adoption curves. Modeled dimensions span anti-aging versus acne treatment demand, hyaluronic acid versus peptide ingredient tiers, pharmacy versus online versus clinic-direct channels, and women versus dermatologist versus men end-user archetypes. CAGRs emerged from regression analysis linking historical replenishment program growth to professional channel expansion trajectories, with input from AI diagnostic adoption curves and regulatory timeline compression effects.
Revisions become necessary when REACH substance approval timelines extend beyond modeled assumptions, when Chinese hyaluronic acid supply experiences geopolitical disruption, or when EU Green Deal enforcement accelerates reformulation cost schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Cosmetic Serum Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market