
 Europe Shampoo Market | 2026-2036
Europe Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Shampoo Market Foresight
Germany is reconfiguring its position as the largest production hub for sulfate-free shampoo formulations in Western Europe. Unilever leverages its Rotterdam-based R&D center to anchor clean-label innovation across the region. L'Oréal competes through specialized salon-grade distribution networks that dominate professional channel access. Henkel sustains manufacturing scale advantages in mass-market liquid formulations through its Düsseldorf operations.
Shampoo comprises surfactant-based cleansing systems, typically containing 10-20% active surfactants such as sodium lauryl sulfate or gentler alternatives like cocamidopropyl betaine, designed to remove sebum and environmental particulates from hair and scalp surfaces. Moisturizing and anti-dandruff variants command the deepest margin pools as consumers prioritize scalp health and hydration claims. Sulfate-free formulations represent the fastest-expanding segment as regulatory pressure and ingredient transparency reshape purchasing behavior. Salon sales channels maintain premium pricing power despite online retail capturing volume growth in standard-tier products.
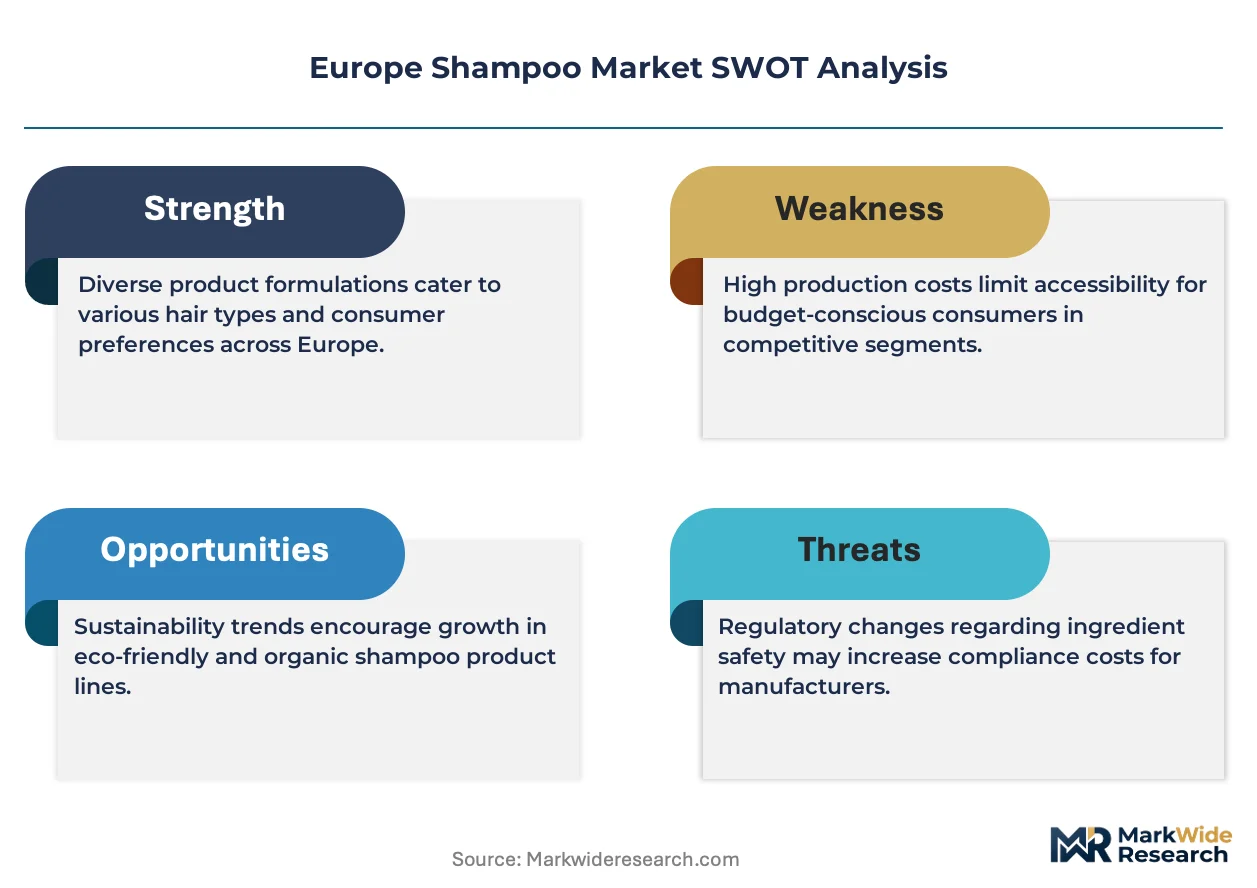
REACH registration requirements and the EU Green Deal framework mandate ingredient disclosure and restrict certain synthetic preservatives, forcing reformulation investments across manufacturers. ECHA substance evaluation processes create compliance timelines that smaller competitors struggle to meet. The CSRD sustainability reporting standards add disclosure obligations that favor companies with established green chemistry programs. Stakeholders must monitor evolving ECHA candidate list additions and assess whether captive organic ingredient sourcing becomes necessary to maintain market access.
Market Dynamics
The European shampoo market is undergoing structural reconfiguration as REACH compliance timelines and the EU Green Deal framework force simultaneous reformulation of thousands of SKUs across the value chain. Manufacturers face compressed investment windows to replace restricted synthetic preservatives while maintaining performance benchmarks and cost structures.
Growth Catalysts
- Clean-label mandates:The EU Green Deal and REACH registration requirements are accelerating consumer demand for ingredient transparency. Reformulation investments are unlocking premium pricing tiers for compliant products.
- Professional channel expansion:Salon-grade formulations are gaining traction among professional stylists seeking differentiated service offerings. Specialized distribution networks are deepening penetration in high-margin professional segments.
- Sulfate-free chemistry:Advanced surfactant alternatives like cocamidopropyl betaine and amino acid-based systems are replacing sodium lauryl sulfate. Germany's production infrastructure is scaling to meet pan-European demand for gentler cleansing systems.
Market Restraints
- Input cost volatility:Organic surfactant feedstocks and certified natural extracts face supply instability. Price fluctuations in coconut-derived and palm-alternative raw materials compress margin predictability.
- Regulatory friction:ECHA substance evaluation processes create compliance timelines that smaller competitors struggle to meet. Candidate list additions force reactive reformulation cycles without grandfathering provisions.
- Technical performance gaps:Sulfate-free formulations struggle to match lather intensity and sebum removal efficiency of conventional systems. Consumer switching costs rise when performance benchmarks are not maintained.
Strategic Opportunities
- CSRD-aligned disclosure:The Corporate Sustainability Reporting Directive creates competitive differentiation for companies with established green chemistry programs. Early compliance investments are building investor and retail buyer preference.
- Eastern European expansion:Poland and Romania show underpenetrated demand for premium organic formulations. Local distribution partnerships can capture first-mover positioning in emerging sulfate-free adoption curves.
- Scalp health specialization:Anti-dandruff and microbiome-focused applications represent emerging white space beyond basic cleansing. Clinical validation partnerships with dermatology channels can unlock pharmacy and clinic distribution.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with expertise in natural preservative systems and biodegradable surfactants command premium compensation. Recruitment pipelines from universities lag industry demand by three to five years.
- Legacy equipment reconfiguration:Manufacturing lines optimized for high-foaming sulfate systems require capital-intensive retooling. Batch consistency challenges emerge when processing lower-foam natural formulations.
- Certification timeline compression:COSMOS and ECOCERT organic standards demand extensive documentation and third-party verification. Parallel certification tracks for multiple national markets strain quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Shampoo Market |
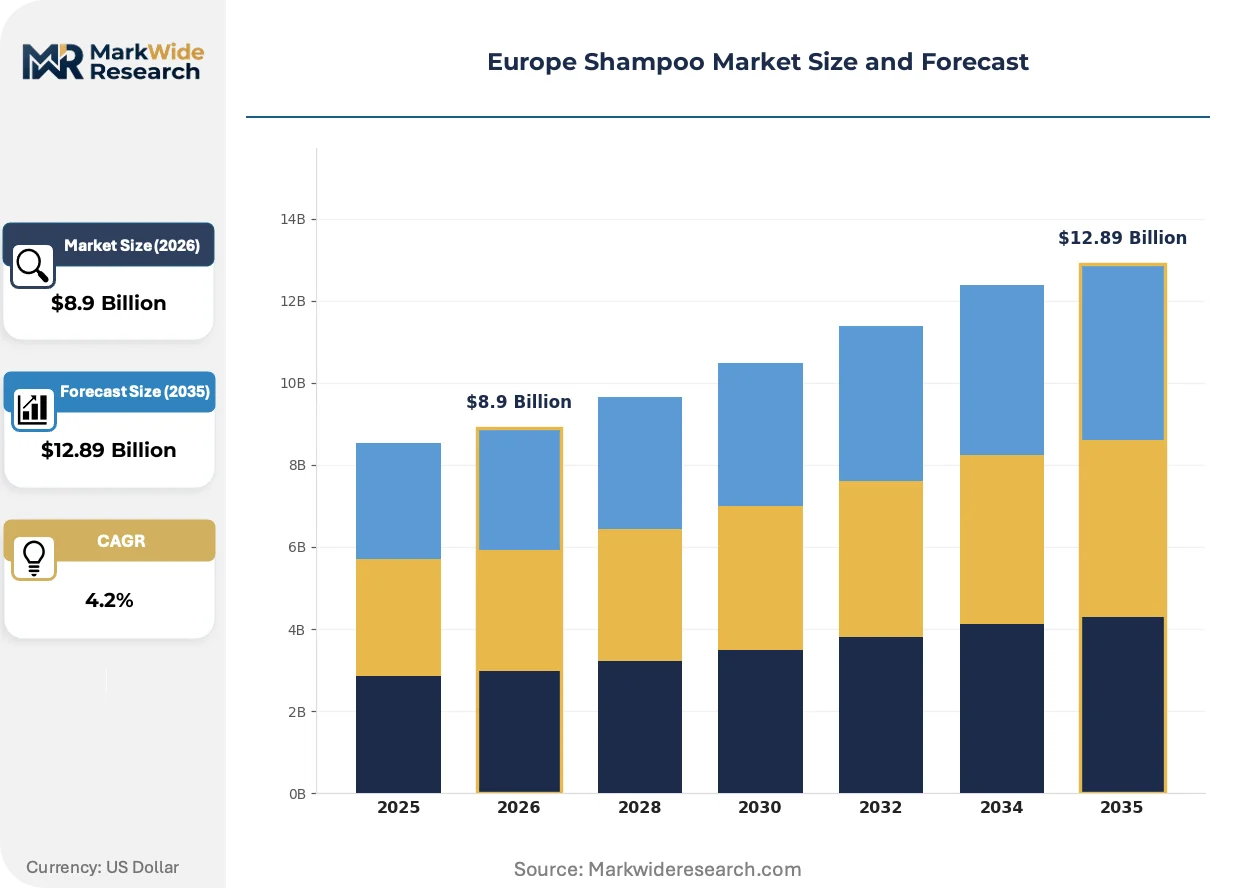
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Dandruff, Moisturizing, Volumizing, Color-Preserving Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Salon Sales End User: Men, Women, Children, Salon Professionals Formulation Type: Organic, Sulfate-Free, Synthetic, Liquid |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal, Henkel, Beiersdorf, Reckitt Benckiser, Colgate-Palmolive, Kao Corporation, P&G Prestige Products, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Shampoo Market Shifts & Advancements
Formulation chemistry and distribution architecture are simultaneously transforming as regulatory pressure intersects with evolving professional and retail channel expectations. Three distinct vectors are restructuring competitive positioning.
Biodegradable surfactant systems are replacing petrochemical-derived cleansing agents in mass-market and premium tiers alike. Professional salons in France and the United Kingdom are piloting concentrated refill formats to reduce packaging waste. The technology is migrating from niche organic specialists toward mainstream manufacturer portfolios as ECHA restrictions tighten on persistent synthetic alternatives.
REACH authorization requirements and the EU Green Deal framework are mandating full supply chain transparency for synthetic preservatives and fragrance compounds. Manufacturers must disclose sub-supplier ingredient sources and conduct hazard assessments for candidate list substances. Mass-market liquid formulations face the steepest compliance burden due to SKU proliferation and complex multi-source supply chains.
Consumers are prioritizing scalp health claims over traditional cosmetic benefits such as shine and fragrance longevity. Pharmacy and clinic channels are displacing conventional retail for therapeutic anti-dandruff and microbiome-focused variants. Germany exhibits the most pronounced channel shift, where pharmacist recommendations carry substantial influence on purchasing decisions for sensitive scalp conditions.
Europe Shampoo Market Segmentation
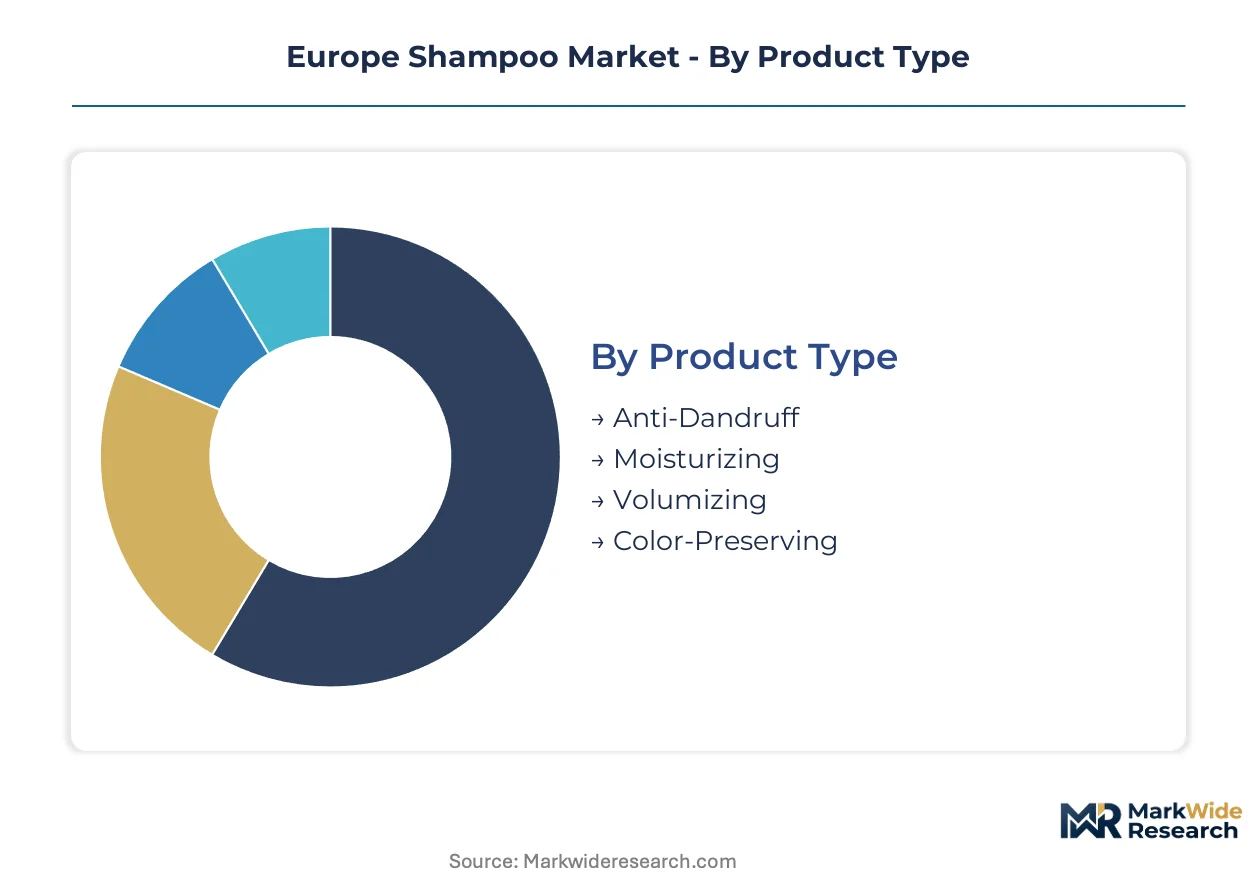
Shampoo segmentation in Europe reflects divergent technical requirements across professional and retail channels. Formulation chemistry, distribution infrastructure, and end-user application intensity create distinct margin architectures that manufacturers must navigate simultaneously.
Product Type:
After-sales engagement intensity varies sharply across functional shampoo categories, with therapeutic variants demanding sustained consumer education and repurchase support.
- Anti-Dandruff:Zinc pyrithione and ketoconazole-based formulations target Malassezia yeast proliferation on the scalp. Pharmacy channels in Germany and France concentrate demand as consumers seek dermatologist-validated solutions for persistent conditions.
- Moisturizing:Glycerin, panthenol, and ceramide-enriched systems restore lipid barriers on damaged hair shafts. Salon professionals in the United Kingdom drive premium-tier demand for intensive hydration treatments.
- Volumizing:Lightweight polymers create temporary lift at the root without residue buildup. Mass-market penetration remains highest among younger demographics seeking daily styling support.
- Color-Preserving:UV filters and acidic pH systems extend artificial pigment retention. Professional color service bundling in French salons sustains pricing premiums for this category.
Moisturizing formulations hold the largest share; momentum sits with anti-dandruff as scalp health claims displace cosmetic benefits in purchasing decisions.
Distribution Channel:
Channel economics stratify around inventory velocity, with high-turnover mass retail commanding fundamentally different service architectures than appointment-based professional sales.
- Supermarkets:Hypermarket and grocery chains move standardized liquid formats through centralized procurement. Price competition compresses margins for national brands while private labels gain shelf space.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture subscription-based replenishment demand. German consumers show highest digital adoption for sulfate-free specialty imports.
- Specialty Stores:Beauty-focused retailers curate premium and niche organic portfolios. Staff training requirements elevate operating costs compared to self-service environments.
- Salon Sales:Professional-only formulations require stylist certification and back-bar demonstration. United Kingdom salon networks maintain exclusive distribution rights for high-concentrate treatment systems.
Supermarkets retain volume leadership; online retail climbs fastest as CSRD-aligned transparency tools enable ingredient verification before purchase.
End User:
Application frequency and performance expectations diverge across demographic segments, with professional users imposing the most stringent formulation standards.
- Men:Simplified two-in-one and three-in-one systems dominate, though beard-care adjacent shampoo demand emerges in urban France. Convenience positioning drives brand switching tolerance.
- Women:Multi-step haircare routines sustain the deepest SKU proliferation and highest per-capita spending. German women lead regional adoption of microbiome-focused scalp treatments.
- Children:Tear-free formulations with mild surfactant systems address parental safety concerns. Pharmacy recommendation influence exceeds advertising impact in this segment.
- Salon Professionals:Licensed stylists require consistent batch performance and concentrated economics for back-bar profitability. Technical support hotlines and education programming cement supplier relationships.
Women command the largest revenue pool; salon professionals deliver the steepest expansion trajectory as service-based differentiation intensifies.
Formulation Type:
Regulatory compliance timelines and raw material sourcing complexity create tiered cost structures that separate mass-market accessibility from premium positioning.
- Organic:COSMOS-certified formulations with minimum 95% natural origin content command ingredient transparency premiums. Supply constraints on certified surfactants limit production scale.
- Sulfate-Free:Amino acid and glucoside-based cleansing systems replace sodium lauryl sulfate for sensitive scalps. REACH restrictions on certain ethoxylated surfactants accelerate technical migration.
- Synthetic:Petrochemical-derived surfactants and preservative systems maintain cost advantages and performance benchmarks. ECHA candidate list monitoring drives proactive reformulation cycles.
- Liquid:Standard aqueous emulsions dominate manufacturing infrastructure and consumer familiarity. Water-weight logistics constrain sustainable packaging innovation compared to solid formats.
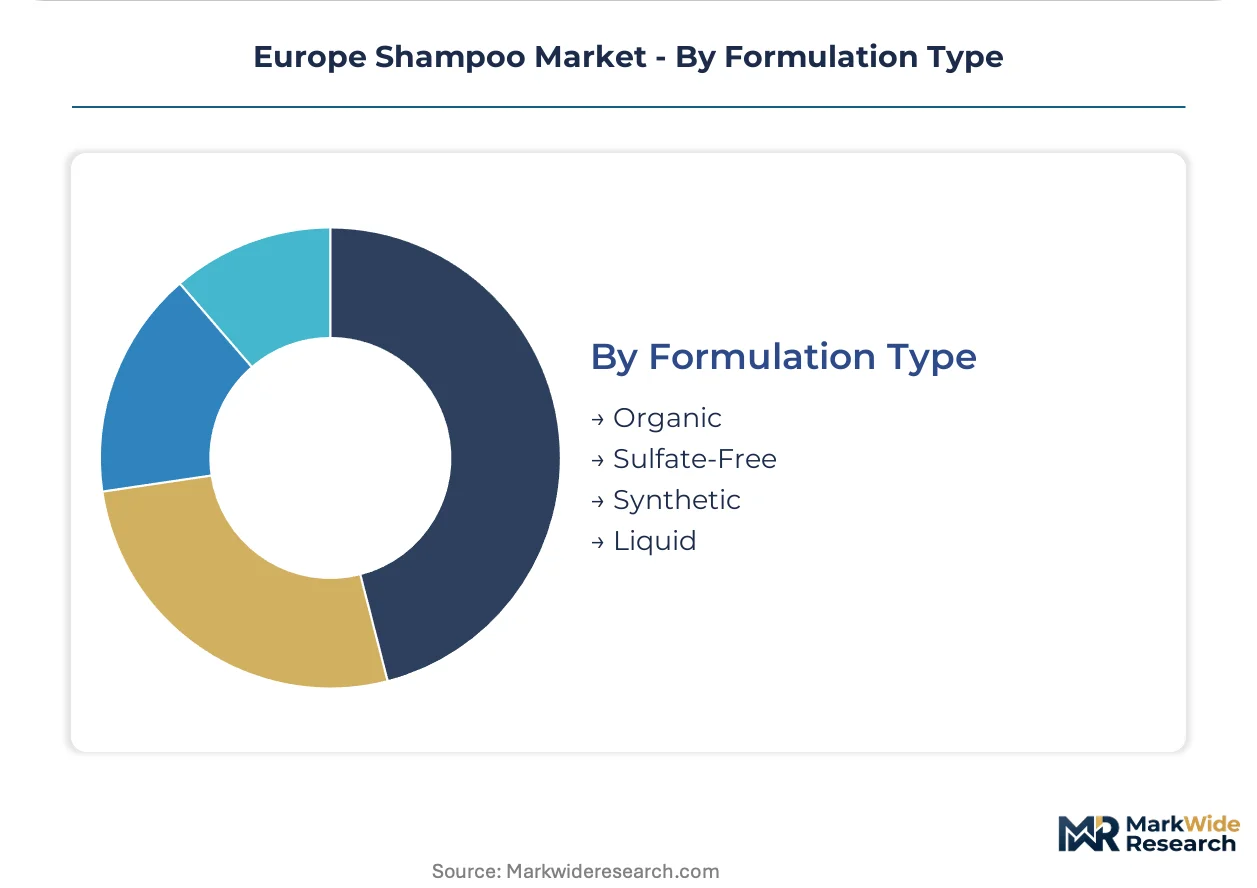
Liquid formulations hold dominant share; organic and sulfate-free categories together gain share fastest as clean-label mandates reshape procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance evaluation processes and REACH compliance timelines anchor strategic positioning across the continent. The EU Green Deal framework mandates simultaneous reformulation investments that reshape national market trajectories.
Germany
Pharmacy channel expansion for scalp health formulations drives demand concentration in urban centers. The Federal Institute for Drugs and Medical Devices enforces strict cosmetic safety assessments that elevate compliance costs for imported brands. Düsseldorf anchors mass-market liquid formulation manufacturing while Berlin-Brandenburg clusters sulfate-free R&D facilities.
France
Professional salon networks sustain premium pricing for color-preserving and treatment systems. ANSM cosmetic surveillance programs mandate enhanced ingredient traceability for products targeting sensitive scalps. Île-de-France concentrates headquarters operations for multinational beauty conglomerates while Provence-Alpes-Côte d'Azur hosts specialized organic ingredient extraction facilities.
United Kingdom
Digital subscription models for sulfate-free specialty imports accelerate online retail penetration. The UK REACH framework maintains regulatory alignment with EU chemical safety standards post-Brexit. Greater London dominates e-commerce fulfillment infrastructure while the Midlands clusters contract manufacturing for private-label salon brands.
Italy
Artisanal organic formulation heritage supports premium positioning in Mediterranean export markets. The Ministry of Health cosmetic notification system enforces rapid compliance updates for restricted preservative lists. Lombardy concentrates luxury haircare production while Emilia-Romagna specializes in biodegradable surfactant ingredient sourcing.
Poland
Underpenetrated demand for certified organic variants creates first-mover expansion opportunities. The Chief Pharmaceutical Inspectorate implements EU cosmetic regulation through national market surveillance programs. Warsaw anchors distribution logistics for Central European wholesale channels while Silesian Voivodeship develops contract manufacturing capacity for Western European brands.
Europe Shampoo Market Competitive Landscape
Capability concentration sits with specialized organic formulators; scale advantage sits with diversified consumer goods conglomerates. The market exhibits tiered structure with premium salon-grade specialists occupying distinct positioning from mass-market liquid manufacturers. Three archetypes dominate: multinational beauty conglomerates with professional channel networks, mid-scale regional organic specialists, and private-label contract manufacturers serving retail chains. Competitive moves center on clean-label reformulation investments and professional distribution exclusivity arrangements.
Within the multinational tier, L'Oréal S.A. and Unilever PLC exemplify divergent strategic positioning through specialized channel access versus R&D-centered innovation architectures. Henkel AG & Co. KGaA occupies a position bridging mass-market scale with professional-grade formulation capabilities. These three entities anchor the competitive structure through their respective emphases on salon distribution, clean-label science, and manufacturing throughput.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal |
| Henkel |
| Beiersdorf |
| Reckitt Benckiser |
| Colgate-Palmolive |
| Kao Corporation |
| P&G Prestige Products |
| Others |
Supply & Pricing Matrix
Düsseldorf's concentrated mass-market liquid formulation capacity grants Henkel and neighboring manufacturers disproportionate leverage over standard-tier pricing across Western European retail channels. This production gravity amplifies margin pressure on smaller competitors when coconut-derived surfactant feedstocks experience supply instability.
Pricing Analysis
German supermarket shelves price sulfate-free formulations at premiums of forty to sixty percent above conventional alternatives, while online retail compresses geographic price spreads through direct-to-consumer imports. Three-tier pricing structure across premium salon-grade, standard mass-market, and economy private-label levels stratifies the market, with certification grade and channel exclusivity serving as primary differentiation drivers. Pricing pressure stems from organic surfactant feedstock volatility as palm-alternative sourcing costs fluctuate. Mass-market retail buyers exhibit highest price sensitivity; salon professionals accept premium positioning for guaranteed batch consistency.
Supply Chain Analysis
REACH authorization requirements function as de facto export controls, restricting synthetic preservative flows from non-compliant sub-suppliers into EU manufacturing networks. Germany, France, and Italy anchor European production, drawing from coconut-derived surfactants, certified natural extracts, and biodegradable polymer inputs. Single-source vulnerability concentrates in palm-alternative feedstocks where Southeast Asian supply disruptions propagate rapidly. Distribution runs through centralized hypermarket procurement for mass-market volumes, while salon networks maintain exclusive professional-only channels with stylist certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid shampoo bars and waterless concentrate formats constitute an accelerating substitution threat that liquid formulation incumbents must neutralize through performance parity investments and sustainability repositioning.
For Market Incumbents: Build formulation moats around proprietary amino acid surfactant complexes that match sulfate performance benchmarks. Secure captive supply agreements for COSMOS-certified organic surfactants before candidate list expansions restrict conventional alternatives. Channel control through exclusive salon distribution networks defends premium positioning against private-label encroachment. For New Entrants and Emerging Players: Pursue underpenetrated pharmacy channel expansion for microbiome-focused scalp treatments in Poland and Romania where dermatologist recommendation influence remains undeveloped. Target professional certification programs as the most penetrable entry vector, leveraging technical support hotlines to cement stylist relationships before scale competitors establish back-bar presence. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance timelines and CSRD disclosure obligations favor acquirers with established green chemistry programs over capital-constrained organic specialists. Acquisition targets should display captive ingredient sourcing or proprietary biodegradable surfactant IP. Monitor ECHA candidate list addition velocity as the critical inflection signal for forced reformulation cycles that trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | REACH compliance unlocks premium pricing tiers while excluding smaller competitors from market access. |
| Professional Channel Exclusivity Arrangements | United Kingdom salon networks sustain pricing power through licensed stylist certification requirements. |
| Captive Organic Surfactant Sourcing | Backward integration into coconut-derived feedstocks mitigates palm-alternative supply volatility risks. |
| Pharmacy Distribution Partnership | German pharmacist recommendation networks displace conventional retail for therapeutic scalp health variants. |
| CSRD-Aligned Sustainability Disclosure | Early compliance builds investor preference and retail buyer procurement criteria alignment. |
Research Methodology
A standing panel of formulation chemists, professional salon owners, pharmacy category managers, and retail procurement directors provided ongoing calibration against secondary validation from ECHA substance evaluations, EU Green Deal implementation documents, and customs trade data for surfactant feedstock flows. Primary interviews with manufacturing plant managers and organic certification auditors combined with bottom-up SKU-level modeling and top-down category spend analysis to triangulate market sizing.
Scenario-bracketing around REACH authorization timelines and CSRD disclosure phase-ins anchored projections across the analysis window. Segmentation dimensions encompassed formulation chemistry, distribution channel economics, end-user application intensity, and regional regulatory cluster alignment. CAGRs derived from elasticity-adjusted volume forecasts incorporating salon service bundling rates and online subscription adoption curves.
Macroeconomic conditions sit as an overlay; deviation in eurozone consumer discretionary spending or feedstock commodity indices would shift the trajectory. Forecasts reflect documented assumptions regarding ECHA candidate list expansion velocity and clean-label procurement mandate enforcement. Material shifts in synthetic preservative restriction scope or organic certification standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Beauty Salon Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Global Personal Care Emollients Market