
 China Mattress Market | 2026-2036
China Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
China Mattress Market Analysis
The premium-commodity split in China's mattress sector is shifting along material composition and brand positioning lines. MLILY leverages its memory foam R&D pipeline to command higher price tiers in first-tier cities. Jinlongheng Furniture anchors its position through manufacturing scale in Hebei province, supplying volume-driven offline retail channels. Xianghe Kaneman differentiates via hybrid constructions that blend latex and coil systems for the hospitality segment.
A mattress is a sleep support system comprising layered materials—typically polyurethane foam, steel coils, natural latex, or bonded combinations—engineered to distribute body weight and maintain spinal alignment across standardized dimensions. Production involves foam pouring, spring unit assembly, quilting, and tape-edging processes governed by density, indentation force deflection, and durability specifications. Memory foam and hybrid categories now capture the strongest margin pools as consumers trade up from basic innerspring units. The residential end user segment remains the volume foundation, while hospitality procurement accelerates fastest amid hotel chain renovation cycles.
SAMR enforces national mattress quality standards covering foam density thresholds and combustion resistance, directly elevating production costs for non-compliant manufacturers. China's GB standards framework, supplemented by provincial environmental regulations under MEE, restricts volatile organic compound emissions in adhesive and foam curing processes. Stakeholders must monitor regulatory tightening on chemical content and traceability requirements, as compliance investments will increasingly separate viable producers from marginal operators.
Market Dynamics
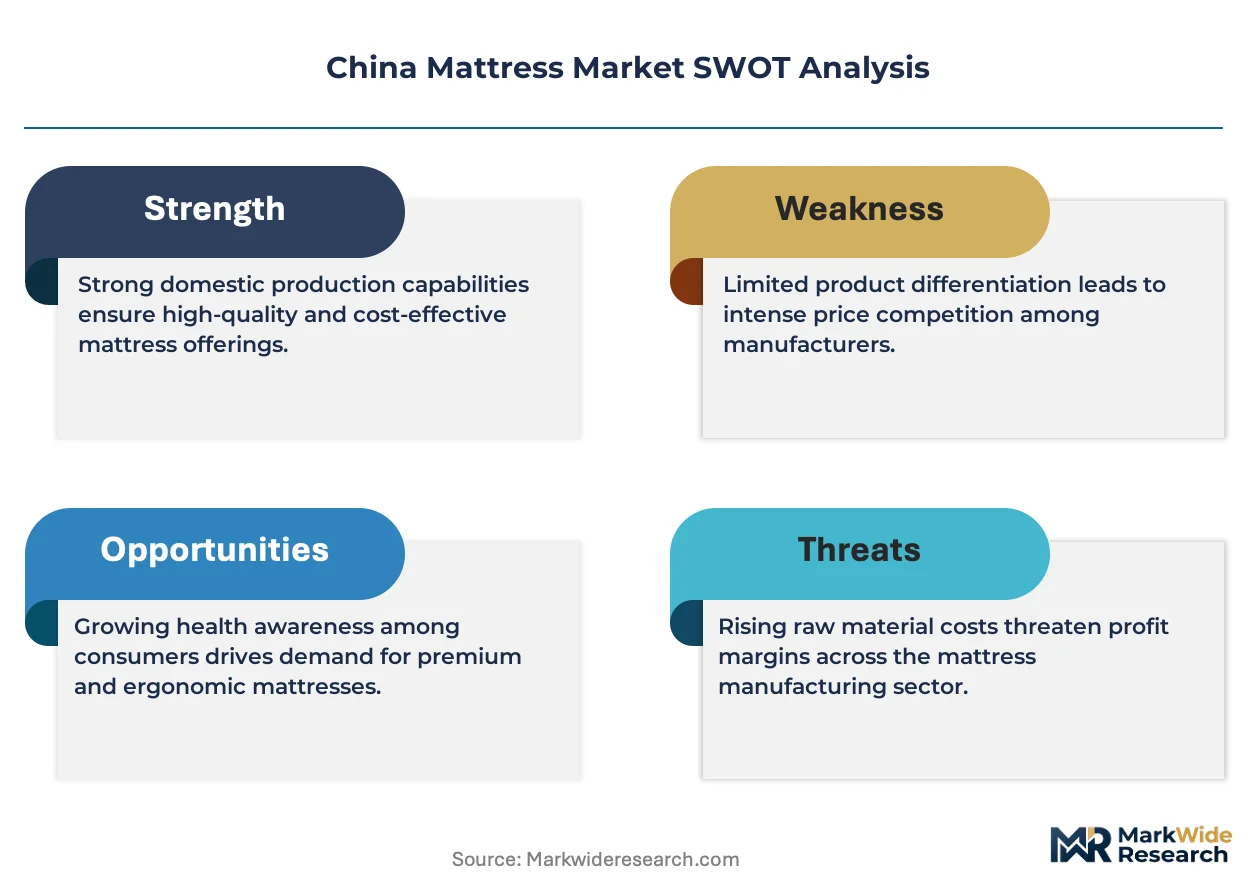
China's mattress sector faces a structural compression between SAMR's tightening GB standards on foam density and flammability and the manufacturing cost advantages concentrated in Hebei and Jiangsu provinces. This regulatory-cost geography tension is forcing facility upgrades while regional production clusters absorb compliance investments at unequal rates.
Growth Catalysts
- Hospitality renovation cycles:Hotel chains across Shanghai, Beijing, and Guangzhou are replacing sleep infrastructure at accelerated rates, pulling premium hybrid and memory foam units into procurement pipelines.
- GB standards elevation:SAMR's updated furniture quality framework mandates higher foam density thresholds and combustion resistance testing, eliminating marginal producers and clearing market share for compliant manufacturers.
- Yangtze River Delta concentration:Manufacturing clusters in Jiangsu and Zhejiang overlap with high-income urban consumption zones, reducing logistics friction and enabling rapid SKU rotation for tier-one city retailers.
Market Restraints
- TDI and polyol input volatility:Polyurethane foam feedstock prices fluctuate with crude oil derivatives and regional chemical plant operating rates, compressing margin predictability for mid-scale producers without captive chemical supply.
- Hebei supply concentration risk:Volume-oriented innerspring and basic foam production concentrates in a single province cluster, creating vulnerability to localized environmental enforcement actions or logistics disruptions.
- Latex substitution pressure:Natural rubber latex faces competition from synthetic alternatives and plant-based polyurethane formulations, limiting pricing power for pure latex positioning despite premium consumer perception.
Strategic Opportunities
- Western China penetration:Chengdu, Xi'an, and Chongqing exhibit underdeveloped branded mattress distribution relative to per-capita income growth, creating first-mover whitespace for organized retail expansion.
- MEE environmental compliance tailwind:Provincial volatile organic compound emission restrictions favor manufacturers with in-house adhesive and foam curing controls, rewarding early capital deployment with regulatory preference.
- Smart sleep convergence:Integration of pressure sensors and temperature-regulating phase-change materials with coil and foam cores is opening hospitality contract segments seeking differentiated guest experience metrics.
Industry Challenges
- Certification timeline compression:SAMR's GB testing protocols and provincial MEE environmental permits require extended lead times for new facility approvals, delaying capacity expansion for growing brands.
- Skilled quilting and tape-edging labor scarcity:Automated edge-finishing equipment reduces but does not eliminate manual finishing requirements, and trained operators concentrate in legacy manufacturing zones with wage inflation pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mattress Market |
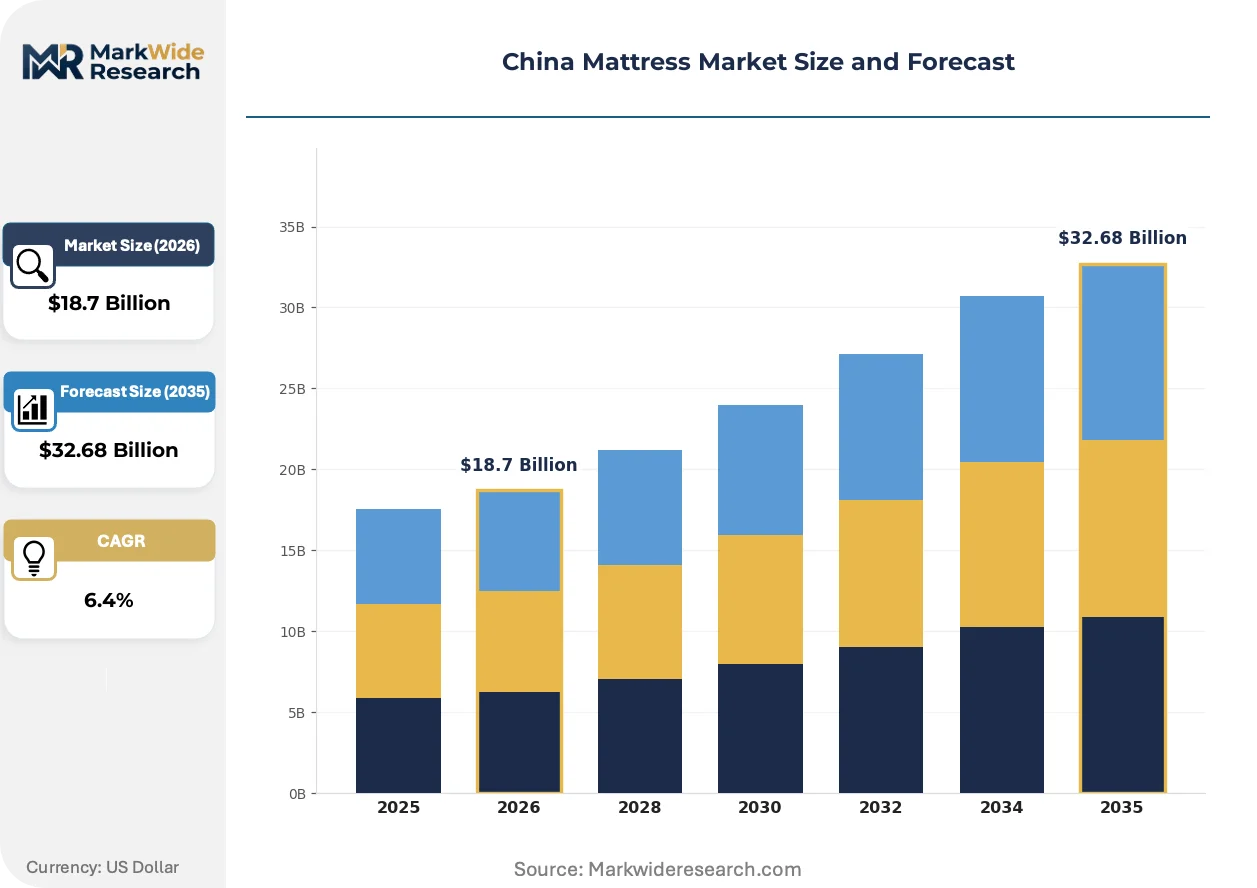
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Innerspring, Latex, Hybrid Distribution Channel: Online Retail, Offline Retail, Supermarkets, Specialty Stores End User: Residential, Hospitality, Healthcare, Institutional Size: Twin, Full, Queen, King |
| Companies Covered | JLH Mattress, CMattress, JBM EON, MLILY, Meng Ruo, AIDI, Xianghe Kaneman, Jinlongheng Furniture, Rayson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mattress Market Emerging Trajectories
Material science advances and regulatory enforcement are compressing traditional manufacturing methods while opening premium positioning through certified performance claims. Sleep technology convergence with wellness tracking is creating new category boundaries.
Phase-change material integration with open-cell memory foam is electrifying temperature regulation as a purchase determinant. Hospitality procurement teams in Shanghai and Shenzhen are specifying gel-infused and graphite-doped foam layers for climate-controlled properties. This thermal performance arms race is compressing basic polyurethane offerings into commoditized price tiers while elevating certified cooling constructions.
SAMR's GB 17927 furniture flammability standards are mandating barrier fabric and intumescent coating investments that smaller Jiangsu workshops cannot absorb. Testing laboratory capacity constraints are extending product launch timelines by four to six months for uncertified entrants. Tier-one city retailers are responding by consolidating supplier relationships toward vertically integrated manufacturers with in-house testing capabilities.
Direct-to-consumer mattress-in-a-box fulfillment is displacing traditional furniture hall distribution in tier-two and tier-three cities. Younger buyers in Hangzhou and Nanjing are purchasing compressed hybrid units through live-stream commerce channels with 100-night trial guarantees. This channel rotation is most visible in the 25-35 age demographic, where brand discovery occurs through short-video platforms rather than physical retail visits.
China Mattress Market Segmentation
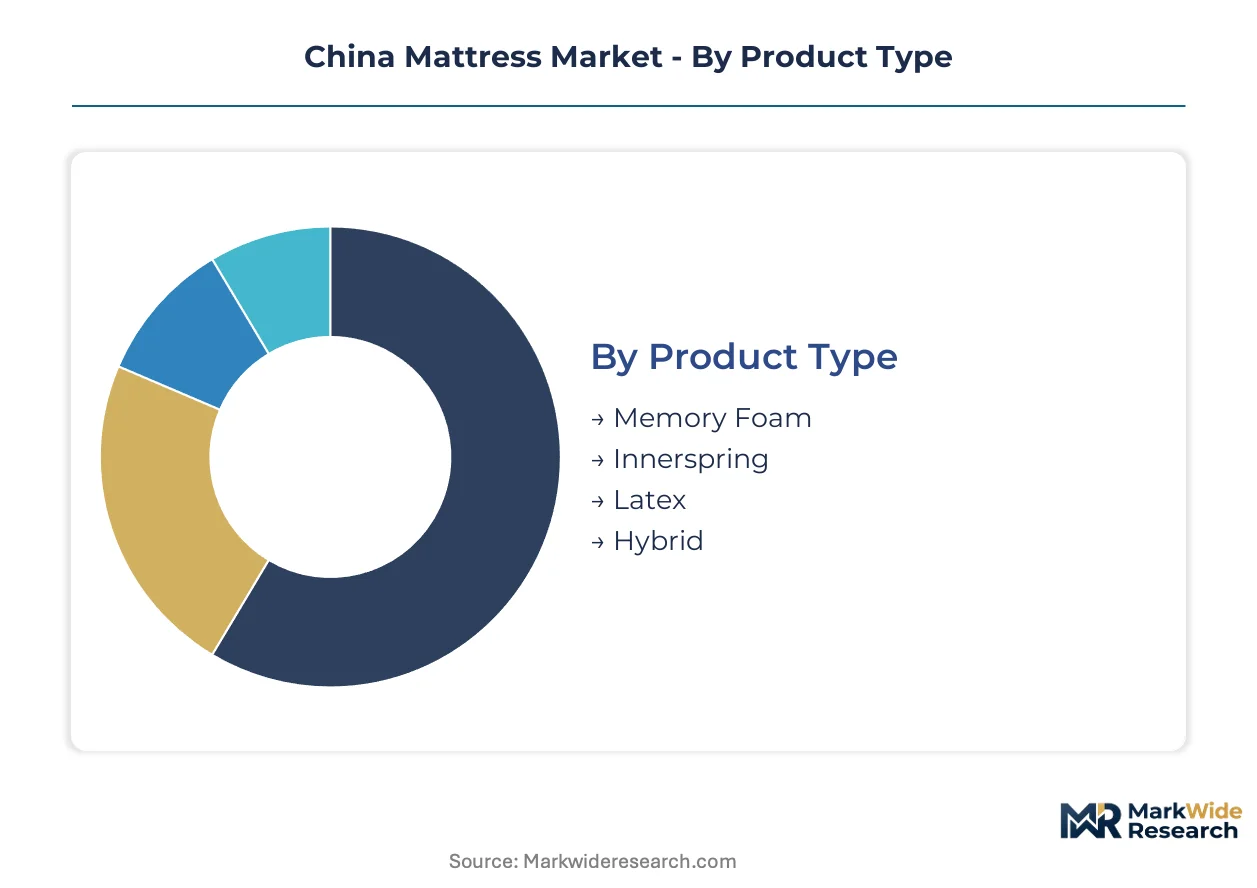
Mattress purchasing decisions in China diverge sharply across buyer types, with residential consumers prioritizing material comfort while hospitality procurement teams emphasize durability specifications and bulk logistics. Understanding these segment boundaries clarifies where pricing power concentrates and which channels warrant capital deployment.
Product Type:
Material composition determines margin structure and brand positioning latitude in first-tier cities.
- Memory Foam:Open-cell polyurethane formulations with viscoelastic recovery properties dominate premium urban retail. Shanghai and Beijing consumers specify gel-infused variants for temperature regulation, pulling margin pools away from basic constructions.
- Hybrid:Coil-and-foam layered systems capture hospitality renovation contracts requiring fire-resistant barrier fabrics under SAMR's GB 17927 standards. Hotel chains in Guangzhou specify these for guest room standardization programs.
- Innerspring:Bonnell and pocketed coil units anchor volume production in Hebei manufacturing clusters, supplying price-sensitive offline retail channels.
- Latex:Natural rubber and synthetic polyol formulations serve niche wellness-positioned consumers, though substitution pressure from plant-based polyurethanes limits pricing power.
Memory Foam leads on scale; Hybrid leads on momentum.
Distribution Channel:
Channel selection shapes customer acquisition cost and trial-period economics.
- Online Retail:Compressed mattress-in-a-box fulfillment through live-stream commerce platforms dominates Hangzhou and Nanjing among buyers aged 25-35. One hundred-night trial guarantees reduce purchase friction for hybrid and memory foam units.
- Specialty Stores:Branded experience centers in Chengdu and Xi'an enable pressure-mapping demonstrations and material education, supporting premium price realization.
- Offline Retail:Furniture hall distribution retains strength in tier-three cities where physical inspection remains a purchase prerequisite.
- Supermarkets:Basic innerspring and thin foam mattresses serve immediate-need replacement purchases with minimal decision cycles.
Online Retail climbs fastest; Specialty Stores defend margin position.
End User:
Application context dictates specification rigor and contract structure.
- Residential:Individual consumers drive volume through replacement cycles and household formation, with Yangtze River Delta cities showing strongest per-capita spending on certified cooling constructions.
- Hospitality:Hotel chains across Shanghai, Beijing, and Guangzhou are accelerating sleep infrastructure replacement, specifying hybrid units with durability warranties and bulk logistics integration.
- Healthcare:Pressure-relief mattresses for patient care facilities require antimicrobial surface treatments and fluid-resistant barriers under clinical procurement protocols.
- Institutional:Dormitory and military procurement emphasizes standardized dimensions and fire-safety certification at volume price points.
Residential anchors volume; Hospitality expands most quickly.
Size:
Dimension selection correlates with residential floor space constraints and hospitality room category tiers.
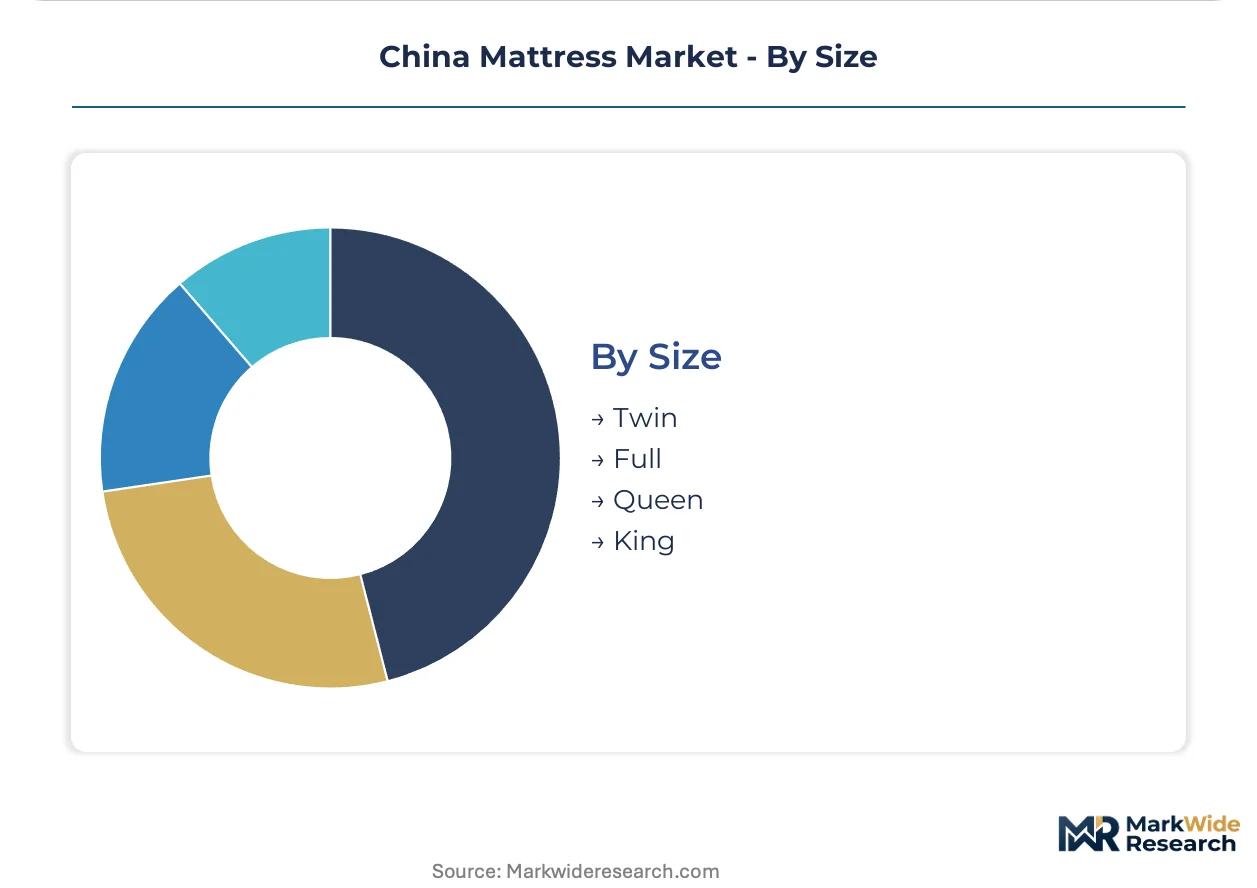
- Queen:The dominant residential specification for master bedrooms in urban apartments, balancing sleeping surface with space efficiency in tier-one and tier-two cities.
- King:Premium residential and upscale hospitality suites specify these dimensions, often paired with split-base adjustable foundations.
- Full:Secondary bedrooms and budget hospitality properties favor this format for space-constrained installations.
- Twin:Single-occupancy hospitality rooms, dormitories, and children's bedrooms drive concentrated but lower-margin demand.
Queen leads on scale; King gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled quilting and tape-edging labor pools concentrate in legacy manufacturing zones across China's eastern seaboard, anchoring production capacity while wage inflation pressures reshape facility location decisions.
Yangtze River Delta
Shanghai and Hangzhou consumers drive premium memory foam demand through live-stream commerce channels with trial guarantees. SAMR's GB standards enforcement elevates compliance costs for Jiangsu workshops lacking in-house testing capabilities. Manufacturing clusters in Suzhou and Ningbo absorb these investments while supplying rapid SKU rotation to tier-one city retailers.
Pearl River Delta
Guangzhou hotel chains accelerate hybrid mattress procurement for renovation cycles, specifying fire-resistant barrier fabrics under GB 17927 standards. MEE provincial regulations restrict volatile organic compound emissions in adhesive processes across Guangdong facilities. Shenzhen's compressed mattress-in-a-box fulfillment networks serve the 25-35 demographic through short-video platform discovery.
Beijing-Tianjin-Hebei
Volume-oriented innerspring production anchors in Hebei province, supplying price-sensitive offline furniture hall channels throughout northern China. SAMR's updated furniture quality framework eliminates marginal producers unable to meet foam density thresholds. Xianghe county maintains concentration risk as environmental enforcement actions periodically disrupt logistics flows.
Sichuan-Chongqing
Chengdu and Chongqing exhibit underdeveloped branded mattress distribution relative to per-capita income growth, creating whitespace for organized retail expansion. MEE environmental compliance investments favor manufacturers with captive adhesive and foam curing controls. Local procurement teams in Xi'an increasingly specify certified cooling constructions for hospitality properties.
Shandong Peninsula
Qingdao and Jinan manufacturing bases serve replacement demand in secondary bedroom and dormitory segments with standardized dimensions. SAMR certification timelines compress new facility approvals, delaying capacity expansion for regional brands. Yantai port logistics enable latex feedstock imports for hybrid construction specialists targeting wellness-positioned consumers.
China Mattress Market Vendor Landscape
Top-tier vendors anchor premium memory foam and hybrid categories, while mid-scale fabricators compete on manufacturing scale and regional distribution reach. The vendor base stratifies across three tiers: R&D-driven specialists commanding first-tier city price premiums, volume producers supplying offline retail channels, and emerging entrants leveraging direct-to-consumer fulfillment. Strategic archetypes include material science innovators, manufacturing scale operators, and digital-native challengers. Dominant competitive moves encompass M&A consolidation for testing laboratory capabilities and backward integration into foam pouring operations.
Among Jiangsu and Zhejiang-based specialists, MLILY exemplifies the R&D-driven archetype through memory foam pipeline development. Jinlongheng Furniture occupies a position within the manufacturing scale tier, anchoring volume production in Hebei province. Xianghe Kaneman represents hybrid construction specialists blending latex and coil systems for hospitality procurement teams. These three entities illustrate how compliance investments and material differentiation separate viable producers from marginal operators under tightening SAMR standards.
| Leading Market Players |
|---|
| JLH Mattress |
| CMattress |
| JBM EON |
| MLILY |
| Meng Ruo |
| AIDI |
| Xianghe Kaneman |
| Jinlongheng Furniture |
| Rayson |
| Others |
Supply Flow & Price Mechanics
Hotel chain procurement teams specifying GB 17927-compliant fire-resistant barrier fabrics are forcing supply-side consolidation toward vertically integrated manufacturers with in-house testing capabilities, compressing margins for uncertified Jiangsu workshops while elevating pricing power for compliant producers.
Pricing Analysis
The bundled service split between trial-period guarantees and bare-unit transactions now separates digital-native challengers from legacy furniture hall operators. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and after-sales service depth, with SAMR compliance investments driving price differentiation between certified cooling constructions and basic polyurethane offerings. Cost compression in the mid-scale tier is intensifying because TDI and polyol input volatility erodes margin predictability. Residential consumers in tier-three cities exhibit highest price sensitivity, while hospitality procurement teams prioritize durability warranties over unit cost.
Supply Chain Analysis
Returns flows from 100-night trial guarantees are creating reverse-logistics infrastructure demands that compressed mattress-in-a-box specialists must absorb. Manufacturing gravity centers on Hebei province for volume innerspring production and Jiangsu-Zhejiang clusters for memory foam and hybrid units, with feedstock supply drawing from domestic polyol producers and imported natural rubber through Yantai port. Single-source vulnerability concentrates in Hebei's Xianghe county, where environmental enforcement actions periodically disrupt logistics flows. Distribution runs through live-stream commerce platforms for tier-one and tier-two city penetration, while offline furniture halls retain northern China reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SAMR's GB standards elevation on foam density and flammability is accelerating demand consolidation toward compliant manufacturers with captive testing capabilities.
For Market Incumbents: Hedge against Hebei supply concentration risk by diversifying foam pouring capacity across Jiangsu and Zhejiang manufacturing clusters. Deepen backward integration into polyol blending operations to buffer TDI feedstock volatility. Prioritize M&A targeting testing laboratory capabilities to compress SAMR certification timelines and lock in tier-one city retailer relationships before smaller competitors absorb compliance investments. For New Entrants and Emerging Players: The mid-market price-point gap between MLILY's premium memory foam positioning and Hebei's volume innerspring tier creates whitespace for hybrid specialists with certified cooling constructions. Target Chengdu and Chongqing for organized retail expansion where branded distribution lags per-capita income growth. Deploy direct-to-consumer mattress-in-a-box fulfillment with live-stream commerce integration to bypass incumbent furniture hall gatekeepers. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-scale manufacturers possessing in-house adhesive and foam curing controls that satisfy MEE environmental compliance ahead of provincial enforcement tightening. Long-term viability over the projection horizon favors targets with SAMR-certified testing capabilities and Yangtze River Delta manufacturing footprints. Monitor SAMR facility approval timelines as the inflection indicator—compressed certification windows signal regulatory acceleration that will strand uncertified capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Pouring | Captive polyol supply buffers TDI volatility and secures SAMR density compliance. |
| Testing Laboratory Acquisition | In-house GB 17927 certification compresses product launch timelines by four to six months. |
| Live-Stream Commerce Channel Launch | Short-video platform discovery captures 25-35 demographic trial-guarantee purchases. |
| Western China Retail Expansion | Chengdu and Xi'an whitespace offers first-mover positioning ahead of income-consumption convergence. |
| Smart Sleep Technology Integration | Pressure sensor and phase-change material convergence opens hospitality contract differentiation. |
Methodological Framework
Direct dialogue with mattress manufacturing executives, hospitality procurement managers at Shanghai and Guangzhou hotel chains, furniture hall operators in Hebei province, and SAMR compliance consultants grounded qualitative insights. Secondary validation drew from GB standards documentation, MEE provincial environmental filings, customs trade data on polyol and natural rubber imports, and SEC disclosures from listed furniture manufacturers. Bottom-up demand modeling across residential replacement cycles and hospitality renovation pipelines was triangulated against top-down sector value estimates.
Top-down sector sizing was cross-checked against bottom-up facility capacity assessments across Jiangsu, Zhejiang, and Hebei manufacturing clusters. Segmentation dimensions modeled include material composition, distribution channel, end-user application, and regional consumption cluster. CAGRs were derived from elasticity-adjusted demand projections and input cost trajectory assumptions. Forecast inputs incorporated SAMR regulatory timeline scenarios and MEE enforcement intensity variations across provincial jurisdictions.
Caveats apply where SAMR certification timeline compression or MEE environmental enforcement acceleration could materially shift the outlook for facility expansion viability. Practitioners should monitor TDI and polyol feedstock price volatility, Hebei logistics disruption frequency, and live-stream commerce platform policy changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
US Adjustable Bed Bases Market
Bedroom Furniture
UK Adjustable Bed Bases Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Baby Cribs and Cots Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
Latex Pillow Market
Bedroom Furniture
Luxury Mattress Market
Bedroom Furniture
North America Mattress Market
Bedroom Furniture
Australia Mattress Market
Bedroom Furniture
Heated Bedding Market
Bedroom Furniture
Wall Bed Market
Bedroom Furniture
Saudi Arabia Mattress Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
Latin America Mattress Market