
 Australia Vegan Cosmetics Market | 2026-2036
Australia Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Vegan Cosmetics Market Insights
Direct-to-consumer subscription financing and asset-light e-commerce leasing is reconfiguring capital barriers for emerging vegan beauty entrants in Australia. Nude by Nature leverages its botanical ingredient sourcing to sustain premium positioning across domestic pharmacy channels. INIKA Organic anchors its competitiveness through certified organic supply chains, while Go-To Skincare differentiates via simplified, single-origin product architectures that reduce formulation complexity.
Australia vegan cosmetics encompass beauty and personal care formulations that exclude all animal-derived ingredients and animal testing, verified through third-party certification programs such as Vegan Australia or Choose Cruelty Free accreditation. These products typically substitute beeswax, lanolin, and carmine with plant-based emollients, synthetic peptides, or mineral pigments to maintain equivalent functional performance in color payoff, moisturization, and shelf stability. Skincare commands the largest revenue pool within the product type dimension, reflecting sustained consumer investment in multi-step routines, while botanical ingredient sourcing captures margin concentration as certified supply chains tighten availability. The distribution channel structure privileges online platforms for customer acquisition, though specialty retailers retain higher conversion rates for fragrance and color cosmetics.
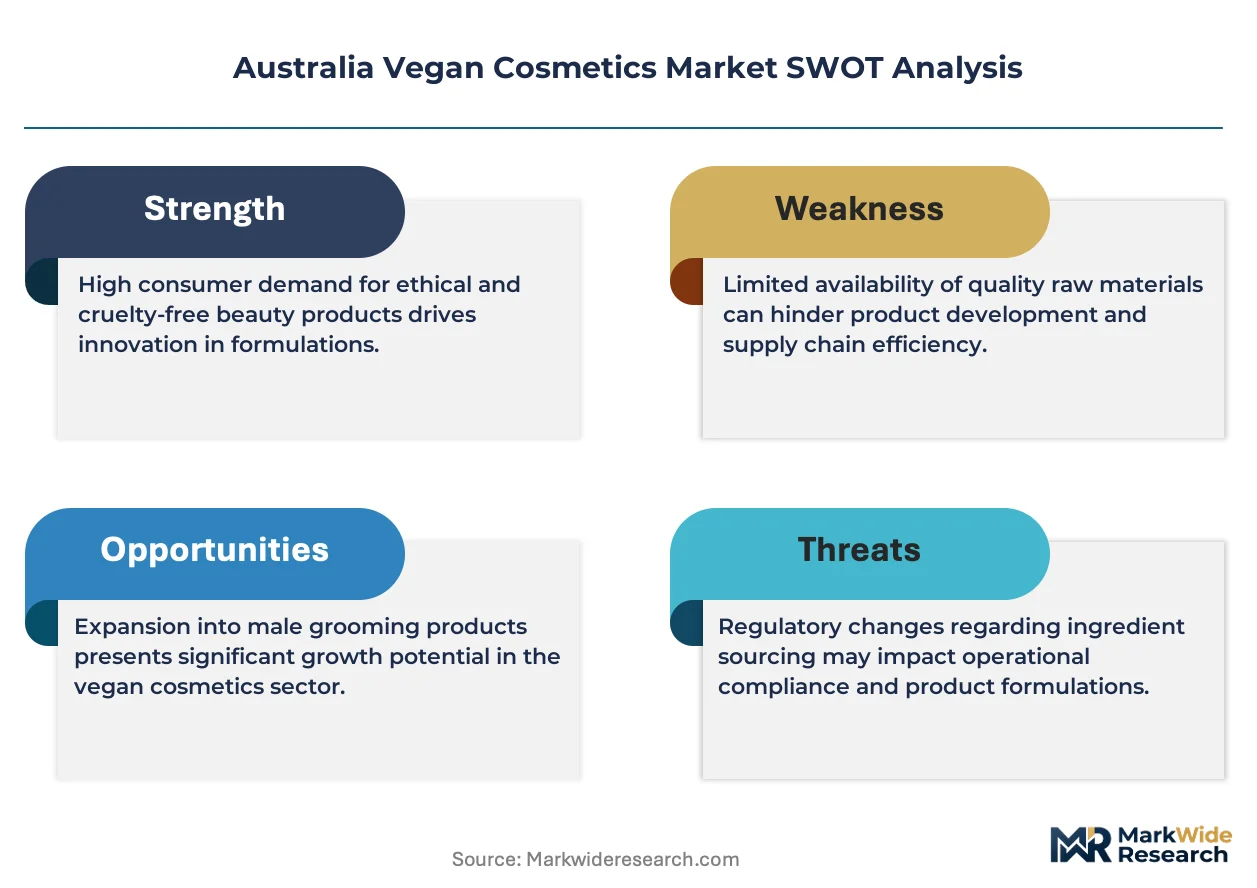
TGA ingredient safety assessments and the ACCC's consumer protection mandates jointly elevate compliance costs for new market entrants, effectively filtering out uncertified competitors. The EU-inspired ban on animal testing for cosmetics sold in Australia, enforced through the Industrial Chemicals Act, redirects R&D investment toward in-vitro and computational toxicology methods. Stakeholders must monitor evolving certification fragmentation between domestic Vegan Australia standards and international Leaping Bunny requirements as export channels expand.
Market Dynamics
TGA's Industrial Chemicals Act enforcement and Vegan Australia's certification fragmentation are compressing formulation timelines while elevating compliance spend for domestic brands seeking pharmacy shelf placement.
Growth Catalysts
- Industrial Chemicals Act:Australia's ban on animal testing redirects R&D investment toward in-vitro toxicology methods, accelerating plant-derived peptide development for domestic formulators.
- Social commerce penetration:Sydney and Melbourne-based Millennial and Gen Z cohorts convert Instagram discovery into repeat subscription purchases through integrated checkout features.
- Botanical supply chain maturation:Certified organic ingredient networks across Queensland and Tasmania reduce lead times for native extract sourcing.
Market Restraints
- Certified organic input scarcity:Tightened global availability of COSMOS-grade plant oils inflates raw material costs for premium skincare lines.
- Single-origin dependency:Kakadu plum and Davidson plum harvesting concentrates in Northern Territory indigenous supply partnerships, creating weather-linked volume risk.
- ACCC compliance burden:Mandatory substantiation of "cruelty-free" and "vegan" claims elevates legal review costs for emerging direct-to-consumer entrants.
Strategic Opportunities
- Western Australia underpenetration:Perth's specialty retail density lags Sydney and Melbourne, presenting first-mover advantage for dedicated vegan beauty storefronts.
- Biotechnology convergence:Precision fermentation-derived squalane and collagen alternatives enable performance parity with animal-derived benchmarks at scale.
- Pharmacy channel expansion:Priceline and Chemist Warehouse shelf resets favor certified vegan SKUs, rewarding brands with Vegan Australia accreditation.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in plant-based emulsion stability and natural preservation systems commands premium compensation in Sydney's talent market.
- Dual certification complexity:Simultaneous Vegan Australia and Choose Cruelty Free accreditation requires redundant documentation and extended timeline-to-shelf.
- Legacy ERP integration:Batch-level traceability for certified supply chains demands software upgrades incompatible with smaller brands' existing inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Vegan Cosmetics Market |
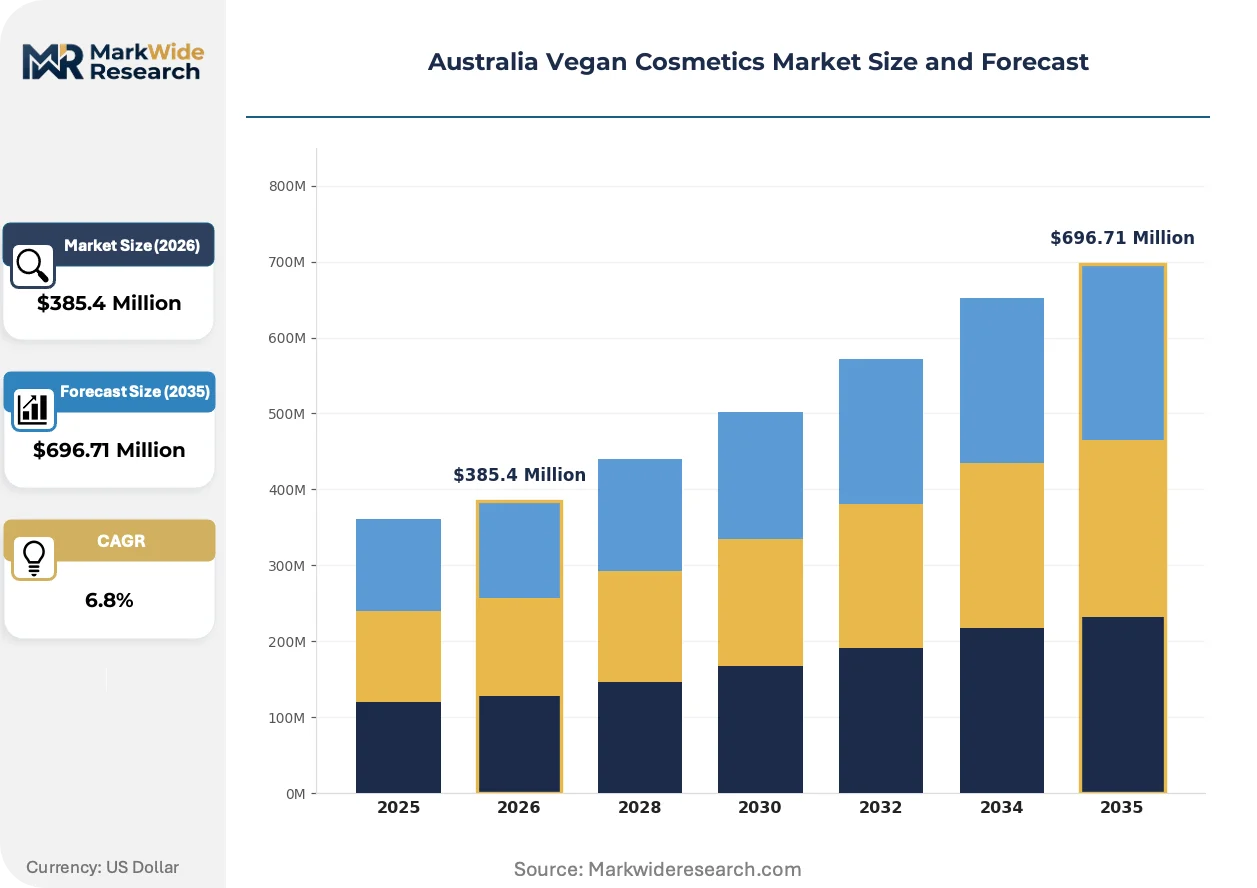
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Ingredient Source: Natural, Organic, Synthetic, Botanicals Customer Type: Health-Conscious, Eco-Friendly, Cruelty-Free, Fashion-Forward Distribution Channel: Online, Beauty Stores, Department Stores, Specialty Retailers |
| Companies Covered | Nude by Nature, Aesop, INIKA Organic, Go-To Skincare, Jurlique, Ere Perez, Eye of Horus, KVD Beauty, RAWW Cosmetics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived functional ingredients and regulatory harmonization pressures are compressing traditional formulation paradigms while elevating transparency requirements across Australian vegan cosmetics.
Precision fermentation for squalane and collagen peptide production is collapsing the performance gap between plant-derived and animal-derived moisturization actives. Mid-tier skincare brands in Brisbane and Adelaide accelerate adoption as unit economics approach petroleum-based alternatives. This biotechnology shift enables simplified INCI lists that reduce consumer education burden at point-of-sale.
TGA's alignment with EU REACH substance restrictions tightens permissible preservative and UV filter inventories for cosmetics sold in Australia. Domestic formulators reformulate sun care and color cosmetic lines to exclude newly restricted chemical classes ahead of enforcement deadlines. Skincare segments with shorter development cycles adapt faster than fragrance and makeup categories locked into longer stability testing protocols.
Subscription-based replenishment models displace traditional retail discovery for core skincare routines among time-constrained professionals in Sydney's eastern suburbs. Direct-to-consumer brands capture recurring revenue through personalized regimen algorithms while pharmacy retailers lose traffic for basic cleanser and moisturizer replenishment. This channel rotation concentrates customer lifetime value with digitally native entrants possessing superior first-party data infrastructure.
Australia Vegan Cosmetics Market Segmentation
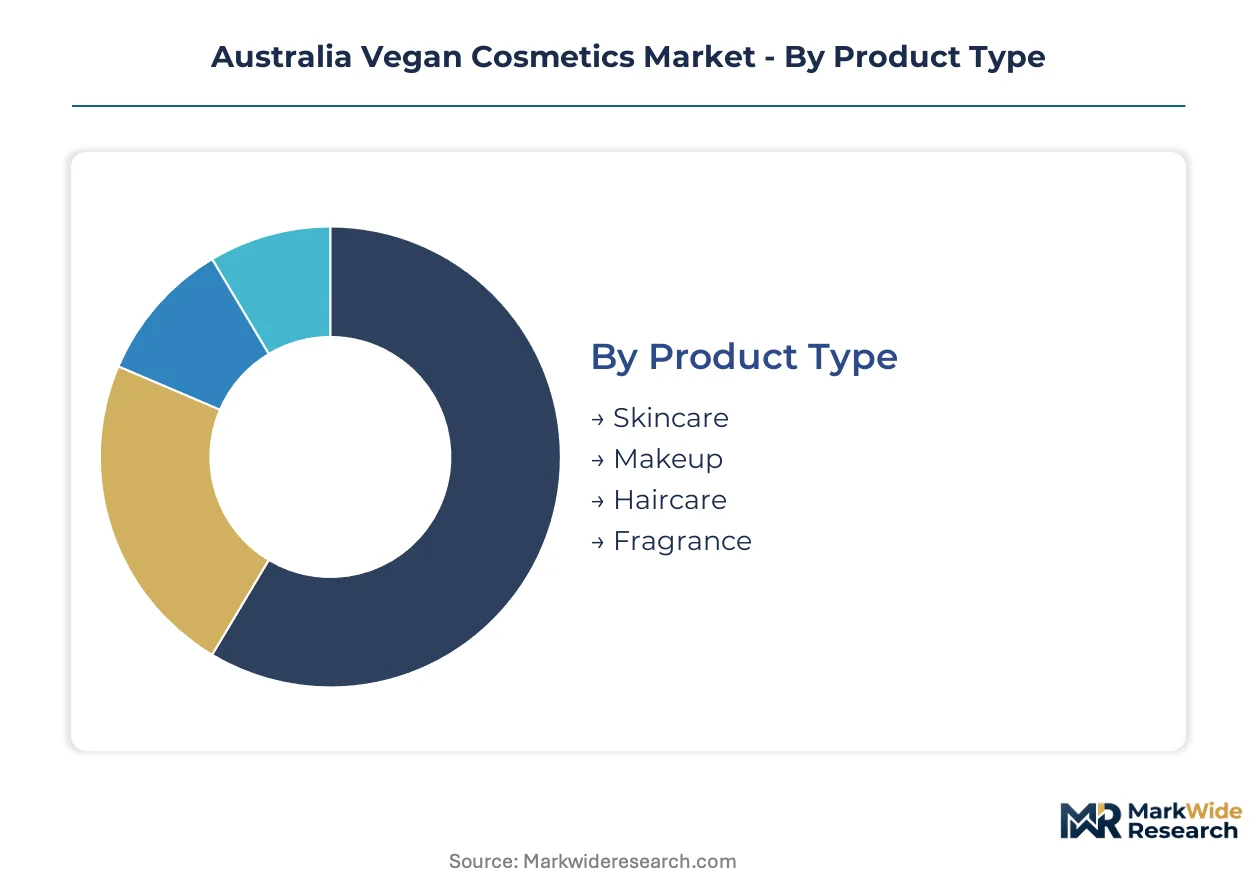
Australia's vegan cosmetics landscape fragments across four distinct dimensions, each revealing divergent margin structures and regulatory exposure. Product type and distribution channel decisions concentrate capital deployment, while ingredient sourcing and customer psychographics determine brand positioning against TGA compliance frameworks.
Product Type:
Mature skincare formulations anchor revenue stability, while emerging biotechnology applications in color cosmetics reshape performance benchmarks.
- Skincare:Multi-step routines encompassing serums, moisturizers, and sun protection dominate pharmacy shelf resets. Sydney and Melbourne professionals drive replenishment cycles through subscription models, with TGA's preservative restrictions accelerating natural emulsion reformulation.
- Makeup:Color payoff parity with conventional cosmetics remains the critical technical hurdle. Mineral pigment sourcing from Queensland clay deposits supports domestic formulators seeking Vegan Australia certification for foundation and lip product lines.
- Haircare:Plant-derived surfactants replace sulfates in shampoo formulations, though conditioning performance gaps persist for curly hair segments.
- Fragrance:Synthetic musk alternatives and botanical extraction methods command premium positioning, with shorter development cycles than skincare.
Skincare retains volume leadership; makeup holds the steepest expansion curve as biotechnology-derived pigments close performance gaps.
Ingredient Source:
Cost tier stratification separates mass-market synthetics from certified organic premiums, with botanical networks commanding supply chain investment.
- Natural:Unprocessed plant oils and waxes serve as entry-level vegan substitutes, though stability limitations restrict formulation flexibility.
- Organic:COSMOS-certified supply chains across Tasmania and Queensland tighten availability, inflating raw material costs for premium skincare lines while satisfying ACCC substantiation requirements.
- Synthetic:Laboratory-derived peptides and fermentation-based actives deliver performance parity at scale. Brisbane manufacturers accelerate adoption as precision squalane unit economics approach petroleum alternatives.
- Botanicals:Native Australian extracts including Kakadu plum concentrate in Northern Territory indigenous partnerships, creating weather-linked volume concentration.
Botanicals capture margin concentration; synthetic alternatives are climbing the fastest as biotechnology scales reduce cost premiums.
Customer Type:
Geography clusters distinct psychographic profiles, with urban density driving adoption velocity and certification literacy.
- Health-Conscious:Ingredient transparency demands extend to preservative systems and UV filter selections, aligning with TGA's REACH-aligned substance restrictions.
- Eco-Friendly:Packaging sustainability and carbon footprint verification supplement vegan claims, particularly among Melbourne's inner-north consumer base.
- Cruelty-Free:Dual certification seekers navigate Vegan Australia and Choose Cruelty Free documentation redundancy, elevating compliance costs for direct-to-consumer entrants.
- Fashion-Forward:Social commerce discovery through Instagram and TikTok converts to repeat purchase, concentrated in Sydney's eastern suburbs.
Health-Conscious segments dominate pharmacy channel volume; Fashion-Forward cohorts gain share fastest through digital-native brand acquisition.
Distribution Channel:
Customer acquisition cost divergence separates high-touch specialty retail from scalable online infrastructure, with pharmacy resets rewarding certification compliance.
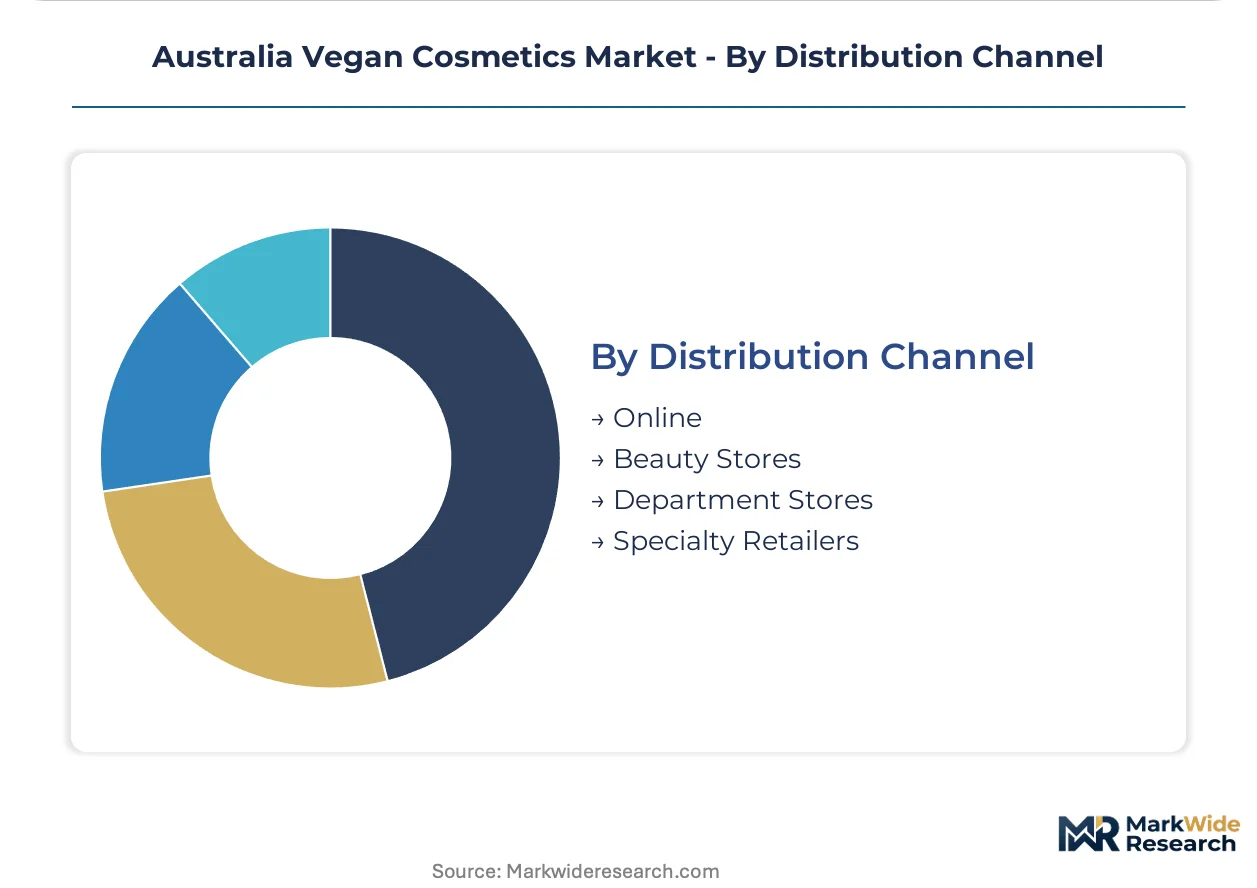
- Online:Subscription algorithms capture recurring revenue from time-constrained professionals, displacing traditional retail discovery for core skincare routines. First-party data infrastructure determines customer lifetime value concentration.
- Beauty Stores:Conversion rates for color cosmetics and fragrance exceed online benchmarks, though rent burdens in Sydney and Melbourne compress margins.
- Department Stores:Premium positioning opportunities persist for certified organic lines, with declining foot traffic shifting focus to experiential sampling.
- Specialty Retailers:Priceline and Chemist Warehouse shelf resets explicitly favor Vegan Australia-accredited SKUs, creating pharmacy channel expansion incentives.
Online channels retain volume leadership; specialty retailers hold the steepest expansion curve as pharmacy accreditation requirements filter competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's vegan cosmetics sector runs a modest trade surplus in botanical extracts while importing precision fermentation actives from North American and European suppliers. Export momentum concentrates in certified organic skincare bound for Southeast Asian markets. Domestic consumption clusters along the eastern seaboard, with state-level regulatory harmonization under TGA frameworks enabling interstate distribution efficiency.
New South Wales
Sydney's eastern suburbs concentrate the highest per-capita spending on subscription-based vegan skincare replenishment. TGA's Industrial Chemicals Act enforcement elevates compliance costs for direct-to-consumer entrants operating from Surry Hills and Alexandria warehouse districts. The Northern Rivers region anchors macadamia oil and tea tree extract supply partnerships that feed into COSMOS-certified formulations.
Victoria
Melbourne's inner-north consumer base drives dual certification demand spanning Vegan Australia and Choose Cruelty Free accreditation. The state's Manufacturing Excellence program provides grant support for biotechnology fermentation facilities targeting collagen alternatives. Port Melbourne logistics hubs facilitate refrigerated ingredient imports from Tasmanian botanical networks.
Queensland
Brisbane manufacturers accelerate adoption of precision squalane as unit economics approach petroleum-based benchmarks. The state's native extract harvesting concentrates in Far North Queensland indigenous partnerships for Kakadu plum sourcing. Gold Coast specialty retailers underperform Sydney and Melbourne conversion rates, creating whitespace for dedicated vegan beauty storefronts.
Western Australia
Perth's specialty retail density lags eastern state benchmarks, presenting first-mover positioning for pharmacy channel expansion. The state's Therapeutic Goods Administration regional office streamlines ingredient notification processes for domestic formulators. Margaret River wine region byproduct streams supply grape seed extract for antioxidant skincare lines.
South Australia
Adelaide's biotechnology convergence centers on fermentation-derived functional ingredients for mid-tier skincare brands. The state's Advanced Manufacturing Growth Fund targets cosmetic ingredient processing infrastructure. Barossa Valley botanical networks provide certified organic rosehip oil for premium facial serum formulations.
Australia Vegan Cosmetics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and certification services. The market structure fragments across digitally native direct-to-consumer entrants, established pharmacy channel incumbents, and biotechnology-enabled ingredient suppliers. Three archetypes dominate: subscription-model skincare platforms, certified organic legacy brands, and precision fermentation technology providers. Competitive moves concentrate on pharmacy shelf reset capture and dual certification acquisition to filter uncertified rivals.
Within the certified organic tier, Nude by Nature and INIKA Organic exemplify botanical ingredient sourcing strategies that sustain premium positioning across domestic pharmacy channels. Go-To Skincare occupies a position within the simplified formulation archetype, reducing product architecture complexity to accelerate development cycles. These three Australian-registered entities collectively represent the intersection of TGA compliance infrastructure and Vegan Australia accreditation pathways that emerging entrants must replicate to secure Priceline and Chemist Warehouse distribution.
| Leading Market Players |
|---|
| Nude by Nature |
| Aesop |
| INIKA Organic |
| Go-To Skincare |
| Jurlique |
| Ere Perez |
| Eye of Horus |
| KVD Beauty |
| RAWW Cosmetics |
| Others |
Pricing and Supply Chain Analysis
The Port Melbourne to Sydney refrigerated freight corridor compresses margin structures for Tasmanian botanical suppliers while amplifying price differentiation between COSMOS-certified organic tiers and synthetic alternatives. Cost dynamics along this logistics spine concentrate pricing power with certified ingredient holders and force downstream brands toward subscription models that stabilize working capital.
Pricing Analysis
Pharmacy chain buyers anchor three-tier pricing stratification across premium, standard, and economy levels. Certification grade and volume scale differentiate tiers, with Vegan Australia accreditation commanding shelf placement premiums. Cost compression in the standard tier intensifies as synthetic squalane alternatives approach petroleum-based benchmarks. Emerging direct-to-consumer entrants exhibit highest price sensitivity; established pharmacy incumbents demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Queensland indigenous harvester partnerships strain working capital for Northern Territory Kakadu plum processors. Australia, North America, and Europe concentrate precision fermentation capacity for collagen alternatives. Raw material dependencies center on COSMOS-grade plant oils, mineral pigments from Queensland clay deposits, and biotechnology-derived actives. Single-source vulnerability in native extract harvesting concentrates weather-linked volume risk. Distribution runs through pharmacy channel resets at Priceline and Chemist Warehouse alongside direct-to-consumer subscription infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise sits as the binding constraint across Australia's vegan cosmetics sector, with plant-based emulsion stability and natural preservation systems commanding premium compensation that filters uncapitalized entrants.
For Market Incumbents: Harden TGA compliance infrastructure through redundant documentation systems that accelerate dual certification timelines. Deepen upstream control over Tasmanian and Queensland botanical networks to secure COSMOS-grade input priority. Biotechnology-enabled entrants threaten premium positioning; counter through pharmacy shelf reset capture at Chemist Warehouse. For New Entrants and Emerging Players: Perth specialty retail whitespace represents the most penetrable entry point for dedicated vegan beauty storefronts. Mid-tier synthetic ingredient tiers in Brisbane and Adelaide offer formulation cost advantages absent in Sydney and Melbourne. Accelerate Vegan Australia accreditation to unlock Priceline distribution before incumbent shelf consolidation completes. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational cosmetic parent companies divesting non-core Australian botanical brands. Long-term viability hinges on biotechnology convergence capacity and first-party data infrastructure for subscription retention. Watch precision fermentation unit economics as the inflection signal for synthetic ingredient cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Acquisition | Vegan Australia and Choose Cruelty Free accreditation unlocks pharmacy shelf resets at Priceline. |
| Botanical Supply Chain Integration | Indigenous partnerships in Northern Territory secure Kakadu plum volume against weather volatility. |
| Precision Fermentation Adoption | Brisbane manufacturers leverage biotechnology squalane to close cost gaps with petroleum alternatives. |
| Direct-to-Consumer Subscription Launch | Sydney eastern suburbs professionals convert to recurring revenue through personalized regimen algorithms. |
| Western Australia Retail Expansion | Perth storefront density lags eastern states, creating first-mover positioning for dedicated vegan beauty. |
Research Methodology
A spread of perspectives from brand managers at pharmacy retailers, category buyers at specialty stores, formulation chemists in Sydney's talent market, and supply planners at botanical extract processors converged on the working assumptions. Primary fieldwork combined with secondary validation against TGA regulatory filings, Vegan Australia certification databases, customs import records for fermentation actives, and Nielsen retail audit data. Bottom-up SKU-level modeling and top-down market sizing triangulated volume estimates.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions encompassed product type, ingredient source, customer psychographic, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement timelines and biotechnology adoption curves. Forecast inputs incorporated TGA Industrial Chemicals Act implementation schedules and precision fermentation capacity buildouts.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and logistics cost indices would shift the trajectory. Forecasts reflect documented assumptions about certification adoption rates and pharmacy channel reset timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Italy Vegan Cosmetics Market
Vegan Cosmetics
Asia-Pacific Vegan Cosmetics Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
Spain Vegan Cosmetics Market
Vegan Cosmetics
Canada Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
South Korea Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Vegan Beauty Products Market