
 Asia-Pacific Vegan Cosmetics Market | 2026-2036
Asia-Pacific Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vegan Cosmetics Market Insights
Clean-label certification is unwinding conventional formulation norms across the Asia-Pacific vegan cosmetics landscape. L'Oréal S.A. leverages its R&D footprint in Shanghai to localize plant-based actives for humid climates. Amway Corporation anchors its direct-selling network across Southeast Asian tier-two cities. Pacifica Beauty LLC differentiates through fragrance-free vegan lines targeting sensitive-skin segments in Japan and Australia.
Vegan cosmetics exclude animal-derived ingredients and animal testing, relying instead on plant-based emollients, synthetic peptides, and mineral pigments with specified purity thresholds above ninety-eight percent; these formulations serve consumers seeking ethical alignment without performance compromise. Skincare dominates value contribution due to higher per-unit pricing and repeat purchase frequency among millennials. Online Retail captures the fastest volume expansion, fueled by live-streaming commerce integrations on platforms dominant in China and South Korea. Plant-based ingredient sourcing commands premium positioning, though synthetic alternatives gain traction where supply consistency matters.
SAMR in China enforces cosmetic registration rules that mandate ingredient disclosure and prohibit animal-tested imports, while India's BIS standards push domestic manufacturers toward vegan labeling compliance. Australia's TGA oversees therapeutic claims on cosmeceuticals, creating a dual-track regulatory environment. Stakeholders must monitor evolving cross-border e-commerce duty structures and harmonization gaps between national cosmetic safety frameworks.
Market Dynamics
Live-streaming commerce integration is compressing purchase cycles across the Asia-Pacific vegan cosmetics landscape, forcing incumbent brands to rebuild their distribution architectures around real-time engagement platforms rather than traditional retail hierarchies.
Growth Catalysts
- China's SAMR cosmetic registration mandate:The prohibition of animal-tested imports and mandatory ingredient disclosure accelerates domestic vegan formulation adoption among Chinese manufacturers seeking compliance pathways.
- Plant-based emollient biotechnology:Advanced fermentation processes for squalane and ceramide analogues eliminate performance gaps with animal-derived equivalents, removing formulation barriers for premium skincare lines.
- South Korean social commerce density:Young consumers in Seoul and Busan drive category normalization through platform-native discovery, collapsing traditional awareness-to-trial timelines.
Market Restraints
- Organic shea and coconut oil price volatility:Climate-induced harvest variability across Southeast Asian sourcing corridors compresses margin structures for mid-tier vegan brands dependent on natural emollients.
- Single-source peptide synthesis concentration:Contract manufacturers in eastern China control over seventy percent of synthetic active production, creating supply vulnerability for brands without captive fermentation capacity.
- India's BIS certification timeline friction:Extended vegan-label verification procedures delay product launches by eight to fourteen months versus conventional cosmetic registration.
Strategic Opportunities
- Indonesia's underpenetrated tier-two cities:Surabaya, Bandung, and Medan present whitespace for direct-selling networks and localized halal-vegan positioning ahead of mass-market saturation.
- Biotech-mineral hybrid pigment convergence:Algae-derived carotenoids combined with high-purity iron oxides enable color cosmetics with enhanced photostability for humid tropical climates.
- Australia's TGA therapeutic claim pathway:Cosmeceutical registration for vegan retinoid alternatives creates pricing headroom and pharmacy channel access distinct from general cosmetic classification.
Industry Challenges
- Formulation chemist scarcity:The intersection of plant-based material science and cosmetic stability engineering lacks trained practitioners across Asia-Pacific R&D centers, inflating compensation premiums.
- Multi-jurisdiction certification complexity:Brands must simultaneously navigate China's SAMR, India's BIS, and Australia's TGA frameworks, fragmenting compliance resources and extending time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vegan Cosmetics Market |
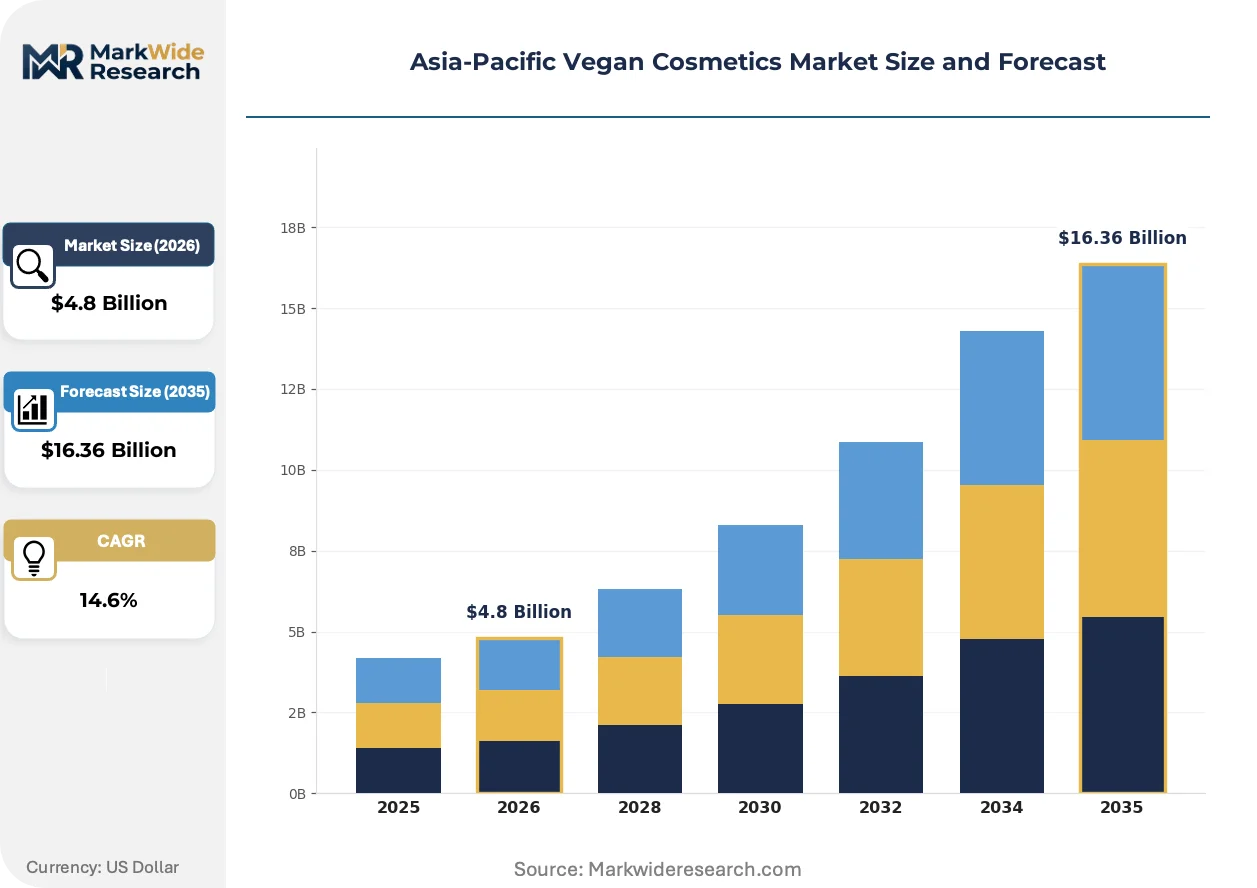
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Makeup, Skincare, Hair Care, Fragrance Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Customer Type: Millennials, Gen Z, Eco-conscious Consumers, Luxury Shoppers Ingredient Source: Plant-based, Synthetic, Organic, Others |
| Companies Covered | L'Oréal S.A., LVMH SE, Amway Corporation, Clarins Group SA, Weleda AG, NAOS, Pacifica Beauty LLC, Plum, Nutriglow Cosmetics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vegan Cosmetics Market Trends and Innovations
Biotechnology is displacing conventional extraction methods across the Asia-Pacific vegan cosmetics value chain, reconfiguring raw material economics and enabling performance claims previously restricted to synthetic or animal-derived inputs.
Precision fermentation for cosmetic actives is miniaturizing production economics, collapsing the scale threshold for viable commercial manufacturing. Indie brands in Tokyo and Singapore now access contract bioreactor capacity at volumes below ten thousand liters, eroding the volume advantages historically held by integrated multinationals. This democratization is fragmenting supply relationships and accelerating ingredient innovation cycles.
SAMR's clean-beauty enforcement in China mandates real-time traceability for imported cosmetic ingredients, compelling suppliers to deploy blockchain-verified chain-of-custody systems. Domestic brands respond by verticalizing sourcing relationships with designated organic cooperatives in Yunnan and Guizhou, converting compliance burden into marketing differentiation through origin storytelling.
Social commerce discovery is compressing brand loyalty cycles among Asia-Pacific millennials, who sample vegan cosmetics through live-streamed demonstrations before committing to repeat purchase. Platforms dominant in China and South Korea now integrate one-click trial-size fulfillment, displacing traditional sampling through retail counters. This behavior concentrates demand volatility around influencer endorsement schedules rather than seasonal promotional calendars.
Asia-Pacific Vegan Cosmetics Market Segmentation
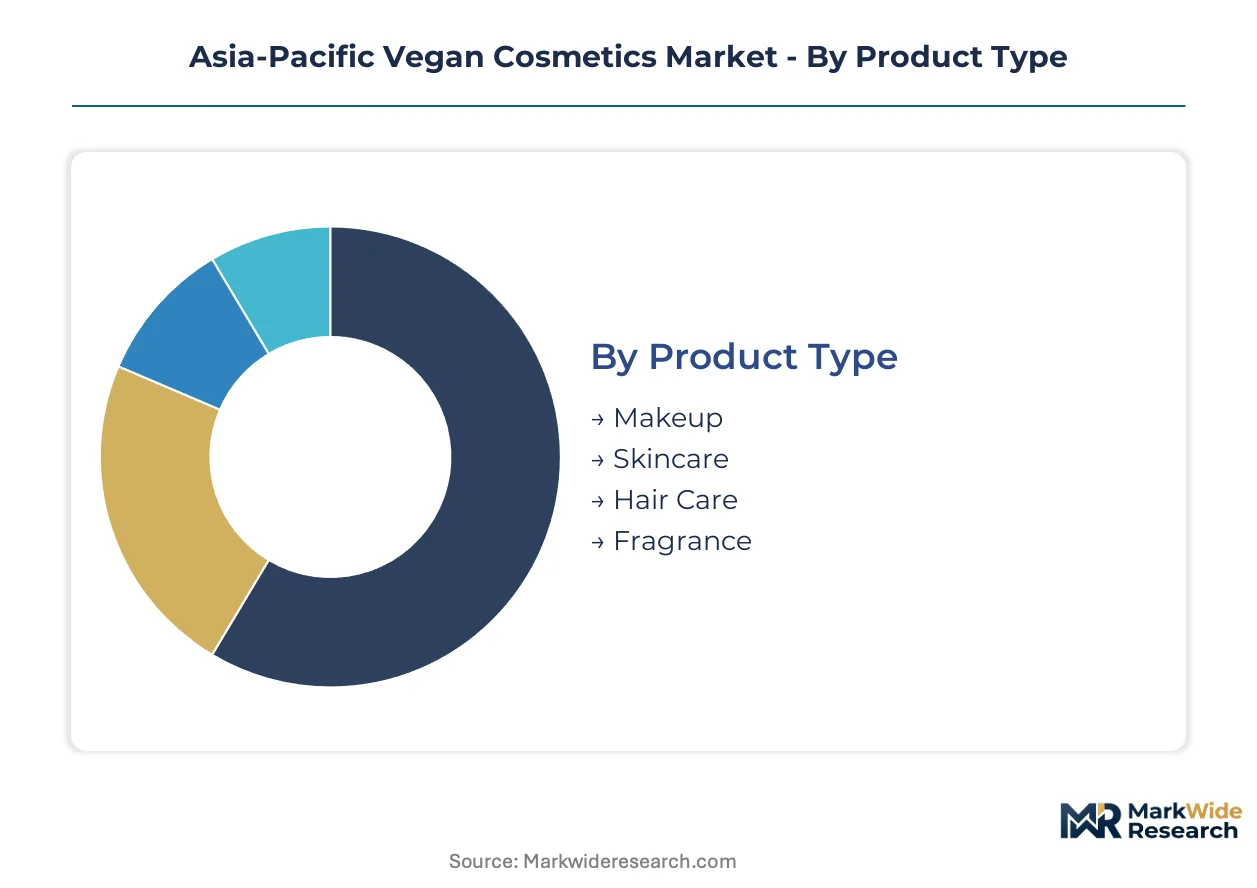
Segmentation in the Asia-Pacific vegan cosmetics market exposes divergent growth mechanics across consumption occasions and sourcing philosophies. Product type and distribution channel splits reveal where margin accretion concentrates versus where volume scaling occurs.
Product Type:
Domestic manufacturing capacity for skincare dominates output volumes in China and South Korea, while makeup formulation clusters increasingly serve export demand into Southeast Asian markets.
- Skincare:High-concentration serums and moisturizers leverage plant-based ceramides and fermented actives with specified purity thresholds. Demand concentrates in China's tier-one cities and India's metropolitan corridors, driven by repeat purchase frequency among millennials seeking ethical alignment without performance compromise.
- Makeup:Color cosmetics rely on mineral pigments and algae-derived carotenoids for photostability in humid tropical climates. South Korean brands lead export-oriented production for Southeast Asian markets, where halal-vegan positioning commands premium shelf placement.
- Hair Care:Plant-based emollients replace keratin-derived conditioning agents.
- Fragrance:Synthetic musk alternatives and botanical extracts serve sensitive-skin segments in Japan and Australia.
Skincare commands the established base. The steepest expansion runs through makeup.
Distribution Channel:
Channel economics bifurcate between high-touch service models and algorithmic discovery platforms, with cost-to-serve ratios determining viable brand scale.
- Online Retail:Live-streaming commerce integrations on platforms dominant in China and South Korea compress purchase cycles through one-click trial-size fulfillment. Seoul and Busan consumers drive category normalization via platform-native discovery, collapsing traditional awareness-to-trial timelines.
- Specialty Stores:Curated vegan assortments with trained consultation staff anchor brand-building in Tokyo and Singapore.
- Supermarkets:Mass-market penetration channels for mid-tier plant-based lines.
- Pharmacies:Australia's TGA therapeutic claim pathway creates pricing headroom for cosmeceutical registration distinct from general cosmetic classification.
Online Retail captures volume leadership. Specialty Stores deliver margin protection.
Customer Type:
Generational cohorts exhibit divergent price elasticity and certification sensitivity, with eco-conscious segments willing to absorb sourcing transparency premiums.
- Millennials:Repeat purchase frequency concentrates in skincare categories with higher per-unit pricing tolerance.
- Gen Z:Social commerce-native discovery patterns dominate trial behavior.
- Eco-conscious Consumers:Blockchain-verified chain-of-custody systems and origin storytelling from Yunnan and Guizhou cooperatives convert compliance burden into marketing differentiation.
- Luxury Shoppers:Premium positioning accepts synthetic peptide alternatives where supply consistency matters over organic certification.
Millennials anchor current revenue. Eco-conscious Consumers are climbing the fastest.
Ingredient Source:
Sourcing strategy determines regulatory pathway complexity and margin structure exposure to agricultural commodity volatility.
- Plant-based:Advanced fermentation processes for squalane and ceramide analogues eliminate performance gaps with animal-derived equivalents. Climate-induced harvest variability across Southeast Asian sourcing corridors compresses margin structures for mid-tier brands dependent on natural emollients.
- Synthetic:Contract manufacturers in eastern China control concentrated synthetic active production, creating supply vulnerability for brands without captive fermentation capacity.
- Organic:Extended BIS certification timelines in India delay product launches versus conventional cosmetic registration.
- Others:Hybrid biotech-mineral formulations for tropical climate stability.
Plant-based commands the established base. Synthetic alternatives gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia-Pacific vegan cosmetics landscape. Japanese and Australian buyers absorb premium pricing for certification-heavy formulations. Indian and Indonesian consumers remain acutely price-sensitive, compressing margin structures for mid-tier entrants.
China
SAMR's prohibition of animal-tested imports and mandatory ingredient disclosure drives domestic manufacturers toward vegan formulation compliance. Shanghai-based R&D clusters localize plant-based actives for humid climate performance. Tier-one cities Beijing, Shanghai, and Shenzhen concentrate demand through live-streaming commerce platforms.
South Korea
Seoul and Busan consumers normalize vegan cosmetics through platform-native social commerce discovery. MFDS cosmetic safety standards accelerate clean-label verification timelines. Domestic brands leverage export-oriented production for Southeast Asian halal-vegan market penetration.
India
BIS vegan-label certification timelines extend product launches by eight to fourteen months versus conventional registration. Maharashtra and Karnataka manufacturing clusters adapt to domestic transparency requirements. Metropolitan corridors Mumbai, Delhi-NCR, and Bangalore drive repeat skincare purchases among millennials.
Japan
METI oversight of cosmetic claims combines with PMDA therapeutic classifications for cosmeceutical positioning. Tokyo and Osaka specialty retail anchors brand-building through trained consultation staff. Sensitive-skin segments accept synthetic peptide alternatives where supply consistency outweighs organic certification.
Australia
TGA therapeutic claim pathways for vegan retinoid alternatives create pharmacy channel access distinct from general cosmetic classification. Sydney and Melbourne clusters concentrate biotech-mineral hybrid pigment development. Blockchain-verified chain-of-custody systems convert regulatory compliance into origin storytelling differentiation.
Asia-Pacific Vegan Cosmetics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific vegan cosmetics landscape. Integrated multinationals leverage captive fermentation capacity and R&D footprints in Shanghai. Indie brands access miniaturized bioreactor production through contract manufacturers in Tokyo and Singapore. The market structure fragments across four strategic tiers: biotechnology-forward specialists, direct-selling network operators, clean-label mass-market entrants, and luxury heritage houses. Dominant competitive moves include vertical integration into plant-based raw material sourcing and live-streaming commerce platform partnerships.
Within the biotechnology-forward tier, L'Oréal S.A. and Pacifica Beauty LLC exemplify divergent scale approaches to plant-based formulation. L'Oréal S.A., a French société anonyme, occupies a position representing integrated multinational R&D deployment. Pacifica Beauty LLC, a US limited liability company, anchors the specialist archetype focused on fragrance-free vegan lines. Amway Corporation, a US-based direct-selling enterprise, sits within the network-operator tier leveraging Southeast Asian tier-two city penetration.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| LVMH SE |
| Amway Corporation |
| Clarins Group SA |
| Weleda AG |
| NAOS |
| Pacifica Beauty LLC |
| Plum |
| Nutriglow Cosmetics |
| Others |
Pricing and Supply Chain Analysis
Bioreactor scale thresholds below ten thousand liters are collapsing minimum viable production economics across the Asia-Pacific vegan cosmetics landscape, concentrating supply relationships among contract manufacturers in eastern China while fragmenting price-setting power between integrated multinationals and indie brands accessing miniaturized fermentation capacity.
Pricing Analysis
SAMR's cosmetic registration mandate dictates the pricing tier structure across China's vegan cosmetics market. Three-tier pricing structure across premium, standard, and economy levels separates TGA-registered cosmeceuticals from general cosmetic classifications from unverified imports. Price differentiation stems from certification grade and geographic delivery cost, with Indian BIS timelines compressing margins for mid-tier entrants. Cost compression in economy tiers is intensifying because climate-induced harvest variability for organic shea and coconut oil feeds raw material volatility. Eco-conscious consumers in Tokyo and Sydney absorb the highest premiums for blockchain-verified chain-of-custody systems, while price-sensitive buyers in Surabaya and Medan drive volume through halal-vegan positioning at standard tiers.
Supply Chain Analysis
Inventory lead times for synthetic peptide synthesis stretch eight to fourteen months longer than conventional cosmetic registration timelines in India. Supply concentrates in eastern China for contract fermentation capacity, South Korea for export-oriented color cosmetics production, and Yunnan province for designated organic cooperative sourcing. Raw material dependencies center on plant-based ceramides, algae-derived carotenoids, and mineral pigments with specified purity thresholds. Single-source vulnerability runs through eastern China's control of over seventy percent of synthetic active production. Distribution runs through live-streaming commerce platforms in tier-one Chinese cities and direct-selling networks across Southeast Asian tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific vegan cosmetics market is cycling through a regulatory enforcement upswing as SAMR, BIS, and TGA frameworks simultaneously tighten compliance requirements, compressing time-to-market for non-compliant entrants while rewarding preemptive certification investments.
For Market Incumbents: Fortify captive fermentation capacity in Shanghai and Singapore R&D clusters to offset single-source peptide synthesis concentration risk from eastern Chinese contract manufacturers. Deepen backward integration into Yunnan and Guizhou organic cooperatives to convert SAMR traceability mandates into origin storytelling differentiation. Prioritize BIS pre-certification filing in India to narrow the eight-to-fourteen-month launch gap versus conventional cosmetic registration.
For New Entrants and Emerging Players: Anchor in Indonesia's underpenetrated tier-two cities of Surabaya, Bandung, and Medan ahead of mass-market saturation. Target halal-vegan positioning as the most penetrable segment for Southeast Asian expansion. Deploy direct-selling network partnerships as the primary go-to-market angle, leveraging Amway Corporation's demonstrated pathway across Southeast Asian tier-two cities.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-forward specialists with miniaturized bioreactor access over legacy extraction-dependent formulators. Long-term viability across the five-to-ten-year window rests on precision fermentation cost curves continuing to decline. Target acquisition archetypes include indie brands with Tokyo or Singapore contract manufacturing relationships and established social commerce platform integrations. The signal to watch is MFDS acceleration of clean-label verification timelines, which would compress competitive moats for early certifiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Miniaturized bioreactor access below ten thousand liters democratizes active ingredient production for indie brands. |
| Blockchain Traceability Deployment | SAMR-mandated chain-of-custody systems convert compliance burden into marketing differentiation for Yunnan-sourced organics. |
| Halal-Vegan Certification Convergence | Dual positioning captures premium shelf placement in Indonesian and Malaysian distribution channels. |
| Social Commerce Platform Integration | One-click trial-size fulfillment on Chinese and South Korean platforms collapses traditional awareness-to-trial timelines. |
| TGA Therapeutic Claim Pathway | Cosmeceutical registration for vegan retinoid alternatives unlocks pharmacy channel access distinct from general cosmetic classification. |
Research Methodology
A spread of perspectives from brand managers at vegan cosmetics houses, category buyers at specialty retailers, supply planners at contract manufacturers, and regulatory affairs leads at multinational R&D centers converged on the working assumptions. Primary interviews combined with secondary validation from SAMR registration filings, BIS certification databases, MFDS cosmetic safety standards, and TGA therapeutic goods listings. Customs records for plant-based raw material imports and Circana retail audit data for channel volume splits anchored bottom-up and top-down triangulation.
Segmentation dimensions modeled include product type, distribution channel, customer cohort, and ingredient sourcing philosophy across the projection horizon. CAGRs derived from regression analysis against macroeconomic indicators and regulatory enforcement intensity indices. Industry-specific forecast inputs incorporated climate volatility projections for Southeast Asian shea and coconut oil harvests and social commerce platform penetration rates in Seoul and Busan.
Decision-makers should treat outputs as directional under assumptions of sustained SAMR enforcement intensity and stable bioreactor scale economics; material deviation in either would warrant model refresh. Forecasts reflect these base assumptions without claiming predictive certainty for regulatory timeline shifts or biotechnology cost curve inflections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegan Cosmetics
Vegan Cosmetics Market
Vegan Cosmetics
Brazil Vegan Cosmetics Market
Vegan Cosmetics
Vegan Face Cream Market
Vegan Cosmetics
Global Probiotic Cosmetics Market
Vegan Cosmetics
Organic Cosmetics Market
Vegan Cosmetics
Argentina Vegan Cosmetics Market
Vegan Cosmetics
Chile Vegan Cosmetics Market
Vegan Cosmetics
India Vegan Cosmetics Market
Vegan Cosmetics
Mexico Vegan Cosmetics Market
Vegan Cosmetics
US Vegan Cosmetics Market
Vegan Cosmetics
France Vegan Cosmetics Market
Vegan Cosmetics
Germany Vegan Cosmetics Market
Vegan Cosmetics
Functional Cosmetics Market
Vegan Cosmetics
Australia Vegan Cosmetics Market
Vegan Cosmetics
China Vegan Cosmetics Market
Vegan Cosmetics
Japan Vegan Cosmetics Market