
 Flushable Wipes Market | 2026-2036
Flushable Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Flushable Wipes Market Analysis
North American nonwoven producers is decoupling from legacy synthetic fiber supply chains as cellulose sourcing costs fluctuate. Procter & Gamble leverages integrated pulp-to-wipe manufacturing across Midwestern US facilities to control input volatility. Kimberly-Clark anchors its institutional flushable portfolio through long-term healthcare procurement contracts. Nice-Pak Products specializes in private-label biodegradable formulations for European retail channels.
Flushable wipes are nonwoven substrates engineered to disintegrate in municipal wastewater systems within a specified flushability timeframe, typically composed of wood pulp fibers bonded through hydroentanglement or thermal processes for controlled dispersibility. Personal care wipes command premium shelf positioning in pharmacy and supermarket channels where consumers prioritize skin-safe formulations. Biodegradable materials represent the fastest-expanding material category as regulators in multiple geographies restrict plastic fiber content. Household wipes maintain volume leadership through recurring purchase patterns in mass retail, though margin pools concentrate in healthcare-focused adult wipe segments.
The EPA monitors flushable wipe dispersibility through wastewater compatibility guidelines while the EU Green Deal pressures substitution of petrochemical-derived fibers. Health Canada and PMRA enforce skin-contact safety standards for wipes marketed to infant and sensitive-skin demographics. Stakeholders must track evolving municipal enforcement of flushability claims as sewage authorities in key markets gain authority to impose product testing mandates and labeling penalties.
Market Dynamics
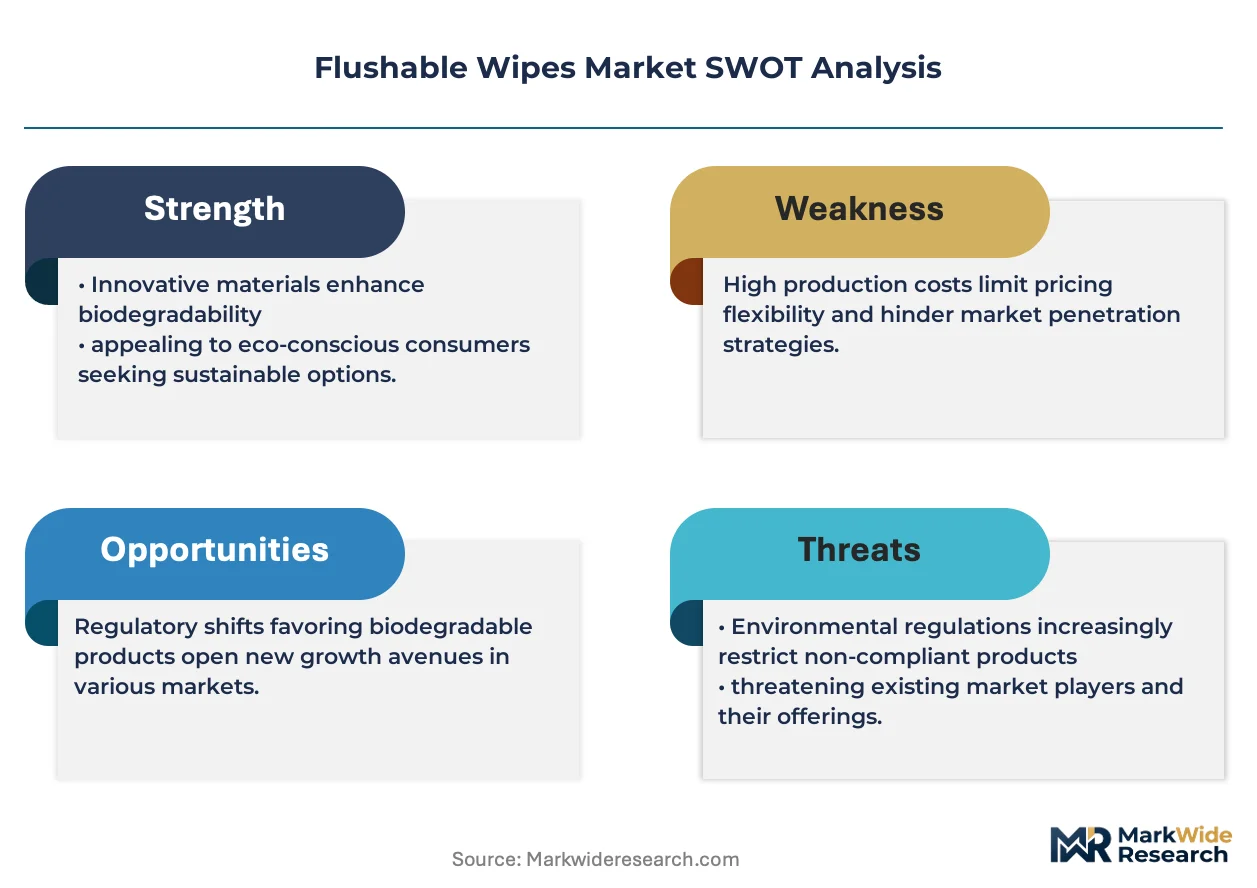
Stringent flushability certifications from municipal sewage authorities are forcing manufacturers to reformulate dispersibility standards while cellulose input costs fluctuate unpredictably. This regulatory-material cost tension is compressing margins and redrawing competitive positioning across supply chains.
Growth Catalysts
- Healthcare procurement expansion:Patient hygiene protocols in acute care and long-term care facilities are institutionalizing flushable wipe consumption as standard equipment.
- EU Green Deal fiber substitution mandates:Petrochemical-derived synthetic fiber restrictions are accelerating demand for biodegradable wood pulp substrates in European retail channels.
- German municipal enforcement:Sewage authorities in Germany impose Europe's strictest flushability testing regimes, creating certified-product premiums that reward compliant manufacturers.
Market Restraints
- Cellulose fiber cost volatility:Wood pulp price fluctuations from North American timber markets destabilize input cost planning for nonwoven producers.
- EPA wastewater guideline uncertainty:Pending dispersibility standard revisions in the United States create compliance timeline risk and capital allocation hesitation.
- Plastic fiber substitution complexity:Biodegradable alternatives exhibit inferior wet-strength performance, limiting functional parity in heavy-duty institutional applications.
Strategic Opportunities
- Healthcare adult wipe segments:Aging demographics and incontinence management protocols in developed markets concentrate margin pools in clinical-grade formulations.
- Private-label biodegradable channels:European retailers seek certified flushable formulations for store-brand portfolios, opening white space beyond multinational brand dominance.
- Integrated pulp-to-wipe manufacturing:Captive cellulose supply chains insulate producers from commodity volatility while shortening quality certification cycles.
Industry Challenges
- Flushability certification timelines:Municipal testing mandates from sewage authorities in Germany, the United Kingdom, and the United States extend product launch cycles by 12-18 months.
- Nonwoven engineering talent scarcity:Hydroentanglement process optimization and dispersibility chemistry expertise concentrates among aging specialist workforces in Midwestern US and Nordic production clusters.
- Legacy wastewater infrastructure incompatibility:Aging municipal sewage systems in older US metropolitan areas reject even certified-flushable products, creating market access fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flushable Wipes Market |
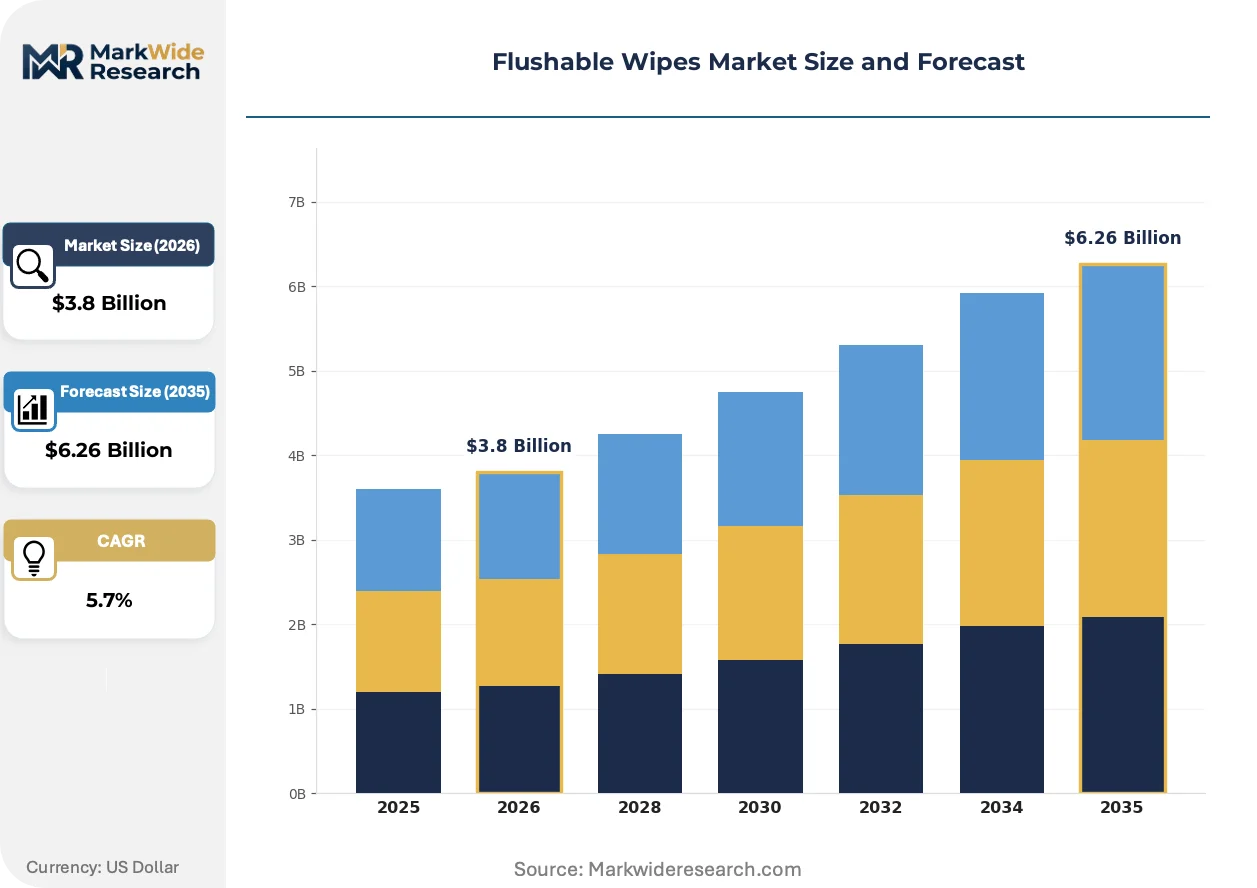
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baby Wipes, Adult Wipes, Household Wipes, Personal Care Wipes Material: Non-Woven Fabric, Cotton, Biodegradable Materials, Plastic Fiber Sales Channel: Retail Stores, Online Platforms, Supermarkets, Pharmacies End User: Households, Healthcare Facilities, Hospitality Sector, Childcare Centers |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Nice-Pak Products, Reynolds Consumer Products, Rockline Industries, S.C. Johnson & Son, Codi Group, The Honest Company, Dude Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flushable Wipes Market Emerging Trajectories
Material science breakthroughs in controlled dispersibility are converging with regulatory pressure to redefine product performance benchmarks. Three interconnected developments are compressing traditional formulation approaches while opening premium positioning for certified-compliant manufacturers.
Hydroentanglement bonding technology is converging with thermal bonding processes to engineer cellulose substrates that maintain wet strength during use yet disintegrate within specified wastewater residence times. Healthcare procurement teams are prioritizing these dual-performance specifications in institutional tenders. The structural consequence is compressing market share for legacy synthetic fiber formulations that fail municipal dispersibility testing.
The EPA's wastewater infrastructure guidelines are pressuring manufacturers to demonstrate dispersibility through standardized testing protocols rather than marketing claims. Industrial consequence includes capital reallocation toward in-house testing facilities and third-party certification partnerships. Adult incontinence and patient hygiene segments in the United States are responding fastest, with procurement contracts now mandating EPA-aligned documentation.
Buyer concentration among large healthcare systems and retail pharmacy chains is compressing supplier negotiation cycles and unbundling traditional distributor markups. Direct procurement relationships between manufacturers and institutional buyers are displacing wholesale intermediaries in North American and Western European channels. This pattern is most visible in United States hospital group purchasing organizations and German pharmacy cooperative networks.
Flushable Wipes Market Segmentation
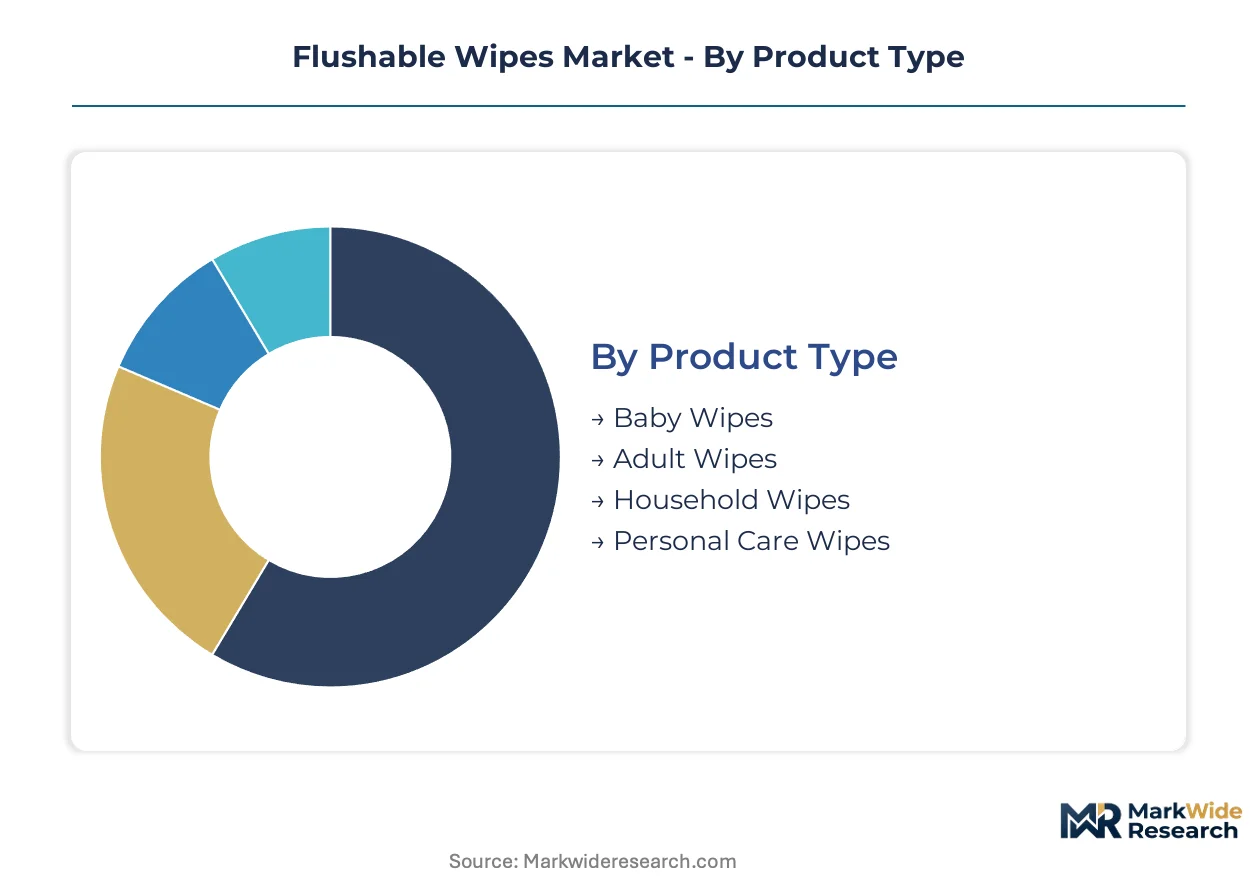
Flushable wipe purchasing decisions split across four distinct axes: functional use case, substrate composition, procurement channel, and institutional versus consumer deployment. Each dimension carries different margin profiles, certification requirements, and supply chain configurations that reshape competitive positioning.
Product Type:
Buyer selection hinges on skin-contact sensitivity and institutional protocol requirements rather than price alone.
- Adult Wipes:Engineered for incontinence management and patient hygiene with higher wet-strength cellulose substrates and pH-balanced formulations. Demand concentrates in United States long-term care facilities where Medicaid reimbursement protocols now mandate flushable disposal compliance for infection control.
- Personal Care Wipes:Facial and feminine hygiene formulations prioritize dermatological safety certifications over dispersibility performance. German pharmacy cooperative networks drive premium positioning through mandatory municipal flushability badges that filter non-compliant suppliers from tender participation.
- Baby Wipes:Hypoallergenic formulations with minimal preservative loads for infant skin tolerance.
- Household Wipes:General surface and bathroom cleaning applications with lower per-unit margins and mass retail volume concentration.
Volume sits with Household Wipes; growth tilts toward Adult Wipes.
Material:
Raw material selection determines regulatory compliance trajectory and capital equipment requirements for substrate bonding.
- Biodegradable Materials:Wood pulp and plant-derived cellulose engineered through hydroentanglement for controlled dispersibility within municipal wastewater residence times. EU Green Deal fiber substitution mandates are accelerating procurement shifts in France and Netherlands retail channels where petrochemical-derived alternatives face shelf-access restrictions.
- Non-Woven Fabric:Synthetic-polymer blends dominate legacy institutional contracts in United States acute care facilities where wet-strength performance outweighs dispersibility certification.
- Cotton:Natural fiber substrates with limited flushability certification due to slow disintegration kinetics.
- Plastic Fiber:Polyester and polypropylene blends facing regulatory phase-out across European jurisdictions.
Non-Woven Fabric retains installed-base volume; biodegradable alternatives gain share fastest.
Sales Channel:
Channel selection reflects buyer scale, certification documentation requirements, and inventory turnover velocity.
- Pharmacies:Dermocosmetic and clinical-grade formulations with trained staff consultation and insurance reimbursement pathways in German and Swiss markets.
- Supermarkets:Mass-market household and baby wipe segments with high-frequency replenishment and private-label penetration.
- Retail Stores:Convenience-oriented personal care formats with impulse-purchase placement.
- Online Platforms:Subscription-based adult incontinence products with direct-to-consumer bypass of distributor markups.
Supermarkets anchor volume throughput; pharmacies concentrate margin extraction.
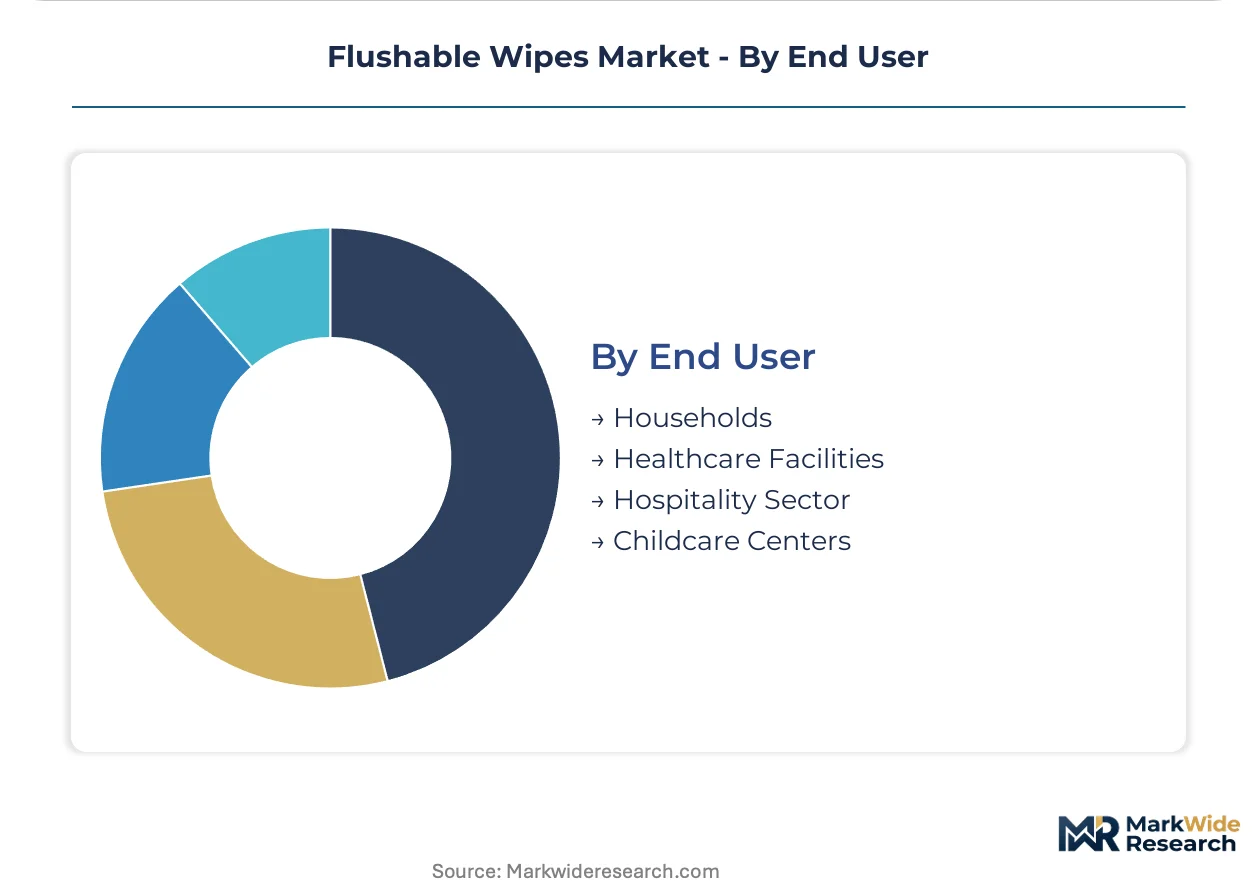
End User:
End-use environment dictates performance specifications, bulk procurement scale, and compliance documentation intensity.
- Healthcare Facilities:Hospital group purchasing organizations in the United States mandate EPA-aligned dispersibility documentation and infection-control protocols. Long-term care operators prioritize adult wipe formulations with clinical-grade wet strength and documented flushability to reduce linen service costs.
- Households:Consumer-directed purchases across mass retail and online channels with price sensitivity and brand loyalty fragmentation.
- Hospitality Sector:Hotel and cruise line procurement with bulk-volume requirements and wastewater system compatibility constraints.
- Childcare Centers:Regulated skin-safety standards with institutional purchasing through specialized distributors.
Healthcare Facilities command premium pricing; Households provide volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wood pulp supply chains anchored in North American timber markets and Nordic forestry operations shape regional manufacturing footprints for dispersible nonwoven substrates.
United States
Hospital group purchasing organizations in the Midwest and Southeast are mandating EPA-aligned dispersibility documentation for adult wipe procurement contracts. The EPA's pending wastewater infrastructure guideline revisions are forcing reformulation timelines across Ohio and Wisconsin production clusters. Procter & Gamble operates integrated pulp-to-wipe facilities in Cincinnati that compress certification cycles for institutional buyers.
Germany
Municipal sewage authorities in North Rhine-Westphalia and Bavaria enforce Europe's strictest flushability testing regimes, creating certified-product premiums. The EU Green Deal's fiber substitution mandates are accelerating wood pulp procurement shifts across Frankfurt and Munich retail networks. Nice-Pak Products anchors private-label biodegradable supply through long-term pharmacy cooperative contracts.
United Kingdom
Water UK and regional sewage authorities in England are extending product launch cycles through municipal testing mandates for dispersibility claims. The Environment Agency's wastewater compatibility standards pressure manufacturers toward hydroentanglement process upgrades. Manufacturing activity concentrates in Greater Manchester and West Midlands clusters serving pharmacy and supermarket channels.
Canada
Health Canada and PMRA skin-contact safety standards govern infant and sensitive-skin wipe formulations marketed through Ontario and Quebec retail networks. Provincial procurement protocols in British Columbia and Alberta are institutionalizing flushable wipe consumption in long-term care facilities. Kimberly-Clark leverages cross-border supply chain integration to serve institutional buyers.
France
ANSM dermatological safety certifications filter non-compliant suppliers from pharmacy tender participation in Paris and Lyon metropolitan markets. The EU Green Deal's plastic fiber restrictions are reshaping substrate sourcing decisions for mass retail channels. Codi Group operates formulation facilities serving private-label biodegradable demand across Western European retail networks.
Flushable Wipes Market Vendor Landscape
Global majors compete with regional champions across certification standards and procurement channel access, producing a tiered structure where scale-driven players anchor volume while specialists capture premium positioning. The vendor base splits between integrated pulp-to-wipe manufacturers controlling input volatility and formulation specialists serving private-label demand. Three archetypes dominate: Midwestern US integrated producers, European biodegradable specialists, and mass-market brand houses with healthcare procurement relationships. Competitive moves concentrate on backward integration into cellulose supply and third-party certification partnerships to compress compliance timelines.
Within the integrated manufacturing tier, Procter & Gamble and Kimberly-Clark exemplify scale-driven positioning through captive pulp supply chains and institutional contract anchoring. Nice-Pak Products occupies a specialist position serving European retail private-label demand with certified biodegradable formulations. These three players represent divergent strategic vectors: input control, procurement relationship depth, and regulatory-specialist positioning.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Nice-Pak Products |
| Reynolds Consumer Products |
| Rockline Industries |
| S.C. Johnson & Son |
| Codi Group |
| The Honest Company |
| Dude Products |
| Others |
Supply Flow & Price Mechanics
Hospital group purchasing organizations in the United States Midwest concentrate procurement volume, compressing supplier margins and forcing unbundling of after-sales service from base product pricing. This buyer consolidation rewards manufacturers with captive cellulose supply chains while penalizing formulation specialists exposed to wood pulp commodity volatility.
Pricing Analysis
After-sales technical support and third-party flushability certification documentation are increasingly unbundled from base wipe pricing in institutional tenders. Three-tier pricing structure across premium certified-compliant, standard municipal-aligned, and economy non-certified levels dominates procurement negotiations. Price differentiation hinges on EPA-aligned dispersibility documentation and hydroentanglement process quality grades. Cost compression in standard-tier formulations is intensifying because wood pulp input volatility transfers margin pressure downstream. Mass retail household segments exhibit highest price sensitivity; healthcare adult wipe buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Freight costs from Nordic and North American timber regions to Midwestern US hydroentanglement facilities constitute a structural cost anchor for dispersible substrate producers. Manufacturing gravity centers on the United States, Germany, and Sweden where pulp-to-wipe integration compresses quality certification cycles. Raw material dependencies draw from Canadian softwood pulp, Brazilian eucalyptus fibers, and specialty dispersibility chemistry inputs. Single-source vulnerability concentrates in hydroentanglement equipment suppliers serving the nonwoven sector. Distribution runs through hospital group purchasing organizations, pharmacy cooperative networks, and mass retail procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flushable wipes sector is becoming a vertical-integration race where captive cellulose supply chains determine margin defense capability. Players lacking upstream pulp control face displacement as wood pulp volatility compresses formulation specialists.
For Market Incumbents: Acquire hydroentanglement production assets in the United States Midwest or Nordic regions to insulate margin structures from wood pulp commodity swings. Secure long-term contracts with German municipal sewage authorities to lock in certified-product premiums before testing mandate expansion. Prioritize backward integration into softwood pulp supply to compress certification timelines for healthcare procurement tenders. For New Entrants and Emerging Players: Premium-economy tier price gaps in European pharmacy private-label channels offer white-space entry points for biodegradable formulation specialists. Target French and Netherlands retail networks where EU Green Deal fiber substitution mandates are accelerating shelf-access restrictions on synthetic alternatives. Pursue direct procurement relationships with regional pharmacy cooperatives to bypass multinational brand distribution layers. For Investors and Strategic Acquirers: The window for entry favors mid-cap biodegradable specialists with existing municipal flushability certifications in Germany or the United Kingdom. Long-term viability over the next decade hinges on regulatory compliance depth rather than volume scale alone. Watch for EPA wastewater guideline finalization as the signal for capital reallocation timing across North American production footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive cellulose sourcing insulates Procter & Gamble and Kimberly-Clark from timber market volatility. |
| Third-Party Flushability Certification Partnership | Nice-Pak Products leverages German municipal testing relationships to compress pharmacy tender participation timelines. |
| Healthcare Procurement Contract Anchoring | Long-term agreements with United States hospital group purchasing organizations stabilize volume throughput for adult wipe segments. |
| Biodegradable Formulation R&D Expansion | Hydroentanglement process optimization addresses wet-strength performance gaps in heavy-duty institutional applications. |
| Direct-to-Consumer Subscription Launch | Online platforms bypass distributor markups in adult incontinence segments where buyer concentration is lowest. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with nonwoven engineering directors, hospital procurement managers, pharmacy cooperative buyers, and municipal sewage authority testing officers combined with EPA guideline documents, EU Green Deal implementation reports, and wood pulp futures exchange data. Bottom-up demand modeling from healthcare facility procurement databases triangulated against top-down market sizing from customs records and industry association shipment reports.
Reconciliation between production-volume data from Midwestern US manufacturing clusters and consumption patterns across German pharmacy networks validated segment-level assumptions across the analysis window. Segmentation dimensions modeled include product type, substrate material composition, sales channel configuration, and end-use environment. CAGRs were derived from regression analysis of historical procurement volumes against demographic and regulatory driver indices. Wood pulp price trajectories and municipal testing mandate adoption curves served as primary forecast sensitivity inputs.
Inputs from EPA draft guideline releases and German municipal sewage authority testing protocols were available through the study window; gaps in real-time healthcare procurement contract terms introduce uncertainty bands around institutional volume projections. Forecasts reflect documented assumptions about regulatory timeline acceleration and fiber substitution cost parity. Stakeholders should weight assumptions against their own operating context and pulp supply contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Freshener Market
Household Items
Thermos Bottle Market
Household Items
Asean Cookware Market
Household Items
Folded Tissues Market
Household Items
Umbrella Market
Household Items
Smart Bathroom Products Market
Household Items
UK Digital Showers Market
Household Items
Dishwasher Detergent Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Scouring Pads Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Hydralight Lanterns Market
Household Items
Bristle Brush Market
Household Items
Smart Memory Foam Market