
 Pet Care E-Commerce Market | 2026-2036
Pet Care E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Care E-Commerce Market Intelligence
China is rewriting fulfillment expectations for pet care e-commerce through same-city warehouse networks and live-stream commerce integration. Chewy, Inc. anchors the United States market with automated pharmacy and subscription replenishment systems. Amazon.com, Inc. dominates general merchandise pet categories through Prime logistics density. Zooplus SE specializes in pan-European specialty diets and breed-specific nutrition formulations.
Pet care e-commerce encompasses the digital retail of companion animal nutrition, health, and lifestyle products through web-based platforms and mobile applications, typically involving temperature-controlled fulfillment for fresh and prescription items alongside standard parcel logistics. Its primary commercial purpose is to disintermediate traditional retail by offering personalized replenishment, veterinary-grade product access, and data-driven dietary recommendations to dispersed pet-owning households. Food commands the largest share of transaction value due to replenishment frequency and subscription attach rates, while subscription services capture the most durable customer lifetime value through auto-ship algorithms and wellness program bundling. Direct-to-consumer channels are expanding fastest among specialty and prescription brands seeking margin control and first-party data ownership.
FDA Center for Veterinary Medicine oversight of pet food safety and labeling, alongside EU REACH and F-Gas Regulation compliance for grooming aerosols and climate-controlled logistics, shapes cross-border product eligibility and warehousing requirements. State-level veterinary board regulations in the United States restrict prescription diet dispensing to licensed clinician relationships, creating platform-level credential verification burdens. Stakeholders must monitor evolving platform liability frameworks for third-party seller product safety and telehealth-adjacent pet wellness claims.
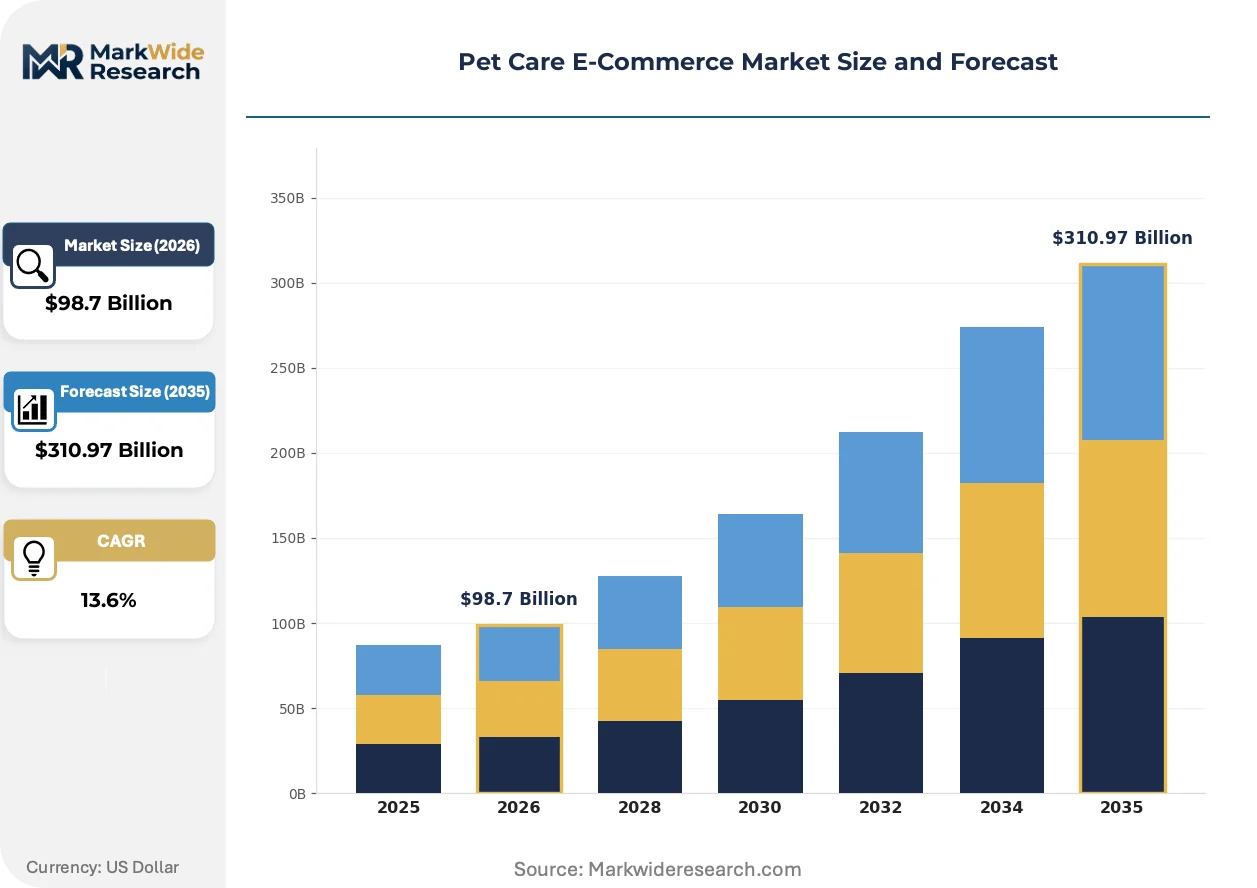
Market Dynamics
Subscription auto-ship algorithms are compressing customer acquisition costs and locking lifetime value through predictive replenishment timing. This structural shift forces platforms to prioritize data infrastructure over traditional marketing spend.
Growth Catalysts
- AAFCO nutritional adequacy protocols:Standardized feeding trials and nutrient profiles reduce cross-border certification friction for specialty diet exporters targeting the United States.
- Live-stream commerce integration:Chinese platforms embed veterinary consultations and product demonstrations within purchase flows, collapsing education-to-transaction cycles.
- Temperature-controlled last-mile networks:Refrigerated micro-fulfillment nodes enable fresh pet food subscriptions previously constrained by spoilage windows.
Market Restraints
- Veterinary prescription verification:State-level veterinary board regulations in the United States mandate licensed clinician relationships for therapeutic diet dispensing, creating platform-level credential infrastructure burdens.
- Cold chain capex concentration:Fresh and frozen pet food categories require refrigerated warehousing density that concentrates fulfillment investment in urban corridors.
- Cross-border REACH compliance:EU F-Gas Regulation and ECHA chemical restrictions on grooming aerosols and climate-controlled logistics equipment reshape product eligibility for non-European sellers.
Strategic Opportunities
- Telehealth-adjacent wellness bundling:Platforms integrating remote veterinary consultations with prescription diet auto-ship capture higher-margin recurring revenue streams.
- AI-driven dietary recommendation engines:Machine learning models processing breed-specific health data and purchase history personalize nutrition plans at scale.
- Rural underpenetration in India:Mobile-first commerce infrastructure and vernacular-language interfaces unlock dispersed pet-owning households outside tier-one cities.
Industry Challenges
- Veterinary pharmacist credential scarcity:Platforms dispensing prescription diets face recruitment bottlenecks for licensed professionals capable of remote consultation compliance.
- Legacy ERP integration with auto-ship algorithms:Established retailers retrofitting subscription infrastructure encounter data architecture fragmentation between inventory and customer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Care E-Commerce Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $310.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Toys, Accessories, Grooming Products Sales Channel: Direct-to-Consumer, Marketplace, Retailer Website, Subscription Service Customer Type: Pet Owners, Breeders, Shelters, Veterinary Clinics Delivery Mode: Home Delivery, In-Store Pickup, Scheduled Delivery, Express Shipping |
| Companies Covered | Amazon.com, Inc., Chewy, Inc., Petco Health and Wellness Co., Inc., PetSmart, Inc., Zooplus SE, Walmart, Target Brands, Inc., BARK, PetMed Express, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Care E-Commerce Market Strategic Shifts & Innovations
Artificial intelligence and live-commerce infrastructure are collapsing the distance between veterinary guidance and purchase execution. These technologies compress decision cycles while raising compliance and data governance stakes.
Machine learning recommendation engines are hybridizing static product catalogs with dynamic health data inputs. Platforms serving millennial pet owners deploy algorithms correlating breed predispositions, age-based nutritional needs, and purchase history to generate personalized diet plans. This capability is compressing the role of traditional veterinary intermediaries in routine nutrition decisions.
EU F-Gas Regulation phase-down schedules are accelerating cold chain equipment replacement across European fulfillment networks. Stricter hydrofluorocarbon restrictions raise capital requirements for climate-controlled warehousing. Specialty fresh food sellers in Germany and France face compressed timelines for retrofitting refrigeration infrastructure.
Mobile-first buying patterns among urban Chinese pet owners are collapsing traditional e-commerce search-and-select sequences. Live-stream commerce embeds real-time veterinary consultation, product demonstration, and flash purchasing within single sessions. This behavioral shift concentrates transaction volume during scheduled broadcast windows rather than distributed throughout the day.
Pet Care E-Commerce Market Segmentation
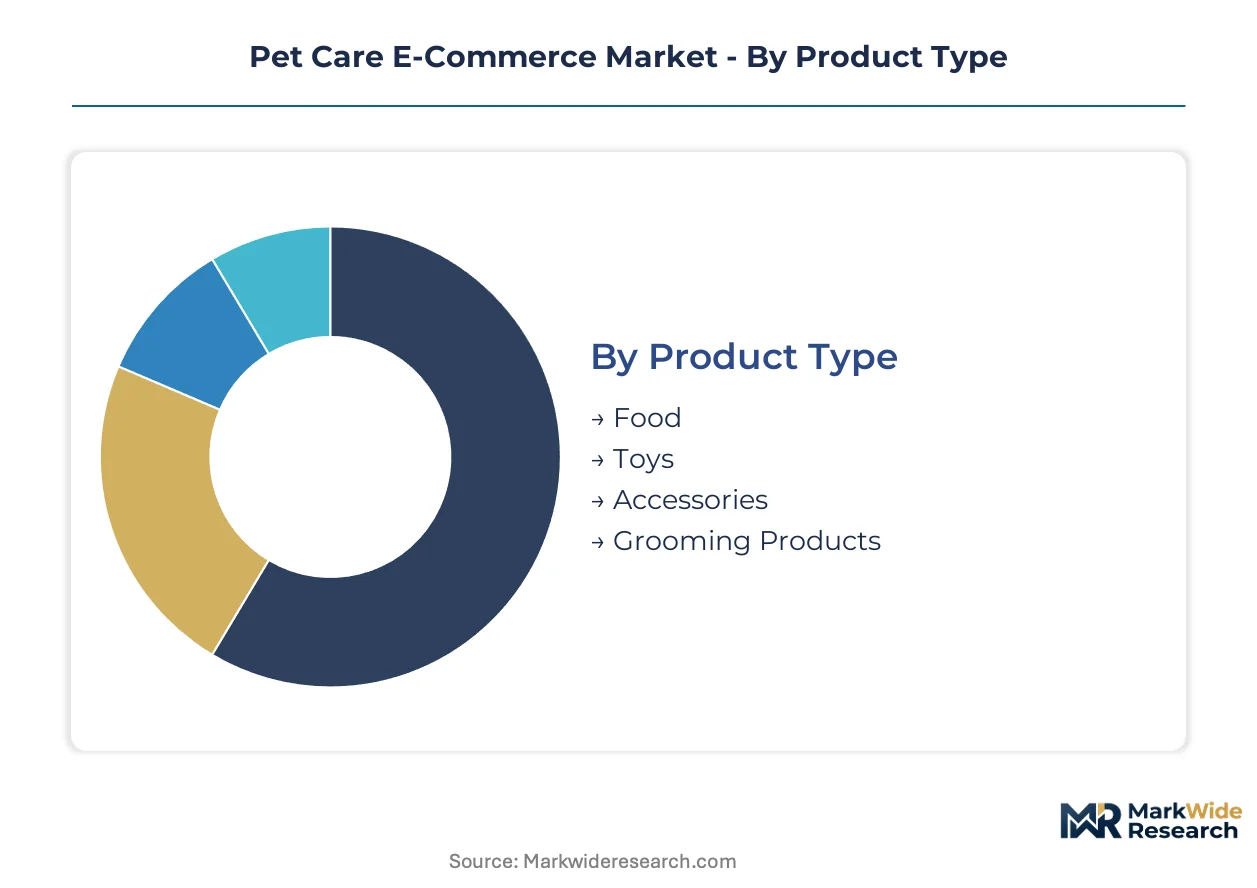
Segmentation in pet care e-commerce reveals how fulfillment infrastructure, customer relationship depth, and regulatory exposure vary across transaction types. Platforms optimize warehouse networks and subscription algorithms differently for each slice.
Product Type:
Cost tier differentiation separates commoditized replenishment categories from discretionary lifestyle purchases with divergent margin profiles.
- Food:Dry kibble and wet formulations dominate transaction frequency and subscription attach rates. Temperature-controlled fulfillment for fresh and raw diets concentrates investment in urban warehouse clusters where spoilage windows compress delivery radius requirements.
- Toys:Durable chew products and interactive enrichment devices carry higher per-unit margins but lower purchase frequency. Demand clusters around breed-specific size requirements and seasonal gifting patterns in North American and European markets.
- Accessories:Collars, leashes, and bedding represent mid-tier margin categories with fashion-driven replacement cycles.
- Grooming Products:Shampoos, dental care, and coat maintenance items face EU REACH compliance burdens for aerosol formulations and chemical ingredient disclosure.
Food holds installed capacity. Toys is rotating up the share rankings.
Sales Channel:
Application architecture determines data ownership depth and margin capture potential across platform models.
- Direct-to-Consumer:Brand-owned storefronts bypass marketplace fees to capture first-party purchase data and lifetime value metrics. Specialty diet manufacturers in Germany and France deploy this channel to maintain margin control over veterinary-exclusive formulations.
- Marketplace:Aggregator platforms consolidate search traffic and logistics density. Amazon dominates general merchandise pet categories through Prime fulfillment networks while absorbing regulatory liability for third-party seller compliance.
- Retailer Website:Traditional pet retail chains extend brick-and-mortar inventory to digital channels with buy-online-pickup-in-store options.
- Subscription Service:Auto-ship algorithms lock recurring revenue through predictive replenishment timing. Chewy anchors this model in the United States with automated pharmacy integration and veterinary diet credential verification systems.
Marketplace channels hold installed capacity. Direct-to-Consumer is rotating up the share rankings.
Customer Type:
Volume concentration varies sharply between dispersed household purchasers and institutional buyers with consolidated order profiles.
- Pet Owners:Millennial and Gen Z households drive mobile-first purchasing with subscription attach rates highest among urban apartment dwellers. Chinese platforms capture this segment through live-stream commerce integration that collapses education-to-transaction cycles.
- Breeders:Professional breeding operations purchase volume-formula nutrition and neonatal care supplies with price-sensitive procurement patterns.
- Shelters:Non-profit animal welfare organizations require donation-optimized pricing and bulk kibble configurations with tax-exempt documentation workflows.
- Veterinary Clinics:Licensed practitioners dispense therapeutic diets under FDA Center for Veterinary Medicine oversight. State-level veterinary board regulations mandate credential verification infrastructure that platforms must maintain for prescription product access.
Pet Owners hold installed capacity. Veterinary Clinics is rotating up the share rankings.
Delivery Mode:
Geography and infrastructure maturity dictate which fulfillment methods achieve viable unit economics.
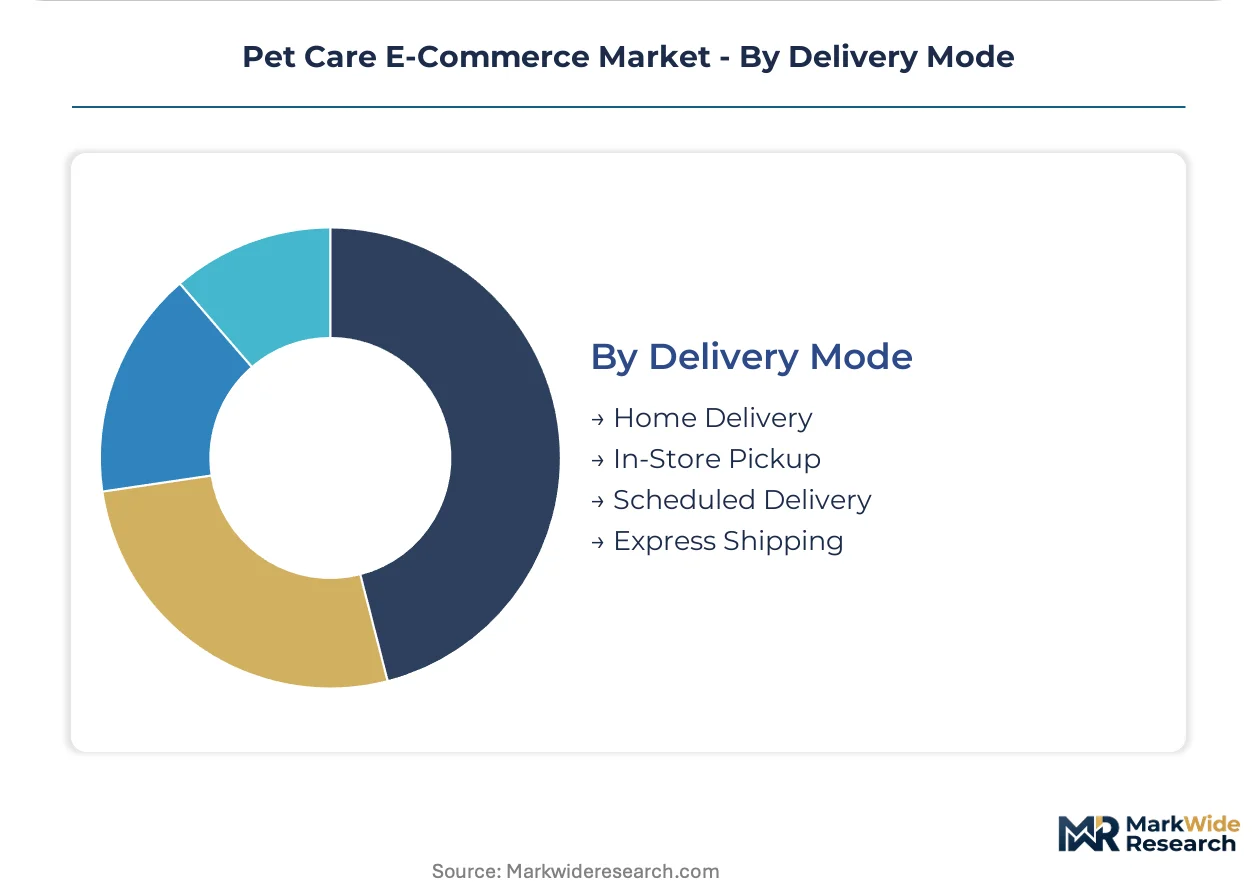
- Home Delivery:Standard parcel networks cover replenishment purchases with 2-3 day service levels. Temperature-controlled last-mile nodes enable fresh food subscriptions previously constrained by spoilage windows.
- In-Store Pickup:Click-and-collect bridges digital discovery with physical inventory verification. Rural underpenetration in India limits this option to tier-one cities with established retail footprints.
- Scheduled Delivery:Subscription algorithms synchronize shipment timing with consumption rates to reduce stockout risk and packaging waste.
- Express Shipping:Same-day and next-day service concentrates in Chinese same-city warehouse networks and dense US metropolitan corridors where logistics density supports premium pricing.
Home Delivery holds installed capacity. Scheduled Delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight anchors the United States as the regulatory benchmark shaping cross-border pet food safety protocols and prescription diet dispensing requirements worldwide.
United States
Millennial subscription adoption drives platform loyalty through auto-ship algorithms and automated pharmacy integration. State-level veterinary board regulations mandate licensed clinician verification for therapeutic diet access. The Boston-Seattle corridor concentrates cold chain fulfillment investment for fresh pet food startups.
China
Urban pet ownership rates and mobile-first commerce penetration accelerate faster than any comparable market. SAMR nutritional labeling standards and GB standards for imported pet food reshape cross-border seller compliance burdens. Shanghai and Hangzhou anchor same-city warehouse networks enabling live-stream commerce integration.
Germany
Pan-European specialty diet demand concentrates procurement volume for breed-specific nutrition formulations. EU F-Gas Regulation phase-down schedules accelerate refrigerated warehousing equipment replacement timelines. The Munich-Hamburg axis hosts temperature-controlled fulfillment nodes serving fresh food subscription services.
United Kingdom
Direct-to-consumer channel expansion among premium pet wellness brands captures first-party data ownership advantages. UK veterinary medicines directorate oversight of prescription product dispensing creates platform-level credential infrastructure requirements. Greater London logistics density supports same-day delivery service proliferation.
India
Mobile-first commerce infrastructure unlocks dispersed pet-owning households outside tier-one cities with vernacular-language interfaces. FSSAI pet food safety standards and import clearance protocols reshape cross-border product eligibility. Maharashtra and Karnataka concentrate fulfillment center investment for subscription service expansion.
Pet Care E-Commerce Market Key Industry Players
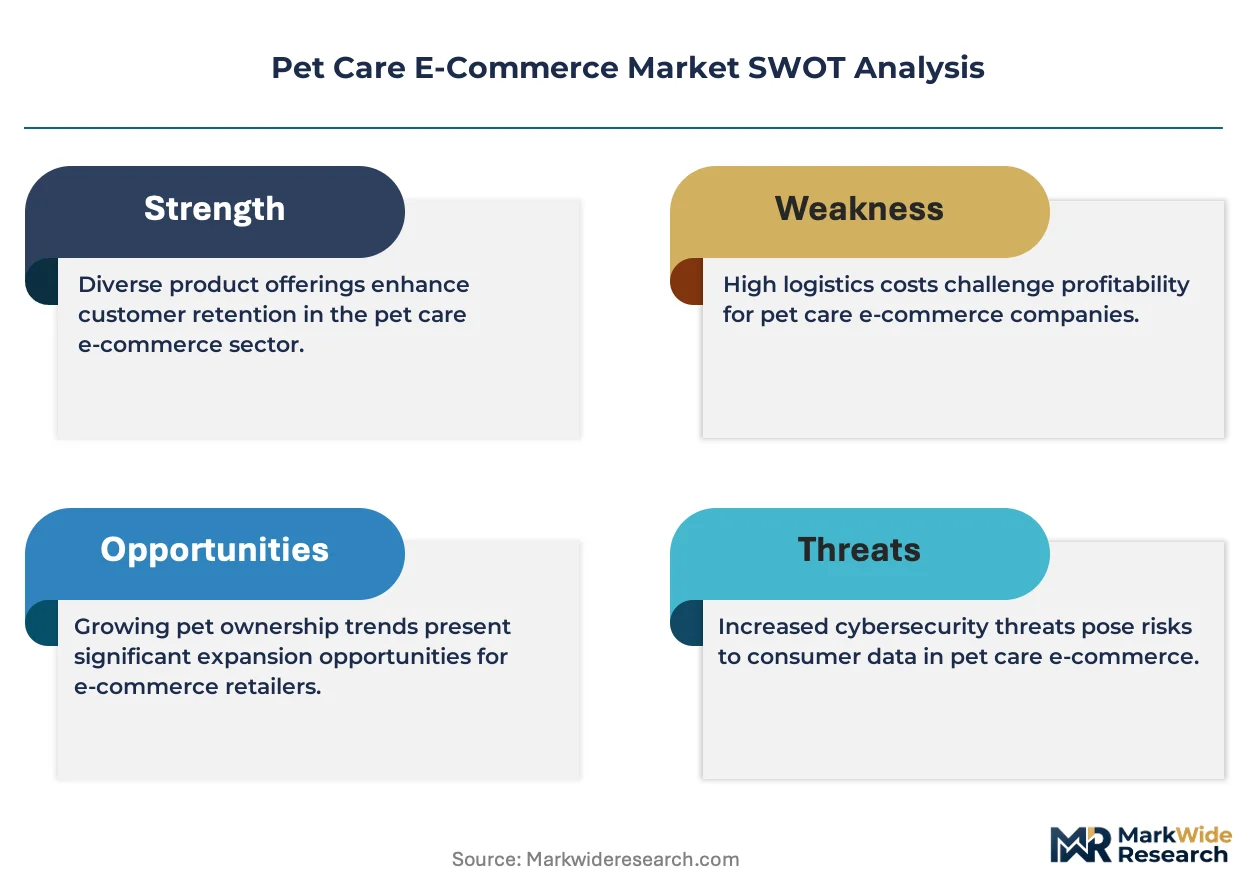
Specialty subscription platforms and general merchandise aggregators split the market between relationship-deepening auto-ship algorithms and logistics-density-driven replenishment capture. The vendor base concentrates around three strategic archetypes: veterinary-integrated pharmacy specialists, pan-regional specialty diet pure-plays, and diversified retail conglomerates with pet category verticals. M&A activity targets subscription technology stacks and cold chain fulfillment assets. Geographic expansion through same-city warehouse networks represents the dominant competitive move in high-growth Asian markets.
Within the veterinary-integrated tier, Chewy, Inc. and PetMed Express, Inc. exemplify platform models combining prescription verification infrastructure with automated replenishment systems. Amazon.com, Inc. occupies the scale-driven aggregator position leveraging Prime logistics density for general merchandise pet category dominance. Zooplus SE anchors the European specialty diet segment through pan-regional formulation expertise and breed-specific nutrition portfolio depth.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Chewy, Inc. |
| Petco Health and Wellness Co., Inc. |
| PetSmart, Inc. |
| Zooplus SE |
| Walmart |
| Target Brands, Inc. |
| BARK |
| PetMed Express, Inc. |
| Others |
Cost & Logistics Intelligence
Shanghai and Hangzhou's same-city warehouse networks concentrate fresh pet food fulfillment capacity, creating tiered pricing power based on spoilage-window compression and last-mile refrigeration density. Subscription auto-ship algorithms in these clusters lock customer lifetime value while commoditized dry kibble pricing erodes through marketplace aggregator competition.
Pricing Analysis
Urban Chinese corridors command 15-25% premiums over tier-two Indian markets for identical fresh diet formulations due to cold chain infrastructure gaps. Three-tier pricing structure across premium veterinary-exclusive, standard specialty, and economy private-label levels stratifies margin capture. Cost compression in dry kibble intensifies because Amazon and Walmart absorb logistics overhead through general merchandise density. Breeders and shelters exhibit highest price sensitivity, while millennial urban pet owners show lowest sensitivity to subscription bundling.
Supply Chain Analysis
Contract manufacturing for temperature-controlled pet nutrition concentrates among German cold-chain specialists and Chinese fresh-food co-packers serving pan-European and East Asian demand respectively. Raw material dependencies center on North American protein meal, Brazilian tallow, and Southeast Asian fish hydrolysate. Single-source vulnerability runs through FDA-registered rendering facilities for prescription diet base ingredients. Distribution runs through platform-owned micro-fulfillment nodes in dense metropolitan corridors, with rural India relying on third-party logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet care e-commerce sits in early-cycle expansion as live-stream commerce penetration and subscription algorithm maturity unlock household penetration rates previously constrained by veterinary intermediary friction.
For Market Incumbents: Insulate prescription diet margins by deepening veterinary telehealth integration and credential verification infrastructure before regulatory harmonization raises compliance barriers. Acquire cold chain fulfillment assets in tier-two Chinese cities to preempt fresh food subscription competition. Threat substitution from direct-to-consumer specialty brands demands first-party data ownership through proprietary app ecosystems rather than marketplace dependency. For New Entrants and Emerging Players: Rural Indian households outside Maharashtra and Karnataka represent the most penetrable entry point for vernacular-language mobile commerce platforms with simplified subscription onboarding. Veterinary clinic dispensing relationships in tier-two US cities offer white-space access through telehealth-adjacent wellness bundling rather than head-to-head marketplace competition. Go-to-market execution should anchor on regional influencer partnerships rather than paid search arbitrage. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription auto-ship algorithms and temperature-controlled last-mile networks compound customer switching costs and fulfillment density advantages. Target acquisition archetypes combine AI-driven dietary recommendation engines with established cold chain footprints. Monitor FDA Center for Veterinary Medicine telehealth guidance evolution as inflection signal for prescription platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Micro-Fulfillment Expansion | Temperature-controlled nodes in Hangzhou and Munich enable fresh diet subscriptions previously constrained by spoilage windows. |
| Veterinary Telehealth Integration | Remote consultation platforms capture prescription diet dispensing relationships under FDA Center for Veterinary Medicine oversight. |
| AI Dietary Recommendation Engine Development | Machine learning models processing breed-specific health data personalize nutrition plans at scale for millennial pet owners. |
| Vernacular Mobile Commerce Launch | Regional language interfaces unlock dispersed pet-owning households in tier-two Indian cities with limited English penetration. |
| Subscription Algorithm Acquisition | Predictive replenishment timing technology compresses customer acquisition costs and locks lifetime value through auto-ship systems. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with veterinary platform executives, cold chain logistics operators, subscription technology architects, and regulatory affairs specialists at FDA and SAMR; alongside secondary validation through customs trade databases, SEC 10-K filings of publicly traded pet retailers, AAFCO nutritional protocol documentation, and EU F-Gas Regulation compliance disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Forecast inputs considered product type segmentation across food, toys, accessories, and grooming categories; sales channel dynamics spanning direct-to-consumer, marketplace, and subscription service models; and customer type differentiation between pet owners, breeders, shelters, and veterinary clinics. CAGRs derived from regression analysis of historical subscription attach rates, urban pet ownership penetration curves, and mobile commerce adoption patterns across the projection horizon.
Practitioners should monitor SAMR import clearance protocol revisions and FDA telehealth guidance evolution for early signals of cross-border product eligibility shifts and prescription platform liability expansion. Quarterly review of cold chain equipment replacement timelines under EU F-Gas Regulation phase-down schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Supplement Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Dog Crate Furniture Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
North America Cat Food Market
Pet Care Products
Pet Tag Market
Pet Care Products
North America Pet Food Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Pet Treats and Chews Market