
 India Pet Food Market | 2026-2036
India Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
India Pet Food Market Outlook
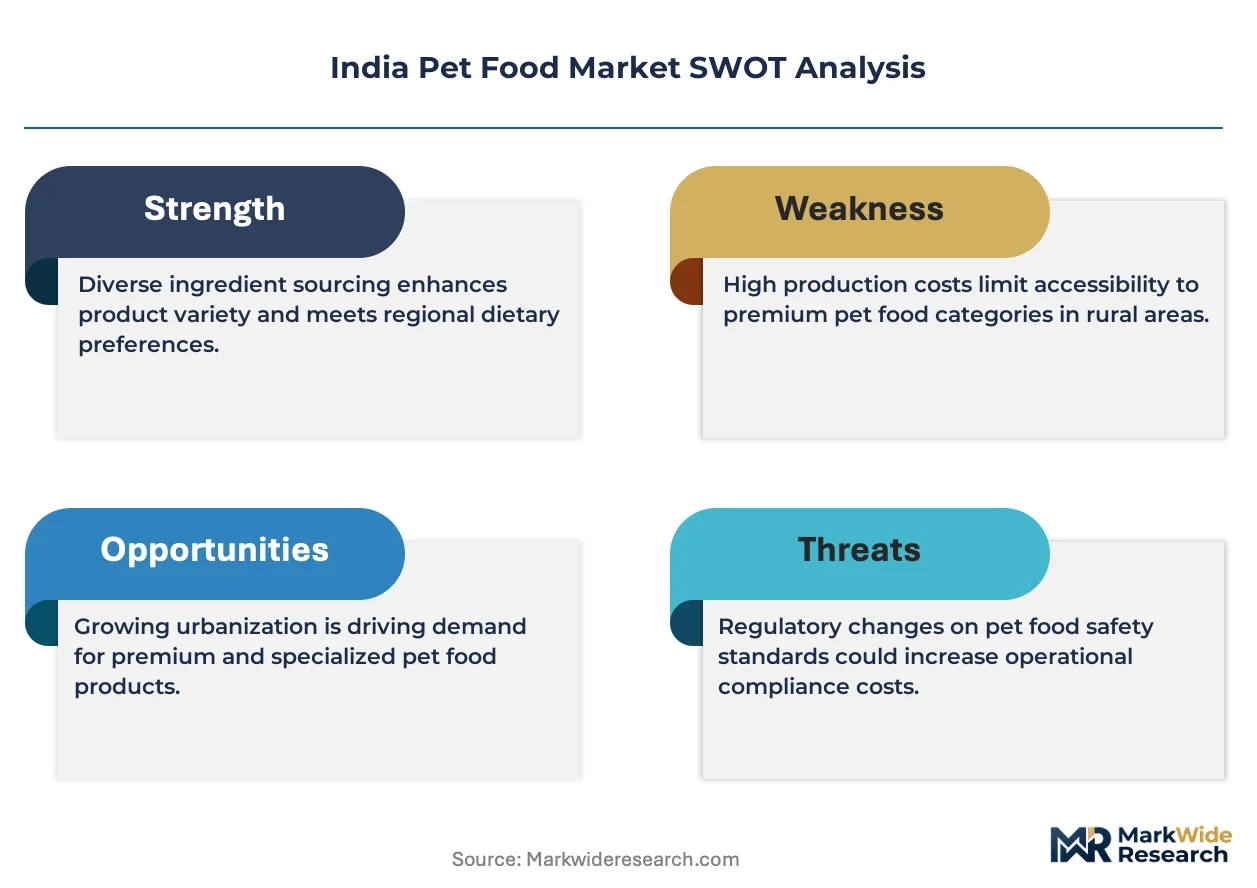
BIS pet food standards is shifting import compliance costs upward and forcing reformulation investments from new entrants. Mars, Incorporated leverages its veterinary nutrition R&D to sustain premium positioning across metros. Drools Pet Food Pvt. Ltd. anchors its competitive stance through backward integration into poultry protein sourcing. Godrej Pet Care competes on mass-market distribution density in tier-2 cities.
Pet food comprises nutritionally complete formulations manufactured through extrusion, canning, or baking processes, with protein content typically ranging from 18% to 32% depending on species-specific dietary requirements. The primary commercial purpose is to deliver standardized, shelf-stable nutrition that substitutes or supplements homemade feeding regimens. Dry food dominates volume throughput due to lower logistics costs and extended shelf stability, while organic options capture expanding margin pools among affluent urban consumers. Wet food occupies a specialized niche targeting palatability-sensitive senior animals and therapeutic dietary management.
FSSAI labeling mandates and BIS quality benchmarks shape product registration timelines and ingredient disclosure norms for both domestic producers and import license holders. CDSCO oversight extends to veterinary therapeutic diets, creating a dual-track regulatory pathway that segments functional nutrition from standard maintenance formulations. Stakeholders must monitor evolving PLI scheme eligibility for animal feed value chains and anticipate state-level veterinary department enforcement intensification.
Market Dynamics
BIS certification mandates for imported pet food formulations are restructuring competitive entry barriers, forcing foreign suppliers toward domestic manufacturing partnerships while accelerating local capacity investments.
Growth Catalysts
- Pet Humanization:Urban millennial households in Mumbai and Bengaluru treat companion animals as family members, driving premium nutrition demand and veterinary-grade ingredient sourcing.
- FSSAI Labeling Mandates:Stricter disclosure requirements for protein content and additive composition are professionalizing product quality benchmarks across the sector.
- Extrusion Technology Adoption:Domestic manufacturers deploying advanced thermal processing achieve shelf stability parity with imports while reducing per-unit logistics costs.
Market Restraints
- Poultry Protein Price Volatility:Feed-grade meat meal costs fluctuate with monsoon-dependent grain harvests, compressing margin predictability for mid-tier producers.
- Import Dependency for Specialty Additives:Taurine, omega fatty acid premixes, and therapeutic-grade vitamins concentrate supply in Southeast Asian chemical processors.
- Veterinary Therapeutic Diet Approval Bottlenecks:CDSCO dual-track oversight for functional nutrition extends registration timelines versus standard maintenance formulations.
Strategic Opportunities
- Tier-2 City Distribution Expansion:Underpenetrated markets in Pune, Hyderabad, and Ahmedabad present volume growth corridors as pet ownership spreads beyond metro cores.
- PLI Scheme Eligibility:Production-linked incentives for animal feed value chains could offset capital equipment costs for extrusion and packaging line upgrades.
- Wet Food Therapeutic Positioning:Palatability-sensitive senior dog nutrition and renal support formulations address gaps in veterinary prescription channels.
Industry Challenges
- Veterinary Nutritionist Talent Scarcity:Formulation science expertise concentrates with multinational R&D centers, constraining indigenous product development pipelines.
- Cold Chain Infrastructure Gaps:Wet food distribution requires temperature-controlled logistics that remain underdeveloped outside major urban corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pet Food Market |
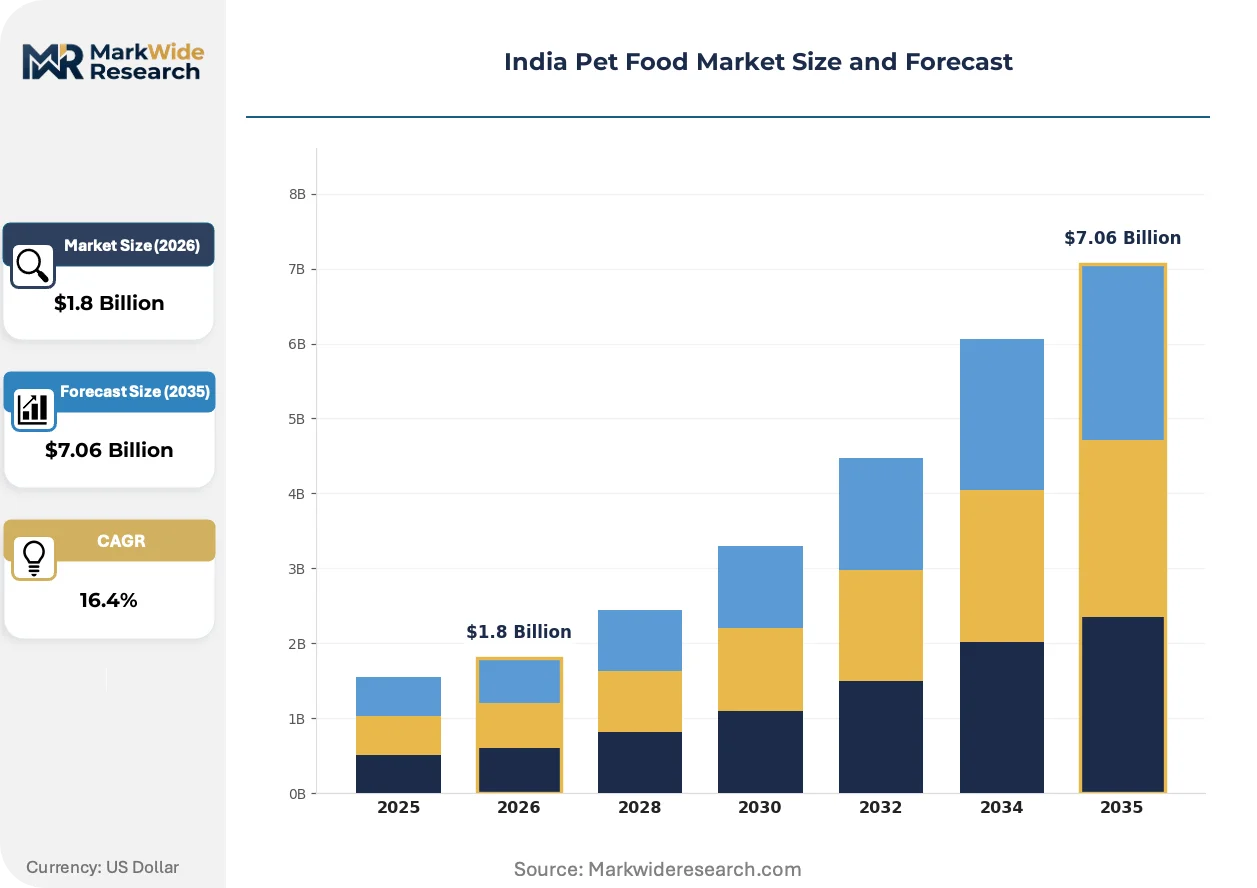
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Organic Options Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Online Stores, Pet Shops, Supermarkets, Veterinary Clinics Price Tier: Premium, Mid-Range, Economy, Value Packs |
| Companies Covered | Charoen Pokphand Group, Godrej Pet Care, Mars, Incorporated, Mankind Pharma, Reliance Consumer Products, Nestle S.A. (Purina), Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.), Tata 1mg, Drools Pet Food Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pet Food Market Strategic Shifts
Product formulation science and regulatory disclosure frameworks are converging to reshape how manufacturers compete on transparency, nutritional specificity, and supply chain traceability.
Extrusion-cooking with precise thermal profiling is unifying protein digestibility optimization with pathogen inactivation in a single continuous process. Premium dry kibble producers in Gujarat and Maharashtra are retrofitting production lines with real-time moisture and density sensors. This convergence is compressing the quality gap between domestic output and imported benchmarks while enabling batch-level traceability compliance.
FSSAI's evolving ingredient disclosure norms are mandating granular reporting of meat-by-product percentages and synthetic additive categories. Domestic manufacturers face reformulation investments to meet transparency thresholds that exceed current import label requirements. Tier-1 urban retailers and veterinary clinics are prioritizing SKUs with full supply chain documentation, shifting procurement criteria toward verifiable provenance.
Subscription-based replenishment models are displacing traditional retail stocking cycles among affluent households in Bengaluru and Gurugram. Direct-to-consumer platforms bundle veterinary diet consultations with automated delivery scheduling, capturing recurring revenue streams. This channel innovation concentrates customer data ownership with platform operators, pressuring conventional distributor margins.
India Pet Food Market Segmentation
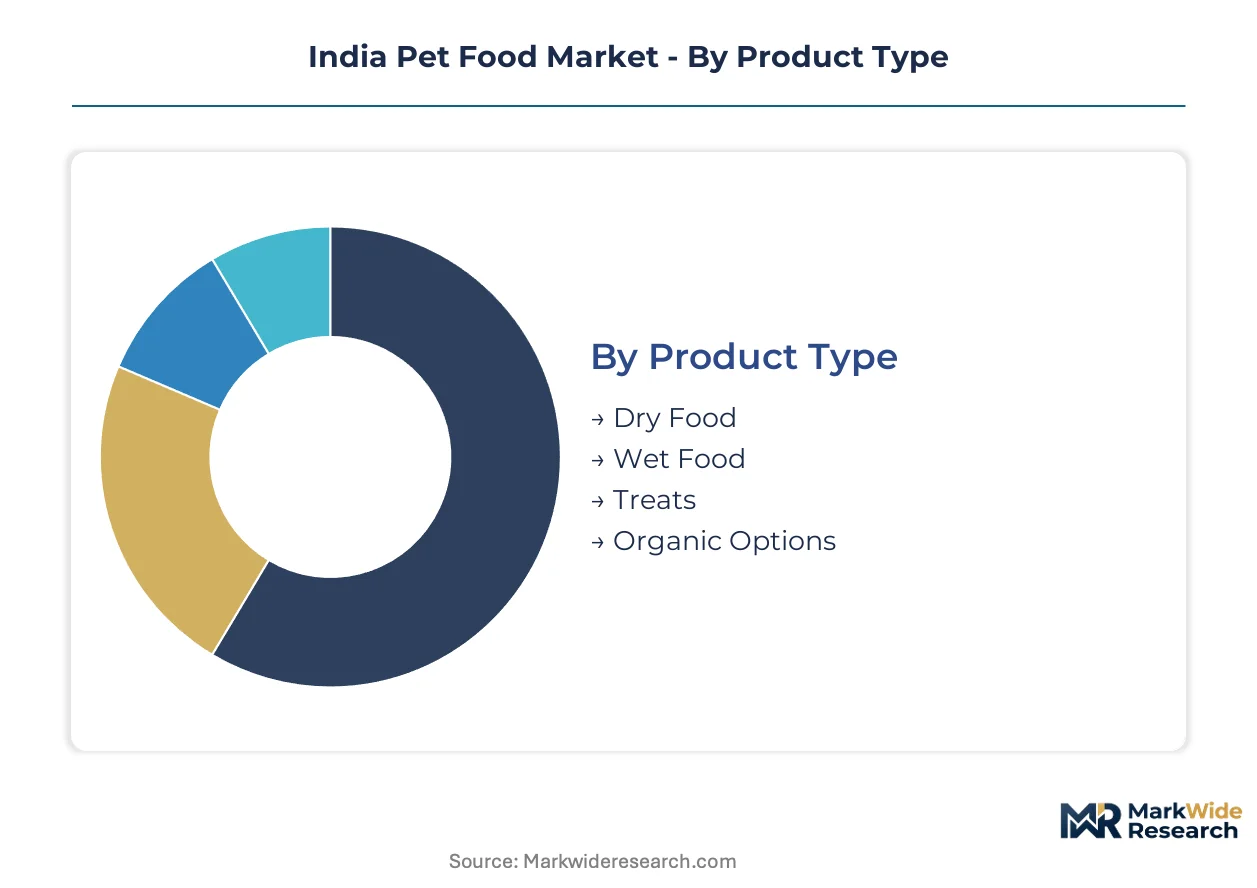
Segmentation in the India pet food market reveals how regulatory compliance burdens, distribution infrastructure, and consumer purchasing power stratify across product categories. BIS certification requirements and FSSAI disclosure mandates create divergent entry barriers that reshape competitive positioning within each segment cluster.
Product Type:
BIS certification applies uniformly across all product types, though dry food formulations face streamlined approval pathways compared to wet food's extended microbiological testing protocols. Organic options trigger additional scrutiny under FSSAI's additive disclosure frameworks.
- Dry Food:Extrusion-processed kibble with 18-32% protein content achieves shelf stability through precise thermal profiling. Demand concentrates in Mumbai and Bengaluru metro corridors where logistics efficiency supports bulk purchasing by urban millennial households facing space constraints for storage.
- Wet Food:Canned or pouch formats with higher moisture content target palatability-sensitive animals and therapeutic dietary management. Tier-1 veterinary clinics in Delhi and Chennai drive prescription channel adoption, though cold chain infrastructure gaps outside major urban corridors constrain distribution reach.
- Treats:Functional and reward-based formulations occupy a discretionary purchase niche with lower regulatory scrutiny than complete diets.
- Organic Options:Synthetic additive-free positioning commands margin premiums among affluent consumers seeking supply chain traceability documentation.
Dry Food sits at the top of the volume ranking, with Organic Options climbing the fastest.
Animal Type:
Species-specific nutritional requirements segment manufacturing complexity and veterinary oversight intensity, with canine formulations dominating production line investments.
- Dogs:Complete and balanced formulations span puppy growth, adult maintenance, and senior life stages with tailored protein-fat ratios. Maharashtra and Karnataka households account for disproportionate category spending as pet humanization accelerates in these high-income states.
- Cats:Obligate carnivore formulations require higher protein density and taurine supplementation, creating import dependency for specialty amino acid premixes.
- Birds:Seed and pellet blends serve avian companion species with distinct beak morphology and foraging behavior requirements.
- Small Mammals:Rodent and lagomorph formulations address fiber-centric digestive needs with limited domestic manufacturing specialization.
Dogs generate the dominant revenue share, with Cats expanding most quickly among urban apartment dwellers.
Distribution Channel:
Channel selection determines customer data ownership, margin capture, and regulatory traceability obligations under FSSAI's batch-level documentation requirements.
- Online Stores:Direct-to-consumer platforms bundle subscription replenishment with veterinary consultation services. Gurugram and Bengaluru tech-corridor households drive adoption, concentrating recurring revenue streams with platform operators rather than traditional distributors.
- Pet Shops:Specialty retailers provide tactile product evaluation and species-specific guidance, anchoring premium brand presence in high-footfall metro locations.
- Supermarkets:Mass-market shelf space in tier-2 cities like Pune and Ahmedabad enables economy-tier volume penetration.
- Veterinary Clinics:Prescription diet dispensing requires CDSCO registration for therapeutic claims, creating a dual-track regulatory pathway.
Online Stores command the steepest expansion trajectory, with Veterinary Clinics maintaining the highest margin per unit.
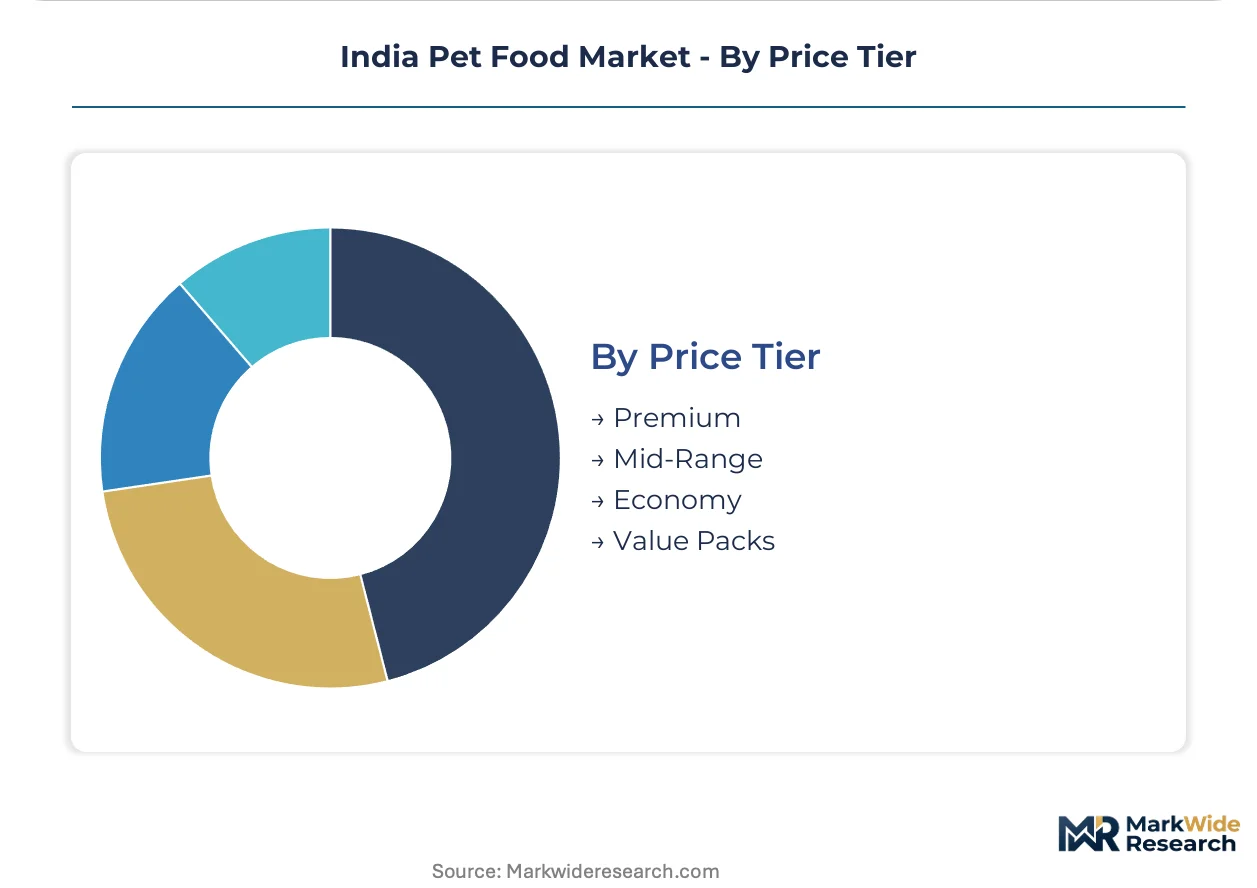
Price Tier:
Pricing stratification aligns with ingredient sourcing transparency, protein quality grades, and packaging sophistication rather than manufacturing scale economies alone.
- Premium:Human-grade protein inputs, single-source traceability, and veterinary nutritionist formulation oversight define positioning. Mumbai and Delhi NCR households absorb price premiums for imported or import-parity domestic alternatives.
- Mid-Range:Balanced cost-quality positioning leverages domestic extrusion capabilities with moderate protein density specifications.
- Economy:Feed-grade meat meal and grain-forward formulations serve price-sensitive first-time pet owners in emerging ownership markets.
- Value Packs:Bulk sizing reduces per-kilogram cost for multi-pet households and institutional buyers such as breeding operations.
Premium tier captures the highest value per ton, with Mid-Range gaining share fastest as quality awareness spreads beyond metro cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet food manufacturing in India traces its commercial lineage to the early 2000s, when multinational entrants established formulation standards that domestic players subsequently adopted. The industry now distributes through state-level veterinary networks and metro-centric retail channels.
Maharashtra
Mumbai households drive premium kibble consumption through subscription-based replenishment models. FSSAI labeling mandates require granular protein disclosure for all formulations sold through Maharashtra's retail channels. Pune anchors emerging demand as veterinary clinic networks expand into tier-2 corridors.
Karnataka
Bengaluru's tech-corridor households concentrate online pet food purchasing through direct-to-consumer platforms. BIS certification requirements for imported formulations create compliance friction for foreign suppliers accessing Karnataka markets. The city's veterinary nutritionist talent pool supports indigenous product development pipelines.
Delhi-NCR
Affluent households in Gurugram absorb price premiums for imported or import-parity domestic alternatives. CDSCO oversight of veterinary therapeutic diets segments prescription channels from standard maintenance formulations. The region's cold chain infrastructure supports wet food distribution to veterinary clinics.
Gujarat
Ahmedabad and Surat manufacturing clusters deploy advanced extrusion technology with real-time moisture sensors. PLI scheme eligibility for animal feed value chains incentivizes capital equipment upgrades across Gujarat production facilities. The state's poultry protein sourcing density enables backward integration strategies.
Tamil Nadu
Chennai's veterinary prescription channels drive therapeutic diet adoption among palatability-sensitive senior animals. State-level veterinary department enforcement intensifies batch-level traceability documentation for retail formulations. Domestic manufacturers in the region achieve shelf stability parity with imported benchmarks.
India Pet Food Market Competitive Environment
The competitive structure tilts toward multinational nutrition science specialists with captive R&D infrastructure. Tiered player concentration separates veterinary-grade formulation capabilities from mass-market distribution scale. Three archetypes dominate: multinational nutrition science platforms, domestic integrated protein processors, and pharmaceutical-channel entrants. Capacity expansion and strategic partnerships represent the dominant competitive moves as foreign suppliers navigate BIS certification requirements.
Among multinational nutrition science platforms, Mars, Incorporated and Nestlé S.A. occupy positions defined by veterinary nutrition R&D depth. Domestic integrated specialists exemplified by Drools Pet Food Pvt. Ltd. anchor competitive stances through upstream control over poultry protein sourcing. Pharmaceutical-channel entrants including Mankind Pharma and Tata 1mg represent a convergence between human health distribution infrastructure and pet therapeutic nutrition.
| Leading Market Players |
|---|
| Charoen Pokphand Group |
| Godrej Pet Care |
| Mars, Incorporated |
| Mankind Pharma |
| Reliance Consumer Products |
| Nestle S.A. (Purina) |
| Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.) |
| Tata 1mg |
| Drools Pet Food Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Veterinary nutritionist talent concentration in Bengaluru and Mumbai generates labor-cost differentials that widen pricing-tier spreads between premium formulations and mass-market alternatives. Manufacturers with captive R&D capabilities absorb specialist salary premiums into premium-tier pricing, while mid-tier producers in Gujarat and Maharashtra compete on extrusion efficiency and poultry protein sourcing density.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by protein quality grade and FSSAI disclosure compliance depth. Price differentiation hinges on human-grade versus feed-grade meat meal inputs and batch-level traceability documentation. Pricing pressure stems from poultry protein cost volatility tied to monsoon-dependent grain harvests, compressing margin predictability for mid-tier producers. Economy-tier buyers in tier-2 cities exhibit highest price sensitivity, while Mumbai and Delhi NCR households absorb premiums for veterinary-grade formulation oversight.
Supply Chain Analysis
Direct-to-veterinary-clinic channels handle therapeutic diet demand, while subscription-based platforms capture affluent household replenishment in Bengaluru and Gurugram. Raw material sourcing draws from domestic poultry protein clusters in Gujarat and Maharashtra, supplemented by Southeast Asian imports for taurine and omega fatty acid premixes. Supply chain risk centers on import dependency for specialty amino acid premixes concentrated with Southeast Asian chemical processors. Distribution runs through state-level veterinary networks, metro-centric retail channels, and emerging direct-to-consumer platforms with automated delivery scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India pet food market functions as a geographic-arbitrage play where BIS certification requirements for imported formulations create compliance-cost advantages for domestic manufacturers versus foreign suppliers.
For Market Incumbents: Deepen backward integration into poultry protein sourcing to offset feed-grade meat meal price volatility and secure margin predictability. Expand extrusion capacity in Gujarat manufacturing clusters to exploit PLI scheme eligibility for animal feed value chains. Defend against pharmaceutical-channel entrants by locking veterinary clinic dispensing relationships through CDSCO-registered therapeutic diet portfolios. For New Entrants and Emerging Players: The mid-range price-point gap between Mars Incorporated premium positioning and Godrej Pet Care economy-tier distribution presents white-space opportunity. Target tier-2 city expansion in Pune, Hyderabad, and Ahmedabad where pet ownership spreads beyond metro cores with limited incumbent presence. Pursue wet food therapeutic positioning for palatability-sensitive senior animals, leveraging underdeveloped cold chain infrastructure as a barrier to multinational replication. For Investors and Strategic Acquirers: Domestic pharmaceutical distributors with human health infrastructure represent the most active acquirer category in this space, converging toward pet therapeutic nutrition. Long-term viability hinges on capturing subscription-based customer data ownership as platform operators displace traditional distributors. Monitor PLI scheme eligibility announcements for animal feed value chains as inflection indicator for capital equipment upgrade cycles and domestic capacity expansion trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Poultry Protein | Drools Pet Food anchors competitive positioning through captive supply of feed-grade meat meal inputs. |
| CDSCO Therapeutic Diet Registration | Dual-track regulatory pathway segments functional nutrition from standard maintenance formulations in prescription channels. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models concentrate recurring revenue streams and customer data ownership with platform operators. |
| Extrusion Technology Upgrade | Real-time moisture and density sensors enable batch-level traceability compliance with FSSAI disclosure mandates. |
| Tier-2 City Distribution Expansion | Underpenetrated markets in Pune and Hyderabad present volume growth corridors as pet ownership spreads. |
Study Parameters
Bottom-up pet food consumption modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with veterinary nutritionists, pet shop proprietors, category buyers at online platforms, and poultry protein procurement managers were cross-validated against BIS certification databases, FSSAI labeling registries, CDSCO therapeutic diet filings, and customs import records for specialty additive premixes. This triangulation ensures demand-side estimates align with supply-side production realities across Maharashtra, Karnataka, and Gujarat manufacturing clusters.
Historical trendline analysis of urban pet ownership penetration, protein input cost indices, and channel shift velocities informed projection framework construction. Segmentation modeling spans product type, animal species, distribution channel, and price tier dimensions, with regional regulatory intensity and veterinary clinic network density incorporated as India-specific forecast inputs. CAGRs were derived through exponential smoothing of segment-level volume trajectories across the analysis window.
Caveats apply where BIS certification requirement amendments, FSSAI disclosure mandate expansions, or PLI scheme eligibility revisions could materially shift the outlook. Forecasts reflect assumptions regarding poultry protein price stability, cold chain infrastructure development pace, and veterinary nutritionist talent pipeline expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Collars Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Pet Stairs Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Cat Litter Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Pet Grooming Gloves Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
UK Pet Diet Market