
 Pet Relaxants Market | 2026-2036
Pet Relaxants Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Relaxants Market Analytics
Veterinary pharmacist expertise is collapsing across rural markets, constraining prescription-grade relaxant access while unlocking demand for over-the-counter alternatives. Zoetis Inc. leverages its veterinary channel dominance to sustain distribution advantages in clinic-directed formulations. Ceva Santé Animale anchors its position through pheromone-based technology leadership, while Virbac competes via behavioral health specialization across European and Latin American markets.
Pet relaxants comprise functional supplements and therapeutics formulated with active compounds such as L-Theanine, valerian root, chamomile extracts, or CBD to modulate stress responses in companion animals, typically administered through chewable matrices, transdermal sprays, or tablet delivery systems designed for species-specific palatability and bioavailability. Calming chews occupy the largest volume position due to owner convenience and palatability engineering, while CBD-infused formulations represent the fastest-expanding active ingredient segment despite regulatory fragmentation across jurisdictions. Spray formulas command premium positioning in travel and environmental stress applications, whereas herbal supplements sustain mature demand among holistic-oriented consumers seeking non-synthetic pathways.
The FDA Center for Veterinary Medicine evaluates safety and labeling claims for animal supplements, while the USDA monitors hemp-derived ingredient sourcing under the Farm Bill framework, and state-level veterinary medical boards impose dispensing restrictions that shape channel access. The EU's Novel Food Catalogue and member state veterinary product classifications create parallel compliance architectures for exporters. Stakeholders must monitor evolving cannabinoid policy thresholds and veterinary telehealth expansion to anticipate channel disruption and formulation investment priorities.
Market Dynamics
Veterinary telehealth expansion is compressing traditional clinic visit patterns while simultaneously fragmenting prescription authority, forcing relaxant manufacturers to recalibrate channel strategies around direct-to-consumer delivery systems and remote consultation protocols.
Growth Catalysts
- FDA Center for Veterinary Medicine pathway clarification:Draft guidance on hemp-derived ingredients in animal supplements is clarifying compliance boundaries, reducing formulation uncertainty for manufacturers targeting the United States market.
- Pheromone synthesis advances:Microencapsulation technologies are extending active release durations in environmental diffusers, improving efficacy metrics for veterinary behaviorists prescribing adjunctive anxiety management.
- Germany:The country's national pharmaceutical regulator has streamlined veterinary health product notifications, accelerating market entry timelines for botanical-based calming formulations.
Market Restraints
- CBD input cost volatility:Hemp biomass pricing fluctuates with agricultural commodity cycles, compressing margin stability for mid-tier manufacturers dependent on cannabinoid active ingredients.
- European Union Novel Food Catalogue fragmentation:Member state divergences in cannabinoid classification create parallel compliance costs, constraining single-formulation scale economies for exporters.
- Veterinary pharmacist scarcity:Rural United States markets face collapsing prescription-grade access, limiting clinic-directed therapeutic penetration outside metropolitan corridors.
Strategic Opportunities
- Brazil:ANVISA's evolving veterinary product framework is creating first-mover windows for pheromone-based formulations in Latin America's largest companion animal market.
- Subscription-based replenishment channels:Direct-to-consumer platforms are capturing recurring revenue from chronic anxiety management cases, displacing episodic retail purchasing patterns.
- Sensor-enabled dosing compliance:Integration of connected devices with chewable matrices enables outcome tracking that satisfies emerging pet insurer wellness program requirements.
Industry Challenges
- Veterinary behaviorist certification bottlenecks:The American College of Veterinary Behaviorists maintains stringent credentialing timelines, constraining prescriber pool expansion for prescription-grade therapeutics.
- Cross-jurisdiction label claim harmonization:Divergent substantiation standards between the USDA Farm Bill framework and state veterinary medical boards force redundant clinical documentation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Relaxants Market |
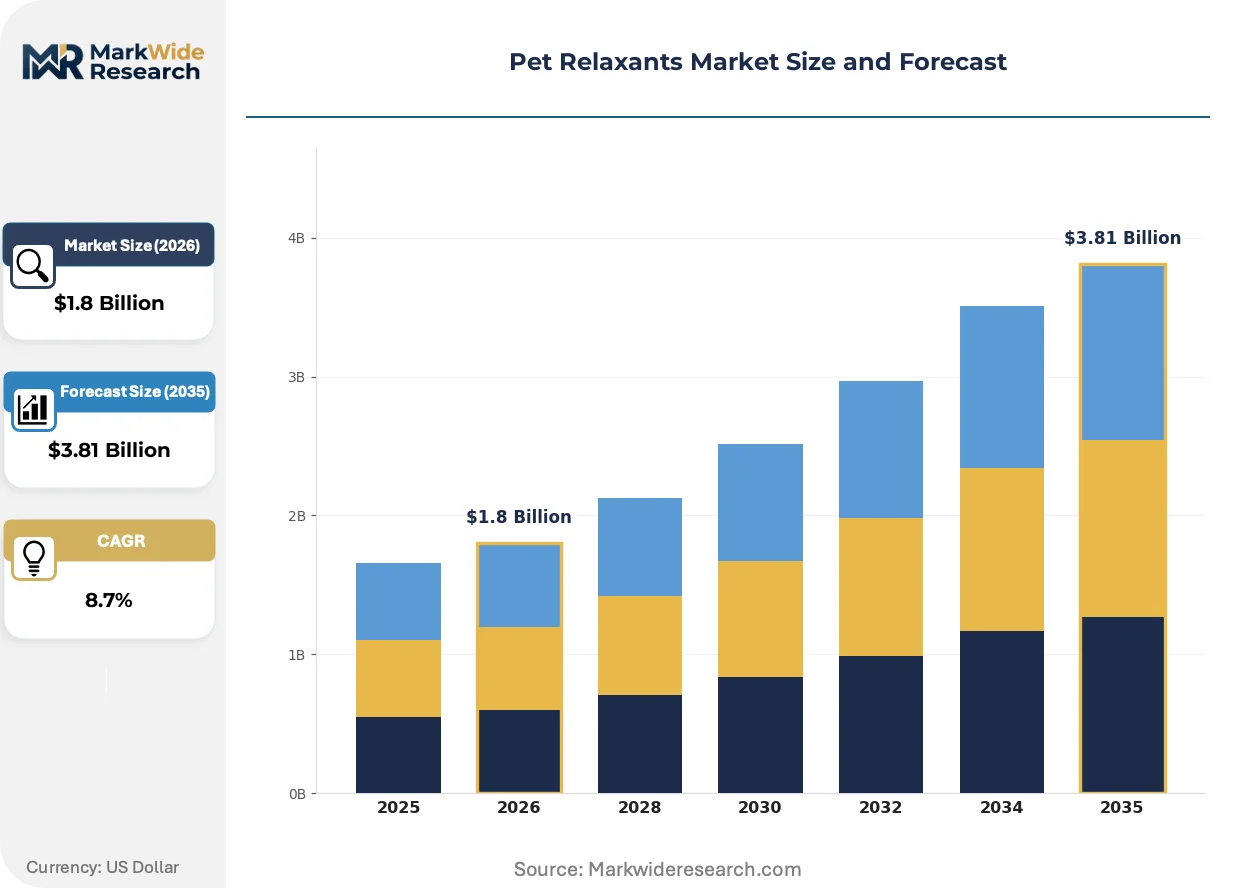
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calming Chews, Spray Formula, Tablets, Herbal Supplements Active Ingredient: Valerian Root, Chamomile, L-Theanine, CBD Pet Type: Dogs, Cats, Rabbits, Guinea Pigs Distribution Channel: Online Retail, Pet Stores, Veterinary Clinics, Supermarkets |
| Companies Covered | Zoetis Inc., Ceva Santé Animale, Nestlé Purina PetCare, Virbac, PetHonesty, Zesty Paws, THUNDERWORKS, Vetoquinol, PetIQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Relaxants Market Evolving Landscape
Formulation science is fragmenting around bioavailability optimization, with delivery mechanism innovation outpacing active ingredient discovery. Manufacturers now compete on pharmacokinetic performance rather than novel compound sourcing.
Microencapsulation technology for pheromone active ingredients is bifurcating the environmental application segment. Veterinary behaviorists in metropolitan United States markets are adopting extended-release diffusers at accelerating rates. This delivery sophistication is compressing demand for spray-based alternatives while enabling premium pricing for sustained-efficacy formats.
The EU Green Deal's sustainable packaging mandates are forcing container redesign investments across export-oriented manufacturers. Biodegradable blister packs and post-consumer recycled bottles now constitute baseline compliance rather than differentiation. Botanical supplement categories face the steepest cost pass-through pressures given their premium positioning and environmentally conscious buyer demographics.
Subscription replenishment models are displacing retail shelf purchasing for chronic-use calming products. Direct-to-consumer platforms capture recurring revenue from separation anxiety and noise phobia cases. This shift concentrates most visibly in United States urban markets where veterinary telehealth adoption has normalized remote prescription workflows.
Pet Relaxants Market Segmentation
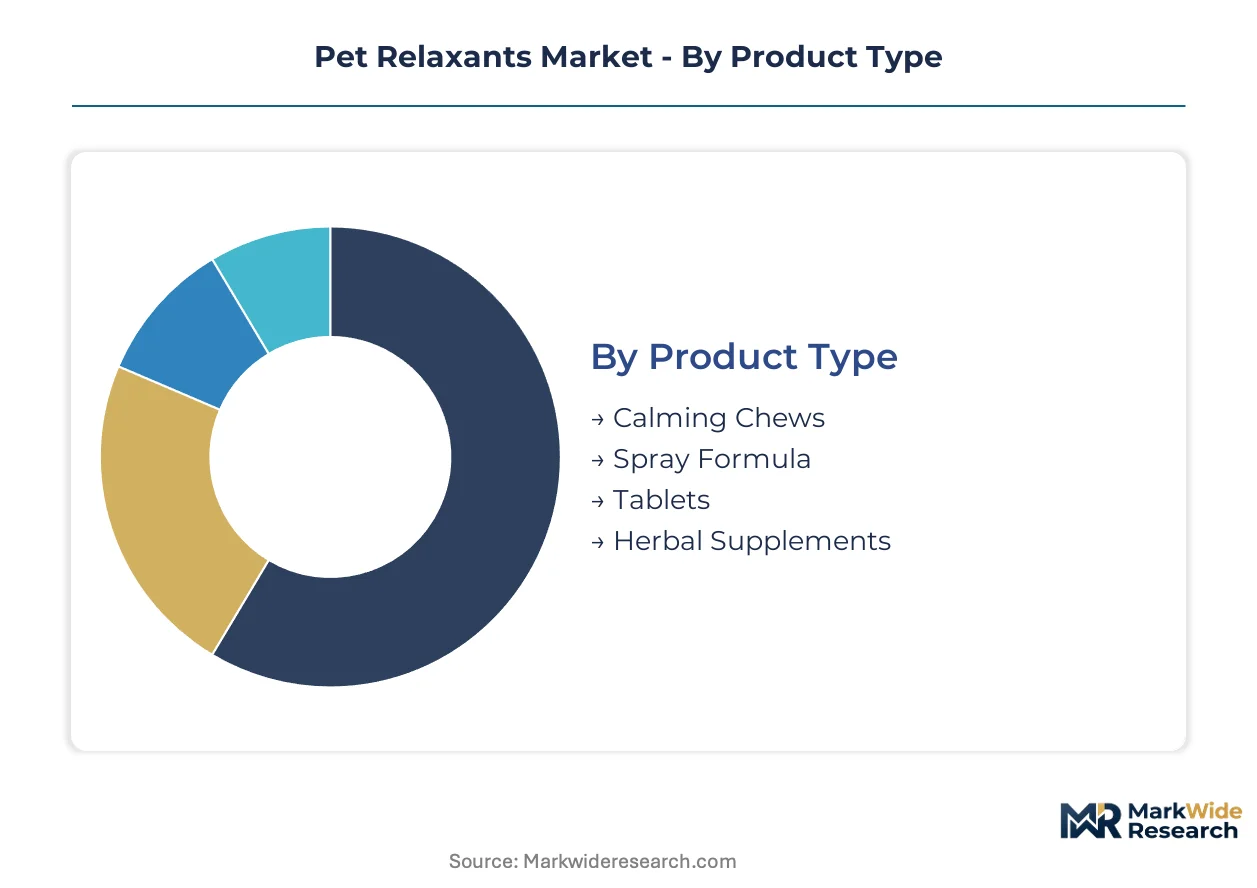
Pet relaxant manufacturers calibrate formulation investments and channel partnerships around distinct consumption patterns across delivery formats, species physiology, and purchase occasions. Segmentation discipline separates volume-driven mass market plays from premium therapeutic positioning.
Product Type:
Margin pools concentrate in formats that solve administration friction for pet owners while enabling dose precision for veterinary prescribers.
- Calming Chews:Palatable soft matrices incorporate active compounds into meat-flavored bases with engineered dissolution profiles for gastric absorption. Demand concentrates in United States metropolitan households where convenience premiums offset higher per-dose costs versus alternatives. Veterinary behaviorists favor chews for chronic anxiety cases requiring consistent compliance.
- Spray Formula:Transdermal and environmental application systems deliver pheromone or botanical actives through atomized dispersion. Travel and relocation stress applications in Germany and France sustain premium positioning despite shorter effective duration versus chewable formats. Microencapsulation advances are extending release profiles in next-generation formulations.
- Tablets:Compressed dose units with enteric coatings protect acid-labile actives through gastric passage. Compact packaging suits veterinary clinic dispensing protocols.
- Herbal Supplements:Multi-botanical complexes target holistic-oriented owners through non-synthetic positioning. United States natural channel retailers capture this demand segment.
The dominant share belongs to Calming Chews, while Spray Formula is closing the gap fastest through pheromone technology advances.
Active Ingredient:
Ingredient selection determines regulatory pathway complexity and manufacturing cost structure across jurisdictions.
- CBD:Hemp-derived cannabinoid formulations face bifurcated compliance between USDA Farm Bill sourcing requirements and state veterinary medical board dispensing restrictions. United States direct-to-consumer platforms capture demand despite FDA Center for Veterinary Medicine claim limitations. Agricultural commodity cycles introduce input cost volatility that compresses mid-tier manufacturer margins.
- L-Theanine:Amino acid isolates from green tea extracts modulate cortical excitability without sedation. Japanese and South Korean markets favor this pathway given established nutraceutical supply chains and clearer regulatory standing versus cannabinoid alternatives.
- Valerian Root:Traditional botanical sedative with established veterinary pharmacopeia recognition. European Union Novel Food Catalogue classifications create notification burdens for concentrated extracts.
- Chamomile:Flavonoid-rich flower extracts target mild stress modulation with broad species tolerance. Mature demand in holistic channels limits growth acceleration.
CBD commands attention for expansion trajectory despite regulatory friction, while L-Theanine offers the cleanest compliance pathway for multi-jurisdiction scale.
Pet Type:
Species-specific physiology dictates formulation bioavailability requirements and palatability engineering priorities.
- Dogs:Canine anxiety disorders including separation distress and noise phobia drive the largest absolute volume. Chewable matrices with meat-based flavor systems achieve highest compliance rates. United States pet humanization trends intensify spending on chronic behavioral management.
- Cats:Feline stress responses concentrate in environmental and social disruption contexts. Pheromone-based environmental applications outperform oral administration given feline taste sensitivity. European veterinary behaviorists prescribe adjunctive diffuser protocols at higher rates than North American counterparts.
- Rabbits:Lagomorph gastrointestinal sensitivity restricts active ingredient selection to low-residue botanicals. Exotic veterinary specialists drive prescription authority.
- Guinea Pigs:Small rodent metabolic rates require micro-dose precision rarely supported by standard formulation strengths. Compounding pharmacies capture this niche.
Dogs retain volume leadership by substantial margin, though Cats demonstrate the steepest expansion trajectory through pheromone delivery advances.
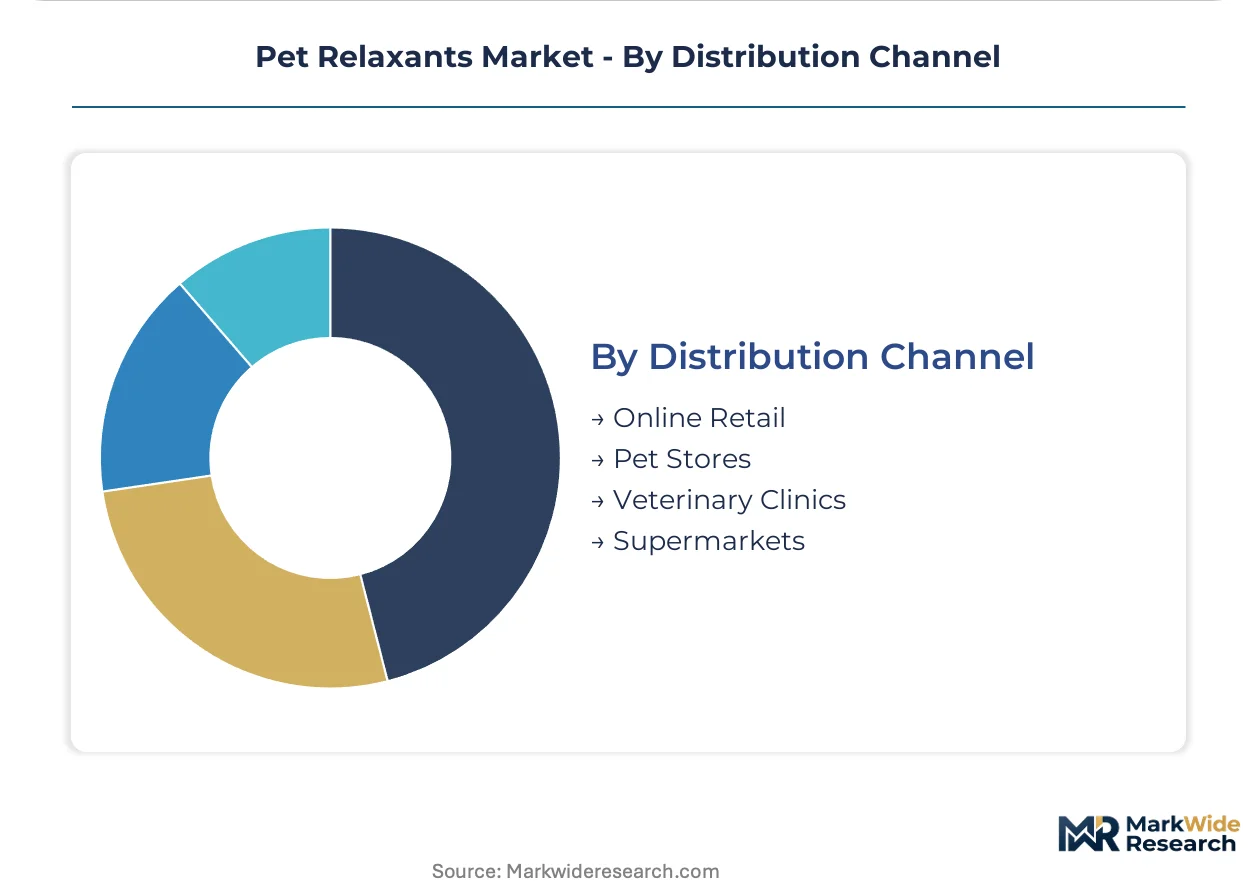
Distribution Channel:
Channel selection shapes customer acquisition economics and prescription authority requirements.
- Veterinary Clinics:Clinic-directed dispensing captures prescription-grade therapeutics and behaviorist-recommended supplements. Rural United States markets face access constraints from collapsing veterinary pharmacist availability.
- Online Retail:Direct-to-consumer platforms capture subscription replenishment demand for chronic-use cases. United States urban markets normalize telehealth prescription workflows that enable remote fulfillment.
- Pet Stores:Mass specialty retailers merchandise over-the-counter calming products with trained staff consultation. Premium positioning competes with convenience-oriented online alternatives.
- Supermarkets:Mass merchandisers stock entry-price botanical supplements with limited staff guidance. Price compression intensifies in this channel.
Veterinary Clinics maintain the highest margin per transaction, while Online Retail is gaining share fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine draft guidance on hemp-derived ingredients is reshaping formulation standards across the United States, while veterinary telehealth adoption accelerates remote prescription workflows in metropolitan corridors.
United States
Pet humanization trends and premium wellness spending intensify demand for behavioral health services. FDA Center for Veterinary Medicine oversight of CBD and hemp-derived ingredients creates compliance boundaries that reduce formulation uncertainty. Veterinary clinics in New York and Los Angeles expand behavioral health service lines, driving adoption among companion animal owners.
Germany
The national pharmaceutical regulator has streamlined veterinary health product notifications, accelerating market entry timelines for botanical-based calming formulations. EU Green Deal sustainable packaging mandates force container redesign investments across export-oriented manufacturers. Berlin and Munich veterinary behaviorists prescribe adjunctive diffuser protocols at higher rates than North American counterparts.
United Kingdom
Veterinary telehealth expansion fragments prescription authority while compressing traditional clinic visit patterns. The Veterinary Medicines Directorate maintains stringent dispensing restrictions that shape channel access for prescription-grade therapeutics. London metropolitan households drive convenience premiums for palatable soft matrices with engineered dissolution profiles.
Brazil
ANVISA's evolving veterinary product framework creates first-mover windows for pheromone-based formulations in Latin America's largest companion animal market. Agricultural commodity cycles introduce input cost volatility for hemp biomass dependent manufacturers. São Paulo veterinary channels capture premium positioning for chronic anxiety management cases.
Japan
Established nutraceutical supply chains and clearer regulatory standing favor L-Theanine amino acid isolates over cannabinoid alternatives. METI standards shape quality benchmarks for botanical supplement imports. Tokyo and Osaka metropolitan markets demonstrate accelerating subscription replenishment adoption for separation anxiety cases.
Pet Relaxants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with pheromone synthesis specialists commanding premium positioning while mass-market supplement manufacturers compete on scale economies. The vendor base stratifies across three tiers: multinational veterinary pharmaceutical conglomerates with clinic channel dominance, direct-to-consumer wellness brands with subscription platform infrastructure, and regional botanical specialists with natural channel retail relationships. Dominant competitive moves include strategic partnerships with veterinary telehealth platforms and portfolio diversification into sensor-enabled dosing compliance systems.
Within the multinational pharmaceutical tier, Zoetis Inc. and Ceva Santé Animale occupy positions that exemplify divergent technology pathways—veterinary channel distribution scale versus pheromone-based environmental application leadership. Virbac represents the behavioral health specialization archetype across European and Latin American markets. These three companies anchor the competitive structure through distinct strategic postures rather than overlapping capability investments.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Ceva Santé Animale |
| Nestlé Purina PetCare |
| Virbac |
| PetHonesty |
| Zesty Paws |
| THUNDERWORKS |
| Vetoquinol |
| PetIQ |
| Others |
Value Network & Pricing Analysis
Hemp biomass substitution for synthetic pheromone precursors is redrawing procurement geography from agricultural belts to pharmaceutical synthesis hubs, compressing margin structures for CBD-dependent manufacturers while elevating pricing power for biotechnology-anchored suppliers. This input shift simultaneously fragments supplier bases across North American hemp cultivation regions and European pheromone synthesis clusters, forcing dual-sourcing strategies that inflate working capital requirements.
Pricing Analysis
Metropolitan United States markets command 35-50% premiums over rural corridors for prescription-grade calming chews, reflecting veterinary behaviorist density and telehealth prescription normalization. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier: FDA Center for Veterinary Medicine notification status separates premium veterinary clinic formulations from mass-market supplements. Price erosion runs through CBD-infused segments as agricultural commodity cycles destabilize hemp biomass input costs. Holistic-oriented consumers demonstrate lowest price sensitivity, accepting substantial premiums for organic botanical sourcing and sustainable packaging compliance.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes inflate inbound logistics costs for L-Theanine isolates sourced from Japanese and South Korean nutraceutical suppliers. Active ingredient concentration rests on three geographic clusters: United States hemp biomass for CBD formulations, European pheromone synthesis facilities in Germany and France, and East Asian amino acid production centers. Raw material dependencies span hemp biomass, green tea extract feedstocks, and microencapsulation polymers. Single-source vulnerability concentrates in pheromone active ingredient synthesis, where proprietary microencapsulation technology locks buyers into limited qualified supplier pools. Distribution runs through veterinary clinic networks for prescription-grade therapeutics, with direct-to-consumer platforms capturing growing share of chronic-use replenishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet relaxants function as a service-attach market where subscription replenishment revenue and veterinary telehealth consultation fees expand faster than standalone product margins, creating recurring revenue architectures that transcend transactional hardware economics.
For Market Incumbents: Fortify clinic channel control through exclusive formulation partnerships with expanding veterinary telehealth platforms, insulating against direct-to-consumer disintermediation. Deepen backward integration into pheromone synthesis capabilities to capture margin pools currently allocated to European biotechnology suppliers. Secure FDA Center for Veterinary Medicine notification status for core formulations to maintain premium pricing tier access against unregulated CBD competitors. For New Entrants and Emerging Players: Lead with sensor-enabled dosing compliance systems that satisfy emerging pet insurer wellness program requirements, anchoring product differentiation in outcome verification rather than ingredient sourcing. Target Brazil's underpenetrated pheromone market through ANVISA pre-submission consultations, exploiting first-mover windows before multinational incumbents localize formulations. Deploy direct-to-consumer subscription platforms with veterinary telehealth integration to bypass traditional clinic channel barriers. For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer wellness brands with established subscription infrastructure and veterinary telehealth platform partnerships, as these assets capture recurring revenue streams with superior retention economics. Long-term viability hinges on regulatory navigation capabilities across fragmented cannabinoid policy environments. Monitor FDA Center for Veterinary Medicine draft guidance finalization as inflection indicator for CBD formulation investment attractiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Pheromone Microencapsulation Scale-Up | Extends release profiles to satisfy veterinary behaviorist efficacy requirements for environmental diffuser protocols. |
| Veterinary Telehealth Platform Partnership | Captures remote prescription workflows that normalize direct-to-consumer fulfillment for chronic anxiety cases. |
| Sensor-Enabled Dosing Compliance Integration | Enables outcome tracking that satisfies pet insurer wellness program reimbursement requirements. |
| EU Green Deal Packaging Compliance Transition | Mandates biodegradable blister packs and post-consumer recycled bottles as baseline market access condition. |
| ANVISA Veterinary Product Framework Pre-Submission | Secures first-mover positioning in Latin America's largest companion animal market before incumbent localization. |
Research Methodology
Desk research of FDA Center for Veterinary Medicine guidance documents, USDA Farm Bill implementation records, EU Novel Food Catalogue classifications, and ANVISA regulatory filings preceded structured interviews with veterinary behaviorists, pet supplement procurement managers at specialty retailers, direct-to-consumer platform operators, and pheromone synthesis technology specialists. Secondary validation drew from customs trade databases, veterinary medical board dispensing records, and pet insurance wellness program documentation. Bottom-up demand modeling triangulated against top-down market sizing from regulatory filing volumes and channel shipment data.
Variance decomposition across product type, active ingredient pathway, pet species physiology, and distribution channel informed analytical framework construction over the projection horizon. Segmentation dimensions modeled included delivery format bioavailability profiles, regulatory pathway complexity tiers, and veterinary prescription authority requirements. CAGRs derived from unit economics analysis of subscription replenishment versus episodic purchase patterns, incorporating veterinary telehealth adoption curves and pet humanization spending elasticity estimates. Pheromone synthesis yield improvements and hemp biomass commodity cycle assumptions shaped input cost trajectories.
Forecasts assume regulatory continuity in FDA Center for Veterinary Medicine oversight frameworks, EU Novel Food Catalogue classifications, and ANVISA veterinary product pathways; material policy shifts would require re-modeling of CBD formulation addressable market boundaries. Agricultural commodity price volatility and veterinary pharmacist availability constraints represent specific risk factors that could revise demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Pet Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Kitten Milk Replacer and Formula Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
South America Dog Food Market
Pet Care Products
PET Market
Pet Care Products
Pet Transporting Service Market