
 Smart Dog Collar Market | 2026-2036
Smart Dog Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dog Collar Market Insights
Multi-source component procurement is shifting toward captive semiconductor sourcing among tier-one manufacturers. Garmin leverages in-house GPS chipset development to control firmware-roadmap timing for high-accuracy tracking products. Tractive anchors its cost structure through dedicated Asian manufacturing partnerships that sustain aggressive subscription pricing. Halo Collar differentiates via proprietary virtual-fencing algorithms trained on proprietary canine behavioral datasets.
A smart dog collar integrates location transceivers, inertial measurement units, and biometric sensors within a weatherproof polymer housing designed for continuous canine wear, transmitting telemetry through cellular or Bluetooth protocols to cloud-based analytics platforms. GPS collars dominate unit volume due to universal lost-pet recovery demand, while health monitors command premium pricing through veterinary-grade photoplethysmography and temperature trending. Cellular-enabled devices represent the fastest-growing technology segment as LTE-M and NB-IoT modules reduce power draw and extend field deployment between charges.
FCC Part 15 emissions testing shapes product development timelines for United States market entry, while CE marking under the EU Radio Equipment Directive governs European spectrum compliance and safety documentation. RoHS substance restrictions and REACH chemical registration obligations constrain adhesive and coating selections across both jurisdictions. Stakeholders must monitor evolving cybersecurity mandates for IoT wearables as France's ANSSI and Germany's BSI publish baseline requirements for connected pet device data protection.
Market Dynamics
Cellular-enabled telemetry is compressing recharge cycles from weekly to monthly intervals, reshaping how manufacturers architect power management firmware and battery chemistry stacks for field-deployed wearables.
Growth Catalysts
- FCC Part 15 emissions frameworks:Equipment authorization timelines in the United States are standardizing pre-market testing protocols, reducing certification friction for new entrants with modular radio designs.
- Veterinary channel integration:Clinics in Germany are bundling health-monitoring subscriptions with wellness plans, creating recurring revenue anchors for biometric-capable hardware.
- LTE-M module proliferation:Low-power wide-area chipsets from Asian semiconductor foundries are collapsing connectivity costs for GPS-tracking form factors.
Market Restraints
- Lithium-polymer cell volatility:Raw material price swings for cobalt and nickel are pressuring gross margins on premium collar SKUs with extended battery specifications.
- Foundry concentration in Taiwan:Single-source dependencies for GPS baseband silicon create supply vulnerability during geopolitical disruptions or water-constrained production periods.
- RoHS substance restrictions:Lead-free solder mandates under EU directives are elevating assembly defect rates in vibration-resistant housing joints.
Strategic Opportunities
- Underpenetrated Japanese households:Pet insurance penetration exceeds forty percent in Tokyo and Osaka, creating receptive infrastructure for preventive health-monitoring hardware.
- Convergence of IMU data with AI-driven behavioral models:Accelerometer fusion with machine learning classifiers enables early lameness detection, opening veterinary diagnostic reimbursement pathways.
- Direct-to-consumer subscription platforms:Bypassing retail markup through proprietary e-commerce channels allows manufacturers to capture lifetime value through firmware-feature upgrades.
Industry Challenges
- Firmware security certification gaps:Absence of harmonized IoT cybersecurity standards across France's ANSSI and Germany's BSI frameworks is delaying multi-country launch timelines.
- Legacy veterinary practice management software:Proprietary data formats in incumbent platforms resist API integration, fragmenting health-record continuity between collar telemetry and clinic EMR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dog Collar Market |
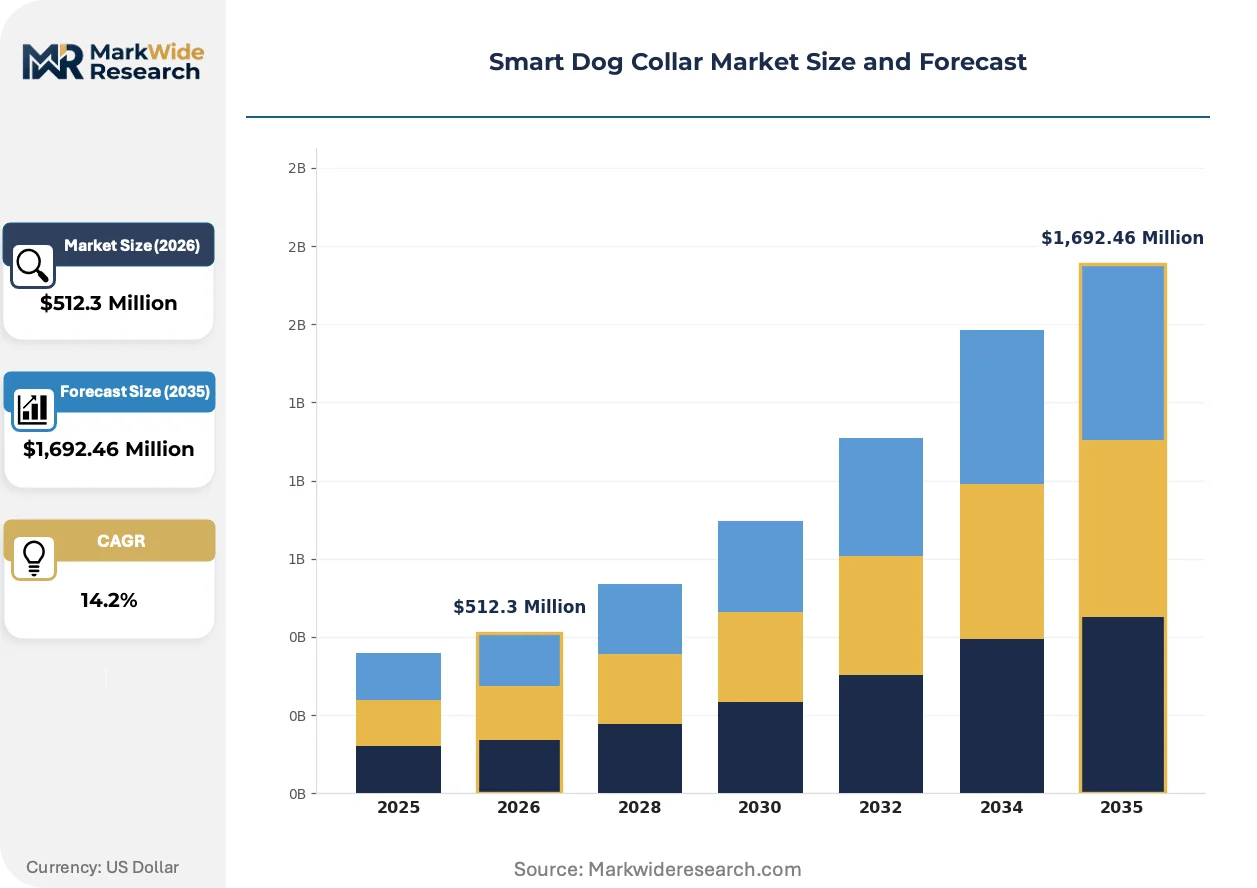
| Market Size in 2026 | $512.3 Million |
| Market Size in 2035 | $1,692.46 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Collars, Activity Trackers, Health Monitors, Training Collars Technology: Bluetooth, Cellular, Wi-Fi, RFID End User: Pet Owners, Professional Trainers, Veterinarians, Dog Walkers Feature: Remote Monitoring, Activity Alerts, Virtual Fencing, Waterproof Design |
| Companies Covered | Garmin, Weenect, Fi Series, SportDog, Pawfit, Tractive, Halo Collar, SATELLAI, SpotOn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dog Collar Market Trends and Innovations
Hardware-software co-design is accelerating as manufacturers embed machine learning inference directly on collar-mounted microcontrollers, reducing cloud dependency for real-time behavioral alerts.
Photoplethysmography sensors are absorbing veterinary-grade signal-processing algorithms previously confined to clinical monitors, enabling continuous heart-rate variability tracking during off-leash exercise. Professional trainers in the United States are adopting these biometric-enabled units for conditioning programs, compressing the price premium between consumer fitness wearables and medical-grade devices.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility documentation requirements for devices operating in shared unlicensed spectrum bands. Manufacturers targeting German and French retail channels must now submit expanded test reports covering spurious emissions in adjacent cellular bands, extending pre-market preparation cycles by eight to twelve weeks.
Subscription unbundling from hardware is reshaping buyer economics as vendors separate GPS-tracking SaaS from fitness-monitoring tiers. Urban dog owners in dense metropolitan clusters are selecting à-la-carte feature activation, forcing manufacturers to architect modular firmware architectures that gate functionality through over-the-air license keys rather than physical SKU differentiation.
Smart Dog Collar Market Segmentation
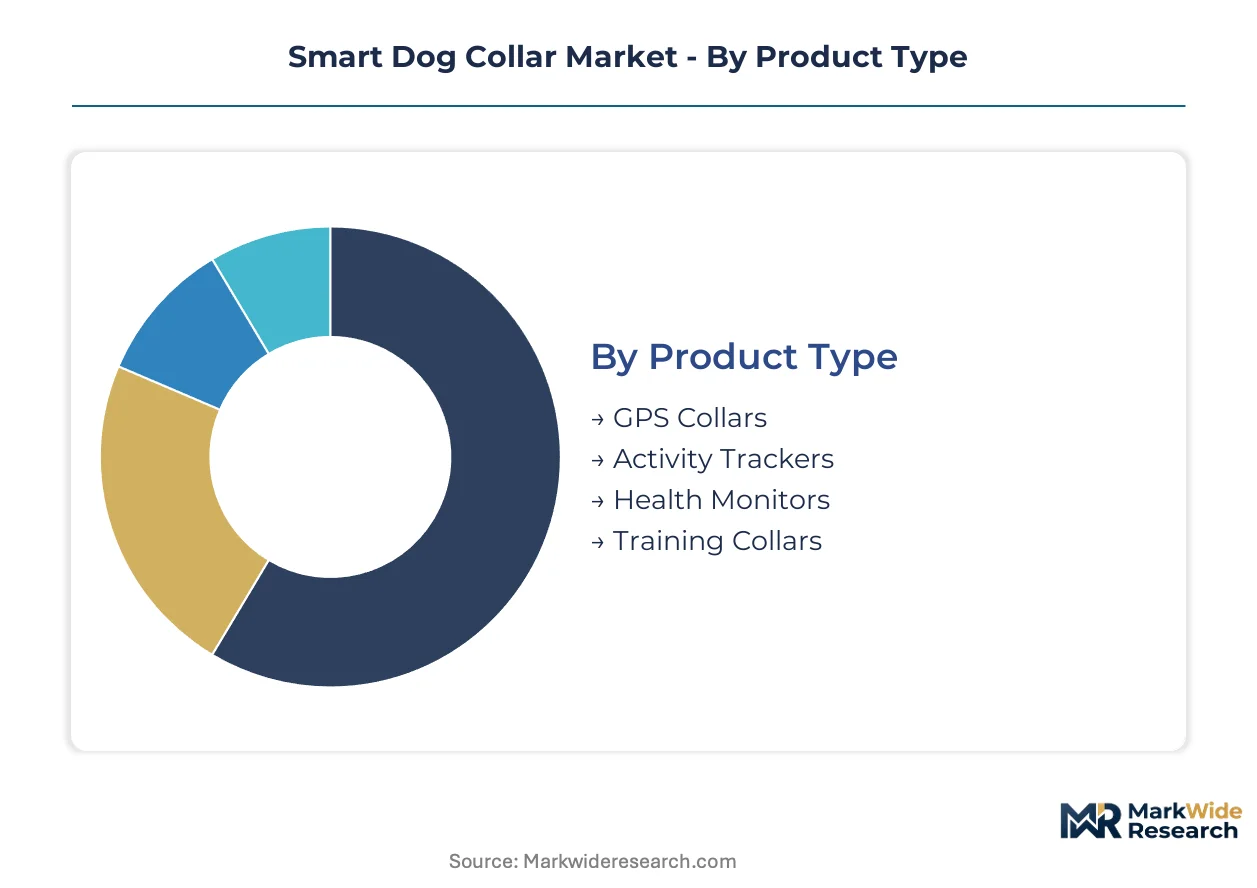
Smart dog collar segmentation reveals divergent paths between mass-market hardware and premium service tiers. Manufacturers calibrate component stacks and firmware architectures differently across these divides, with GPS tracking commanding unit volume while health monitoring extracts subscription value.
Product Type:
Volume concentrates in entry-level tracking hardware, while premium pricing attaches to veterinary-grade biometric capabilities.
- GPS Collars:Location transceivers paired with LTE-M or NB-IoT modules deliver real-time position telemetry for lost-pet recovery. Demand clusters in Germany's dense urban corridors where off-leash regulations and veterinary channel bundling create favorable unit economics for subscription models.
- Health Monitors:Photoplethysmography sensors and temperature trending algorithms enable continuous cardiac and thermal surveillance. Professional trainers in the United States are adopting these units for conditioning programs, compressing the price gap between consumer fitness wearables and clinical-grade devices.
- Activity Trackers:Inertial measurement units quantify step counts, sleep patterns, and exercise intensity for wellness-focused owners.
- Training Collars:Stimulus delivery mechanisms integrated with behavioral algorithms support remote correction and positive reinforcement protocols.
Today's leader: GPS Collars. Tomorrow's challenger: Health Monitors.
Technology:
Connectivity cost structures determine addressable market breadth, with cellular modules collapsing price barriers for field-deployed tracking.
- Cellular:LTE-M and NB-IoT chipsets from Asian foundries reduce power draw and extend deployment intervals between charges. FCC Part 15 emissions testing shapes United States product development timelines, while CE marking under the EU Radio Equipment Directive governs European spectrum compliance.
- Bluetooth:Low-energy protocols support smartphone-tethered operation for proximity-based activity logging in controlled environments.
- Wi-Fi:Higher bandwidth enables firmware updates and data synchronization when collars enter home network coverage zones.
- RFID:Passive identification supports veterinary clinic check-in and shelter intake workflows without battery dependency.
Cellular-enabled devices are climbing the fastest as module costs fall and carrier roaming agreements simplify cross-border deployment.
End User:
Customer acquisition economics shift dramatically between direct-to-consumer channels and institutional procurement pathways.
- Pet Owners:Urban households in metropolitan clusters drive subscription unbundling trends, selecting à-la-carte feature activation through over-the-air license keys rather than physical SKU differentiation.
- Professional Trainers:Precision livestock management techniques are migrating to companion animal care, creating rapidly expanding demand for biometric-enabled conditioning hardware.
- Veterinarians:German clinics bundle health-monitoring subscriptions with wellness plans, establishing recurring revenue anchors for preventive care hardware.
- Dog Walkers:Fleet management needs for multi-dog handling generate demand for consolidated tracking dashboards and group activity reporting.
Professional Trainers represent the steepest expansion trajectory as behavioral data monetization extends beyond consumer applications.
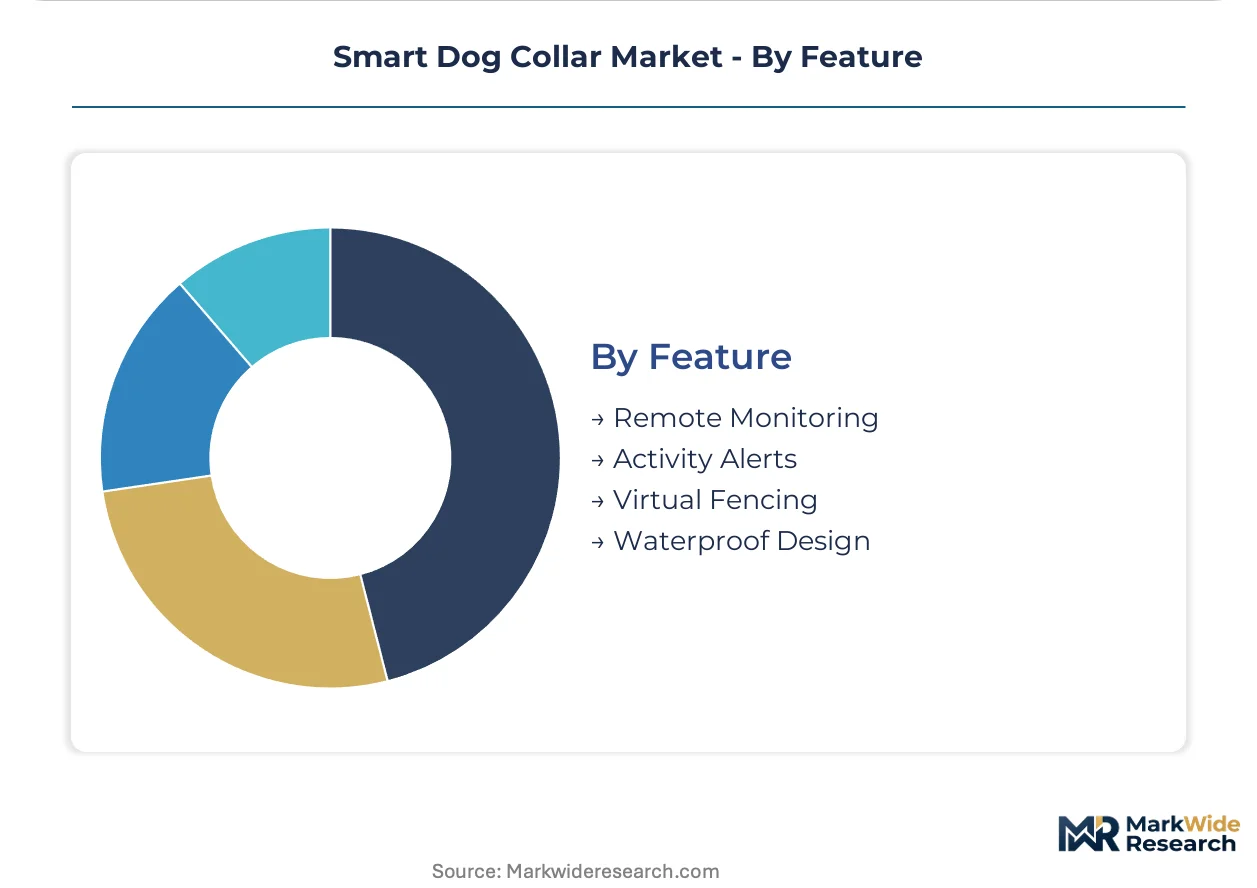
Feature:
Hardware-software co-design prioritizes firmware-modular architectures that gate functionality through license management rather than physical configuration.
- Remote Monitoring:Cloud-based analytics platforms aggregate telemetry for owner dashboard visualization and veterinary alert routing.
- Activity Alerts:Machine learning classifiers on collar-mounted microcontrollers detect behavioral anomalies without continuous cloud dependency.
- Virtual Fencing:Proprietary boundary algorithms trained on canine behavioral datasets enable GPS-defined containment without physical infrastructure.
- Waterproof Design:Weatherproof polymer housings with sealed joints maintain IP ratings through swimming and sustained precipitation exposure.
Virtual Fencing commands the highest feature-specific willingness-to-pay among suburban property owners seeking containment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense urban corridors anchor smart dog collar demand through veterinary channel bundling and premium subscription economics. FCC Part 15 frameworks in the United States and CE marking under the EU Radio Equipment Directive shape multi-jurisdictional product development timelines. Manufacturing partnerships across Asian foundries and European assembly nodes complete the supply architecture.
United States
Professional trainers in California and Texas drive biometric-enabled conditioning hardware adoption for precision livestock techniques migrated to companion animals. FCC Part 15 emissions testing standardizes pre-market protocols for modular radio designs entering the market. Greater Boston and Austin tech clusters concentrate firmware development for virtual-fencing algorithms and behavioral machine learning classifiers.
Germany
Veterinary clinics in Munich and Hamburg bundle health-monitoring subscriptions with wellness plans, creating recurring revenue anchors for preventive care hardware. CE marking under the EU Radio Equipment Directive governs electromagnetic compliance for devices operating in shared unlicensed spectrum. The Rhine-Ruhr metropolitan region hosts dense urban dog ownership patterns that sustain premium collar subscription economics.
Japan
Pet insurance penetration exceeding forty percent in Tokyo and Osaka creates receptive infrastructure for preventive health-monitoring hardware. METI guidelines for IoT cybersecurity establish baseline requirements for connected pet device data protection. The Kanto region concentrates demand for photoplethysmography-enabled units among aging pet demographics seeking veterinary-grade cardiac surveillance.
United Kingdom
Urban households in Greater London drive subscription unbundling trends toward à-la-carte feature activation through over-the-air license keys. RoHS substance restrictions constrain adhesive and coating selections for weatherproof polymer housings. The Southeast England corridor hosts direct-to-consumer subscription platforms capturing lifetime value through firmware-feature upgrades.
France
ANSSI cybersecurity mandates for IoT wearables establish data protection baselines that delay multi-country launch timelines for unprepared vendors. Dense metropolitan clusters in Paris and Lyon concentrate demand for GPS-tracking form factors with LTE-M module connectivity. The Île-de-France region anchors retail channel penetration for cellular-enabled devices with extended field deployment intervals.
Smart Dog Collar Market Competitive Landscape
Global majors compete with regional champions across firmware-roadmap control and subscription pricing architectures. The vendor base stratifies between captive semiconductor developers, dedicated Asian manufacturing partners, and proprietary algorithm specialists. Three archetypes dominate: integrated GPS chipset developers, cost-optimized connectivity aggregators, and behavioral-data monetization platforms. Capacity expansion through foundry partnerships and strategic technology licensing represent the primary competitive vectors reshaping positioning.
Within the integrated hardware tier, Garmin leverages in-house GPS chipset development to control firmware-roadmap timing for high-accuracy tracking products. Tractive anchors cost structures through dedicated Asian manufacturing partnerships that sustain aggressive subscription pricing. Halo Collar occupies a position exemplifying proprietary virtual-fencing differentiation trained on canine behavioral datasets.
| Leading Market Players |
|---|
| Garmin |
| Weenect |
| Fi Series |
| SportDog |
| Pawfit |
| Tractive |
| Halo Collar |
| SATELLAI |
| SpotOn |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FCC Part 15 authorized units and CE-marked European variants manifests in both subscription pricing power and dual-track supply chain configurations. Tier-one manufacturers absorb electromagnetic compliance testing costs into premium collar SKUs while Asian foundry partnerships enable aggressive entry-level pricing for mass-market GPS tracking hardware.
Pricing Analysis
Input-cost pass-through from lithium-polymer cell volatility and cobalt price swings compresses gross margins on extended-battery premium SKUs. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-grade photoplethysmography units from basic GPS trackers and white-label commodity hardware. Pricing pressure stems from LTE-M module cost collapse as Asian semiconductor foundries expand NB-IoT capacity. Urban pet owners in dense metropolitan clusters show highest price sensitivity, selecting à-la-carte subscription tiers, while German veterinary clinics demonstrate lowest sensitivity through wellness-plan bundling.
Supply Chain Analysis
Dual-sourcing requirements for GPS baseband silicon mandate qualification across Taiwanese and South Korean foundries to mitigate single-source vulnerability during water-constrained production periods. Component procurement draws from China for polymer housings, Taiwan for cellular modules, and Germany for precision IMU sensors. Raw material dependencies center on cobalt and nickel for battery cells, rare earth elements for antenna substrates, and medical-grade adhesives for sealed joints. Tariff exposure on Chinese-manufactured housings elevates landed costs for United States market entry. Distribution runs through veterinary clinic channels in Germany, direct-to-consumer platforms in the United Kingdom, and electronics retail chains in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as buyer preference shifts toward veterinary-grade biometric specifications over basic location tracking. Premium health-monitoring subscriptions now anchor recurring revenue models across German and Japanese channels.
For Market Incumbents: Anticipate margin compression from emerging direct-to-consumer entrants by deepening captive semiconductor development for GPS chipset control. Prioritize firmware-roadmap acceleration for real-time behavioral alerts to defend against algorithmic differentiation from behavioral-data platforms. CE marking documentation investments create regulatory moats against modular-radio new entrants seeking rapid European market entry. For New Entrants and Emerging Players: Enter via underpenetrated Japanese households where forty-percent pet insurance penetration creates receptive infrastructure for preventive health-monitoring hardware. Target professional trainer segments in California and Texas as precision livestock techniques migrate to companion animal conditioning programs. Pursue veterinary channel partnerships in Germany as the most penetrable institutional pathway, leveraging wellness-plan bundling economics. For Investors and Strategic Acquirers: Consolidation pressure builds where proprietary virtual-fencing algorithms and canine behavioral datasets create acquisition premiums for data-monetization platforms. Long-term viability favors vendors with integrated hardware-software co-design capabilities and direct subscription relationships. Watch for inflection signals in veterinary diagnostic reimbursement pathways for IMU-driven lameness detection as the indicator of health-monitor segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GPS Chipset Development | Garmin's in-house production controls firmware-roadmap timing for high-accuracy tracking products. |
| Asian Manufacturing Partnership | Tractive's dedicated foundry relationships sustain aggressive subscription pricing through cost-optimized LTE-M module sourcing. |
| Proprietary Algorithm Training | Halo Collar's virtual-fencing differentiation rests on proprietary canine behavioral datasets. |
| Veterinary Channel Integration | German clinic bundling creates recurring revenue anchors for preventive care hardware deployments. |
| Direct-to-Consumer Platform Launch | Subscription unbundling through proprietary e-commerce captures lifetime value via over-the-air firmware upgrades. |
Research Methodology
Direct dialogue with product managers at collar manufacturers, procurement leads at veterinary clinic chains, firmware engineers at GPS chipset developers, and subscription platform operators grounded qualitative findings. Secondary validation drew from FCC equipment authorization databases, CE marking documentation under the EU Radio Equipment Directive, METI cybersecurity guidelines, and pet insurance penetration statistics. Bottom-up unit shipment estimates triangulated against top-down subscription revenue analysis across the analysis window.
Segmented outputs across product type, connectivity technology, end-user archetype, and feature tier informed the projection framework. Modeled dimensions included GPS collar versus health monitor hardware splits, cellular versus Bluetooth connectivity adoption curves, and professional trainer versus pet owner demand trajectories. CAGRs derived from regression analysis of historical module cost decline curves and veterinary channel bundling penetration rates.
Inputs from foundry production schedules and carrier roaming agreement disclosures were available through the study window; gaps in proprietary canine behavioral dataset valuations introduce uncertainty bands around virtual-fencing segment sizing. Forecasts reflect documented assumptions regarding LTE-M module cost trajectories and cybersecurity mandate implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Dog Treats Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
United States Pet Market
Pet Care Products
Pet Toys Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
Canada Pet Food Market