
 US Percussion Massage Gun Market | 2026-2036
US Percussion Massage Gun Market Size, Share, and Industry Trends Forecast 2026-2036
US Percussion Massage Gun Market Analytics
Subscription-based recovery programming is consolidating around hardware ecosystems, shifting unit economics from one-time sales toward recurring revenue attachment. Therabody leverages its app-integrated content platform to sustain premium positioning across professional athletic facilities. Hyperice competes through strategic partnerships with major sports leagues, while Lifepro anchors its growth in direct-to-consumer channels with aggressive price positioning.
A percussion massage gun is a handheld electromechanical device employing rapid percussive strokes typically between 1,200 and 3,200 percussions per minute to deliver deep tissue manipulation for muscular recovery and pain relief. Cordless configurations now dominate unit shipments as lithium-ion battery energy density improvements enable sustained high-torque motor output without tethering constraints. The athlete and fitness enthusiast target audience commands the highest per-unit spend and brand loyalty coefficients, while the under $50 price band remains structurally crowded with low-margin private-label entrants.
The FDA regulates percussion massage guns as Class I medical devices when therapeutic claims exceed general wellness positioning, creating compliance bifurcation between fitness-branded and clinically-positioned products. FCC certification governs wireless connectivity features increasingly bundled with premium units. OSHA guidelines for workplace ergonomics influence corporate wellness procurement standards. Stakeholders must monitor whether the FTC intensifies substantiation requirements for performance claims, as that regulatory shift would reshape marketing expenditures and product liability exposure across the competitive set.
Market Dynamics
Professional athletic recovery protocols now mandate percussion therapy as standard equipment, compressing sales cycles from discretionary purchases to institutional procurement mandates across NCAA programs, NBA franchises, and physical therapy chains.
Growth Catalysts
- FDA Class I medical device pathway:Therapeutic claims positioning unlocks reimbursement eligibility through HSA/FSA channels, expanding addressable spend beyond out-of-pocket fitness budgets.
- Lithium-ion energy density gains:Battery chemistry improvements enable sustained 3,200 percussions-per-minute output in cordless configurations, eliminating tethering constraints that previously limited clinical adoption.
- Texas and Florida athletic infrastructure:State-level investment in high school and collegiate sports facilities concentrates demand for recovery equipment procurement.
Market Restraints
- Rare-earth magnet supply concentration:High-torque brushless motor production depends on neodymium sourcing concentrated in Chinese processing facilities, exposing margin stability to export control volatility.
- OSHA ergonomic guideline ambiguity:Workplace wellness procurement standards lack specificity for handheld vibration devices, creating qualification friction for corporate bulk orders.
- Manual massage therapy substitution:Licensed massage therapists in California and New York markets resist equipment-based displacement, slowing clinical penetration in unionized healthcare settings.
Strategic Opportunities
- Corporate wellness channel underpenetration:Fortune 500 onsite fitness facilities in Illinois and Ohio currently stock recovery equipment at sub-15% rates, creating whitespace for B2B contract expansion.
- Bluetooth-enabled prescription integration:Convergence of percussion hardware with telehealth platforms enables remote protocol adjustment by licensed physical therapists.
- FTC substantiation gap:Pending enforcement action on performance claims creates first-mover advantage for brands investing in clinical trial documentation ahead of mandatory requirements.
Industry Challenges
- Biomedical engineering talent scarcity:Firmware development for percussive motor control algorithms requires specialized electromechanical expertise concentrated in Boston and San Francisco metro areas.
- FCC Part 15 certification timelines:Wireless connectivity feature additions extend product launch schedules by 4-6 months, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Percussion Massage Gun Market |
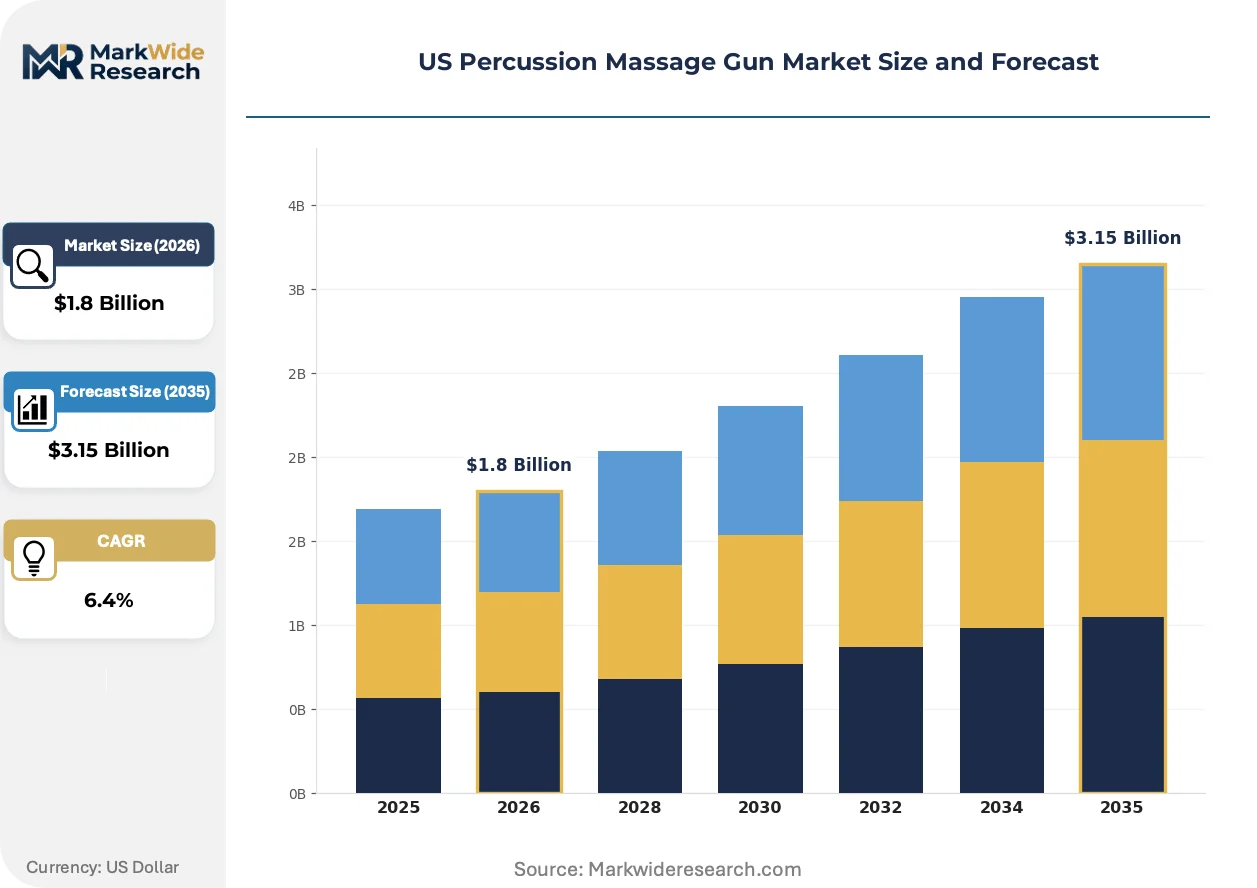
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Cordless, Wired, Heavy-Duty Target Audience: Athletes, Fitness Enthusiasts, Physical Therapists, General Consumers Battery Life: 1 Hour, 3 Hours, 5 Hours, Unlimited Price Range: Under $50, $50-$100, $100-$200, Over $200 |
| Companies Covered | Ekrin Athletics, TimTam, Therabody, OPOVE, RENPHO, Hyperice, Lifepro, iReliev, HoMedics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Percussion Massage Gun Market Evolving Landscape
Sensor-integrated hardware ecosystems now capture usage biometric data, transforming percussion devices from passive tools into active recovery protocol managers that communicate with athlete management platforms.
Force-sensing resistor arrays embedded in massage gun heads is automating pressure adjustment in real-time based on tissue density feedback. Professional sports training staffs in Arizona and Colorado are piloting these units for standardized treatment protocols across athlete rosters. The technology is automating therapist-dependent technique variation, reducing outcome variability between staff members.
FDA draft guidance on wellness versus medical device claims is tightening substantiation requirements for pain relief assertions. Manufacturers must now distinguish fitness positioning from therapeutic indications through labeling architecture and marketing channel selection. Products targeting physical therapy clinics face expanded clinical evidence burdens compared to direct-to-consumer fitness variants.
Athletic directors and facility managers now bundle recovery equipment into comprehensive vendor contracts rather than sourcing standalone units. This procurement consolidation favors multi-product suppliers with service infrastructure over specialized massage gun manufacturers. The shift concentrates purchasing authority at conference and league levels, most visible in Southeastern Conference athletic department RFPs.
US Percussion Massage Gun Market Segmentation
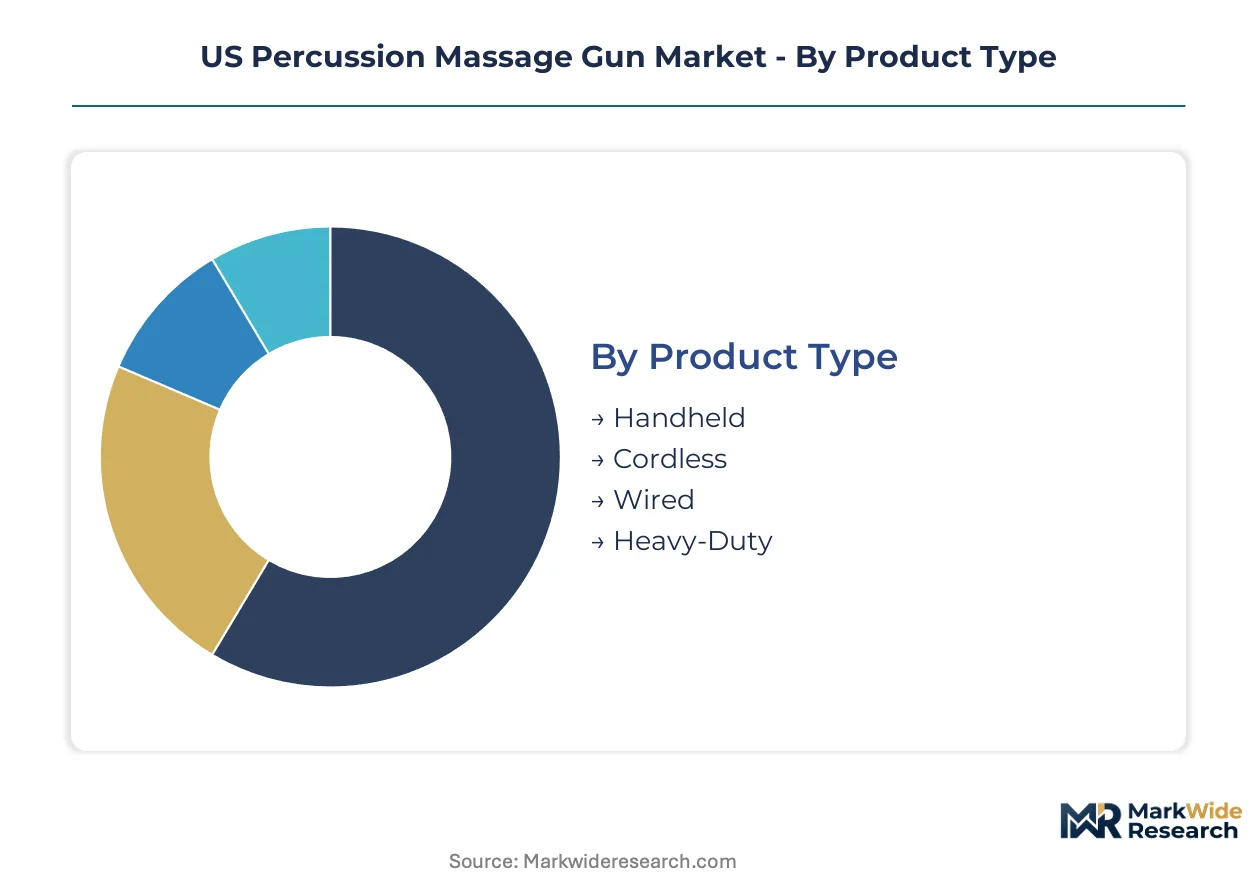
Percussion massage gun segmentation reveals divergent buyer priorities across clinical precision, athletic performance, and household convenience. Manufacturers must align motor specifications, battery architectures, and price positioning with distinct procurement channels.
Product Type:
Buyers in this category differentiate by mobility requirements and torque demands rather than brand preference alone.
- Cordless:Lithium-ion configurations now dominate unit shipments as energy density improvements enable sustained 3,200 percussions-per-minute output without tethering constraints. Texas and Florida athletic departments standardize cordless units for facility-wide deployment.
- Handheld:Ergonomic grip designs with 1.5-2.5 pound chassis weights address therapist fatigue in clinical settings. Physical therapy chains in California prefer handheld units for mobile treatment rooms.
- Heavy-Duty:Stall-force ratings above 60 pounds serve professional sports training staffs requiring sustained deep-tissue penetration. NCAA Division I programs drive procurement concentration.
- Wired:Continuous power delivery supports clinical settings where session duration exceeds cordless battery endurance. Unionized healthcare facilities in New York maintain wired unit preference.
Volume sits with Cordless; growth tilts toward Heavy-Duty.
Target Audience:
Procurement authority and per-unit spend vary dramatically across buyer categories, from institutional mandates to discretionary fitness purchases.
- Athletes:Professional sports franchises and NCAA programs mandate percussion therapy in standardized recovery protocols. Southeastern Conference athletic departments consolidate vendor contracts around multi-unit procurement.
- Physical Therapists:Licensed clinicians in California and Texas drive clinical-grade unit adoption where FDA Class I positioning unlocks HSA/FSA reimbursement eligibility.
- Fitness Enthusiasts:Boutique gym members and CrossFit participants generate premium unit demand with high brand loyalty coefficients. Direct-to-consumer channels capture this segment.
- General Consumers:Post-exercise soreness relief motivates occasional-use purchases with elevated price sensitivity. Amazon and big-box retailers dominate distribution.
Athletes command the steepest expansion trajectory; General Consumers anchor absolute volume.
Battery Life:
Runtime specifications determine use-case viability across mobile clinical practice, athletic training floors, and home environments.
- 5 Hours:Extended runtime supports multi-athlete treatment sessions without mid-day recharging. Professional team training staffs in Arizona pilot these units for standardized protocols.
- 3 Hours:Balanced capacity-to-weight ratios serve physical therapy clinics with moderate daily caseloads. Texas outpatient rehabilitation chains standardize on this tier.
- 1 Hour:Compact cells reduce unit weight for travel-oriented fitness enthusiasts. Weekend warrior demographics in Florida concentrate here.
- Unlimited:Wired configurations eliminate battery degradation concerns in fixed clinical installations. Hospital-based therapy departments maintain this preference.
3 Hours holds current volume leadership; 5 Hours gains share fastest.
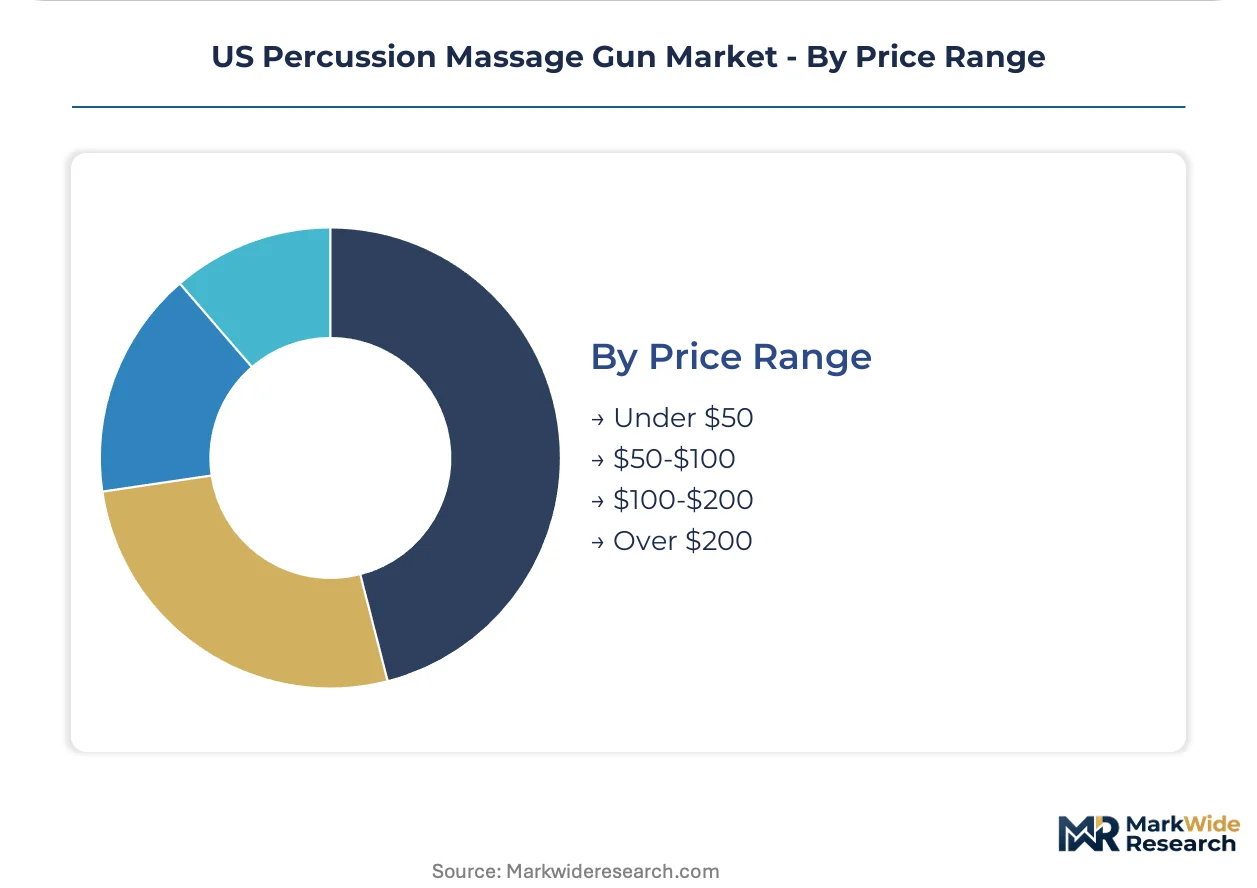
Price Range:
Price tier alignment with distribution channel and certification grade creates distinct competitive battlegrounds.
- $100-$200:Premium fitness positioning with app integration and Bluetooth connectivity captures athletic facility procurement. Therabody and Hyperice compete intensely here.
- $50-$100:Mid-tier specifications balance motor performance with mass-market accessibility. Lifepro anchors growth through aggressive direct-to-consumer positioning.
- Over $200:Clinical-grade certifications and extended warranties justify premium pricing for physical therapy chains. FDA Class I pathway eligibility distinguishes this tier.
- Under $50:Private-label entrants crowd this band with commoditized specifications. Margin compression limits sustainable manufacturer participation.
$100-$200 represents the fastest-growing trajectory; Under $50 remains structurally crowded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in coastal electronics corridors while consumption clusters around athletic infrastructure investment zones. Texas and Florida drive procurement volume through collegiate sports expansion, while California anchors clinical-grade adoption through physical therapy network density.
California
Physical therapy chains and boutique fitness studios generate concentrated demand for FDA Class I certified units. The state's Department of Consumer Affairs oversees licensed massage therapy scope-of-practice boundaries that influence clinical equipment procurement. Los Angeles and San Francisco metro areas host recovery technology startups piloting sensor-integrated hardware for professional sports franchises.
Texas
NCAA Division I athletic departments and high school sports infrastructure expansion drive institutional procurement mandates. The Texas Department of Licensing and Regulation governs massage therapy equipment standards affecting clinical adoption timelines. Dallas-Fort Worth and Houston medical centers standardize percussion therapy in outpatient rehabilitation protocols.
Florida
Retirement community wellness programs and collegiate athletic programs create dual demand streams for recovery equipment. The Florida Board of Massage Therapy regulates therapeutic device claims in clinical settings. Miami and Orlando fitness infrastructure investment outpaces national averages for per-capita recovery equipment procurement.
New York
Unionized healthcare settings and licensed massage therapy resistance slow equipment-based displacement in clinical channels. The New York State Department of Education oversees massage therapy licensure affecting scope-of-practice boundaries. New York City corporate wellness programs underpenetrate relative to Fortune 500 headquarters density, creating whitespace for B2B contract expansion.
Illinois
Fortune 500 onsite fitness facilities and corporate headquarters concentration drive underpenetrated B2B recovery equipment demand. The Illinois Department of Financial and Professional Regulation governs physical therapy practice standards. Chicago metro area procurement consolidation favors multi-product suppliers with service infrastructure over specialized manufacturers.
US Percussion Massage Gun Market Competitive Landscape
Top-tier vendors anchor the premium tier through app-integrated ecosystems and league partnerships, while mid-market specialists compete on aggressive direct-to-consumer pricing. The vendor base stratifies across three archetypes: premium ecosystem builders, performance partnership specialists, and volume-driven direct-to-consumer operators. Consolidation pressures favor multi-product suppliers with service infrastructure as athletic departments bundle recovery equipment into comprehensive vendor contracts.
Within the premium ecosystem tier, Therabody and Hyperice exemplify archetypes built around content platforms and strategic league affiliations. Lifepro occupies a position among aggressive direct-to-consumer price-positioned specialists. Ekrin Athletics, TimTam, and OPOVE represent mid-market performance-focused fabricators competing on motor specifications and warranty terms. RENPHO and iReliev anchor the accessible price band through Amazon-centric distribution, while HoMedics exemplifies legacy wellness brand extension into percussion therapy categories.
| Leading Market Players |
|---|
| Ekrin Athletics |
| TimTam |
| Therabody |
| OPOVE |
| RENPHO |
| Hyperice |
| Lifepro |
| iReliev |
| HoMedics |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between FDA Class I medical devices and general wellness positioning creates parallel pricing architectures that demand entirely different supply chain configurations. Premium clinical-grade units commanding over $200 rely on validated component sourcing and extended warranty infrastructure, while sub-$50 private-label entrants optimize for commodity electronics procurement with minimal after-sales obligation.
Pricing Analysis
Margin tightening in the sub-$100 tier reflects neodymium magnet cost volatility and lithium-ion cell price swings. Three-tier pricing structure across premium, standard, and economy levels segments by certification burden and connectivity features, with FDA pathway eligibility and Bluetooth integration driving $100-$200 premiums. Cost-down pressure on economy units accelerates as Amazon private-label entrants absorb distribution margin. General Consumers exhibit highest price sensitivity, while NCAA athletic departments demonstrate inelastic demand for heavy-duty specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth processing facilities that refine neodymium for brushless motor production. Manufacturing draws from Shenzhen electronics corridors for PCB assembly, South Korean battery cell suppliers for lithium-ion configurations, and domestic Texas distribution hubs for athletic department fulfillment. Tariff exposure on Chinese magnet exports threatens margin stability across all tiers. Distribution runs through Amazon Marketplace for consumer volume, direct-to-consumer portals for fitness enthusiasts, and GPO contracts for physical therapy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation by Southeastern Conference athletic departments and physical therapy chains is compressing vendor counts, forcing sub-scale manufacturers toward exit or acquisition.
For Market Incumbents: Cement multi-product ecosystem positioning by integrating sensor-enabled hardware with subscription recovery programming, defending against pure-play massage gun commoditization. Secure captive supply of neodymium magnets through backward integration or long-term offtake agreements with Australian mining operations. Prioritize FCC Part 15 pre-certification for Bluetooth-enabled units to compress competitive response windows. For New Entrants and Emerging Players: FDA Class I medical device pathway eligibility in the United States opens a window for clinical-grade positioning that unlocks HSA/FSA reimbursement channels underserved by fitness-branded incumbents. Target Fortune 500 corporate wellness facilities in Illinois and Ohio where recovery equipment penetration sits below 15 percent. Pursue white-label manufacturing partnerships with established Shenzhen electronics fabricators to bypass capital-intensive production buildout. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given FDA substantiation requirements that favor clinical trial documentation and quality management infrastructure. Long-term viability hinges on multi-channel presence spanning direct-to-consumer, athletic institutional, and clinical reimbursement pathways. Monitor FTC enforcement action on therapeutic claims as inflection indicator for marketing expenditure restructuring across the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Hardware Development | Force-sensing resistor arrays automate pressure adjustment for standardized athlete treatment protocols. |
| Bluetooth-Enabled Prescription Integration | Telehealth platform convergence enables remote protocol adjustment by licensed physical therapists. |
| Neodymium Supply Security | Captive magnet sourcing insulates margin stability from Chinese export control volatility. |
| Corporate Wellness Channel Expansion | Fortune 500 onsite fitness facility penetration in Illinois and Ohio remains under 15 percent. |
| FDA Class I Certification Investment | Medical device pathway unlocks HSA/FSA reimbursement eligibility beyond out-of-pocket fitness budgets. |
Research Methodology
SEC filings, FDA 510(k) databases, and athletic department procurement records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with biomedical engineers, physical therapy clinic directors, NCAA athletic equipment managers, and GPO contract specialists validated demand assumptions and pricing elasticity estimates. Bottom-up unit shipment modeling triangulated against top-down expenditure analysis across HSA/FSA reimbursement channels and institutional procurement databases.
Top-down macroeconomic indicators and bottom-up segment-level unit economics converged across the projection horizon. Segmentation dimensions modeled include product mobility configuration, target buyer archetype, battery runtime specification, and price tier alignment with certification grade. CAGRs were derived from regression analysis of historical shipment data against athletic infrastructure investment indices and lithium-ion battery cost curves. Motor torque specification evolution and FDA guidance timeline uncertainty informed scenario-weighted outcomes.
Caveats apply where FTC enforcement intensity on therapeutic claims or rare-earth export restriction severity could materially shift the outlook for premium-tier manufacturers. Forecasts reflect documented assumptions regarding battery energy density improvement trajectories and institutional procurement consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Razor Market
Personal Grooming Products
Epilators Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Organic and Natural Tampons Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
Global Beard Balm Market
Personal Grooming Products
Baby Oil Market
Personal Grooming Products
Shaving Care Market
Personal Grooming Products
Infant Mosquito Repellent Market