
 Global Massage Guns Market | 2026-2036
Global Massage Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Global Massage Guns Market Foresight
Brushless motor miniaturization is reshaping how massage guns achieve percussive force without thermal degradation or acoustic penalty. Therabody leverages proprietary acoustic dampening to sustain premium positioning across professional sports partnerships. Hyperice anchors North American distribution through controlled placement in NBA and NFL training facilities. Ekrin Athletics specializes in ergonomically angled handles that differentiate its lineup for self-administered physical therapy.
A massage gun is a handheld percussive therapy device employing a reciprocating head driven by an electric motor, typically delivering strokes between 1,200 and 3,200 percussions per minute at amplitude depths of 10 to 16 millimeters, designed to modulate soft tissue stiffness and enhance localized blood flow. Cordless configurations now dominate unit volume as lithium-ion energy density eliminates tethered operation without sacrificing stall force. Brushless motor technology captures the highest margin pool due to reduced friction wear and extended duty cycles, while compact form factors represent the fastest-growing product type as portability becomes a decisive purchase criterion for personal users and travel-oriented fitness consumers.
FDA oversight of therapeutic claims constrains how manufacturers label recovery benefits in the United States, while CE marking under the EU Medical Device Regulation shapes market access for devices positioned toward clinical applications in Germany and France. ISO 13485 certification increasingly functions as a procurement filter for rehabilitation clinics and wellness resorts evaluating supplier qualification. Stakeholders must monitor whether regulatory bodies in China and Japan extend medical device classification to percussive therapy instruments, as this would fundamentally alter compliance costs and channel eligibility across the industry's largest manufacturing bases and emerging demand centers.
Market Dynamics
Brushless motor miniaturization and lithium-ion density gains are compressing the performance gap between compact personal units and professional-grade devices, forcing manufacturers to recalibrate tier differentiation around acoustic engineering and ergonomic patents rather than raw stall force specifications.
Growth Catalysts
- FDA therapeutic claim pathways:Rehabilitation clinics in the United States now qualify percussive devices for insurance reimbursement when paired with documented treatment protocols, expanding institutional procurement volumes.
- Brushless motor efficiency thresholds:Reduced thermal degradation extends duty cycles from 20 minutes to 45 minutes, enabling continuous clinical use without cooldown intervals that previously disrupted therapy workflows.
- Germany's sports medicine infrastructure:Bundesliga training facilities and Olympic preparation centers standardize recovery protocols around percussive therapy, creating reference demand that cascades into consumer segments.
Market Restraints
- Lithium-ion supply concentration:Cathode precursor refining clusters in China's Hunan and Fujian provinces expose manufacturers to export licensing volatility and forced technology transfer requirements.
- EU Medical Device Regulation compliance costs:CE marking under MDR Annex IX requires clinical evaluation reports and notified body intervention, adding 18-24 months to European market entry timelines.
- Manual therapy substitution:Licensed massage therapists in Australia and Canada contest device efficacy claims, limiting penetration among consumers seeking credential-backed recovery modalities.
Strategic Opportunities
- India's fitness infrastructure buildout:Urban gym chains in Mumbai and Bangalore deploy recovery stations as membership differentiators, creating bulk procurement channels absent five years prior.
- ISO 13485 certification arbitrage:Wellness resorts and cruise lines now mandate quality management certification for supplier qualification, enabling premium positioning for compliant manufacturers.
- Acoustic dampening convergence with AI:Adaptive motor control algorithms adjust percussion patterns based on tissue resistance feedback, opening software-subscription revenue streams alongside hardware sales.
Industry Challenges
- Acoustic engineer talent scarcity:Noise reduction below 55 decibels requires specialized motor control firmware expertise concentrated among automotive and aerospace talent pools with limited mobility into consumer wellness.
- Patent thickets around ergonomic handle geometries:Established players hold broad design patents on 15-degree angled grips, forcing new entrants into costly licensing negotiations or inferior form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Massage Guns Market |
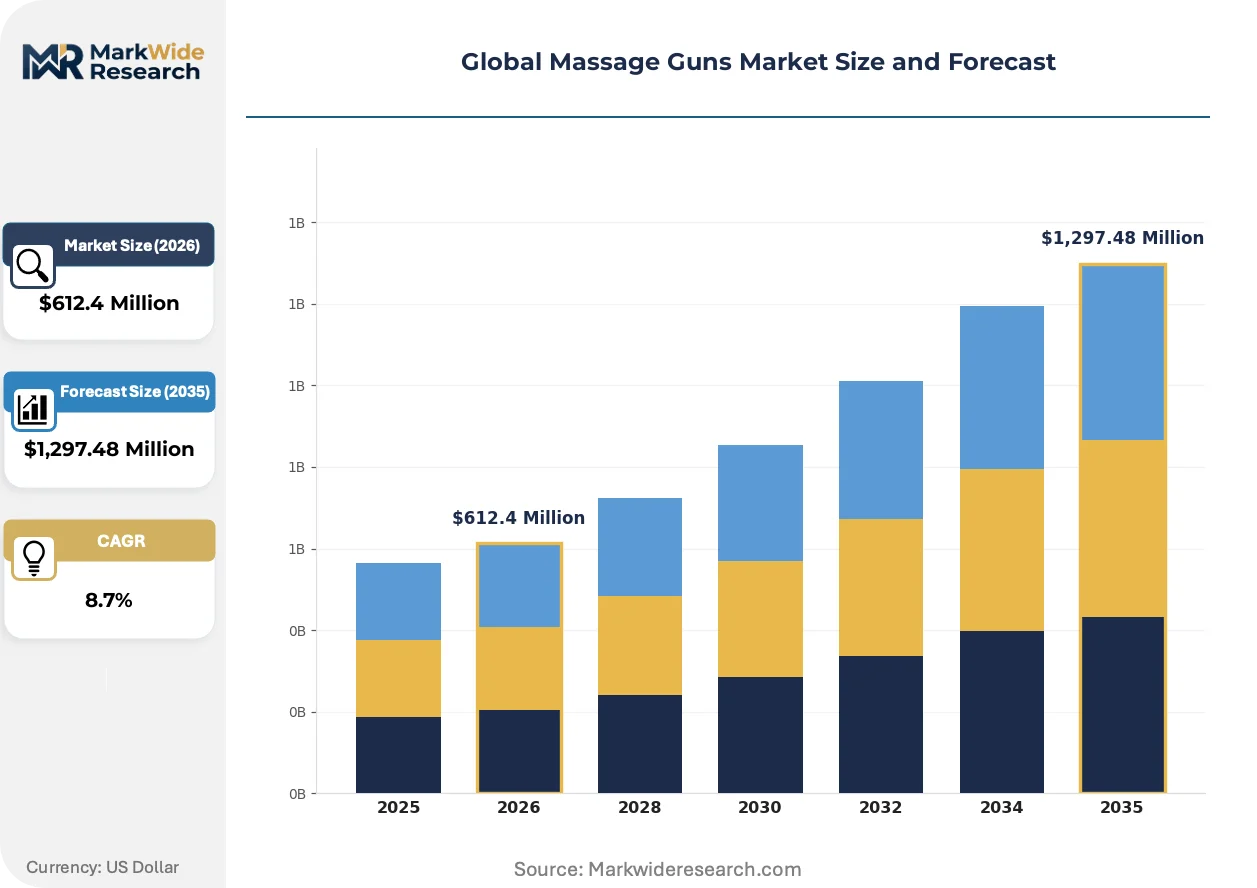
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Cordless, Percussion, Rechargeable, Compact Technology: Brushless Motor, Pneumatic, Electromagnetic, Vibration, Pneumatic Pump Application: Sports Recovery, Physical Therapy, Fitness Training, Posture Correction, Stress Relief End User: Fitness Centers, Rehabilitation Clinics, Personal Users, Wellness Resorts, Professional Therapists |
| Companies Covered | Therabody, Hyperice, TimTam, LifePro, RENPHO, HoMedics, Bob and Brad, Ekrin Athletics, Toloco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Massage Guns Market Shifts & Advancements
Intelligent motor control and regulatory medicalization are transforming percussive therapy from fitness accessory into clinical infrastructure, compressing the boundary between wellness and rehabilitation equipment categories.
Adaptive percussion algorithms embedded in brushless motor controllers is virtualizing the therapist's manual palpation function. Professional sports teams in Australia's AFL and NRL leagues deploy these systems for real-time tissue compliance mapping. The technology is virtualizing traditional massage therapy assessment protocols into quantifiable biomechanical data streams that athletic trainers integrate with load management software.
Japan's PMDA is evaluating whether percussive therapy devices qualify as Class II medical instruments under the Pharmaceutical and Medical Devices Act, a classification that would mandate clinical trial documentation and quality management system audits. Domestic manufacturers METI oversees have begun pre-submission consultations to align technical files with potential requirements. This regulatory trajectory is compressing development timelines as firms race to establish predicate device pathways before formal guidance issuance.
Direct-to-clinic procurement models are displacing traditional distributor networks for institutional buyers. Rehabilitation centers in Germany's Rhine-Ruhr corridor now negotiate volume contracts directly with Shenzhen manufacturers, bypassing European medical device distributors that previously captured 35-40 point margins. This channel compression is most visible among mid-sized clinic chains seeking ISO 13485-certified supply without intermediary markup layers.
Global Massage Guns Market Segmentation
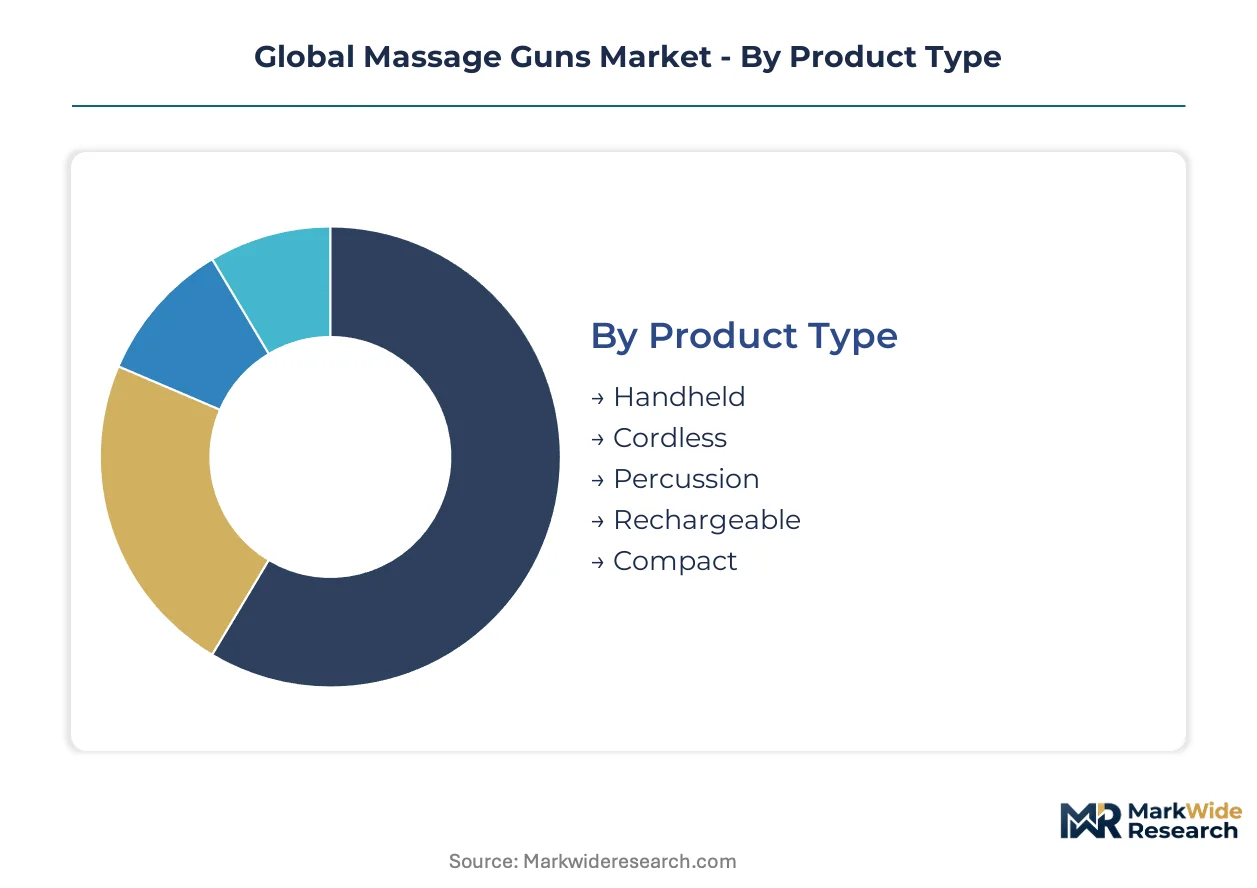
Massage gun segmentation reveals how technical specifications, use environments, and buyer sophistication create distinct commercial battlegrounds. Manufacturers must align motor engineering, acoustic profiles, and certification pathways to specific segment requirements rather than pursuing universal product architectures.
Product Type:
Mature handheld configurations coexist with emerging compact formats that sacrifice raw stall force for portability.
- Handheld:Full-size ergonomic chassis with 10-16mm amplitude and 40-60 pound stall force remain the clinical standard. Demand concentrates among professional therapists in Germany and the United States where extended duty cycles justify larger battery packs and brushless motor assemblies.
- Cordless:Lithium-ion configurations have displaced tethered units across all price tiers, with energy density improvements from 2,000 to 3,000 mAh eliminating runtime anxiety for personal users. Australian fitness consumers prioritize cordless operation for outdoor training recovery protocols.
- Percussion:Reciprocating head mechanisms delivering 1,200-3,200 strokes per minute define the core therapeutic action. The segment captures institutional procurement from Bundesliga training facilities standardizing recovery station specifications.
- Rechargeable:USB-C fast-charging interfaces now standardize at 18-25 watt input, reducing full-cycle recharge times to 90 minutes. Wellness resorts in Dubai and Singapore specify rechargeable units for guest amenity programs.
- Compact:Miniaturized form factors below 1.5 pounds sacrifice 20-30% stall force for travel compatibility. Personal users in Japan and South Korea drive fastest adoption as gym bag portability becomes a decisive purchase criterion.
Handheld configurations retain volume leadership; compact formats hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium brushless implementations from legacy electromagnetic alternatives.
- Brushless Motor:Permanent magnet synchronous designs eliminate carbon brush friction, extending motor life beyond 10,000 hours while reducing acoustic output below 55 decibels. Rehabilitation clinics in the United States mandate brushless certification for insurance reimbursement eligibility.
- Pneumatic:Compressed air-driven reciprocation delivers superior stall force consistency for high-torque clinical applications. German sports medicine facilities deploy pneumatic systems for Olympic athlete preparation centers where thermal management is critical.
- Electromagnetic:Solenoid-based actuation offers cost advantages at the expense of efficiency and duty cycle limitations. Budget personal users in India and Southeast Asia dominate residual demand as price-sensitive entry points.
- Vibration:Oscillating plate mechanisms at 20-50 Hz target superficial tissue modulation rather than deep percussive penetration. Stress relief applications in Japanese corporate wellness programs favor vibration for seated desk-worker protocols.
- Pneumatic Pump:Integrated compressor systems enable variable pressure calibration for tissue-specific treatment protocols. Australian physiotherapy chains evaluate pneumatic pump integration for load management correlation with GPS athlete tracking data.
Brushless motor systems command margin leadership; pneumatic architectures gain share in institutional procurement.
Application:
Volume concentrates in performance recovery while medicalization opens reimbursement pathways.
- Sports Recovery:Post-exercise lactate clearance and fascia mobility protocols dominate professional team deployments. AFL and NRL franchises in Australia standardize percussive therapy within 30-minute post-match recovery windows.
- Physical Therapy:FDA-cleared treatment protocols for myofascial pain syndrome enable insurance billing in the United States. Rehabilitation clinics now document percussive therapy within episode-based care bundles.
- Fitness Training:Pre-workout activation and inter-set recovery drive gym chain procurement. Urban fitness centers in Mumbai and Bangalore install recovery stations as membership differentiators.
- Posture Correction:Upper trapezius and levator scapulae targeting addresses desk-worker musculoskeletal complaints. Corporate wellness programs in Japan integrate posture-focused protocols with ergonomic workstation assessments.
- Stress Relief:Parasympathetic activation through vagus nerve stimulation guides product positioning for anxiety management applications. Wellness resorts in Thailand and Bali incorporate stress relief programming into multi-day retreat packages.
Sports recovery retains volume leadership; physical therapy holds the steepest expansion curve.
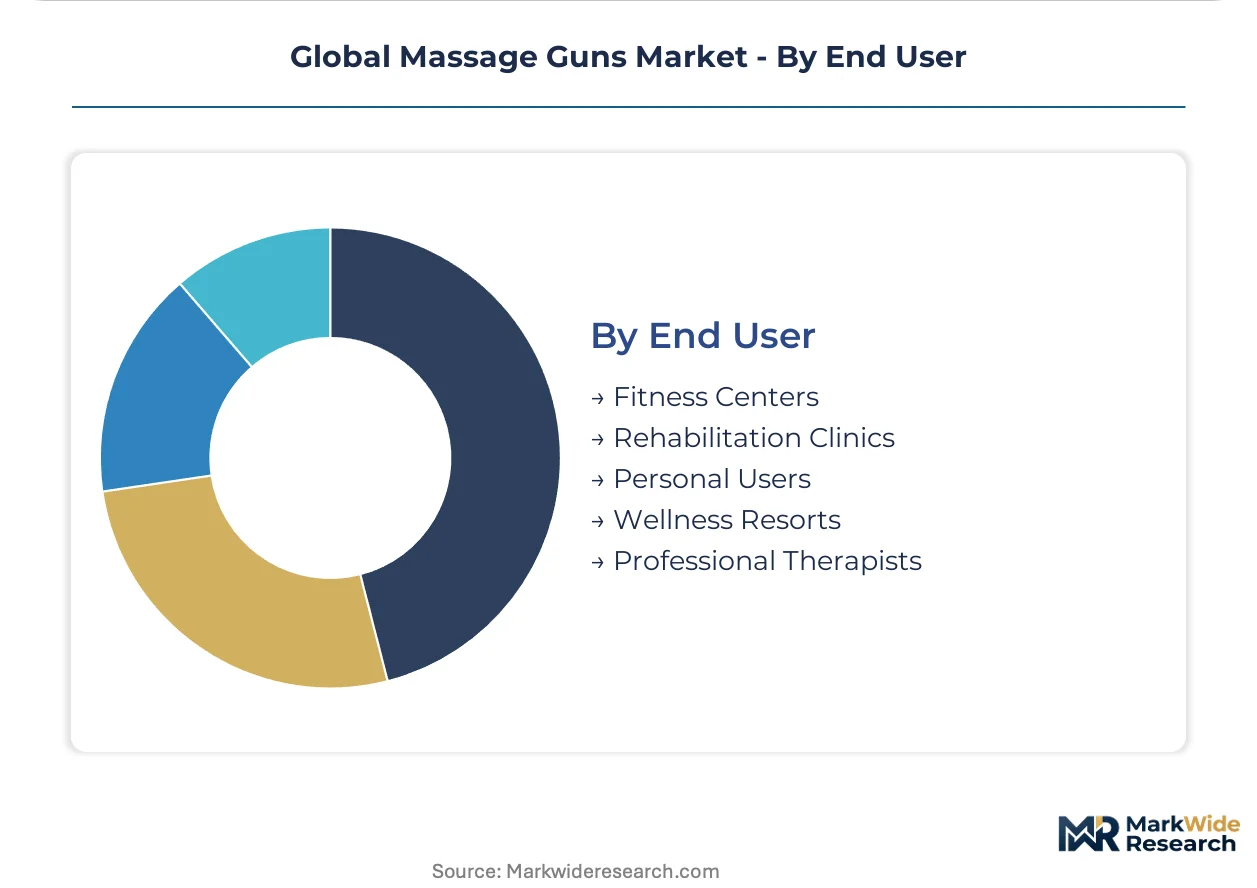
End User:
Customer type segmentation separates high-volume personal consumption from high-margin institutional procurement.
- Fitness Centers:Commercial-grade durability specifications with 8+ hour daily duty cycles define procurement criteria. Gold's Gym and Equinox deployments in the United States establish reference specifications for mid-market chains.
- Rehabilitation Clinics:ISO 13485 certification and FDA therapeutic claim compliance filter supplier qualification. German clinic chains in the Rhine-Ruhr corridor negotiate direct manufacturer contracts bypassing traditional distributor markups.
- Personal Users:Self-administered recovery drives the largest unit volumes with price sensitivity concentrated below $200 retail. Amazon and direct-to-consumer channels capture dominant share in North American and European personal segments.
- Wellness Resorts:Aesthetic design integration and whisper-quiet operation below 50 decibels prioritize guest experience over raw performance. Mandarin Oriental and Four Seasons procurement specifications influence premium tier engineering priorities.
- Professional Therapists:Licensed massage practitioners and athletic trainers represent the fastest-expanding institutional segment as continuing education curricula formalize percussive therapy competencies. Canadian provincial regulatory colleges now evaluate device efficacy claims within scope-of-practice determinations.
Personal users retain volume leadership; professional therapists hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dominance in lithium-ion cathode precursor refining creates export-import asymmetry, with Hunan and Fujian province clusters supplying battery cells to assembly operations in the United States, Germany, and Australia. This concentration exposes manufacturers to licensing volatility while compressing margins for brands without captive cell supply.
United States
FDA therapeutic claim pathways now enable insurance reimbursement for percussive devices paired with documented treatment protocols, expanding institutional procurement volumes. Rehabilitation clinics in Texas and Florida lead adoption, with episode-based care bundles integrating percussive therapy for myofascial pain syndrome. Los Angeles-based fitness chains establish reference specifications that cascade into mid-market consumer segments.
Germany
Bundesliga training facilities and Olympic preparation centers in Bavaria and North Rhine-Westphalia standardize recovery protocols around percussive therapy, creating reference demand that filters into consumer markets. CE marking under EU MDR Annex IX requires clinical evaluation reports, adding 18-24 months to market entry timelines. The Rhine-Ruhr corridor hosts direct manufacturer negotiations bypassing traditional distributor markups.
Australia
AFL and NRL franchises deploy adaptive percussion systems for real-time tissue compliance mapping, with post-match recovery windows standardized within 30 minutes. TGA oversight shapes therapeutic claim boundaries, while licensed massage therapists in Victoria and New South Wales contest device efficacy claims. Sydney and Melbourne gym chains install recovery stations as membership differentiators.
Japan
PMDA evaluation of Class II medical device classification under the Pharmaceutical and Medical Devices Act compresses development timelines as firms race to establish predicate pathways. METI oversight drives pre-submission consultations among domestic manufacturers. Corporate wellness programs in Tokyo and Osaka integrate posture-focused vibration protocols for desk-worker populations.
India
Urban gym chains in Mumbai and Bangalore deploy recovery stations as membership differentiators, creating bulk procurement channels absent five years prior. BIS certification requirements filter supplier qualification for institutional buyers. The Maharashtra-Gujarat industrial corridor attracts contract manufacturing investments from brands seeking to serve Middle East and African demand centers.
Global Massage Guns Market Competitive Landscape
On the supply side, the industry is bifurcated between premium-tier specialists with acoustic engineering patents and volume-oriented assemblers competing on lithium-ion cell integration efficiency. The vendor base separates into three strategic archetypes: wellness lifestyle brands anchored by athlete endorsements, clinical-grade manufacturers pursuing ISO 13485 certification, and direct-to-consumer specialists optimizing Amazon algorithmic visibility. Competitive moves concentrate on ergonomic design patent licensing and backward integration into brushless motor controller firmware development.
Among North American wellness technology developers, Therabody and Hyperice exemplify the endorsement-driven premium archetype, while Ekrin Athletics occupies a position within the ergonomic specialization tier. These three entities represent distinct competitive vectors: acoustic dampening intellectual property, controlled placement in professional sports facilities, and anatomically angled handle geometries respectively. Chinese contract manufacturers supply cell integration and final assembly to brands across all tiers, with Shenzhen-based operations serving both direct-to-clinic procurement models and traditional retail distribution.
| Leading Market Players |
|---|
| Therabody |
| Hyperice |
| TimTam |
| LifePro |
| RENPHO |
| HoMedics |
| Bob and Brad |
| Ekrin Athletics |
| Toloco |
| Others |
Supply & Pricing Matrix
Hunan and Fujian province cathode precursor refining clusters concentrate lithium-ion cell supply for massage gun assembly operations, anchoring margin pools in brushless motor controller firmware and acoustic dampening intellectual property rather than commodity battery integration. This upstream concentration forces downstream brands to compete on patented ergonomic geometries and ISO 13485 certification tiers that filter institutional procurement.
Pricing Analysis
Professional therapists and rehabilitation clinics anchor pricing stratification across premium, standard, and economy tiers. FDA therapeutic claim compliance and ISO 13485 certification grade separate premium positioning from mass-market alternatives, while acoustic engineering below 55 decibels commands brand premium. Cost compression in economy tiers intensifies as electromagnetic motor alternatives from Shenzhen contract manufacturers flood direct-to-consumer channels. Personal users below $200 retail demonstrate highest price sensitivity; wellness resorts and German clinic chains show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for brands without captive cell supply. Lithium-ion cathode materials, brushless motor assemblies, and injection-molded ergonomic chassis draw from Chinese, South Korean, and Japanese manufacturing bases. Single-source vulnerability concentrates in Hunan province cathode refining capacity. Distribution runs through direct-to-clinic procurement models displacing traditional medical device distributors in Germany and the United States, alongside Amazon algorithmic visibility for personal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. ISO 13485 certification and FDA therapeutic claim pathways create switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Pre-empt emerging ergonomic patent challenges by securing licensing agreements with acoustic engineering specialists from automotive talent pools. Defend margin position through backward integration into brushless motor controller firmware development rather than commodity assembly. Accelerate direct-to-clinic channel control in Germany's Rhine-Ruhr corridor before distributor networks reconstitute. For New Entrants and Emerging Players: Pursue compact form factor white space in Japanese and South Korean personal user segments where travel portability drives purchase criteria. Target India's urban gym chain recovery station deployments as the most penetrable institutional geography. Lead with USB-C fast-charging specifications and sub-1.5-pound chassis as differentiated go-to-market angle against established acoustic engineering leaders. For Investors and Strategic Acquirers: Capital is best deployed toward clinical-grade manufacturers with ISO 13485 certification and predicate device pathways under Japan's PMDA evaluation. Long-term viability over the projection horizon hinges on regulatory medicalization convergence between wellness and rehabilitation equipment categories. Watch PMDA Class II medical device classification guidance issuance as the critical inflection signal for compliance cost restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks insurance reimbursement eligibility for rehabilitation clinics in the United States and German institutional procurement. |
| Acoustic Engineering Patent Licensing | Secures sub-55 decibel operation that wellness resorts and Four Seasons procurement specifications mandate. |
| Direct-to-Clinic Channel Development | Bypasses 35-40 point distributor markups in Germany's Rhine-Ruhr corridor clinic chains. |
| Brushless Motor Controller Firmware Acquisition | Captures adaptive percussion algorithm capabilities for AFL and NRL franchise tissue compliance mapping deployments. |
| PMDA Predicate Device Pathway Establishment | Positions ahead of Class II medical device classification mandates under Japan's Pharmaceutical and Medical Devices Act. |
Research Methodology
Initial hypotheses were tested against primary input from rehabilitation clinic procurement managers, professional athletic trainers, brushless motor engineering directors, and wellness resort operations executives and refined through secondary validation. FDA 510(k) filings, CE marking documentation under EU MDR Annex IX, TGA therapeutic goods registrations, and PMDA pre-submission consultation records anchored regulatory trajectory assessment. Bottom-up unit shipment modeling across product type and technology segments triangulated against top-down category value estimates.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, motor technology tier, application environment, and end-user procurement sophistication. CAGRs derived from logistic diffusion curves fitted to institutional adoption patterns and personal user replacement cycles. Brushless motor efficiency thresholds and lithium-ion energy density improvement trajectories served as key technology input variables.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Shenzhen contract manufacturers into branded distribution would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Global Mosquito Repellent Products Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
AI Toothbrush Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Wet Shave Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Disposable Razor Market