
 Infant Mosquito Repellent Market | 2026-2036
Infant Mosquito Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Mosquito Repellent Market Insights
Pharmacy chains and specialty baby retailers is restructuring the channel mix for infant mosquito repellents, shifting volume away from general merchandise outlets. SC Johnson & Son, Inc. leverages its household pest-control infrastructure to maintain shelf dominance in North American drugstores. Godrej Consumer Products Limited anchors its position through deep distribution in Indian kirana networks and modern trade. Reckitt Benckiser Group plc competes on pediatric brand trust built through its broader hygiene portfolio.
Infant mosquito repellents comprise topical and spatial formulations engineered with reduced-concentration active agents, typically below adult-equivalent dosages, to minimize dermal absorption and inhalation risk in neonates and toddlers. These products serve the primary commercial purpose of preventing arthropod-borne disease transmission while accommodating immature metabolic pathways and sensitive integumentary systems. DEET-based formulations still occupy the largest revenue share among active ingredient categories, though picaridin and oil of lemon eucalyptus segments are gaining fastest as parents reject synthetic chemistry for daily-use scenarios. Online retailers lead sales channel growth, capturing subscription-driven repeat purchases that supermarkets struggle to replicate.
The US EPA mandates specific efficacy and safety labeling for infant-directed repellents, while India's CDSCO oversees cosmetic-drug hybrid classifications that determine retail channel access for botanical formulations. REACH compliance in Europe restricts certain synthetic active concentrations, creating formulation divergence between regulatory jurisdictions. Stakeholders must monitor evolving pediatric toxicology standards and channel-specific registration requirements to sustain market access across divergent compliance regimes.
Market Dynamics
Infant mosquito repellent manufacturers face a structural pivot as the US EPA's pediatric-specific efficacy-testing requirements force reformulation toward botanical actives, compressing development timelines while expanding addressable segments.
Growth Catalysts
- India's Monsoon-Driven Demand Cycles:Seasonal vector-borne disease surges in Mumbai, Delhi, and Bangalore create predictable replenishment patterns among urban middle-class households, stabilizing inventory planning for modern trade and e-commerce channels.
- REACH-Compliant Botanical Formulations:European restrictions on synthetic active concentrations accelerate R&D investment in oil of lemon eucalyptus and citronella derivatives, opening premium positioning opportunities for compliant suppliers.
- Subscription Commerce Infrastructure:Online retailers capture recurring revenue through auto-replenishment models that pharmacy chains struggle to replicate, deepening customer lifetime value in direct-to-consumer segments.
Market Restraints
- Active Ingredient Supply Concentration:Synthetic pyrethroid and refined botanical oil production clusters in Chinese and Indian chemical processing zones, creating geographic vulnerability to environmental compliance shutdowns and export licensing delays.
- CDSCO Classification Friction:India's cosmetic-drug hybrid determinations for botanical formulations force dual registration pathways, extending commercialization timelines by 18-24 months for products crossing the therapeutic claims threshold.
- DEET Perception Substitution:Parental rejection of synthetic chemistry for daily-use scenarios drives volume erosion toward picaridin and plant-based alternatives, compressing margin structures in legacy formulation portfolios.
Strategic Opportunities
- Underpenetrated Rural India:Kirana network expansion into tier-3 and tier-4 cities offers volume scale for affordable sachet and single-use formats priced below premium modern trade offerings.
- Wearable Spatial Devices:Convergence of ultrasonic emitters with clip-on and stroller-attachment formats creates new usage occasions beyond topical application, capturing parental preference for non-contact protection.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework for specialty chemicals reduces capital intensity for domestic active ingredient synthesis, enabling backward integration into botanical extraction and refinement.
Industry Challenges
- Pediatric Toxicology Expertise Scarcity:Dermal absorption modeling and neonatal metabolic pathway assessment require specialized toxicologists whose limited availability extends safety dossier preparation timelines.
- Multi-Jurisdiction Labeling Complexity:Divergent EPA, CDSCO, and ECHA efficacy-claim standards force SKU proliferation and packaging fragmentation, raising working capital requirements for inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Mosquito Repellent Market |
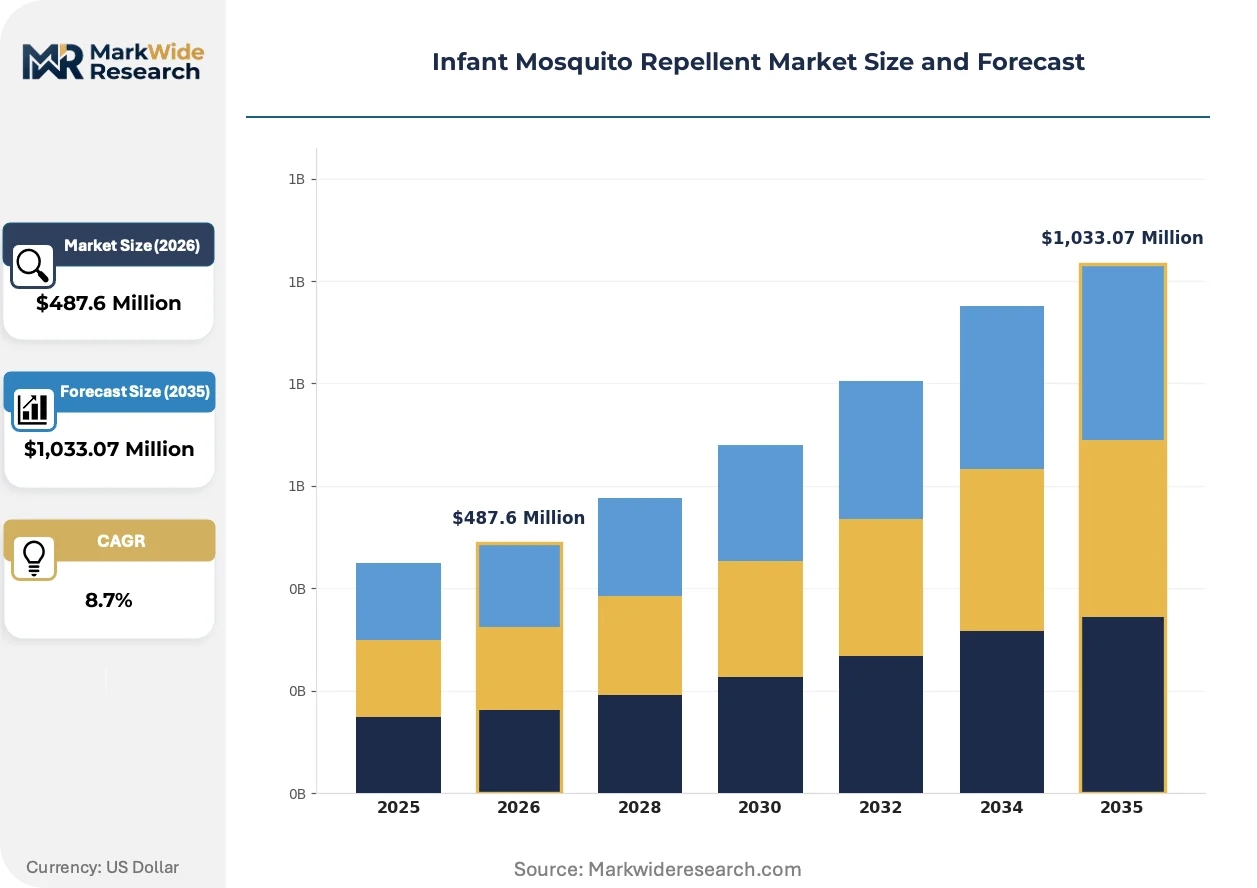
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Lotions, Wipes, Plugins Active Ingredient: Picaridin, DEET, Oil of Lemon Eucalyptus, IR3535 Packaging Type: Tube, Bottle, Spray Can, Sachet Sales Channel: Online Retailers, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | SC Johnson & Son, Inc., Reckitt Benckiser Group plc, Godrej Consumer Products Limited, Spectrum Brands Holdings, Inc., Dabur India Limited, Johnson & Johnson Services, Inc., 3M Company, Sawyer Products, Inc., Babyganics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Mosquito Repellent Market Trends and Innovations
Formulation science and channel architecture are undergoing parallel transformation as botanical actives achieve parity with synthetic benchmarks and subscription models displace transactional retail relationships.
Encapsulated time-release technologies are integrating citronella and lemongrass oils into polymer matrices that extend protection windows from two hours to six hours. Premium infant apparel brands in the United States and Germany are adopting these microcapsule treatments for clothing and bedding lines. This integration is compressing the addressable market for standalone topical sprays in daily-use scenarios.
REACH restrictions on synthetic active concentrations are forcing European manufacturers to reformulate DEET-based portfolios toward picaridin and PMD (p-menthane-3,8-diol) alternatives. The industrial consequence is a bifurcation between high-efficacy travel formulations and reduced-concentration daily-use products. German and French pharmacy chains are responding by segmenting shelf space into "intensive protection" and "gentle daily" zones, training staff on active-ingredient selection criteria.
Direct-to-consumer subscription models are displacing supermarket impulse purchases as the dominant replenishment channel for repeat buyers. Specialty baby retailers and pharmacy chains are losing volume to e-commerce platforms offering bundled auto-ship programs with pediatrician endorsement content. This channel rotation is most visible in India's urban middle-class households, where smartphone penetration and UPI payment infrastructure enable frictionless recurring transactions.
Infant Mosquito Repellent Market Segmentation
Infant mosquito repellent manufacturers navigate divergent regulatory pathways depending on formulation chemistry and application mode. Segmentation reveals how certification burdens cluster around active ingredient choices while packaging and channel decisions determine geographic access and margin capture.
Product Type:
Sprays and lotions carry EPA pediatric-specific efficacy-testing requirements for dermal application to children under three months, while spatial formats face lighter registration burdens in most jurisdictions.
- Sprays:Aerosol and pump-dispersed formulations dominate pharmacy shelf space in North American drugstores. Concentration caps for DEET and picaridin in US formulations drive parental preference toward lower-dose botanical alternatives for daily nursery use.
- Lotions:Emulsion-based creams with time-release encapsulation extend protection windows for overnight infant sleep scenarios. German and French pharmacy chains segment lotions into "intensive protection" versus "gentle daily" zones based on active concentration tiers.
- Wipes:Pre-saturated towelettes offer portable single-use convenience for travel and stroller-based protection. Indian modern trade channels stock affordable wipe formats in monsoon-season promotional stacks.
- Plugins:Ultrasonic and heated mat spatial devices bypass dermal absorption concerns entirely. Premium positioning in US and German markets targets parents rejecting topical chemistry for neonatal environments.
Sprays sit at the top of the volume ranking, with plugins climbing the fastest as non-contact protection gains parental traction.
Active Ingredient:
Ingredient selection determines which regulatory framework governs market entry, with botanical actives facing cosmetic-drug hybrid classifications in India and synthetic alternatives triggering EPA efficacy mandates in the United States.
- Picaridin:Synthetic piperidine derivative delivers DEET-comparable efficacy without the plasticizer damage and odor complaints that erode parental acceptance. European REACH restrictions on synthetic concentrations position picaridin as the compliant bridge between efficacy and regulatory access.
- DEET:N,N-diethyl-meta-toluamide remains the reference standard for high-efficacy travel formulations despite daily-use volume erosion. US EPA pediatric labeling requirements compress margin structures through extended safety dossier preparation timelines.
- Oil of Lemon Eucalyptus:Botanical extract refined to PMD (p-menthane-3,8-diol) delivers CDC-recognized protection without synthetic classification. CDSCO cosmetic-drug determinations in India force dual registration pathways that extend commercialization timelines.
- IR3535:Amino acid-derived synthetic biopesticide offers lower toxicity profiles than DEET with comparable duration. Limited production scale and higher raw material costs restrict penetration to premium positioning in developed markets.
DEET commands the largest revenue base, though oil of lemon eucalyptus gains share fastest as European REACH enforcement and parental chemistry rejection converge.
Packaging Type:
Format economics determine channel access, with unit-dose sachets penetrating Indian kirana networks while pump bottles dominate US pharmacy replenishment cycles.
- Tube:Collapsible aluminum or laminate tubes protect lotion viscosity in tropical climates. Indian tier-3 and tier-4 city expansion favors tube formats for kirana network affordability.
- Bottle:PET and glass pump bottles anchor pharmacy chain merchandising in North American and European modern trade. Subscription commerce auto-replenishment programs favor bottle formats for shipping efficiency.
- Spray Can:Pressurized aerosol containers deliver fine-mist coverage for nursery spatial treatment. Environmental compliance shutdowns in Chinese chemical processing zones create supply vulnerability for propellant and canister components.
- Sachet:Single-use foil pouches enable trial-size distribution and rural affordability in price-sensitive markets. Godrej Consumer Products Limited leverages sachet formats for deep distribution in Indian kirana networks.
Bottle formats lead volume, with sachets expanding most quickly through rural India penetration strategies.
Sales Channel:
Channel selection determines customer lifetime value capture, with subscription models deepening retention while supermarket impulse purchases erode under smartphone-enabled replenishment habits.
- Online Retailers:Direct-to-consumer platforms capture auto-replenishment subscriptions with pediatrician endorsement content. Indian UPI payment infrastructure and smartphone penetration enable frictionless recurring transactions among urban middle-class households.
- Specialty Stores:Baby-focused retailers offer curated assortment and staff training on active-ingredient selection criteria. SC Johnson & Son, Inc. maintains shelf dominance through category management investments in North American specialty chains.
- Pharmacies:Drugstore chains anchor trust-based purchasing for first-time parents seeking pharmacist guidance. German and French pharmacy staff training programs on EPA versus REACH formulation differences drive premium tier capture.
- Supermarkets:General merchandise outlets lose volume to digital channels as replenishment shifts from impulse to planned purchase. Seasonal promotional stacking in Indian modern trade survives through monsoon-driven demand cycles.
Pharmacies retain the largest transaction volume, with online retailers gaining share fastest through subscription infrastructure and bundled auto-ship programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions offering streamlined pediatric-toxicology dossier pathways and lower cost-of-compliance thresholds. India and China absorb contract manufacturing volume from European and North American brands seeking to bypass REACH concentration caps and EPA extended-testing timelines.
United States
Pediatric clinic networks and maternity retail chains in Texas and California are expanding shelf space for infant-safe formulations ahead of peak mosquito season. The EPA's stringent efficacy-testing requirements for products applied to children under three months compress development timelines and elevate compliance costs. SC Johnson & Son, Inc. leverages its household pest-control infrastructure to maintain shelf dominance in drugstore chains across the Midwest and Southeast.
Germany
Pharmacy chains in Bavaria and North Rhine-Westphalia segment shelf space into "intensive protection" and "gentle daily" zones based on active concentration tiers. REACH restrictions on synthetic active concentrations force reformulation of DEET-based portfolios toward picaridin and PMD alternatives. Industrial clusters around Frankfurt and Hamburg host formulation science facilities developing encapsulated time-release technologies for premium infant apparel brands.
India
Monsoon-season vector-borne disease cycles in Mumbai, Delhi, and Bangalore drive consistent category purchasing among urban middle-class households. The CDSCO's cosmetic-drug hybrid classifications for botanical formulations force dual registration pathways that extend commercialization timelines by 18-24 months. Godrej Consumer Products Limited anchors its position through deep distribution in kirana networks and modern trade penetration across Maharashtra and Karnataka.
China
Active ingredient production clusters in Zhejiang and Jiangsu chemical processing zones supply synthetic pyrethroid and refined botanical oils to global formulators. Environmental compliance shutdowns and export licensing delays create geographic vulnerability in the supply chain. Domestic manufacturers are capturing contract manufacturing volume from Western brands seeking cost advantages in pediatric-toxicology dossier preparation.
Brazil
ANVISA oversight of pediatric personal care products creates a compliance pathway distinct from pharmaceutical registration, accelerating market entry for botanical formulations. Urban middle-class households in São Paulo and Rio de Janeiro demonstrate rising willingness-to-pay for DEET-free alternatives. Regional distributors are building direct-to-consumer subscription infrastructure modeled on Indian and US e-commerce platforms.
Infant Mosquito Repellent Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend from adult pest-control franchises into pediatric-specific formulations. The vendor base stratifies across three tiers: multinational household goods conglomerates with existing retail infrastructure, regional FMCG specialists with deep distribution in emerging markets, and direct-to-consumer pure-plays built on subscription commerce. Two strategic archetypes predominate: synthetic-chemistry incumbents defending DEET and picaridin portfolios against botanical substitution, and botanical-first challengers capturing parental chemistry rejection through oil of lemon eucalyptus and citronella positioning. Competitive moves concentrate on geographic expansion into underpenetrated rural India and technology licensing for wearable spatial devices.
Within the multinational conglomerate tier, SC Johnson & Son, Inc., Reckitt Benckiser Group plc, and Godrej Consumer Products Limited occupy positions exemplifying divergent geographic anchoring strategies. SC Johnson represents North American drugstore channel dominance through category management investments. Reckitt Benckiser exemplifies pediatric brand trust built through broader hygiene portfolio affiliation. Godrej Consumer Products Limited anchors the emerging-market specialist archetype through kirana network penetration and modern trade expansion in price-sensitive segments.
| Leading Market Players |
|---|
| SC Johnson & Son, Inc. |
| Reckitt Benckiser Group plc |
| Godrej Consumer Products Limited |
| Spectrum Brands Holdings, Inc. |
| Dabur India Limited |
| Johnson & Johnson Services, Inc. |
| 3M Company |
| Sawyer Products, Inc. |
| Babyganics |
| Others |
Pricing and Supply Chain Analysis
Urban middle-class parents in India anchor demand concentration, driving a subscription-dominated pricing model where auto-replenishment discounts compress transactional premiums while locking in lifetime value.
Pricing Analysis
Retailer markup layers in North American drugstore chains absorb the steepest margin compression as pharmacy staff training investments and pediatric-specific shelf space fees inflate landed costs. Three-tier pricing structure across premium, standard, and economy levels separates CDC-recognized synthetic formulations from REACH-compliant botanicals and unregistered local alternatives. Price erosion runs through the standard tier as Indian kirana networks and direct-to-consumer platforms undercut modern trade premiums. Rural households in tier-3 and tier-4 cities exhibit highest price sensitivity, while German pharmacy chains command lowest elasticity through pharmacist-guided selection.
Supply Chain Analysis
Freight cost volatility from Zhejiang and Jiangsu chemical processing zones to European and North American formulation facilities amplifies working capital requirements for just-in-time botanical oil procurement. Active ingredient synthesis clusters in China, India, and Germany feed global formulators with synthetic pyrethroids, refined citronella derivatives, and picaridin intermediates. Raw material dependencies center on palm-derived emulsifiers, polymer encapsulation matrices, and propellant gases vulnerable to environmental compliance shutdowns. Single-source vulnerability in Chinese canister manufacturing creates bottleneck risk for aerosol formats. Distribution runs through contract manufacturing networks serving private-label pharmacy chains and direct-to-consumer pure-plays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on backward integration into botanical extraction and the premium-tier shift toward wearable spatial devices that bypass dermal-absorption liability.
For Market Incumbents: Acquire pediatric-toxicology consulting capabilities to compress EPA and CDSCO dossier preparation timelines. Defensive consolidation should prioritize captive supply of oil of lemon eucalyptus through Indian PLI-linked extraction facilities, while channel control investments in subscription commerce infrastructure counter pharmacy chain volume erosion. For New Entrants and Emerging Players: ANVISA's streamlined cosmetic-pathway registration in Brazil opens a window for botanical-first positioning without dual-track pharmaceutical compliance. White-space targets include rural India's kirana network penetration with sachet formats and ultrasonic wearable licensing for stroller-attachment hardware. Go-to-market execution should leverage UPI-enabled direct-to-consumer subscription trials in Mumbai and Bangalore. For Investors and Strategic Acquirers: Consumer goods conglomerates with existing pest-control infrastructure are the most active acquirer in this space, seeking pediatric brand extensions. Long-term viability favors targets with CDSCO-registered botanical portfolios and Indian manufacturing footprints. The inflection signal to monitor is REACH enforcement tightening on synthetic concentration caps, which would accelerate botanical substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Extraction | Indian PLI incentives reduce raw material cost exposure for citronella and lemongrass supply. |
| Direct-to-Consumer Subscription Launch | UPI infrastructure and smartphone penetration enable frictionless recurring revenue capture in urban India. |
| Wearable Spatial Device Development | Ultrasonic emitters address parental rejection of topical chemistry for neonatal protection scenarios. |
| CDSCO Dual-Registration Investment | Cosmetic-drug hybrid compliance unlocks pharmacy channel access for PMD-based formulations. |
| Rural Kirana Network Expansion | Tier-3 and tier-4 city penetration scales volume for affordable single-use sachet formats. |
Research Methodology
Bottom-up household consumption modeling reconciled against top-down active ingredient production tracking forms the analytical core of this study. Primary interviews with pediatric formulation scientists, CDSCO regulatory consultants, pharmacy category buyers, and kirana network distributors were cross-validated against customs records, CDSCO registration databases, and EPA pesticide product registrations. Secondary sources included Nielsen retail audit data for Indian modern trade, REACH substance restriction notifications, and ANVISA pediatric personal care filings.
Historical trendline analysis of monsoon-season replenishment patterns and channel-shift trajectories informed the projection framework. Segmentation dimensions modeled include product type, active ingredient chemistry, packaging format, and sales channel across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance cost escalators and substitution dynamics between synthetic and botanical actives. Forecast inputs included EPA pediatric labeling timeline assumptions and Indian PLI scheme uptake rates for domestic extraction capacity.
Revisions become necessary when CDSCO reclassifies botanical formulations as therapeutic drugs, when Chinese environmental compliance triggers sustained pyrethroid export restrictions, or when REACH synthetic concentration caps tighten beyond current thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Electric Foot Callus Remover Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
India Sexual Wellness Market
Personal Grooming Products
Global Hairbrush Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Hair Styling Tools Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Pre-Shave Products Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Organic and Natural Tampons Market