
 Razor Market | 2026-2036
Razor Market Size, Share, and Industry Trends Forecast 2026-2036
Razor Market Analysis
The gap between premium blade systems and commodity disposables is recalibrating competitive investment across the razor industry. Procter & Gamble leverages its Gillette brand equity and R&D infrastructure to sustain premium pricing in cartridge systems. Edgewell Personal Care Company anchors its position through Schick's broad retail distribution and value-tier offerings. Harry's, Inc. differentiates via direct-to-consumer subscription models that compete on convenience rather than shelf space.
A razor is a handheld cutting tool with one or more sharpened edges, typically manufactured from stainless steel or carbon steel with hardness ratings between 48 and 58 HRC, designed to sever hair at the skin surface with minimal tissue trauma. Electric razors occupy the fastest-expanding margin pool as lithium-ion battery improvements and pivoting foil designs attract time-constrained professionals. Safety razors are experiencing renewed demand among sustainability-focused consumers who reject plastic cartridge waste. Salons and barbershops represent a concentrated professional end-user segment where blade longevity and sanitation standards drive procurement decisions.
The U.S. Consumer Product Safety Commission monitors blade-related injury reports, while the EU REACH regulation restricts nickel migration from metal handles and blade alloys. ISO 8442-1 governs materials and performance for manually operated cutting tools including razors, setting baseline sharpness retention and corrosion resistance benchmarks. Stakeholders must monitor evolving state-level extended producer responsibility laws for single-use plastics that threaten disposable razor economics.
Market Dynamics
The razor market pivots on a fundamental tension between convenience-driven cartridge systems and sustainability-motivated safety razor revival, with regulatory pressure on single-use plastics accelerating format substitution across developed economies.
Growth Catalysts
- EU REACH nickel restrictions:Blade alloy reformulation is creating demand for premium stainless-steel grades that command higher unit economics and extend replacement cycles.
- Lithium-ion energy density gains:Electric foil shavers now deliver 90-minute cordless operation, erasing the performance gap with corded professional equipment in barbershop settings.
- Direct-to-consumer subscription normalization:United States households increasingly accept automated replenishment for consumable grooming products, locking in predictable revenue streams.
Market Restraints
- Stainless steel price volatility:Blade substrate costs fluctuate with nickel and chromium ore availability, compressing margins on value-tier disposable products.
- Single-supplier ceramic coating dependency:Super-hard blade edge treatments rely on concentrated German and Japanese specialty chemical providers.
- Biodegradable polymer performance ceiling:Plant-based handle materials lack the impact resistance of ABS plastic, limiting their adoption in travel-focused SKUs.
Strategic Opportunities
- Indian urban male grooming expansion:Tier-1 and Tier-2 cities show underpenetrated safety razor adoption among millennials seeking ritualized shaving experiences.
- Extended producer responsibility tailwinds:France and Germany mandate packaging take-back programs that favor durable metal-handle systems over plastic disposables.
- AI-enabled skin-type personalization:Smartphone-connected electric razors with pressure sensors and beard-density mapping are absorbing premium positioning from manual systems.
Industry Challenges
- ISO 8442-1 certification timelines:New blade geometries require 18-24 month testing protocols before commercialization, delaying product pipeline velocity.
- Precision grinding workforce scarcity:Master blade sharpeners with sub-micron edge control expertise are retiring faster than apprenticeship programs replenish talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Razor Market |
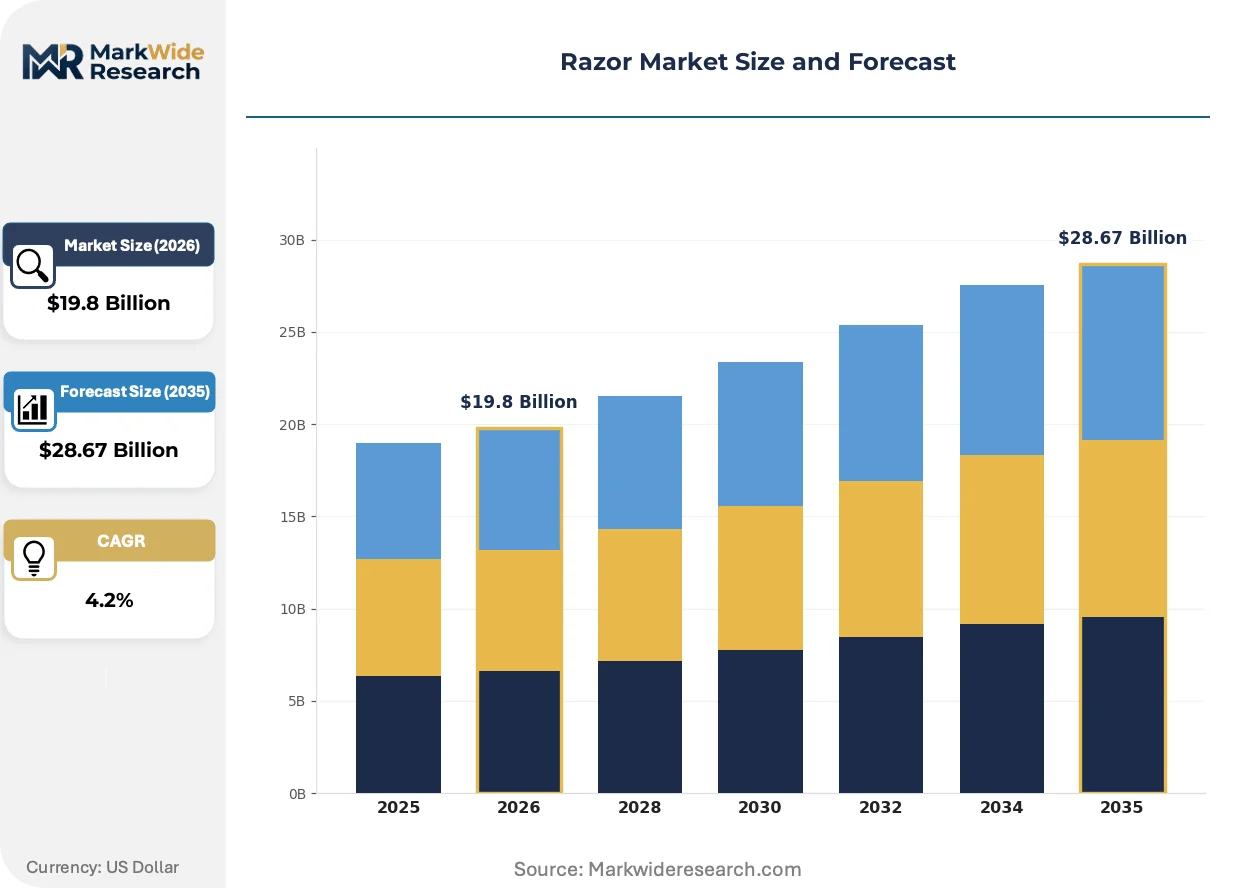
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $28.67 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Razors, Safety Razors, Electric Razors, Straight Razors End User: Men, Women, Salons, Barbershops Use Case: Personal Grooming, Professional Shaving, Sensitive Skin, Travel Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Procter & Gamble, Edgewell Personal Care Company, Koninklijke Philips N.V., Société Bic S.A., Harry’s, Inc., Dorco Co. Ltd., Supermax Group, Beiersdorf AG, Feather Safety Razor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Razor Market Emerging Trajectories
Active materials science and regulatory chemistry are rewriting competitive rules across razor formats. Manufacturers now engineer blade edges at the nanoscale while navigating polymer substitution mandates that threaten legacy disposable economics.
Laser-deposited diamond-like carbon coatings are absorbing the premium cartridge segment by extending blade longevity from five to fifteen shaves. Dermatology clinics and high-frequency travelers are adopting these systems fastest. The technology is absorbing margin from traditional platinum-chrome edges by reducing replacement frequency and justifying subscription price premiums.
REACH nickel migration limits are forcing handle and blade alloy redesigns across European supply chains. Manufacturers substitute 316L surgical steel for lower-grade substrates to comply with 0.5 μg/cm²/week release thresholds. Safety razor producers with existing stainless-steel expertise capture share from cartridge brands scrambling to reformulate metal injection molded components.
Subscription bundling of blades with skincare actives is displacing standalone hardware purchases in United States direct channels. Younger male buyers expect integrated grooming regimens rather than single-purpose tools. Barbershop wholesale accounts in Texas and California now specify blade-plus-aftershave procurement packages, compressing traditional distributor roles.
Razor Market Segmentation
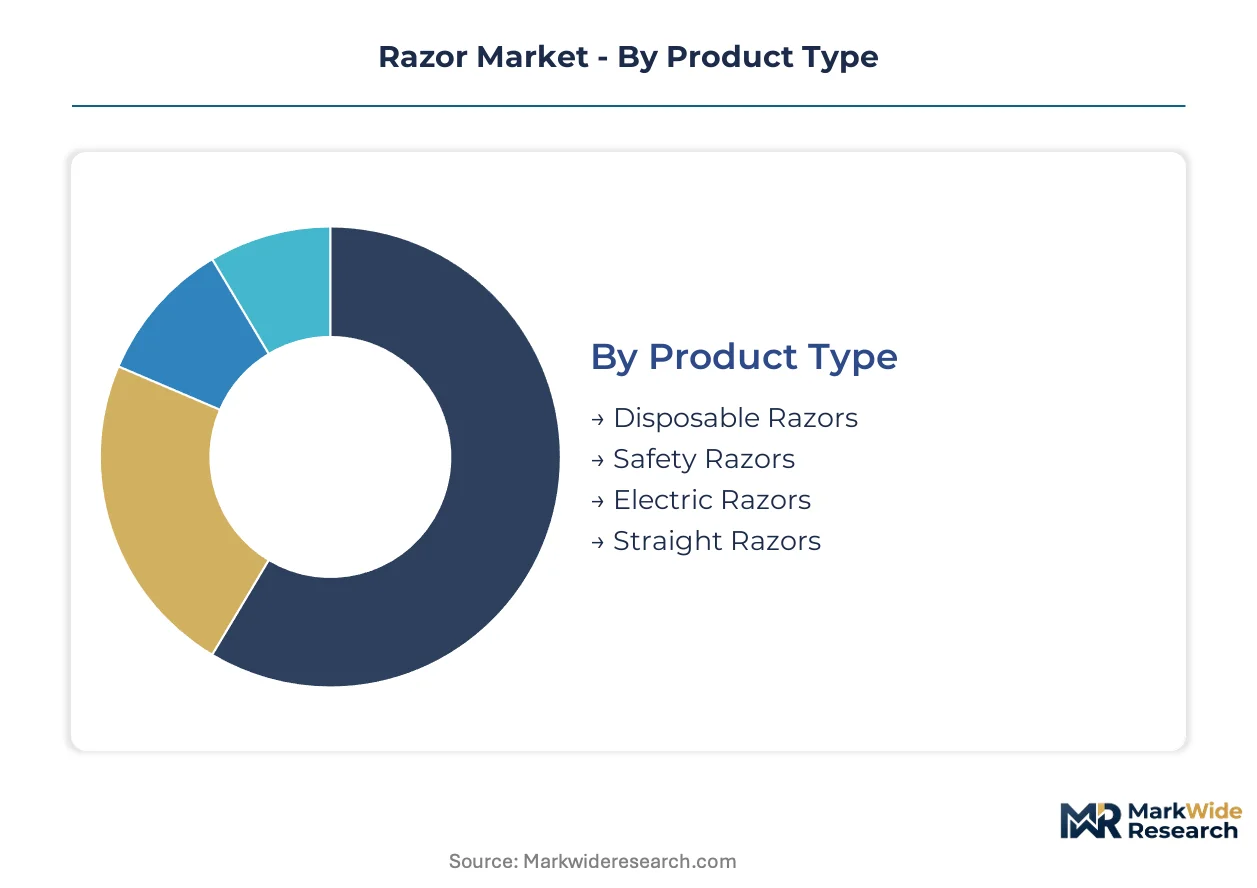
Razor market segmentation reveals divergent capital requirements and margin structures across formats. Product type determines manufacturing infrastructure needs, while distribution channel selection shapes customer acquisition economics and brand positioning.
Product Type:
Capital intensity varies dramatically across razor formats, with electric systems demanding the heaviest upfront investment in motor assembly and battery integration.
- Disposable Razors:Injection-molded plastic handles with bonded steel blades produced through high-speed stamping. Mass-market volume concentrates in United States supermarkets and convenience retail, though EU single-use plastic directives are compressing long-term demand visibility.
- Safety Razors:Machined metal handles with replaceable double-edge blades, requiring precision threading and corrosion-resistant finishing. German and Japanese manufacturers dominate premium stainless-steel sourcing, with sustainability-focused consumers in France and Germany driving replacement blade subscriptions.
- Electric Razors:Pivoting foil and rotary systems integrating lithium-ion cells, micro-motors, and flexing cutter heads. Cordless runtime improvements are erasing performance gaps with professional barbershop equipment.
- Straight Razors:Hand-forged carbon or stainless steel with hollow-ground edges, produced through artisanal grinding traditions. Master blade sharpeners in Solingen and Seki City supply limited professional and collector markets.
Safety razors absorb the bulk of installed metalworking capacity; electric razors are expanding most quickly.
End User:
Customer lifetime value diverges sharply between individual consumers and professional accounts, with barbershops demanding bulk procurement and sanitation compliance.
- Men:Primary volume driver across cartridge, safety, and electric formats. Direct-to-consumer subscriptions in the United States lock in predictable replenishment revenue through automated blade delivery.
- Women:Specialized handle ergonomics and moisture strips targeting leg and underarm grooming. Retail shelf placement in pharmacies and beauty specialty stores drives trial.
- Salons:Professional-grade disposables with single-use hygiene protocols. California and Texas wholesale accounts increasingly specify blade-plus-skincare bundled procurement.
- Barbershops:Straight razor and safety razor systems with autoclave-compatible metal handles. Blade longevity and sanitation standards override unit cost in vendor selection.
Men's individual purchases anchor total volume; barbershop professional accounts are climbing the fastest.
Use Case:
Application context dictates performance specifications and price tolerance, with sensitive skin formulations commanding premium positioning.
- Personal Grooming:Daily home use across all razor formats. Convenience preferences in United States urban households favor subscription replenishment over retail stocking.
- Professional Shaving:Barbershop and salon services requiring sanitized, durable equipment. Hot towel preparation rituals in Indian Tier-1 cities are reviving straight razor demand among millennials.
- Sensitive Skin:Hypoallergenic coatings, lubrication strips with aloe or vitamin E, and reduced blade count configurations. Dermatology clinic recommendations in Germany and France validate premium pricing.
- Travel:Compact disposables and miniaturized electric systems with universal voltage. TSA-compliant designs dominate United States airport retail placement.
Personal grooming absorbs the bulk of unit shipments; sensitive skin applications are gaining share fastest.
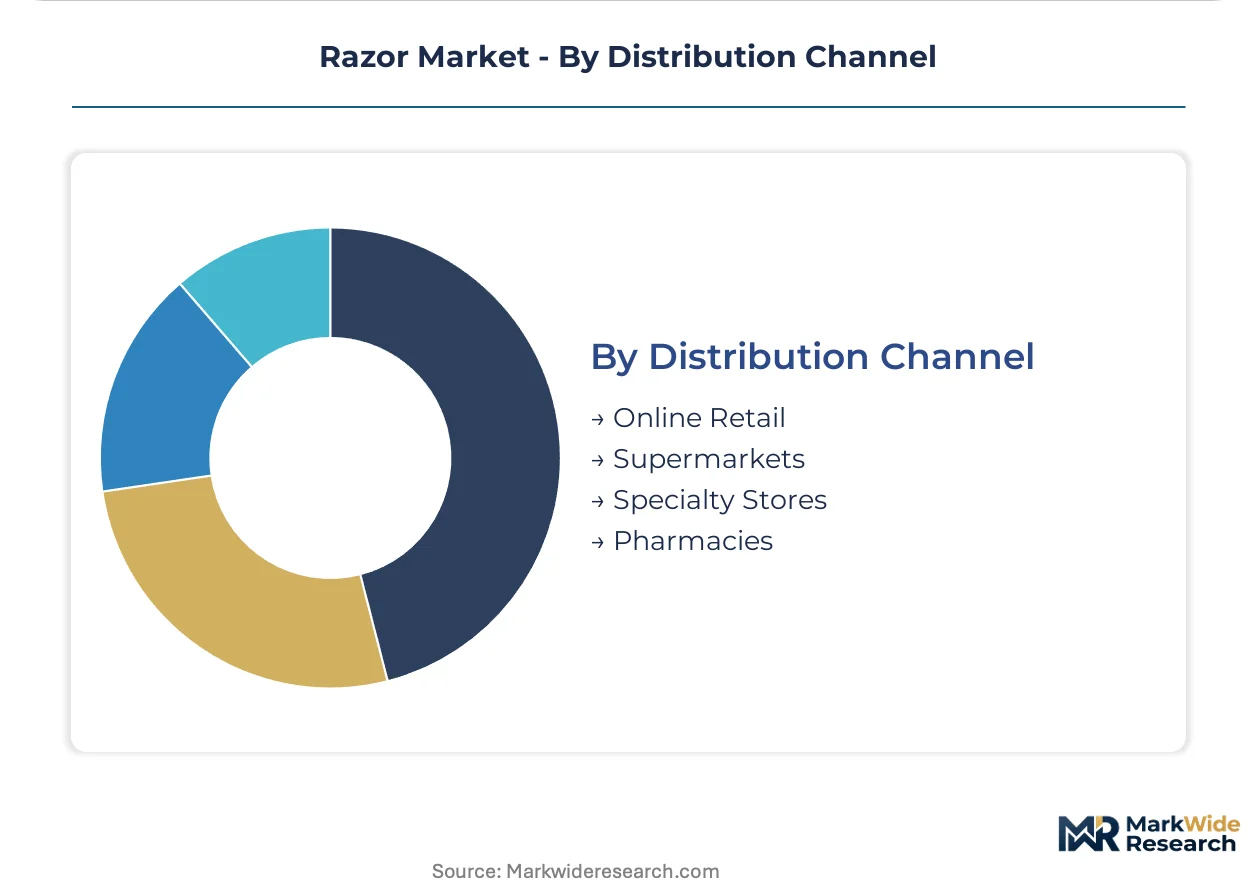
Distribution Channel:
Channel selection determines margin capture and customer data access, with online retail enabling subscription economics unavailable through physical retail.
- Online Retail:Direct-to-consumer platforms and marketplace listings with automated replenishment algorithms. Harry's and Dollar Shave Club built United States market presence through this channel before limited retail expansion.
- Supermarkets:Mass-market cartridge and disposable placement with high-frequency impulse purchases. Slotting fees and promotional calendars compress net margins for value-tier brands.
- Specialty Stores:Grooming boutiques and department store counters with assisted selling and premium positioning. Japanese department stores in Tokyo and Osaka maintain dedicated men's grooming floors.
- Pharmacies:Health-positioned SKUs with sensitive skin claims and dermatological endorsements. European pharmacy chains in France and Germany emphasize nickel-free metal certifications.
Supermarkets absorb the bulk of physical inventory; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American razor subscription innovation, hosting Harry's direct-to-consumer headquarters and venture capital backing for grooming startups. The city's e-commerce infrastructure supports automated replenishment algorithms that now penetrate one-third of United States urban households.
United States
Direct-to-consumer subscriptions concentrate in coastal metropolitan corridors, with California and Texas barbershops now specifying blade-plus-skincare bundled procurement. The U.S. Consumer Product Safety Commission monitors blade-related injury reports, creating compliance documentation requirements for all domestic manufacturers. Solingen-trained master sharpeners operate small-batch ateliers in Brooklyn and Portland, serving collector and professional barber demand.
Germany
REACH nickel migration limits at 0.5 μg/cm²/week force alloy reformulation across blade and handle production. ECHA compliance costs favor incumbent manufacturers with existing 316L surgical steel expertise. The Solingen industrial cluster maintains hollow-ground straight razor traditions while pivoting toward premium safety razor exports for French and Scandinavian sustainability markets.
France
Extended producer responsibility laws mandate packaging take-back programs that disadvantage plastic disposable economics. ANSM dermatological endorsements validate hypoallergenic coating claims in pharmacy channels. Parisian grooming boutiques anchor premium safety razor distribution, with Île-de-France consumers showing highest European adoption of metal-handle subscription models.
India
Tier-1 cities including Mumbai and Bangalore exhibit underpenetrated safety razor adoption among millennials seeking ritualized shaving experiences. BIS certification requirements for imported blade alloys create entry barriers for foreign cartridge brands. Traditional hot towel preparation rituals in Delhi and Hyderabad barbershops are reviving straight razor demand among urban professionals.
Japan
Seki City maintains artisanal blade grinding traditions supplying limited professional and collector markets globally. METI standards for lithium-ion energy density drive electric foil shaver performance improvements. Tokyo and Osaka department stores dedicate entire men's grooming floors to assisted selling of premium cartridge and electric systems.
Razor Market Vendor Landscape
Premium-margin players sit above commodity-margin players across coating technology and distribution channel control. The razor industry structures around three tiers: multinational consumer goods conglomerates with R&D infrastructure, direct-to-consumer specialists with subscription algorithms, and regional blade manufacturers with metalworking heritage. Strategic moves concentrate on backward integration into specialty steel sourcing and geographic licensing of coating technologies.
Within the multinational tier, Procter & Gamble and Koninklijke Philips N.V. exemplify divergent format dominance—cartridge systems versus electric foil engineering—while Harry's, Inc. occupies the direct-to-consumer archetype that bypasses traditional retail slotting fees entirely. Edgewell Personal Care Company and Société Bic S.A. represent scale-driven commodity positioning across mass-market retail channels. Dorco Co. Ltd. and Feather Safety Razor Co., Ltd. anchor East Asian precision manufacturing heritage in blade substrate supply.
| Leading Market Players |
|---|
| Procter & Gamble |
| Edgewell Personal Care Company |
| Koninklijke Philips N.V. |
| Société Bic S.A. |
| Harry's, Inc. |
| Dorco Co. Ltd. |
| Supermax Group |
| Beiersdorf AG |
| Feather Safety Razor Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Captive blade coating capabilities in Germany and Japan anchor premium positioning while insulating holders from commodity margin erosion. Procter & Gamble and Koninklijke Philips N.V. leverage in-house diamond-like carbon deposition and foil engineering respectively to sustain subscription pricing power against value-tier competitors sourcing through third-party metallurgists.
Pricing Analysis
Shave-count value anchors cartridge subscription tiers, with dermatological endorsement and autoclave compatibility commanding the widest spreads. Three-tier pricing structure across premium, standard, and economy levels separates laser-coated systems from platinum-chrome edges and stamped disposables. Cost compression in value-tier disposables intensifies because EU single-use plastic directives threaten volume economics. Price-sensitive supermarket shoppers in the United States drive promotional intensity, while barbershop procurement officers in Texas and California exhibit lowest sensitivity due to sanitation compliance requirements.
Supply Chain Analysis
ISO 8442-1 certification timelines and REACH nickel compliance gates concentrate qualified supply among incumbent metallurgists with existing 316L surgical steel expertise. Blade substrate production draws from Germany, Japan, and India, with Seki City and Solingen maintaining hollow-ground traditions. Lithium-ion cell supply rests on South Korean and Japanese chemistry specialists, creating single-source vulnerability for electric razor assemblers. Distribution runs through direct-to-consumer platforms for subscription models and supermarket slotting agreements for mass-market disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH enforcement and extended producer responsibility laws are compressing plastic disposable economics, forcing sub-scale cartridge brands toward exit or acquisition. Consolidation pressure favors metallurgical specialists with pre-qualified stainless-steel supply chains.
For Market Incumbents: Hedge against format substitution by acquiring safety razor metalworking capacity in Solingen or Seki City before REACH-compliant alloy expertise becomes captive. Secure 316L surgical steel offtake agreements to defend subscription pricing power against reformulation delays that plague competitors dependent on metal injection molding contractors. For New Entrants and Emerging Players: Capture whitespace in Indian Tier-1 city safety razor subscriptions by bundling hot towel ritual accessories with automated blade replenishment. Target sustainability-motivated millennials in Mumbai and Bangalore through barbershop channel partnerships rather than retail slotting battles dominated by Edgewell and Bic. For Investors and Strategic Acquirers: Exit pathways concentrate in direct-to-consumer subscription platforms with proven replenishment algorithms and captive metallurgical supply. Long-term viability over the projection horizon favors targets with backward integration into specialty steel sourcing rather than brand-dependent assemblers exposed to nickel price volatility. Watch for REACH nickel threshold tightening as the inflection signal accelerating format substitution toward metal-handle systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive 316L supply insulates Procter & Gamble from REACH reformulation delays compressing competitor margins. |
| Direct-to-Consumer Subscription Launch | Harry's automated replenishment algorithms bypass supermarket slotting fees that erode Edgewell's value-tier economics. |
| Safety Razor Metalworking Acquisition | Solingen hollow-ground expertise commands premium positioning in French and German extended producer responsibility markets. |
| Lithium-Ion Energy Density Partnership | Philips collaboration with South Korean cell suppliers extends cordless runtime to match professional barbershop equipment standards. |
| AI-Enabled Skin Personalization Platform | Smartphone-connected pressure sensors absorb premium positioning from manual systems through dermatology clinic validation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this razor market assessment. Primary interviews with brand managers at direct-to-consumer platforms, category buyers at United States supermarket chains, Solingen master blade sharpeners, and barbershop procurement officers in Texas and California supplied operational validation. ECHA REACH documentation, FDA injury report databases, and ISO certification registries complemented bottom-up production estimates with top-down demand triangulation.
Reconciliation of shipment data, retail audit feeds, and subscription platform disclosures shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user archetype, use case context, and distribution channel control. CAGRs emerged from curve-fitting historical volume trajectories against regulatory phase-in schedules and battery technology improvement curves. Electric razor adoption rates and safety razor replacement blade subscription attach rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH nickel threshold revisions and lithium-ion supply concentration. Projections reflect assumptions regarding regulatory enforcement consistency and barbershop sanitation standard adoption. A model refresh is warranted upon material change in extended producer responsibility implementation timelines or ceramic coating supplier consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
China Beard Trimmer Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
Smart Body Scales Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Lice Combs Market
Personal Grooming Products
Europe Hair Styling Tools Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
360 Degree Toothbrush Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
United States Electric Toothbrush Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Razor Blade Market
Personal Grooming Products
Heated Razor Starter Kit Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market