
 Global Beard Balm Market | 2026-2036
Global Beard Balm Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beard Balm Market Analysis
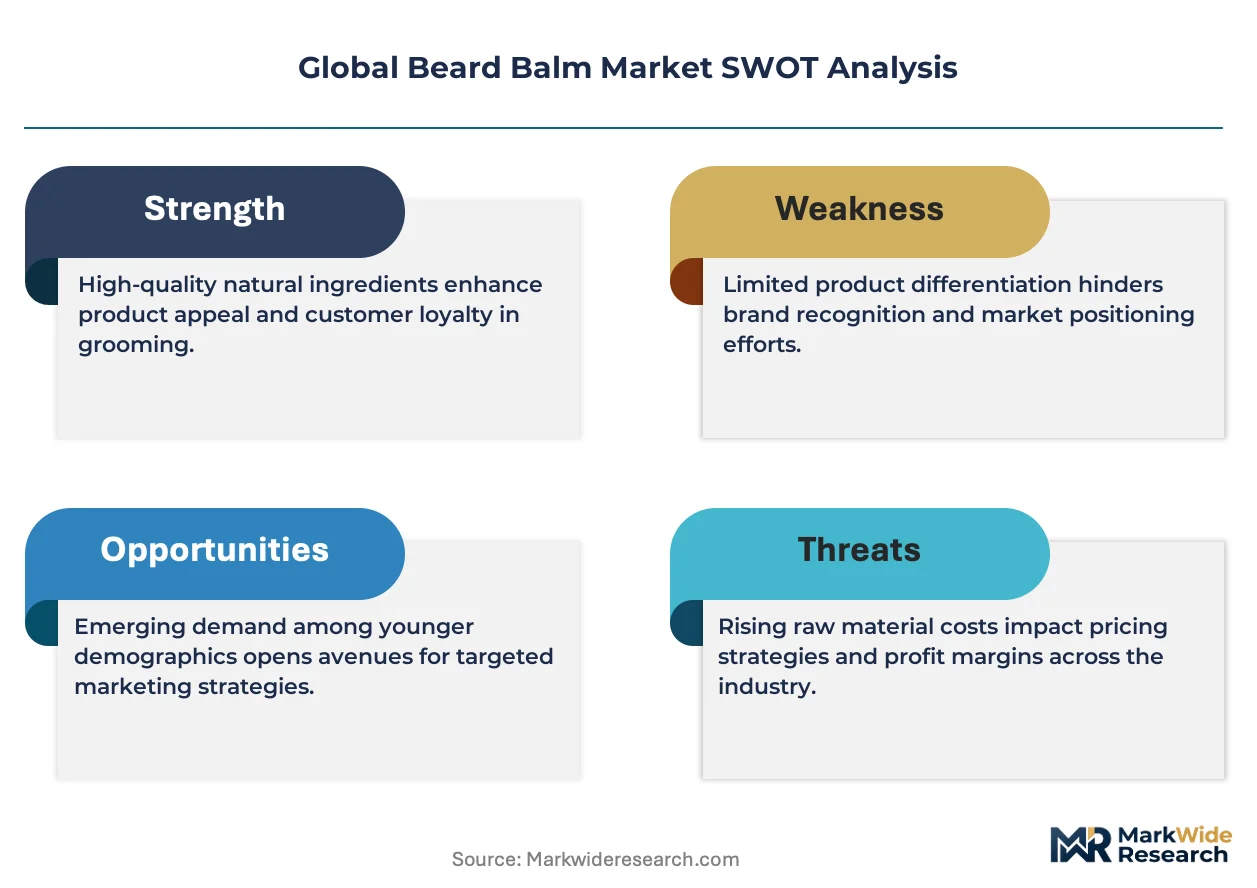
Plant-derived wax substitution and cold-pressed oil infusion is reshaping formulation architecture across the beard balm category. Beardbrand leverages its vertical content-to-commerce pipeline to sustain premium positioning in North America. Honest Amish anchors the artisan segment through Amish-crafted supply chains and heritage positioning. Murdock London competes on barbershop credibility, extending its London grooming salon origins into formulated products.
Beard balm is a leave-in conditioning and styling preparation, typically comprising beeswax or plant waxes, carrier oils such as jojoba or argan, and optional essential oils, manufactured through low-temperature blending to preserve bioactive compounds; its primary commercial purpose is to moisturize facial hair, reduce breakage, and provide light hold for styling. Organic formulations command the deepest margin pools as clean-label premiums persist among professionals and retail consumers. Scented variants dominate volume through grooming salons, where fragrance layering integrates with broader service menus. Unscented balms occupy a growing niche among users with dermatological sensitivities or fragrance-free workplace policies.
REACH in Europe mandates full ingredient disclosure and restricts certain synthetic preservatives, pushing formulators toward certified organic inputs. FDA cosmetic labeling requirements in the United States govern allergen declarations and marketing claims, creating compliance costs that favor scaled manufacturers over artisan entrants. ISO 16128 guidelines on natural and organic cosmetics provide a voluntary benchmark that premium brands increasingly adopt for cross-border credibility. Stakeholders must monitor evolving state-level clean beauty legislation and decide whether to front-run compliance or segment geographic portfolios.
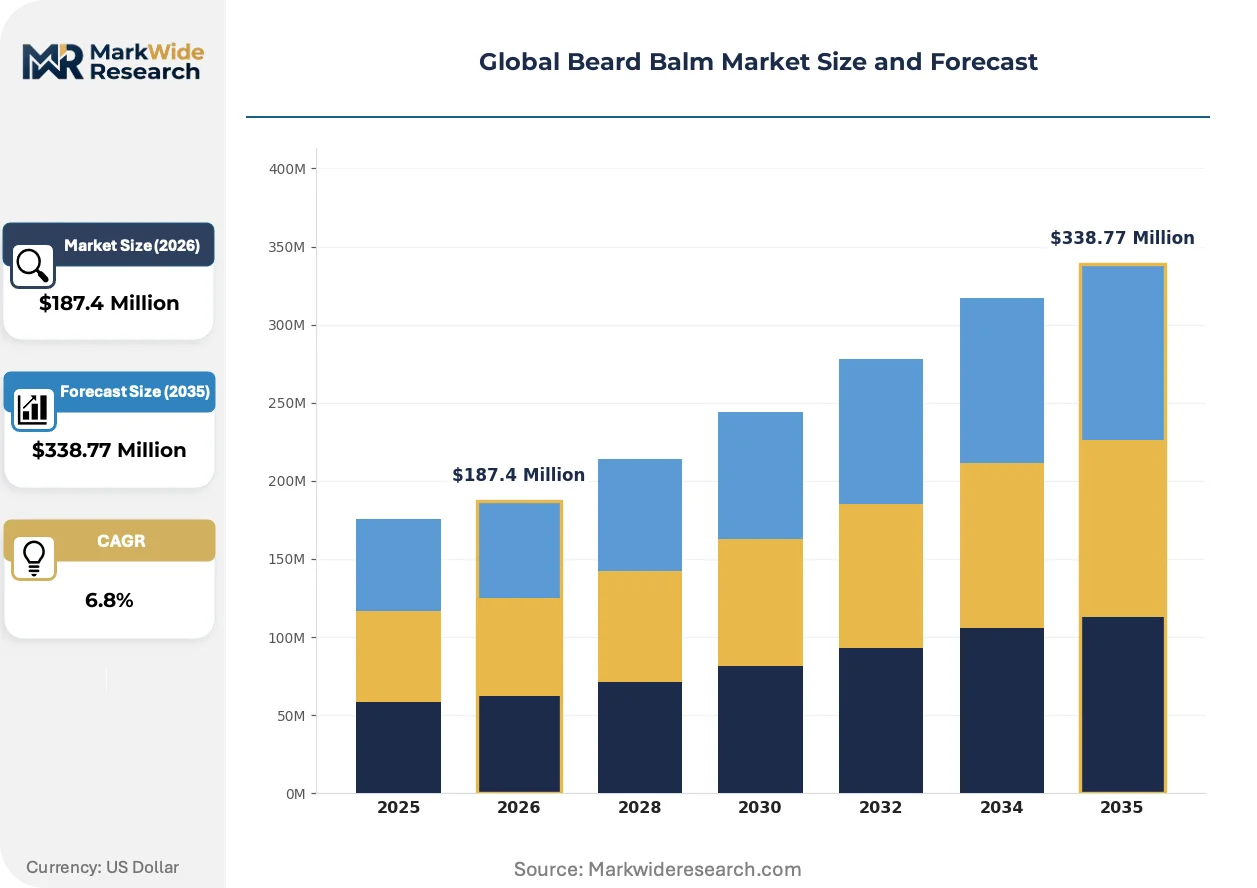
Market Dynamics
Plant wax substitution is forcing reformulation across the beard balm supply chain as REACH compliance costs and FDA labeling rules compress margins for synthetic-dependent producers.
Growth Catalysts
- Barbershop channel expansion:Professional grooming salons in the United States now stock beard balm as a service-integrated retail item, pulling volume through trained stylist recommendations.
- REACH ingredient transparency:ECHA-mandated disclosure requirements in Europe are accelerating certified organic certification as a competitive differentiator among export-oriented formulators.
- Cold-pressed oil infusion:Low-temperature manufacturing preserves bioactive compounds in jojoba and argan inputs, enabling premium positioning among dermatologically conscious users.
Market Restraints
- Beeswax supply volatility:Colony collapse disorder in North American apiaries concentrates wax sourcing among a shrinking pool of commercial beekeepers, compressing input security for conventional formulations.
- Artisan scale limitations:Small-batch producers lack capital for ISO 16128 certification, locking them out of cross-border retail channels demanding standardized natural-content verification.
- Fragrance-free workplace policies:Corporate wellness mandates in professional services sectors are displacing scented variants in certain metropolitan employment clusters.
Strategic Opportunities
- Subscription direct-to-consumer models:Automated replenishment platforms in the United States capture recurring revenue through personalized scent profiling and usage-based reorder algorithms.
- India grooming salon penetration:Urban male grooming chains in Mumbai and Bangalore represent underdeveloped distribution infrastructure for leave-in conditioning preparations.
- Clean beauty state legislation:California's forthcoming cosmetic ingredient disclosure rules create first-mover advantage for brands with pre-positioned transparency protocols.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient stability and shelf-life extension remains concentrated among a narrow cohort of specialists trained in cold-process emulsion science.
- Supply chain reconfiguration costs:Shifting from Asian synthetic preservative suppliers to European certified organic inputs demands working capital restructuring and extended qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beard Balm Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Scented, Unscented, Deep Conditioning Texture: Soft, Firm, Whipped, Gel End User: Professionals, Hobbyists, Retail Consumers, Grooming Salons Packaging Type: Tub, Jar, Stick, Pouch |
| Companies Covered | The Bearded Bastard, Billy Jealousy, Beardbrand, Murdock London, Scotch Porter, Texas Beard Company, Smoky Mountain Beard Co., Brickell Men’s Products, Honest Amish, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beard Balm Market Emerging Trajectories
Digital formulation tools and regulatory automation are compressing product development cycles while fragmenting competitive advantage across technical and compliance capabilities.
Cold-process emulsion technology is virtualizing traditional heat-dependent manufacturing. Barbershop-oriented brands adopt low-temperature blending equipment to preserve volatile terpenes in essential oil infusions. This virtualization collapses the gap between artisan sensory claims and scaled production consistency.
REACH Annex XVII restrictions on synthetic preservatives are forcing preservative-system redesign across European-exporting formulators. The industrial consequence is accelerated investment in hurdle-technology approaches combining pH modulation with packaging barrier engineering. North American brands with European distribution exposure are pre-emptively reformulating to avoid dual-SKU complexity.
Professional service bundling is restructuring retail economics in the beard balm category. Grooming salons now capture margin through service-integrated product application rather than standalone shelf sales, displacing traditional wholesale-distributor relationships. This pattern concentrates in United States urban markets where barbershop culture anchors male grooming rituals.
Global Beard Balm Market Segmentation
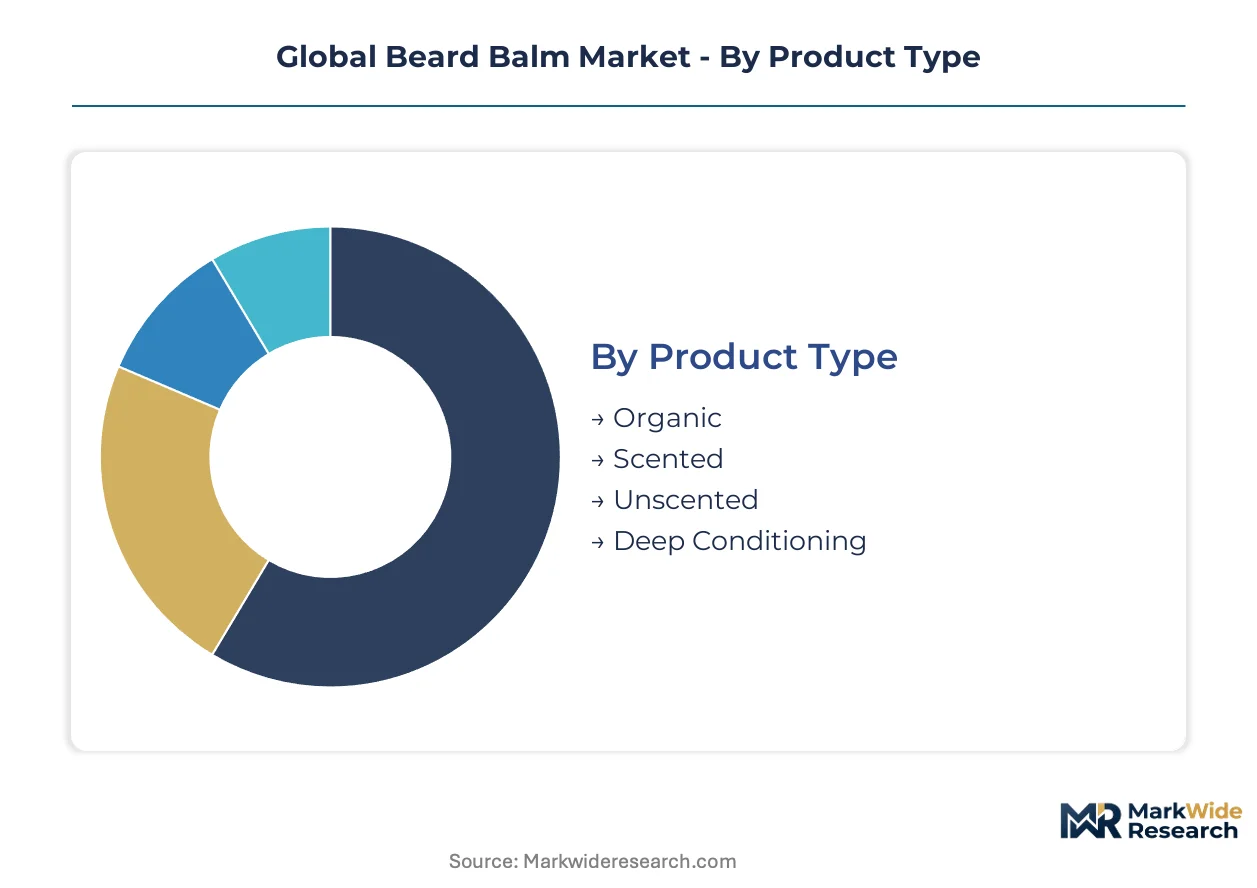
Segmentation in beard balm reflects divergent formulation philosophies and channel economics. Product type and texture determine manufacturing complexity, while end-user targeting shapes pricing architecture and distribution strategy.
Product Type:
Mature certified segments now compete with emerging clean-label alternatives for shelf space and margin.
- Organic:Certified organic formulations rely on cold-pressed carrier oils and plant-derived waxes without synthetic preservatives. Demand concentrates among dermatologically conscious professionals in Germany and California, where REACH compliance and state-level clean beauty legislation reward transparency investment.
- Scented:Fragrance-layered variants incorporate essential oil terpenes preserved through low-temperature blending. Grooming salons in London and New York pull volume through service-integrated application, though corporate fragrance-free workplace policies in professional services sectors constrain metropolitan expansion.
- Unscented:Fragrance-free formulations serve users with sensitivities or employment restrictions; BIS certification in India and FDA allergen labeling in the United States favor standardized unscented SKUs for cross-border retail.
- Deep Conditioning:High-oil-content preparations target coarse or damaged facial hair; demand clusters in cold-climate urban centers where seasonal dryness accelerates replenishment cycles.
Organic handles the majority of throughput; Scented is expanding most quickly on share.
Texture:
Cost tier stratification separates artisan small-batch positioning from scaled manufacturing efficiency.
- Soft:Lower wax-to-oil ratios enable easy scoopability and rapid absorption. Hobbyists in Australian metropolitan markets favor soft textures for daily reapplication without residue buildup.
- Firm:Higher beeswax or candelilla content provides structural hold for styling. Barbershops in São Paulo and Mexico City specify firm textures for service-integrated shaping that survives humid climates.
- Whipped:Aerated emulsions reduce per-use weight and create premium tactile experience. Direct-to-consumer subscription models in the United States leverage whipped textures for differentiation in automated replenishment channels.
- Gel:Water-based formulations offer non-greasy alternatives; MFDS cosmetic stability requirements in South Korea and ANVISA moisture-content rules in Brazil shape regional gel formulation standards.
Firm textures anchor professional channel revenue; Whipped formats are climbing the fastest among premium direct-to-consumer launches.
End User:
Customer type determines whether brands invest in stylist education or automated personalization infrastructure.
- Professionals:Corporate and creative-sector workers demand portable, workplace-appropriate formats. Unscented stick packaging dominates this segment in Tokyo and Singapore where grooming rituals intersect with transit-heavy commutes.
- Hobbyists:Enthusiast communities drive ingredient literacy and small-batch discovery. Artisan producers in Portland and Austin cultivate hobbyist loyalty through limited-batch essential oil profiles and heritage positioning.
- Retail Consumers:Mass-market purchasers prioritize accessibility and price predictability. E-commerce aggregators in the United Kingdom and Netherlands consolidate retail demand through algorithmic scent matching and subscription bundling.
- Grooming Salons:Professional service providers capture margin through application labor rather than product markup. Urban barbershop chains in Chicago and Toronto integrate balm application into haircut service tiers, displacing traditional wholesale relationships.
Grooming salons command the highest per-unit margin capture; Retail consumers represent the steepest expansion trajectory through digital channels.
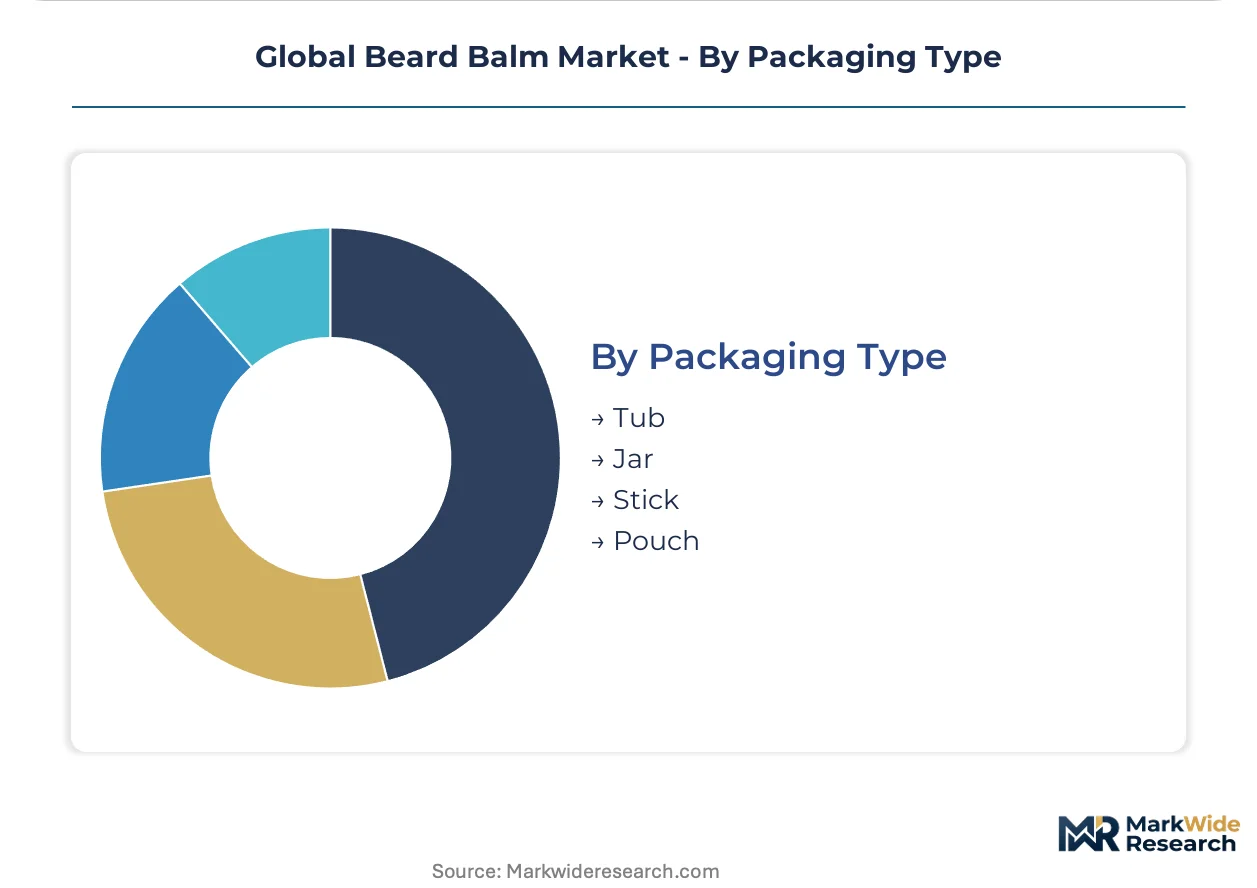
Packaging Type:
Supply concentration in aluminum and post-consumer recycled materials is reshaping format availability.
- Tub:Wide-mouth aluminum containers enable finger-scoop application and refill programs. ECHA packaging waste directives in Europe and California's extended producer responsibility rules favor tub formats with established recycling infrastructure.
- Jar:Glass jars signal premium positioning and support essential oil preservation. Japanese grooming retailers specify amber glass for UV-sensitive organic formulations targeting METI-certified natural cosmetic standards.
- Stick:Twist-up applicators minimize contamination and suit travel and workplace use. TGA therapeutic goods classifications in Australia and Health Canada cosmetic regulations govern stick labeling for balm products with added skin-conditioning claims.
- Pouch:Flexible single-use or refill sachets reduce shipping weight and support sampling. Indian urban grooming chains in Mumbai and Bangalore pilot pouch formats for service-integrated trial before full-size conversion.
Tub formats handle the majority of volume throughput; Stick packaging is gaining share fastest among professional and commuter segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented formulators in Germany and the United States dominate cross-border trade flows, while import-dependent grooming markets in India and Brazil absorb premium positioning through salon channel expansion. Trade balance asymmetries concentrate formulation IP in REACH-compliant jurisdictions and FDA-registered facilities.
United States
Urban barbershop culture in Chicago and Brooklyn drives service-integrated retail, with subscription direct-to-consumer models capturing recurring revenue through automated replenishment. FDA cosmetic labeling requirements govern allergen declarations and marketing claims, creating compliance thresholds that favor scaled manufacturers. California's forthcoming cosmetic ingredient disclosure rules are accelerating pre-positioned transparency investments among domestic formulators.
Germany
Dermatologically conscious professionals in Berlin and Munich sustain premium demand for certified organic formulations with full supply chain traceability. REACH compliance through ECHA mandates comprehensive ingredient disclosure and restricts synthetic preservatives, pushing formulators toward plant-derived wax substitution. The country's chemical industry cluster around Ludwigshafen provides qualified cosmetic chemist talent for cold-process emulsion development.
India
Urban male grooming chains in Mumbai and Bangalore represent underdeveloped distribution infrastructure for leave-in conditioning preparations, with salon penetration expanding fastest among metropolitan professionals. BIS certification requirements favor standardized unscented SKUs for cross-border retail compliance. Heritage positioning through artisan supply chains competes with mass-market accessibility via e-commerce aggregators in Delhi-NCR.
United Kingdom
London's grooming salon origins extend into formulated products through barbershop credibility plays, with fragrance-layered variants integrating into broader service menus. ECHA packaging waste directives favor aluminum tub formats with established recycling infrastructure. Algorithmic scent matching through e-commerce platforms consolidates retail demand from Manchester and Birmingham commuter belts.
Brazil
Humid climate conditions in São Paulo specify firm-texture balms for service-integrated styling that survives environmental stress. ANVISA moisture-content rules shape regional gel formulation standards, while import tariffs on premium positioning create localization incentives. The country's personal care manufacturing corridor in São Paulo state attracts contract formulation investment from export-oriented brands.
Global Beard Balm Market Vendor Landscape
On the supply side, the industry is bifurcated between artisan small-batch producers and scaled manufacturers with regulatory compliance infrastructure. Tiered competitive dynamics separate heritage-positioned craft formulators from direct-to-consumer platforms with vertical content-to-commerce pipelines. Two strategic archetypes dominate: barbershop-credibility brands extending salon origins into retail, and clean-label specialists leveraging certified organic certification as cross-border differentiation. Dominant competitive moves include geographic expansion through regulatory pre-positioning and portfolio diversification across scent and texture variants.
Within the heritage-craft archetype, Honest Amish anchors artisan positioning through supply chain transparency claims, while Beardbrand occupies the premium direct-to-consumer tier with content-driven customer acquisition. Murdock London represents the barbershop-credibility extension model, translating London grooming salon origins into formulated product legitimacy. These three exemplify how geographic origin and channel strategy stratify competitive positioning without requiring scale-dependent manufacturing infrastructure.
| Leading Market Players |
|---|
| The Bearded Bastard |
| Billy Jealousy |
| Beardbrand |
| Murdock London |
| Scotch Porter |
| Texas Beard Company |
| Smoky Mountain Beard Co. |
| Brickell Men’s Products |
| Honest Amish |
| Others |
Supply Flow & Price Mechanics
North American apiary concentration for beeswax and candelilla sourcing from Mexican desert cultivation centers feed directly into margin stratification across organic and conventional formulation tiers. Plant wax substitution investments compress synthetic-dependent producers while certified organic certification premiums deepen pool capture for REACH-compliant exporters.
Pricing Analysis
Grooming salons anchor pricing architecture through service-integrated application premiums that exceed standalone retail markups. Three-tier pricing structure across premium certified-organic, mid-tier clean-label, and economy synthetic formulations stratifies by certification grade and cold-process manufacturing investment. Cost compression in conventional beeswax-dependent tiers intensifies because colony collapse disorder concentrates wax supply among commercial beekeepers. Retail consumers through direct-to-consumer channels exhibit highest price sensitivity; professional grooming salons demonstrate lowest sensitivity due to labor-integrated margin capture.
Supply Chain Analysis
Beeswax feedstock draws from United States commercial apiaries, Mexican candelilla cultivation zones, and Brazilian carnauba extraction regions. Cold-pressed argan oil from Morocco, jojoba from Arizona and Sonora, and shea from West African cooperatives constitute core carrier oil dependencies. Single-source vulnerability in North American beeswax supply chains elevates reformulation risk for conventional formulators. Distribution runs through barbershop direct procurement, specialty grooming retailers, and automated replenishment platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beard balm functions as a service-attach category where subscription replenishment and salon application labor expand faster than product-only revenue streams. Recurring revenue through automated scent profiling and usage-based reorder algorithms outpaces transactional retail growth.
For Market Incumbents: Entrench barbershop channel control through exclusive stylist education programs and service-tier bundling that locks out competitor shelf placement. Pre-position REACH Annex XVII compliance and FDA cosmetic labeling infrastructure ahead of evolving state-level clean beauty legislation to capture artisan competitor displacement. Vertical integration into cold-pressed oil sourcing secures input quality consistency for premium positioning.
For New Entrants and Emerging Players: Urban grooming chains in Mumbai and Bangalore represent the most penetrable entry point given underdeveloped leave-in conditioning infrastructure and expanding metropolitan male grooming rituals. Direct-to-consumer subscription models with personalized scent profiling algorithms offer lowest customer acquisition cost versus contested retail shelf space. White-label formulation partnerships with ISO 16128-certified contract manufacturers accelerate speed-to-market without capital-intensive certification investment.
For Investors and Strategic Acquirers: Capital is best deployed toward direct-to-consumer platforms with vertical content-to-commerce pipelines and established automated replenishment infrastructure. Acquisition targets should demonstrate regulatory pre-positioning across REACH and FDA jurisdictions with scalable cold-process manufacturing capabilities. Monitor barbershop channel consolidation rates and state-level clean beauty legislative passage as inflection signals for compliance-premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Barbershop Channel Expansion | Service-integrated retail in Chicago and Brooklyn captures margin through application labor rather than product markup. |
| Certified Organic Certification Investment | ECHA REACH compliance and ISO 16128 adoption unlock cross-border retail access for export-oriented formulators. |
| Cold-Process Manufacturing Scale-Up | Low-temperature blending equipment preserves volatile terpenes while collapsing artisan-scaled production consistency gaps. |
| Subscription Platform Development | Automated replenishment with usage-based reorder algorithms captures recurring revenue through personalized scent profiling. |
| Plant Wax Supply Chain Integration | Backward integration into candelilla and carnauba sourcing mitigates colony collapse disorder exposure in beeswax-dependent formulations. |
Methodological Framework
Desk research of customs trade data, ECHA regulatory filings, and grooming salon industry publications preceded structured interviews with cosmetic chemists, barbershop owners, contract formulation facility managers, and direct-to-consumer brand operators. Primary fieldwork combined with secondary validation through FDA cosmetic labeling guidance documents, ISO 16128 natural cosmetics standards, and state-level clean beauty legislative tracking. Bottom-up volume estimation across product type, texture, and end-user segments triangulated against top-down market sizing from trade flow analysis.
Assumptions held fixed include REACH Annex XVII preservative restrictions and FDA cosmetic labeling requirements across the projection horizon; variables included barbershop channel penetration rates and state-level clean beauty legislative adoption timelines. Segmentation dimensions modeled encompass product certification tier, texture formulation, end-user archetype, packaging format, and regional regulatory cluster. CAGRs derived from historical volume trajectory analysis adjusted for channel shift acceleration and formulation substitution elasticities. Forecast inputs incorporated beeswax supply volatility indices and cold-pressed oil price series from Moroccan and Sonoran sourcing regions.
Practitioners should monitor colony collapse disorder severity, ECHA substance restriction updates, and California cosmetic ingredient disclosure rule implementation for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data and grooming salon point-of-sale transaction benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Shavers Market
Personal Grooming Products
Smart Water Bottle Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Disposable Shower Caps Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Disposable Electric Toothbrushes Market
Personal Grooming Products
Military Hydration Products Market
Personal Grooming Products
Ear Piercing Guns Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Organic Tampons Market
Personal Grooming Products
Electric Toothbrush Market
Personal Grooming Products
Electrical Neck Warmer Market
Personal Grooming Products
Nose & Ear Hair Trimmers Market
Personal Grooming Products
US Percussion Massage Gun Market