
 Organic and Natural Tampons Market | 2026-2036
Organic and Natural Tampons Market Size, Share, and Industry Trends Forecast 2026-2036
Organic and Natural Tampons Market Outlook
GOTS certification is rotating as the primary gatekeeping standard for organic tampon manufacturers seeking shelf placement in premium retail channels. Natracare Limited leverages its early organic certification to sustain British and Scandinavian distribution dominance. Cora Inc. anchors its competitive position through direct-to-consumer subscription models that bypass traditional pharmacy gatekeepers. Rael Inc. differentiates via Korean beauty-retail crossover channels, occupying shelf space in Sephora and specialized wellness outlets that conventional feminine-hygiene brands rarely access.
Organic and natural tampons are cylindrical absorbent devices composed of certified organic cotton or plant-based fibers, free from synthetic pesticides, chlorine bleach, and rayon, designed for menstrual fluid collection and management. Manufacturing requires adherence to soil-association organic standards and medical-device hygiene protocols, with absorbency ratings typically ranging from light to super-plus based on standardized gram-capacity testing. Applicator and non-applicator product types split the market structurally, with non-applicator variants commanding stronger margins among eco-conscious buyers despite lower absolute unit volumes. Online retail channels represent the fastest-growing distribution pathway, though supermarkets still capture the majority of impulse purchases from health-conscious individuals who lack subscription commitment.
FDA oversight in the United States classifies tampons as Class II medical devices, mandating absorbency labeling and adverse-event reporting that shapes product development timelines and compliance costs for entrants. The EU MDR and REACH frameworks collectively restrict chemical residues and mandate clinical biocompatibility documentation, creating asymmetric compliance burdens that favor established players with dedicated regulatory affairs teams. Stakeholders must monitor evolving state-level ingredient-disclosure legislation in California and New York, where proposed bills would mandate plain-language labeling of all constituent materials including adhesive and wrapper components.
Market Dynamics
Millennial women are redirecting procurement toward chemical-free menstrual products, compressing legacy brand shelf space while EU REACH restrictions on synthetic additives accelerate formulation turnover across manufacturing bases.
Growth Catalysts
- EU REACH chemical restrictions:Tightening residue limits on dioxins and pesticides in personal care items are forcing conventional manufacturers to reformulate, opening shelf space for certified organic alternatives.
- Millennial buyer segment expansion:Women aged 25-40 demonstrate the fastest preference shift toward transparency-labeled menstrual products, concentrating demand in urban clusters with premium retail density.
- Subscription commerce infrastructure:Direct-to-consumer platforms bypass pharmacy gatekeepers and capture recurring revenue through automated replenishment models.
Market Restraints
- Organic cotton input cost volatility:Weather-dependent harvests in India and Turkey create margin pressure that synthetic-fiber competitors avoid.
- FDA Class II medical device compliance:Absorbency testing and adverse-event reporting requirements extend product development timelines for entrants without dedicated regulatory affairs teams.
- Bioplastic applicator technical limitations:Plant-based polymers lack the structural integrity of conventional plastics, limiting performance in super-plus absorbency tiers.
Strategic Opportunities
- German retail channel density:Organic certification awareness and pharmacy distribution penetration exceed other European markets, creating a test-bed for premium positioning.
- Korean beauty-retail crossover:Shelf placement in Sephora and specialized wellness outlets accesses buyers who reject conventional feminine-hygiene aisles.
- California ingredient-disclosure legislation:Proposed plain-language labeling mandates would advantage early adopters of full-material transparency.
Industry Challenges
- GOTS certification timeline compression:Soil-association organic standards require 12-18 month supply chain audits that delay product launches.
- Medical-device hygiene protocol integration:Manufacturers must reconcile agricultural organic standards with ISO 13485 quality management systems.
- Legacy adhesive and wrapper material substitution:Eliminating synthetic components from peripheral product elements demands reformulation of supply contracts with packaging suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic and Natural Tampons Market |
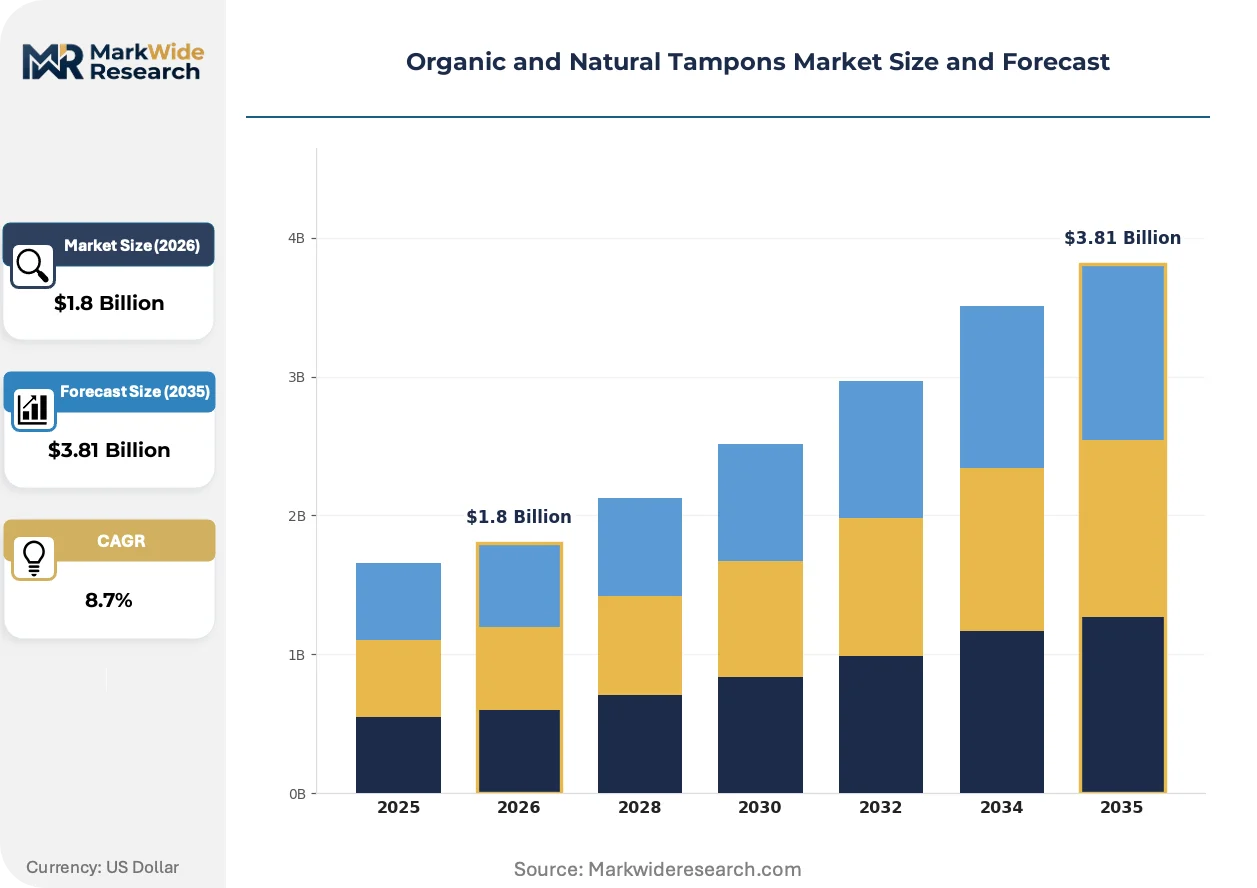
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Applicator, Non-Applicator, Organic Cotton, Herbal End User: Women, Teens, Eco-Conscious Consumers, Health-Conscious Individuals Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Packaging Type: Biodegradable, Recyclable, Plastic, Paper |
| Companies Covered | The Honest Company, Rael Inc., Cora Inc., Tampon Tribe, BON Health Group, Natracare Limited, Seventh Generation, Rif Care, Organyc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic and Natural Tampons Market Strategic Shifts
Formulation transparency and certification hierarchy are restructuring competitive positioning, with third-party verification replacing brand trust as the primary purchase trigger among educated buyers.
Plant-based fiber blends combining organic cotton with bamboo or hemp are fragmenting the raw-material supplier base. Specialty agricultural cooperatives in Austria and the Netherlands are securing long-term contracts with manufacturers seeking supply security outside conventional cotton commodity markets. This diversification is fragmenting procurement concentration that previously centered on Egyptian and Turkish organic cotton sources.
EU MDR biocompatibility documentation requirements are extending clinical validation timelines for new entrants. Established manufacturers with dedicated regulatory affairs teams absorb these compliance costs more efficiently than mid-cap challengers. The non-applicator product segment faces the steepest documentation burden due to direct skin-contact surface area considerations.
Subscription-based replenishment models are displacing impulse pharmacy purchases among urban professional women. Automated delivery platforms capture buyer loyalty through convenience while bypassing retail margin stacking. This channel shift concentrates most visibly in London and Berlin, where logistics infrastructure supports same-day or next-day fulfillment commitments.
Organic and Natural Tampons Market Segmentation
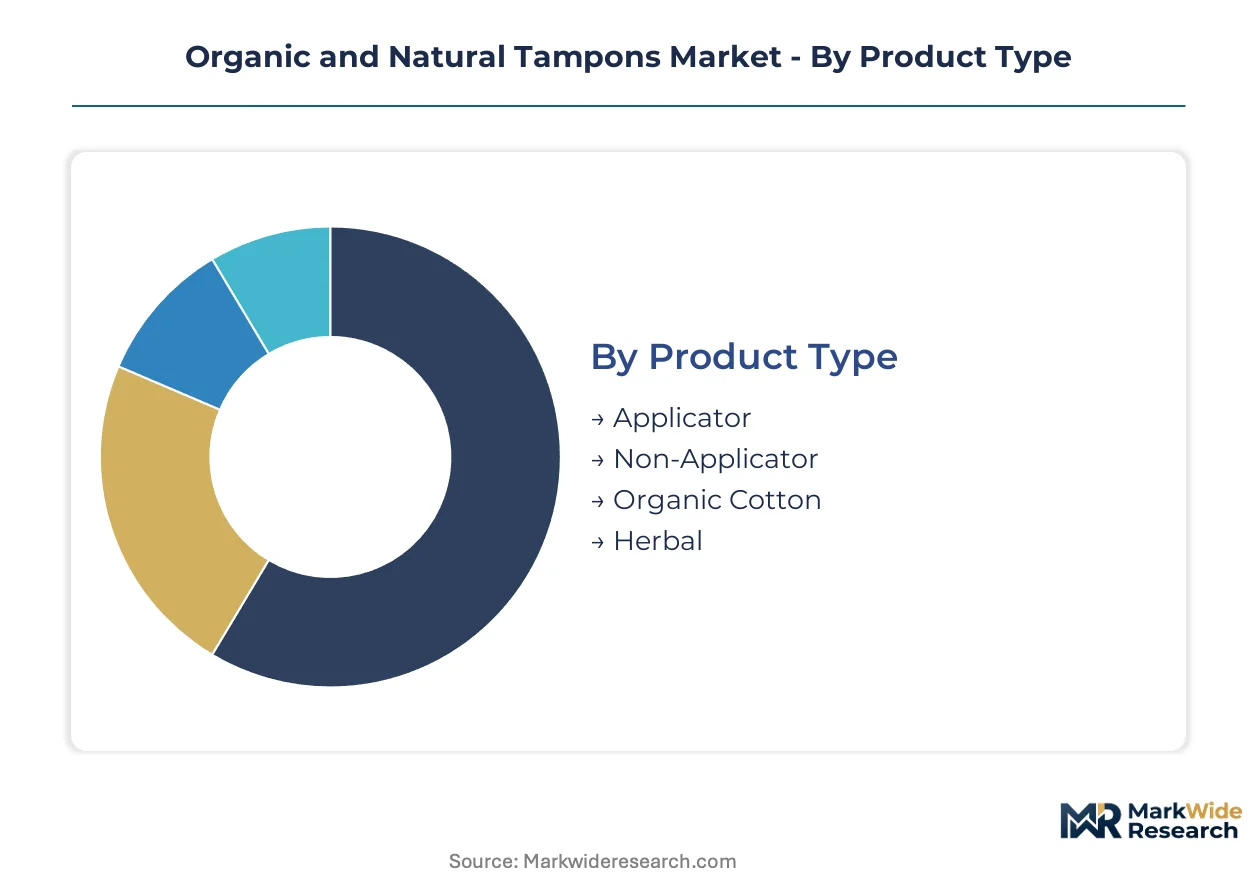
Segmentation in organic and natural tampons reveals divergent supply chain configurations and regulatory exposure profiles. Product type and distribution channel splits determine whether manufacturers face FDA Class II medical device compliance or EU REACH chemical restrictions. Understanding these divides clarifies where margin pressure concentrates versus where subscription revenue pools form.
Product Type:
Domestic production dominates applicator and non-applicator variants, while organic cotton and herbal segments rely heavily on imported agricultural inputs from certified cooperatives in Turkey and India.
- Applicator:Cylindrical devices with plastic or bioplastic insertion mechanisms, typically paired with super-plus absorbency ratings. Demand clusters in US suburban pharmacy chains where first-time buyers prefer familiar insertion formats despite higher unit costs.
- Non-Applicator:Compressed organic cotton cylinders without mechanical insertion aids, requiring finger insertion. Eco-conscious buyers in German and Scandinavian urban markets drive volume here, accepting the learning curve for reduced plastic waste and compact portability.
- Organic Cotton:Certified GOTS-compliant absorbent cores free from synthetic pesticide residues.
- Herbal:Plant-infused variants incorporating chamomile or aloe extracts for claimed soothing properties.
Applicator formats command the established base. The steepest expansion runs through non-applicator variants as zero-waste commitments harden among millennial buyers.
End User:
Cost tier stratification separates premium-positioned organic certification from entry-level natural claims, with subscription pricing capturing health-conscious professionals while teens remain price-sensitive pharmacy shoppers.
- Women:Core demographic aged 25-45 with established brand loyalty patterns and willingness to pay certification premiums. Demand concentrates in London and Berlin where subscription infrastructure supports automated replenishment.
- Teens:First-time menstrual product users typically entering through parental supermarket purchases or school-based sampling programs. California and New York state-level ingredient-disclosure legislation shapes parental purchasing criteria in these markets.
- Eco-Conscious Consumers:Buyers prioritizing biodegradability and packaging minimization over absorbency performance.
- Health-Conscious Individuals:Users with specific chemical sensitivity concerns or endocrine-disruption risk perceptions.
Women sustain volume concentration. Eco-conscious consumers are climbing the fastest as zero-waste lifestyle adoption accelerates in dense urban clusters.
Distribution Channel:
Volume scale divides sharply between impulse-driven physical retail and loyalty-driven digital subscription, with margin structures inversely correlated to customer acquisition costs.
- Online Retail:Direct-to-consumer platforms and marketplace listings enabling subscription automation and personalized absorbency curation. Berlin and London logistics density supports same-day fulfillment commitments that lock in recurring revenue.
- Supermarkets:Mass-market shelf placement capturing unplanned purchases from health-curious shoppers without subscription commitment. German retail chains lead European organic certification visibility in this channel.
- Health Stores:Specialized outlets with trained staff capable of explaining GOTS certification hierarchies.
- Pharmacies:Traditional gatekeepers with pharmacist endorsement leverage, dominant in French and Italian markets.
Supermarkets anchor current volume. Online retail is gaining share fastest as urban professional women abandon pharmacy impulse patterns for convenience automation.
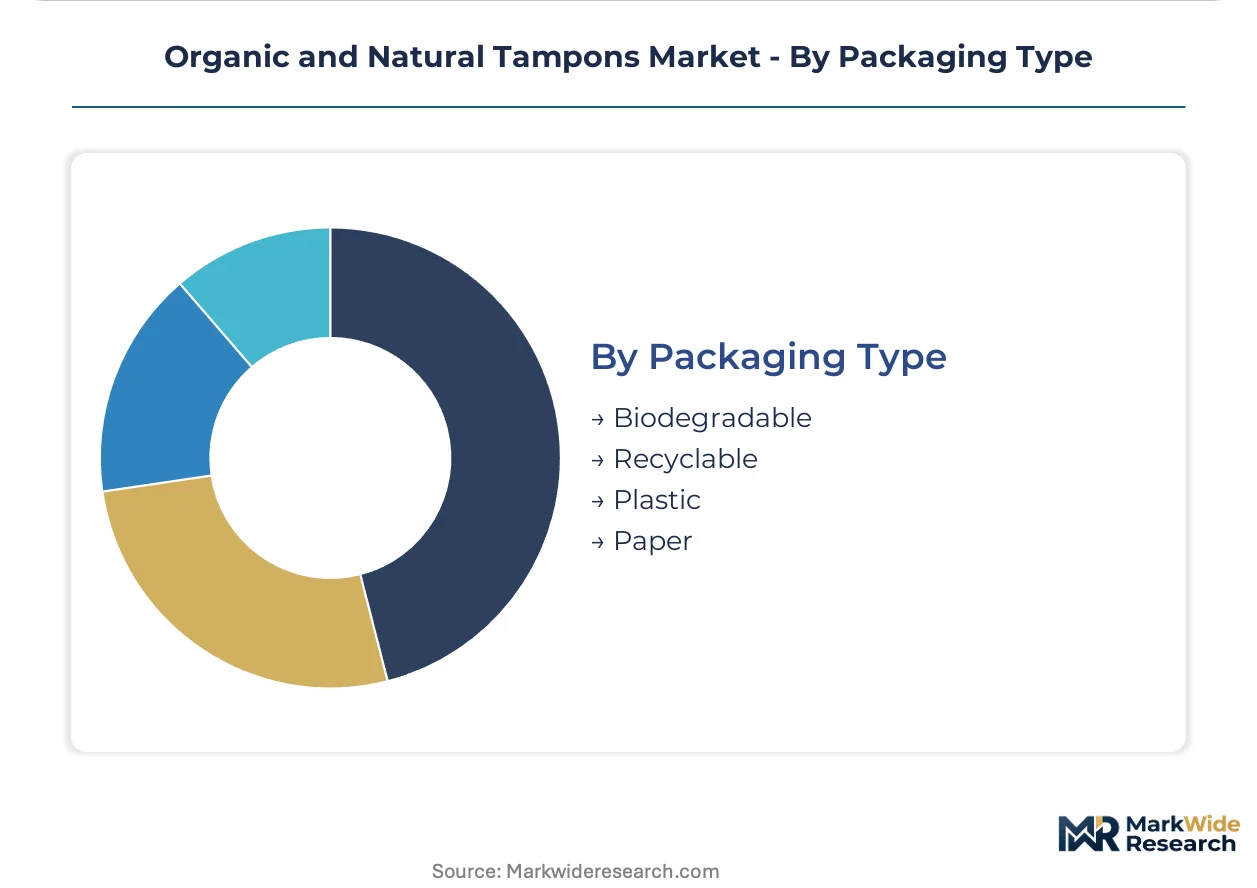
Packaging Type:
Supply concentration in agricultural fiber sourcing contrasts with fragmented packaging supplier bases, where bioplastic and paper alternatives face technical performance gaps against conventional plastics.
- Biodegradable:Wrapper and applicator materials engineered for industrial composting breakdown within specified timeframes. EU Green Deal circular economy targets accelerate procurement mandates for this segment across German and Dutch retail contracts.
- Recyclable:Mono-material packaging streams compatible with existing municipal recycling infrastructure. Demand clusters in UK and Scandinavian markets where consumer sorting compliance rates exceed Southern European levels.
- Plastic:Conventional petroleum-based wrappers and applicators with established cost and performance profiles.
- Paper:Fiber-based outer packaging with moisture-barrier limitations restricting use to low-humidity distribution environments.
Plastic formats retain the installed base. Biodegradable alternatives are expanding most quickly as retailer ESG procurement criteria harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial women in urban clusters drive geographic demand variation, with certification awareness and subscription logistics infrastructure determining where premium organic tampon penetration outpaces conventional alternatives.
Germany
Pharmacy distribution density and organic certification literacy create Europe's deepest market penetration. EU REACH residue limits on dioxins accelerate conventional brand reformulation, opening shelf space for GOTS-verified alternatives. Berlin's same-day fulfillment infrastructure anchors subscription model adoption among professional women.
United States
California and New York state-level ingredient-disclosure legislation reshape parental purchasing criteria for teen entry segments. FDA Class II medical device classification mandates absorbency testing that extends product development timelines. Direct-to-consumer platforms in Los Angeles and New York Metro bypass traditional pharmacy gatekeepers through automated replenishment.
United Kingdom
Soil Association organic standards and supermarket private-label expansion compress branded shelf space in London and Southeast England. Recyclable packaging compliance rates exceed Southern European benchmarks, favoring mono-material wrapper configurations. Natracare Limited leverages early certification to sustain British distribution dominance.
France
Pharmacist endorsement culture maintains traditional retail gatekeeper power despite subscription growth elsewhere. ANSM oversight of medical-device hygiene protocols creates compliance asymmetry favoring established players. Parisian urban clusters concentrate demand for non-applicator variants among zero-waste committed buyers.
South Korea
Korean beauty-retail crossover channels access buyers who reject conventional feminine-hygiene aisles. MFDS biocompatibility documentation requirements extend clinical validation timelines for new entrants. Seoul's specialized wellness outlets and Sephora placements anchor premium positioning for imported organic brands.
Organic and Natural Tampons Market Competitive Environment
Player mix skews toward early-certified specialists and direct-to-consumer challengers, with legacy consumer goods conglomerates holding residual pharmacy share through distribution scale rather than organic certification. Three archetypes dominate: soil-association-certified heritage brands with supply chain control, subscription-native digital-first entrants with logistics partnerships, and Korean beauty-channel crossovers with wellness retail access. Competitive moves concentrate on GOTS certification acquisition to unlock premium retail placement and bioplastic applicator R&D to resolve super-plus absorbency performance gaps.
Within the heritage-certified tier, Natracare Limited exemplifies early-mover advantage through British and Scandinavian distribution anchoring. Among subscription-native challengers, Cora Inc. and Rael Inc. occupy positions that bypass traditional gatekeepers through automated replenishment and beauty-retail crossover channels respectively.
| Leading Market Players |
|---|
| The Honest Company |
| Rael Inc. |
| Cora Inc. |
| Tampon Tribe |
| BON Health Group |
| Natracare Limited |
| Seventh Generation |
| Rif Care |
| Organyc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at GOTS-certified cotton gins in Turkey and India shapes both raw material availability and organic tampon price floors, compressing margins when harvest volatility coincides with EU REACH compliance deadlines. This scale-concentration dynamic creates asymmetric cost pressure that favors manufacturers with multi-year supply contracts over spot-market dependent challengers.
Pricing Analysis
Cost-plus contracts indexed to ICE cotton futures dominate organic cotton procurement, with GOTS certification premiums adding a fixed tier above conventional commodity benchmarks. Price differentiation rests on absorbency tier and subscription volume commitment, with super-plus variants and automated replenishment buyers showing lowest price sensitivity. Cost compression in entry-level natural claims is intensifying because synthetic-fiber competitors avoid organic input volatility. Teens remain the most price-sensitive segment, entering through parental supermarket purchases rather than certification-premium channels.
Supply Chain Analysis
Strait of Hormuz transit underwrites a portion of organic cotton shipments from Indian cooperatives to European manufacturing bases, exposing just-in-time inventory models to geopolitical disruption. Supply concentrates in Turkey, India, and Egypt for certified organic fiber, with Austrian and Dutch specialty cooperatives fragmenting procurement for plant-based blends. The chain draws from bioplastic polymers, GOTS-certified cotton cores, and medical-grade adhesives as critical inputs. Single-source vulnerability in super-absorbent polymer alternatives for bioplastic applicators threatens super-plus tier availability. Distribution runs through pharmacy chains in Germany and France, subscription platforms in London and Berlin, and Korean beauty-retail crossover channels in Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR biocompatibility documentation requirements and tightening REACH residue limits constitute a dual regulatory inflection that accelerates consolidation among organic tampon manufacturers while raising barriers for formulation-only entrants.
For Market Incumbents: Fortify GOTS certification moats through backward integration into Turkish and Indian organic cotton cooperatives, securing supply priority during harvest volatility. Expand Berlin and London same-day fulfillment infrastructure to lock in subscription revenue pools before logistics density saturates. Cora Inc.'s direct-to-consumer automation and Rael Inc.'s Sephora channel access represent replicable defensive templates against pharmacy gatekeeper erosion. For New Entrants and Emerging Players: Differentiate on Korean beauty-retail crossover positioning, where MFDS documentation burdens filter out mid-cap challengers and wellness outlet shelf space remains underallocated. Target California and New York teen entry segments, where proposed ingredient-disclosure legislation advantages early adopters of plain-language labeling. Pursue health-store distribution with trained staff capable of explaining certification hierarchies to bypass supermarket private-label compression. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-native platforms with automated replenishment infrastructure in dense urban logistics clusters. Long-term viability over the next decade favors soil-association-certified heritage brands with captive supply contracts and dedicated regulatory affairs teams capable of absorbing EU MDR compliance costs. Watch for GOTS certification timeline compression as an inflection signal, where 12-18 month audit delays advantage established players with pre-certified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acquisition | Unlocks premium retail placement in German pharmacy chains and Scandinavian health stores. |
| Bioplastic Applicator R&D | Resolves structural integrity gaps that currently limit super-plus absorbency tier performance. |
| Subscription Platform Launch | Captures recurring revenue from London and Berlin professional women abandoning impulse pharmacy purchases. |
| Korean Beauty-Retail Expansion | Accesses Sephora and wellness outlet buyers who reject conventional feminine-hygiene aisles. |
| California Compliance Pre-positioning | Anticipates plain-language ingredient-disclosure mandates that advantage early transparency adopters. |
Study Parameters
Desk research of EU MDR guidance documents, FDA 510(k) filings, and GOTS supply chain audit protocols preceded structured interviews with organic tampon brand managers, GOTS certification auditors, pharmacy category buyers, and bioplastic polymer procurement leads. Secondary validation drew from Soil Association annual reports, REACH restriction dossiers, and customs records of organic cotton trade flows. Bottom-up segment sizing triangulated against top-down category expenditure estimates from retail audit data.
Variance decomposition across product type, distribution channel, and geographic regulatory cluster informed the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Absorbency tier migration rates, subscription conversion velocity, and certification penetration curves served as industry-specific forecast inputs alongside REACH implementation timelines.
Material uncertainties — organic cotton harvest yields, bioplastic polymer technical performance breakthroughs, and state-level ingredient-disclosure legislative passage — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and buyer preference shift velocity. Practitioners should keep alternative scenarios live as EU MDR biocompatibility documentation requirements and California labeling mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Global Away-From-Home Tissue and Hygiene Market
Personal Grooming Products
Electric Massagers Market
Personal Grooming Products
Disposable Slippers Market
Personal Grooming Products
Smart Bathroom Scale Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Electric Hair Clipper and Trimmer Market
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
Shoe Insert Market
Personal Grooming Products
Tattoo Accessories Market
Personal Grooming Products
India Beard Trimmer Market
Personal Grooming Products
Mexico Beard Trimmer Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Shaving Pen Market