
 Global Training Software Market | 2026-2036
Global Training Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Training Software Market Foresight
North American SaaS infrastructure is rebalancing capacity toward enterprise learning stacks. Adobe Inc. leverages its creative software ecosystem to extend into corporate training content creation. Cornerstone OnDemand Inc. anchors the mid-market with unified talent management suites spanning recruitment through upskilling. Skillsoft Corp. specializes in compliance and leadership content libraries that occupy a defensible niche in regulated industries.
Training software encompasses digital platforms that deliver, track, and assess structured learning interventions through web-based interfaces, typically integrating SCORM or xAPI protocols for content interoperability and learner analytics aggregation. These systems serve commercial and institutional buyers by reducing instructor-led delivery costs while standardizing knowledge transfer across distributed workforces. Cloud-based deployment leads volume adoption as IT departments outsource infrastructure maintenance, though hybrid architectures retain traction in financial services and defense sectors where data residency requirements constrain pure SaaS migration. Learning Management System offerings dominate solution-level revenue, while assessment software represents the fastest-expanding category as organizations shift from completion metrics to competency-verification models.
The U.S. Department of Labor enforces training documentation requirements under OSHA standards, while the EU AI Act imposes transparency obligations on adaptive learning algorithms deployed within European member states. India's BIS certification framework for educational technology products is tightening market access for foreign platform providers. Stakeholders must monitor how divergent data localization mandates between the European GDPR regime and emerging Indian digital sovereignty rules reshape cross-border content delivery architectures.
Market Dynamics
Cloud migration is compressing deployment timelines while AI personalization engines reallocate vendor R&D budgets away from static content libraries toward adaptive learning architectures.
Growth Catalysts
- OSHA Documentation Mandates:US employers must maintain auditable training records for workplace safety compliance, forcing systematic digitization of manual tracking processes.
- Healthcare Accreditation Standards:Joint Commission requirements for continuing medical education are redirecting hospital procurement toward integrated learning management systems.
- xAPI Protocol Adoption:Next-generation learning record stores enable granular competency tracking beyond SCORM completion metrics, accelerating platform replacement cycles.
Market Restraints
- Data Residency Requirements:GDPR localization rules and India's emerging digital sovereignty framework fragment cloud infrastructure strategies, raising compliance costs for cross-border content delivery.
- Legacy System Integration Friction:Financial services and defense sectors maintain hybrid architectures due to classified data handling protocols, slowing pure SaaS adoption.
- Skill Gap in Instructional Design:Shortage of professionals capable of converting instructor-led curricula into effective digital formats constrains content production velocity.
Strategic Opportunities
- EU AI Act Transparency Requirements:Adaptive learning algorithms deployed in European member states must demonstrate explainable decision-making, creating demand for compliance-certified personalization engines.
- Competency-Based Assessment Expansion:Organizations are shifting from completion metrics to verified skill demonstration, opening revenue pools for integrated assessment software vendors.
- German Mittelstand Digitization:Mid-sized industrial enterprises represent underpenetrated demand for unified talent management suites spanning recruitment through upskilling.
Industry Challenges
- Algorithmic Bias Certification:AI-driven learning recommendations require audit trails for fairness validation, extending product development timelines before commercial release.
- Content Interoperability Fragmentation:Competing standards between SCORM, xAPI, and proprietary formats force vendors to maintain multiple integration layers, elevating engineering overhead.
- Change Management Resistance:Instructor-led training departments obstruct platform adoption to preserve headcount, requiring executive sponsorship to overcome organizational inertia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Training Software Market |
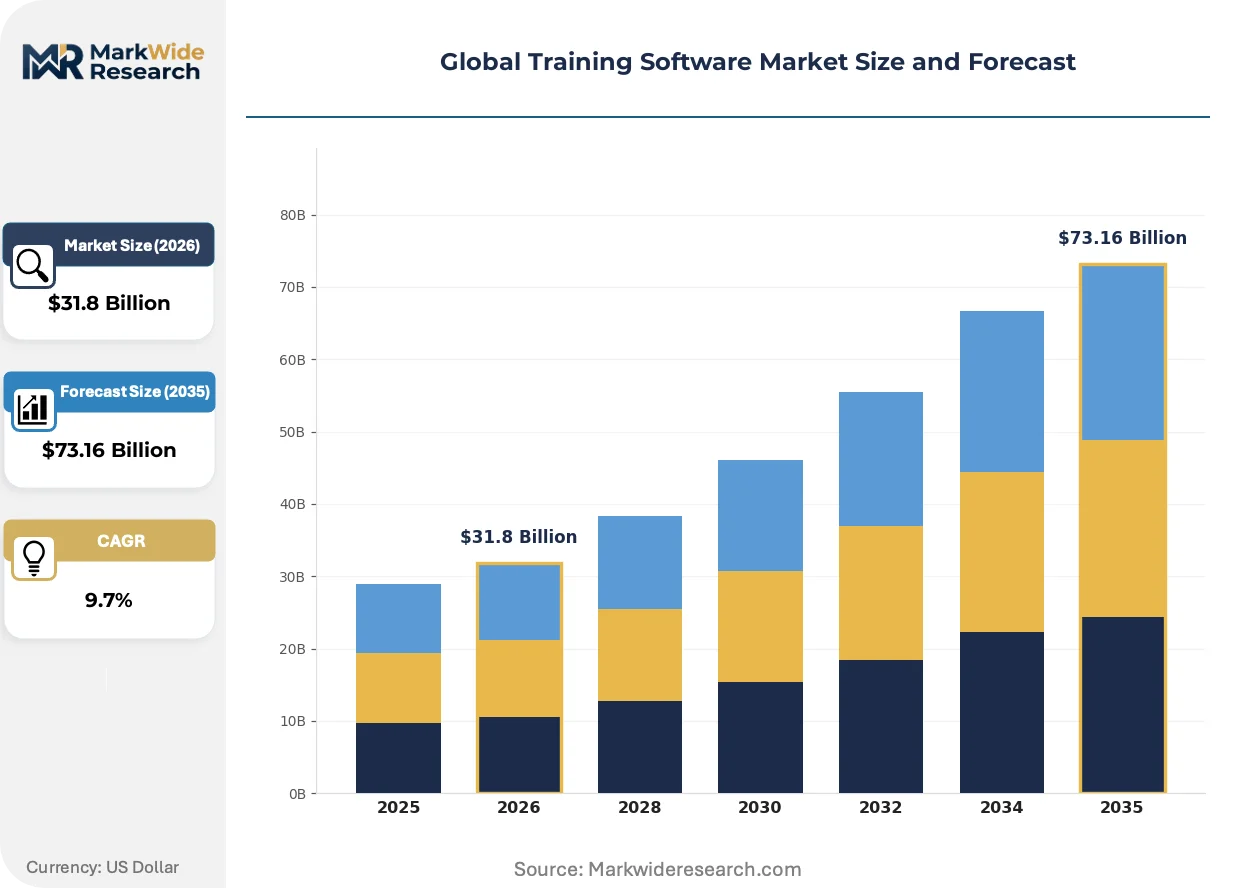
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $73.16 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Self-Hosted Solution Offering: Learning Management System, Virtual Classroom, Authoring Tools, Content Management, Assessment Software Application: Employee Onboarding, Skill Development, Compliance Training, Sales Enablement, Leadership Training Customer Type: Corporate Enterprises, Government Agencies, Educational Institutions, Nonprofit Organizations |
| Companies Covered | D2L Inc., Korn Ferry, Skillsoft Corp., Docebo Inc., Franklin Covey Co., Adobe Inc., Cisco Systems Inc., Cornerstone OnDemand Inc., Articulate Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Training Software Market Shifts & Advancements
Generative AI is restructuring content production economics while regulatory pressure on algorithmic transparency forces architectural redesigns of personalization engines.
Adaptive learning algorithms are consolidating market share among vendors capable of real-time competency gap analysis. Large employers in regulated industries—pharmaceuticals, energy, aviation—are prioritizing platforms with embedded assessment verification. This capability compression is marginalizing point solutions that lack integrated analytics stacks.
The EU AI Act imposes documentation requirements on machine learning systems that profile learners or adjust content difficulty automatically. Vendors must now maintain technical files demonstrating human oversight mechanisms. European healthcare and financial services buyers are demanding pre-certified platforms, accelerating procurement consolidation toward established compliance leaders.
Enterprise buyers are unbundling content libraries from delivery infrastructure, selecting best-of-breed assessment tools while retaining legacy learning management systems. This procurement pattern favors vendors with API-first architectures and modular pricing. German automotive and Indian IT services sectors exhibit the strongest preference for composable learning stacks over unified suites.
Global Training Software Market Segmentation
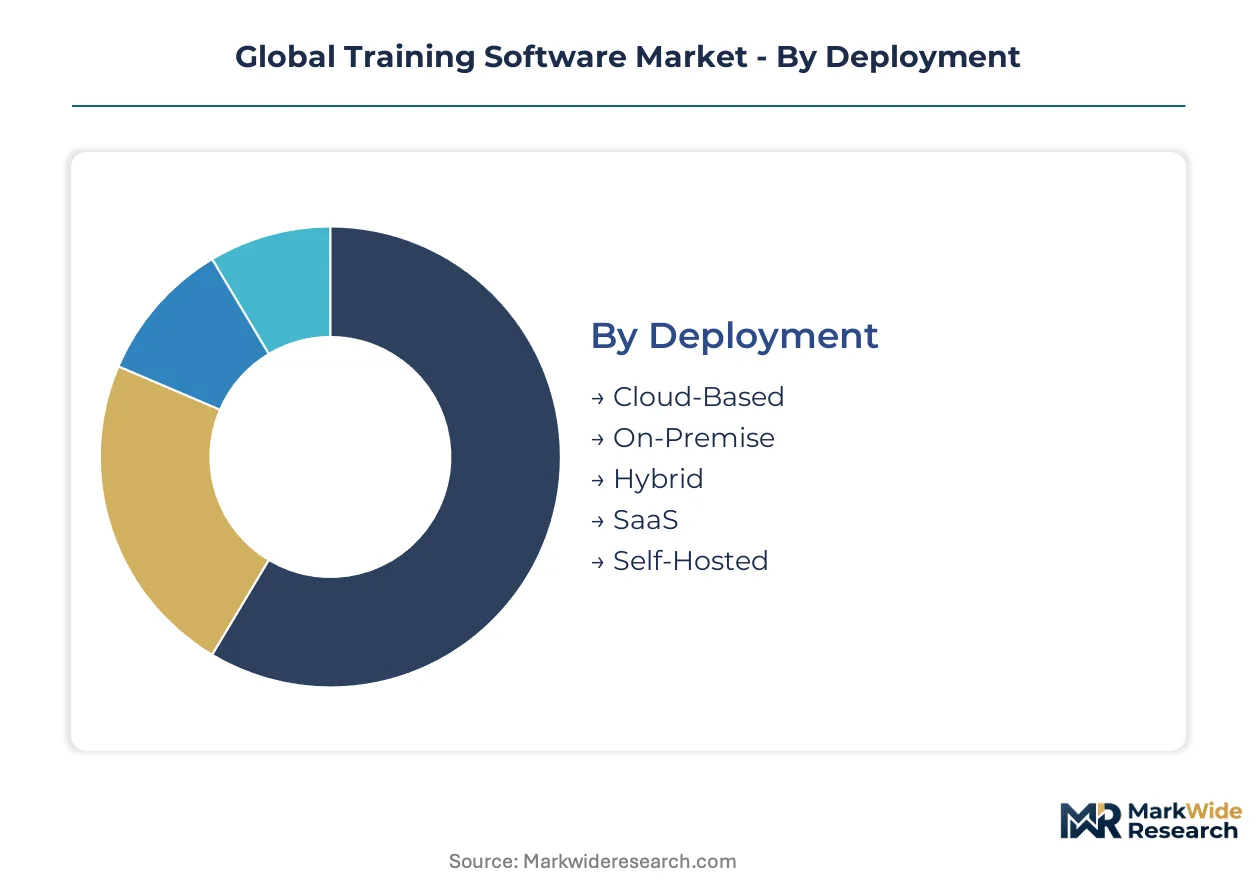
Training software procurement diverges sharply across deployment architectures, solution types, and buyer maturity. Vendors must align platform capabilities with specific compliance burdens, workforce dispersion patterns, and legacy system constraints that vary by segment.
Deployment:
Cloud infrastructure specifications determine integration complexity, data residency compliance, and total cost of ownership for enterprise buyers.
- Cloud-Based:Multi-tenant architectures with automatic scaling eliminate server maintenance overhead. US healthcare systems and German automotive suppliers prioritize these deployments for distributed workforce access, though GDPR localization requirements force EU-specific instance provisioning.
- On-Premise:Dedicated hardware installations behind corporate firewalls maintain complete data sovereignty. Indian defense contractors and US financial institutions mandate this architecture for classified or regulated information handling, accepting higher capital expenditure for compliance assurance.
- Hybrid:Split configurations keep sensitive records on local servers while pushing general content to cloud edge nodes. This architecture satisfies India's emerging digital sovereignty framework without sacrificing scalability for non-regulated training modules.
- SaaS:Subscription models with standardized feature sets accelerate procurement cycles for mid-market buyers. German Mittelstand manufacturers favor per-seat pricing that aligns costs with seasonal hiring fluctuations.
- Self-Hosted:Single-tenant cloud instances on vendor-managed infrastructure offer customization without hardware ownership. This option attracts US nonprofit organizations with limited IT staff but strict donor data protection requirements.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution Offering:
Functional specialization across the learning technology stack creates distinct vendor positioning based on integration depth versus point solution agility.
- Learning Management System:Centralized platforms orchestrating enrollment, delivery, and certification tracking. US hospital networks anchor procurement here to consolidate fragmented departmental systems under Joint Commission audit trails.
- Virtual Classroom:Real-time video conferencing with breakout rooms and interactive whiteboards. Indian IT services firms drove pandemic-era adoption; sustained demand now concentrates in sales enablement scenarios requiring live role-play.
- Authoring Tools:Software for creating SCORM- and xAPI-compliant content without programming expertise. German industrial training departments use these to convert instructor-led safety protocols into self-paced digital modules.
- Content Management:Repositories organizing learning assets with version control and metadata tagging. Government agencies in the United States deploy these for interdepartmental knowledge sharing with granular access permissions.
- Assessment Software:Platforms verifying competency through proctored examinations and skill demonstrations. EU AI Act transparency requirements are accelerating procurement of these tools with embedded audit trails for algorithmic decision-making.
Learning Management System dominates installed base; Assessment Software climbs the fastest.
Application:
Use case specificity dictates content library requirements, assessment rigor, and integration with adjacent HR systems.
- Employee Onboarding:Structured pathways accelerating time-to-productivity for new hires. US technology companies prioritize these systems to standardize remote onboarding across distributed engineering teams.
- Skill Development:Continuous upskilling aligned with evolving role requirements. Indian business process outsourcing firms deploy these at scale to maintain service quality amid high attrition environments.
- Compliance Training:Mandatory certification tracking for regulatory adherence. OSHA documentation mandates in the United States and EU AI Act obligations in Europe make this the most defensible budget line for procurement.
- Sales Enablement:Product knowledge and negotiation skill reinforcement tied to revenue metrics. German pharmaceutical field forces rely on these platforms to maintain detailing certification across dispersed territories.
- Leadership Training:Executive development programs with cohort-based progression and coaching integration. Nonprofit organizations in the United States leverage these for succession planning in resource-constrained environments.
Compliance Training commands the largest absolute spend; Sales Enablement shows steepest expansion trajectory.
Customer Type:
Organizational scale and funding mechanisms create divergent requirements for pricing flexibility, data isolation, and content customization.
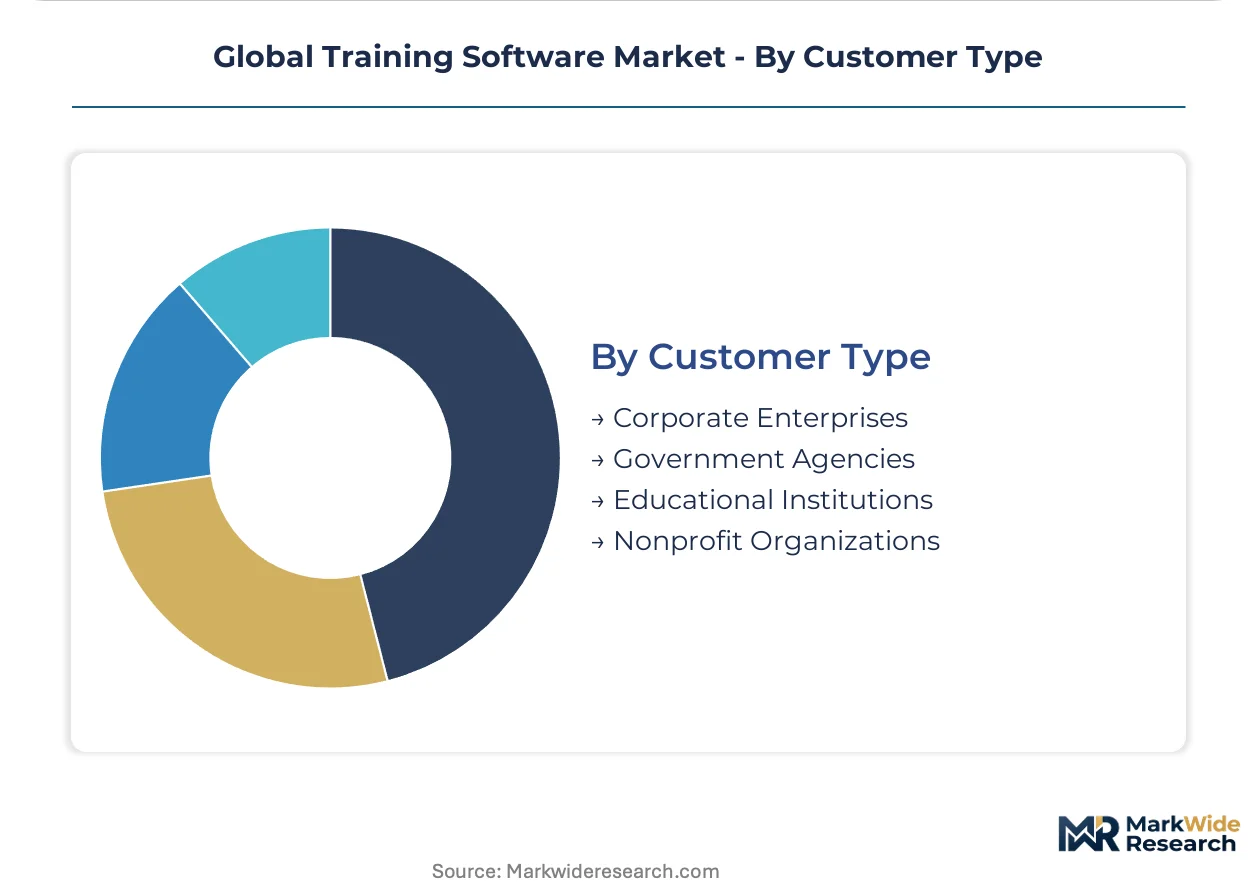
- Corporate Enterprises:Large employers with dedicated L&D budgets and complex integration needs. These buyers drive demand for unified talent management suites spanning recruitment through retirement.
- Government Agencies:Public sector entities with procurement regulations and transparency mandates. US federal buyers require FedRAMP authorization; Indian state governments prioritize BIS-certified platforms.
- Educational Institutions:Universities and K-12 systems blending academic instruction with workforce preparation. These institutions favor open standards interoperability to prevent vendor lock-in across multi-year student lifecycles.
- Nonprofit Organizations:Mission-driven entities with constrained budgets and volunteer management needs. These buyers gravitate toward grant-funded implementations with donated or discounted software licensing.
Corporate Enterprises lead on absolute revenue contribution; Government Agencies lead on contract duration and renewal predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement budgets for enterprise learning platforms outpace German Mittelstand investment cycles, while India's IT services sector drives volume adoption across Asia-Pacific. Regulatory divergence between OSHA documentation mandates, EU AI Act transparency requirements, and India's BIS certification framework fragments vendor go-to-market strategies.
United States
Healthcare networks and federal contractors anchor domestic demand as Joint Commission audit trails and FedRAMP authorization requirements redirect procurement toward integrated compliance platforms. OSHA mandates auditable training records for workplace safety, forcing systematic digitization across manufacturing and logistics operations. Hospital networks in Texas and California consolidate fragmented departmental systems under unified learning management architectures.
Germany
Automotive suppliers and pharmaceutical field forces prioritize competency-verification platforms with embedded assessment engines. The EU AI Act imposes documentation requirements on adaptive learning algorithms, accelerating procurement of pre-certified personalization engines. Industrial training departments in Bavaria and Baden-Württemberg convert instructor-led safety protocols into self-paced digital modules using authoring tools.
India
Business process outsourcing firms and IT services companies deploy training software at scale to maintain service quality amid high attrition environments. BIS certification frameworks for educational technology products tighten market access for foreign platform providers. Bangalore and Hyderabad clusters exhibit strongest preference for composable learning stacks over unified suites.
United Kingdom
Financial services firms and professional services organizations drive demand for hybrid deployment architectures balancing data residency with scalability. GDPR localization rules force EU-specific instance provisioning for cloud-based platforms. London's fintech corridor prioritizes API-first architectures enabling best-of-breed assessment tool integration with legacy systems.
Japan
Manufacturing conglomerates and automotive exporters invest in leadership development platforms with cohort-based progression and coaching integration. METI industrial policy encourages workforce reskilling aligned with digital transformation initiatives. Tokyo-Osaka corridor concentrates procurement of virtual classroom solutions for sales enablement and remote technical training.
Global Training Software Market Competitive Landscape
United States vendors anchor the premium tier with unified talent management suites; European specialists hold compliance-certified niches. Market structure exhibits moderate consolidation with three distinct strategic tiers: enterprise-scale platform providers, vertical-specific content libraries, and modular API-first toolmakers. Dominant competitive moves include portfolio diversification into adjacent HR technologies and geographic expansion through localized data center provisioning.
Within the enterprise-scale tier, Adobe Inc. and Cornerstone OnDemand Inc. exemplify platform consolidation strategies spanning content creation through talent lifecycle management. Skillsoft Corp. occupies a defensible position in regulated industries with specialized compliance and leadership content libraries. These three anchors represent divergent archetypes: creative ecosystem extension, unified talent management, and vertical content specialization.
| Leading Market Players |
|---|
| D2L Inc. |
| Korn Ferry |
| Skillsoft Corp. |
| Docebo Inc. |
| Franklin Covey Co. |
| Adobe Inc. |
| Cisco Systems Inc. |
| Cornerstone OnDemand Inc. |
| Articulate Global Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists dominate the training software vendor landscape, concentrating ownership among portfolio companies with disciplined pricing power and centralized procurement leverage over cloud infrastructure providers.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for mid-market SaaS tiers as local data center provisioning reduces cross-border hosting premiums. Three-tier pricing structure across enterprise, professional, and basic levels differentiates by compliance certification depth and API access granularity. Cost compression in the basic tier is intensifying because open-source learning record store alternatives commoditize entry-level functionality. Nonprofit organizations and small educational institutions exhibit highest price sensitivity, while pharmaceutical and energy buyers prioritize audit-trail completeness over per-seat cost.
Supply Chain Analysis
Dual-sourcing requirements in US federal procurement and EU healthcare systems mandate multi-supplier qualification for cloud infrastructure and content library components. Supply concentrates in the United States, Ireland, and Singapore for hyperscale data center capacity, with Germany and India emerging as secondary nodes for GDPR and digital sovereignty compliance. Platform engineering draws from specialized labor pools in Bangalore, Berlin, and Austin for adaptive algorithm development. Single-source vulnerability in AI training data licensing creates concentration risk for personalization engine vendors. Distribution runs through direct enterprise sales teams with embedded customer success functions, supplemented by systems integrator partnerships for complex hybrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by regulatory mandates that institutionalize recurring procurement cycles across healthcare, energy, and defense verticals.
For Market Incumbents: Anticipate margin compression from API-first modular competitors by deepening integration partnerships with HRIS and talent management suites. Prioritize FedRAMP and EU AI Act pre-certification investments to defend position against compliance-native challengers. Build captive data center capacity in India and Germany to neutralize digital sovereignty requirements as a procurement discriminator. For New Entrants and Emerging Players: Enter via assessment software specialization targeting German Mittelstand manufacturers with unmet competency-verification needs. German automotive suppliers and industrial training departments represent the most penetrable segment due to legacy system fragmentation and instructor-led conversion backlogs. Pursue channel partnerships with established HR consultancies rather than direct field sales buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-specific content libraries with embedded regulatory expertise but limited platform infrastructure. Five-to-ten-year viability hinges on adaptive algorithm differentiation and compliance certification moats. Monitor EU AI Act enforcement intensity as the critical inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Accelerates procurement cycles among European healthcare and financial services buyers requiring explainable algorithm documentation. |
| Hybrid Cloud Infrastructure Expansion | Enables Indian defense contractors and US financial institutions to satisfy data residency mandates without sacrificing scalability. |
| Assessment Software Acquisition | Captures fastest-expanding revenue pool as organizations shift from completion metrics to verified skill demonstration models. |
| xAPI Protocol Native Development | Replaces legacy SCORM-dependent platforms with granular competency tracking that commands premium pricing in regulated industries. |
| German Mittelstand Channel Partnership | Unlocks underpenetrated mid-sized industrial demand through embedded HR consultant relationships rather than direct sales overhead. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with chief learning officers, IT procurement officers, platform engineers, and compliance specialists at healthcare networks, automotive suppliers, and IT services firms. Secondary validation draws from SEC filings, EU regulatory submissions, hyperscaler capex disclosures, and hospital procurement databases. Bottom-up deployment counts and top-down enterprise software spending estimates were triangulated to anchor market sizing.
Rate-of-change decomposition across the projection horizon separates baseline SaaS subscription growth from accelerated replacement cycles driven by xAPI adoption and AI Act compliance deadlines. Segmentation dimensions modeled include deployment architecture, solution type, application use case, and customer maturity tier. CAGRs were derived from regression analysis against historical IT spending elasticity and regulatory implementation timelines, with specific adjustment for OSHA documentation mandate enforcement intensity and Joint Commission audit trail digitization waves.
Inputs from federal procurement databases and EU regulatory filings were available through the study window; gaps in real-time pricing data from private vendor transactions introduce uncertainty bands around revenue concentration estimates. Deviation in EU AI Act enforcement timelines or India's BIS certification implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Learning Management Systems (LMS)
Global Exam Management Software Market
Learning Management Systems (LMS)
Managed Learning Service Market
Learning Management Systems (LMS)
Global Mobile Learning Market
Learning Management Systems (LMS)
Smart Learning Systems Market
Learning Management Systems (LMS)
School Management System Market
Learning Management Systems (LMS)
Global Classroom Management Software Market
Learning Management Systems (LMS)
Global Corporate M-Learning Market
Learning Management Systems (LMS)
Qatar E-Learning Management System Market
Learning Management Systems (LMS)
Global Learning Management Systems (LMS) Market
Learning Management Systems (LMS)
Asia-Pacific Learning Management Systems Market
Learning Management Systems (LMS)
E-Learning Solutions Market
Learning Management Systems (LMS)
Healthcare LMS Software Market
Learning Management Systems (LMS)
Corporate Learning Management System Market