
 Global Virtual Training and Simulation Market | 2026-2036
Global Virtual Training and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Training and Simulation Market Foresight
North American defense primes is restructuring supplier networks around sovereign simulation capacity. CAE Inc. anchors the commercial aviation training segment with full-flight simulator manufacturing and airline operator partnerships. Rheinmetall AG leverages land-system simulation expertise to compete for NATO armored vehicle crew training contracts. Lockheed Martin Corporation dominates military flight simulation through captive integration with fighter and rotary-wing platforms.
Virtual training and simulation encompasses computer-generated immersive environments that replicate operational conditions through physics-based modeling, real-time rendering, and haptic feedback interfaces for skill acquisition without physical asset exposure. The technology stack spans Augmented Reality, Virtual Reality, Mixed Reality, 3D Visualization, and Gesture Recognition, with Mixed Reality commanding premium deployment costs while Virtual Reality scales fastest across corporate training budgets. Application demand stratifies across Military Simulation, Corporate Training, Flight Simulation, Medical Simulation, and Maritime Simulation, where Military Simulation absorbs the largest capital outlays and Medical Simulation represents the fastest-growing margin pool as residency programs replace cadaver-based procedures.
The U.S. FAA mandates simulator hours for type-rating certifications, while the EU AI Act imposes transparency requirements on adaptive training algorithms deployed in European aviation academies. China's MIIT issues GB standards governing VR hardware interoperability for industrial training deployments. Stakeholders must monitor divergence between U.S. ITAR-controlled simulation exports and EU open-architecture procurement specifications as dual-use classification debates reshape market access rules.
Market Dynamics
Defense procurement cycles and FAA certification mandates are compressing deployment timelines for immersive training infrastructure, forcing suppliers to align development roadmaps with sovereign capability requirements rather than commercial off-the-shelf specifications.
Growth Catalysts
- FAA Simulator Mandates:The U.S. Federal Aviation Administration's updated pilot training requirements are accelerating simulator-based certification pathways, displacing legacy flight hours with synthetic training environments for type ratings and recurrent checks.
- Medical Residency Reform:Surgical training programs are replacing cadaver-based procedures with haptic-enabled virtual environments, creating pull for high-fidelity tissue modeling and force-feedback instrumentation across accredited teaching hospitals.
- Physics-Based Modeling Advances:Real-time computational fluid dynamics and finite element analysis are enabling vehicle crew trainers to replicate terrain deformation and ballistic effects without live-fire exercises.
Market Restraints
- ITAR Export Controls:U.S. International Traffic in Arms Regulations restrict cross-border transfer of military-grade simulation source code, fragmenting supplier ecosystems and forcing non-U.S. buyers to develop parallel indigenous capabilities.
- Display Hardware Concentration:High-resolution micro-OLED and pancake lens manufacturing concentrates in East Asian supply chains, exposing Western simulator OEMs to single-source dependencies for headset subsystems.
- Motion Platform Energy Intensity:Full-flight simulators require 200-400 kW electrical feeds for hexapod actuation and environmental control, limiting deployment to facilities with industrial-grade power infrastructure.
Strategic Opportunities
- Industrial Training in India:The country's Production-Linked Incentive scheme for manufacturing is creating demand for VR-based equipment familiarization across automotive and electronics assembly lines where skilled technician pipelines remain underdeveloped.
- EU AI Act Compliance Services:Aviation academies deploying adaptive training algorithms require audit-ready transparency documentation, opening consulting and software validation revenue streams for compliance-focused vendors.
- Mixed Reality Maritime Bridge:Convergence of spatial computing with physical helm consoles allows ship operators to overlay digital navigation data onto real instrument panels, reducing simulator footprint for coastal vessel certification.
Industry Challenges
- Systems Integration Talent Scarcity:Deploying multi-vendor simulation stacks requires specialists fluent in both real-time operating systems and game engine architectures, a hybrid skill set concentrated among defense contractors and absent in commercial IT labor pools.
- Legacy Platform Interoperability:NATO armored vehicle fleets operate mixed-nationality equipment generations, forcing training system architects to bridge 1980s analog interfaces with modern digital synthetic environments.
- Residency Program Accreditation Cycles:Medical simulation vendors must synchronize product releases with ACGME review timelines, compressing revenue recognition windows to 18-month curriculum adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Training and Simulation Market |
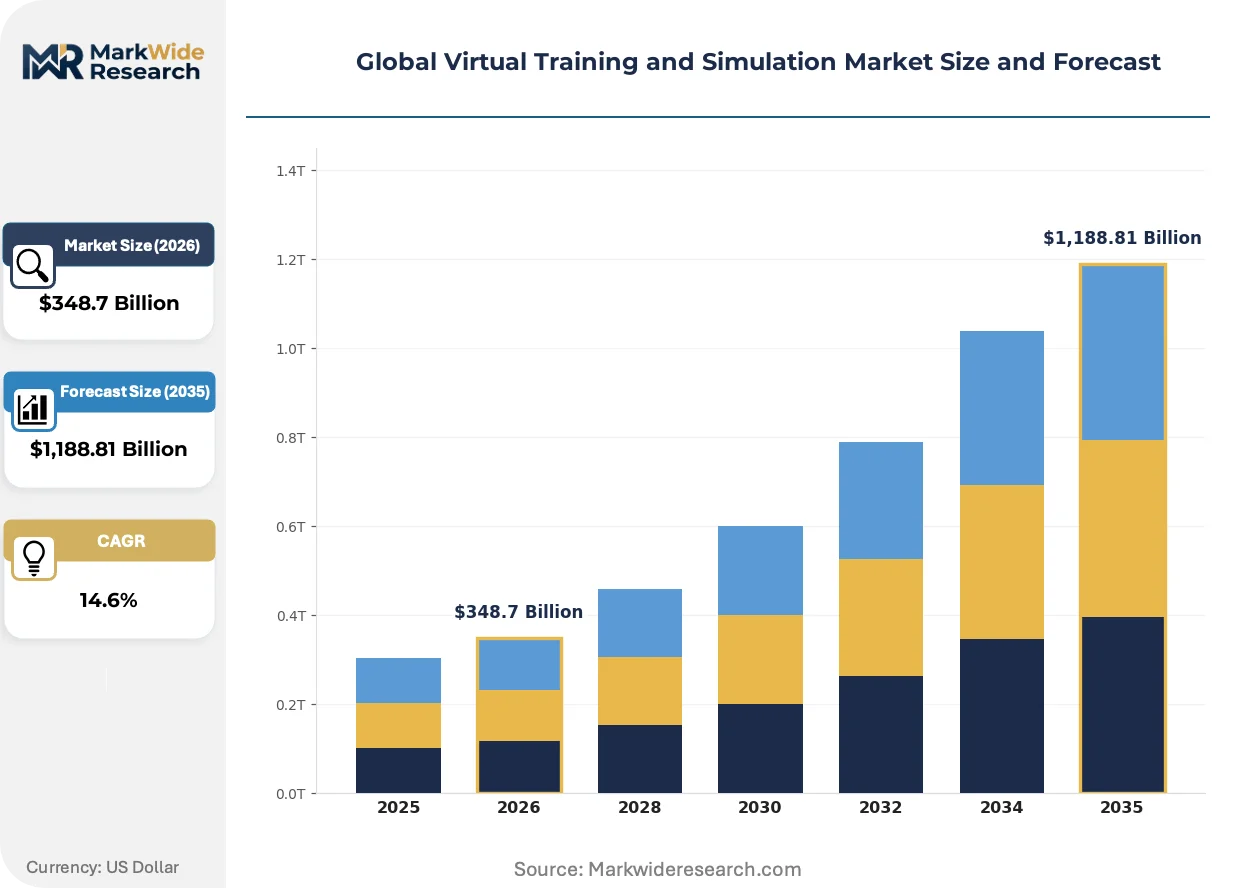
| Market Size in 2026 | $348.7 Billion |
| Market Size in 2035 | $1,188.81 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Augmented Reality, Virtual Reality, Mixed Reality, 3D Visualization, Gesture Recognition Application: Military Simulation, Corporate Training, Flight Simulation, Medical Simulation, Maritime Simulation End User Industry: Defense Contractors, Aviation, Healthcare Institutions, Maritime Operators, Manufacturing Firms Deployment Mode: Cloud-based, On-Premise, Hybrid, Web-based, Mobile-based |
| Companies Covered | CAE Inc., Rheinmetall AG, Lockheed Martin Corporation, Saab AB, Cubic Corporation, Thales Group, Collins Aerospace, L3Harris Technologies Inc., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Training and Simulation Market Shifts & Advancements
Simulation fidelity requirements are diverging across end-use verticals, with defense customers prioritizing physics accuracy while commercial buyers optimize for deployment velocity and hardware cost reduction.
Digital twin architectures are converging with live training environments, enabling maintenance crews to rehearse procedures on exact equipment replicas before physical access. Airlines including Lufthansa and United are deploying these synchronized environments for line maintenance qualification, reducing aircraft downtime and spare parts consumption. The structural consequence is converging with traditional classroom instruction, collapsing the boundary between theoretical knowledge and hands-on competency verification.
The EU AI Act's transparency requirements for high-risk AI systems are mandating algorithmic audit trails in adaptive aviation training platforms. European academies must now document decision pathways for personalized learning adjustments, increasing compliance overhead but creating competitive differentiation for vendors with pre-certified explainability frameworks. Flight training organizations in Germany and France are prioritizing suppliers with established conformity assessment procedures, reshaping procurement evaluation criteria.
After-sales service unbundling is fragmenting long-term simulator support contracts. Airlines and military operators are separating hardware maintenance from software update subscriptions, pressuring OEMs to defend recurring revenue through modular content libraries rather than captive service agreements. This pattern is most visible in the United States, where carrier consolidation has concentrated buyer leverage and enabled aggressive contract renegotiation for legacy full-flight simulator fleets.
Global Virtual Training and Simulation Market Segmentation
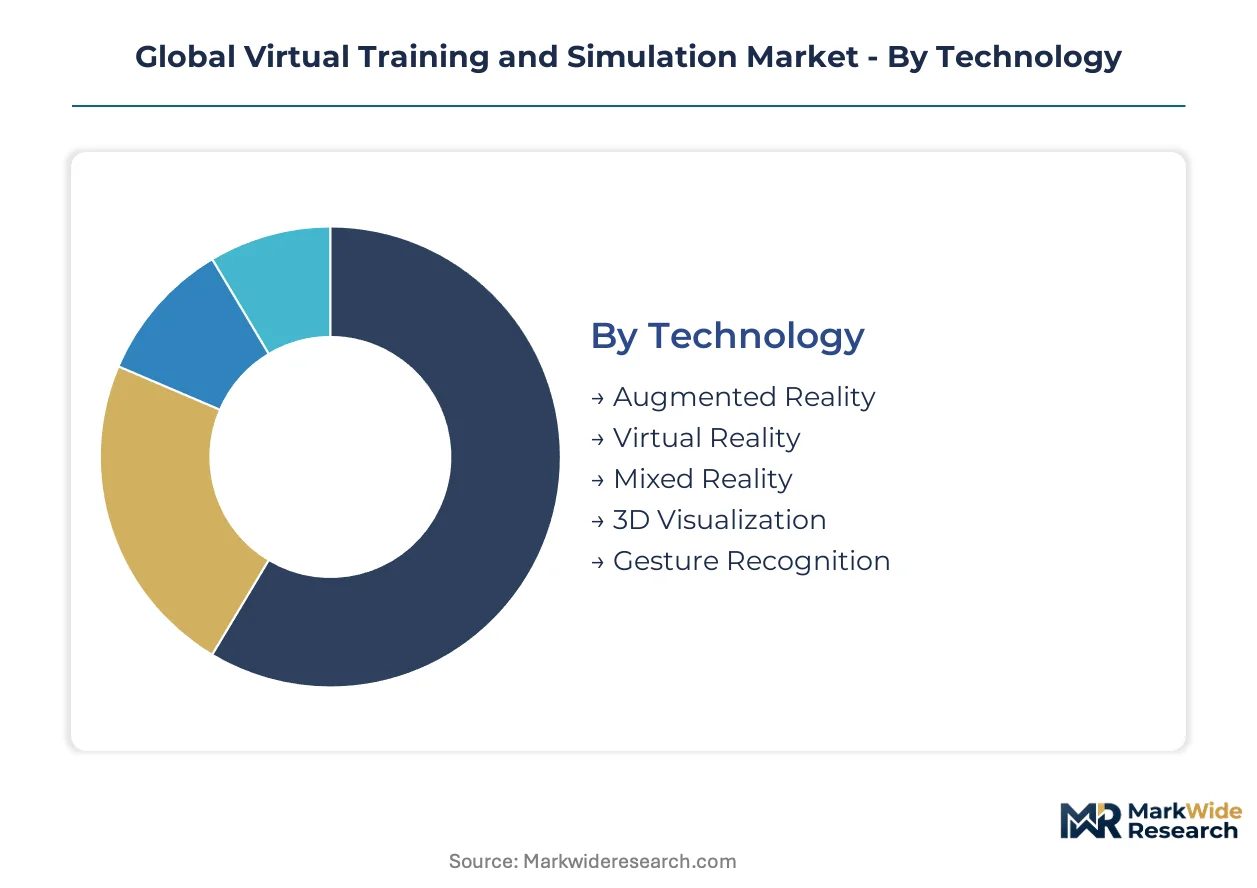
Technology choices in virtual training determine capital intensity and deployment velocity. Application focus shapes procurement cycles and regulatory exposure. End-user industry concentration drives sovereign capability requirements and export control sensitivity.
Technology:
Cost tier separates premium immersive systems from scalable baseline deployments.
- Mixed Reality:Combines optical see-through displays with spatial mapping to anchor digital content in physical environments. Surgical training programs at Johns Hopkins and Mayo Clinic deploy these systems for anatomy visualization where hand-eye coordination fidelity is non-negotiable.
- Virtual Reality:Fully occlusive headsets with inside-out tracking deliver the lowest cost-per-seat for procedural training. Corporate learning departments at Siemens and Boeing favor VR for equipment familiarization at scale where physical presence is not required.
- Augmented Reality:Overlay graphics on real-world views through smartphone or headset cameras for maintenance guidance. Field technicians at Deutsche Bahn use AR work instructions for rolling stock repair.
- 3D Visualization:Desktop and powerwall displays render synthetic environments without head-mounted hardware. Naval architects at BAE Systems employ these for ship design review and damage control training.
- Gesture Recognition:Computer vision and sensor arrays track hand and body motion without controllers. Automotive assembly trainers at BMW deploy gesture interfaces for ergonomic assessment.
Virtual Reality leads volumes today; Mixed Reality is gaining share fastest.
Application:
Customer type determines certification rigor and replacement cycle length.
- Military Simulation:Networked collective training systems replicate combined arms operations with threat environment fidelity. U.S. Army Synthetic Training Environment contracts require terrain databases covering the Korean Peninsula and Eastern European corridors.
- Medical Simulation:Haptic-enabled virtual patients replace cadaver-based procedures for residency credentialing. ACGME-accredited programs at Cleveland Clinic and Mass General Brigham drive demand for tissue deformation modeling.
- Flight Simulation:Full-flight simulators with motion platforms achieve zero-flight-time certification for type ratings. FAA mandates at U.S. Part 121 carriers accelerate replacement of 1990s-era Level C devices.
- Corporate Training:Scalable VR modules for safety and soft skills deploy across distributed workforces. Amazon fulfillment centers use these for hazardous material handling certification.
- Maritime Simulation:Bridge resource management trainers replicate vessel handling in constrained waters. STCW compliance requirements at Singapore and Rotterdam maritime academies sustain replacement demand.
Military Simulation absorbs the largest capital outlays; Medical Simulation is expanding most quickly.
End User Industry:
Geography concentrates procurement authority and shapes vendor qualification requirements.
- Defense Contractors:Prime systems integrators Lockheed Martin and Rheinmetall specify simulation subsystems for platform-embedded training. ITAR-controlled source code restrictions force parallel development tracks for allied export programs.
- Aviation:Airlines and training centers purchase full-flight simulators with 20-year service life expectations. Lufthansa Aviation Training and CAE operate the densest installed bases in Germany and Canada respectively.
- Healthcare Institutions:Academic medical centers and teaching hospitals acquire surgical simulators through capital equipment budgets. Joint Commission accreditation standards influence purchasing committee composition.
- Maritime Operators:Shipping companies and port authorities invest in bridge simulation for license renewal and incident investigation. Maersk and MSC maintain internal training facilities in Denmark and Switzerland.
- Manufacturing Firms:Automotive and electronics producers deploy VR for assembly line pre-production validation. India's PLI scheme recipients in Tamil Nadu and Karnataka are emerging customers.
Defense Contractors lead volumes today; Healthcare Institutions are climbing the fastest.
Deployment Mode:
Volume and margin profile diverge between centralized infrastructure and distributed access models.
- On-Premise:Dedicated server rooms and local rendering hardware support classified or latency-sensitive applications. U.S. military installations require air-gapped networks for mission rehearsal systems.
- Cloud-based:Streaming rendering and centralized content management reduce hardware refresh burdens. Commercial aviation training centers in the United Kingdom pilot these for remote instructor stations.
- Hybrid:Local edge processing with cloud content synchronization balances performance and scalability. German automotive OEMs favor this architecture for global engineering training.
- Web-based:Browser-delivered 3D environments eliminate client software installation. Corporate compliance training at financial institutions in New York and London deploys these for rapid rollout.
- Mobile-based:Smartphone and tablet AR applications extend reach to field personnel without dedicated hardware. Utility line workers at National Grid use these for transformer inspection guidance.
On-Premise leads volumes today; Cloud-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense modernization budgets dwarf German commercial aviation training investments, while China's industrial policy accelerates domestic simulator capacity faster than India's manufacturing incentive schemes.
United States
FAA mandates for simulator-based pilot certification and Pentagon Synthetic Training Environment contracts drive procurement. ITAR regulations restrict military simulation exports to allied nations. Orlando's Central Florida Research Park hosts the densest cluster of defense training contractors, where primes integrate fighter jet simulators with live-virtual-constructive architectures.
Germany
Lufthansa Aviation Training operates Europe's largest full-flight simulator fleet for airline type-rating certification. EU AI Act transparency requirements reshape procurement evaluation for adaptive aviation training algorithms. The Hamburg-Cologne corridor concentrates maritime bridge simulator manufacturing for STCW-compliant officer training.
China
MIIT GB standards for VR hardware interoperability govern industrial training deployments across state-owned manufacturing enterprises. Dual carbon goals accelerate energy-efficient simulator adoption to replace live-fire military exercises. The Yangtze River Delta cluster in Shanghai-Nanjing anchors domestic flight simulator assembly lines serving COMAC and military aviation programs.
India
Production-Linked Incentive scheme recipients in automotive and electronics manufacturing generate demand for VR-based equipment familiarization. CEA guidelines for industrial power infrastructure constrain motion platform deployment to established manufacturing zones. Tamil Nadu's Sriperumbudur-Oragadam belt sees rapid simulator adoption for pre-production assembly line validation.
United Kingdom
Royal Air Force synthetic training contracts prioritize networked collective mission rehearsal systems. Health and Safety Executive regulations mandate competency verification through simulation for high-risk industrial operations. The Bristol-Bath corridor hosts specialist firms developing haptic feedback systems for surgical training export markets.
Global Virtual Training and Simulation Market Competitive Landscape
North American primes anchor the defense tier; European specialists hold commercial aviation and land systems niches. Market structure concentrates around platform-integrated military suppliers and full-flight simulator OEMs with airline operator partnerships. Two archetypes dominate: captive defense integrators with classified program access, and independent training service providers with modular content libraries. Competitive moves center on sovereign capability partnerships and after-sales service unbundling.
Within the defense integrator tier, Lockheed Martin Corporation and Rheinmetall AG exemplify contrasting geographic anchoring strategies. CAE Inc. occupies a distinctive position bridging commercial aviation certification requirements with military platform training. These three entities represent the spectrum from captive aerospace primes through independent training specialists, illustrating how regulatory divergence between ITAR-controlled and EU open-architecture procurement reshapes competitive positioning.
| Leading Market Players |
|---|
| CAE Inc. |
| Rheinmetall AG |
| Lockheed Martin Corporation |
| Saab AB |
| Cubic Corporation |
| Thales Group |
| Collins Aerospace |
| L3Harris Technologies Inc. |
| BAE Systems |
| Others |
Supply & Pricing Matrix
Dual carbon goals in China are tightening energy-efficiency standards for motion platform manufacturing, gating supplier qualification for premium-tier simulator contracts and compressing margins for legacy full-flight simulator OEMs unable to retool power systems.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for micro-OLED display subsystems, forcing Western headset manufacturers toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FAA certification tier and after-sales service bundling, with airline training centers showing acute price sensitivity on hardware while military buyers prioritize physics fidelity over unit cost. Cost compression in the corporate VR training tier is intensifying because cloud-rendering alternatives eliminate local compute requirements.
Supply Chain Analysis
Dual-sourcing requirements from U.S. defense primes are fragmenting component procurement across domestic and allied supplier bases. Manufacturing concentrates in China, South Korea, and Japan for display panels, motion actuators, and haptic feedback arrays. The supply chain draws from rare earth magnet feeds for hexapod motors and specialized aluminum alloys for simulator cockpit structures. Single-source vulnerability in pancake lens optics exposes OEMs to export restriction risk. Distribution runs through prime contractor integration facilities for defense and direct OEM sales for commercial aviation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cloud-based deployment shifts that eliminate motion platform hardware for mid-tier training segments, capturing premium pricing for sovereign-capability defense contracts.
For Market Incumbents: Acquire haptic instrumentation specialists to secure force-feedback IP before medical residency programs consolidate vendor relationships. Defense primes must anchor simulator source code development in ITAR-compliant facilities to preempt allied nation indigenous build-out. Lockheed Martin and Rheinmetall demonstrate captive integration with fighter platforms as the defensive standard. For New Entrants and Emerging Players: Cloud-based streaming architectures open white-space in distributed corporate training where CAE and L3Harris maintain limited presence. India's PLI scheme recipients in Tamil Nadu represent the most penetrable manufacturing training segment. A compliance-focused go-to-market angle targeting EU AI Act documentation gaps at European aviation academies bypasses incumbent service bundling. For Investors and Strategic Acquirers: Roll-up economics work for independent software content libraries because airline consolidation has fragmented long-term support contracts into modular procurement. Target firms with established FAA certification pathways and existing airline operator relationships. Watch for Pentagon Synthetic Training Environment contract awards as the signal for defense-tier capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CAE's full-flight simulator manufacturing anchors airline partnerships through hardware-software bundling. |
| Acquisition of Specialist Firm | Haptic feedback system purchases secure tissue modeling IP for ACGME-accredited surgical training programs. |
| Strategic Partnership | Rheinmetall's NATO armored vehicle crew training contracts require sovereign capability co-development agreements. |
| Product Launch | Mixed Reality maritime bridge systems reduce simulator footprint for Singapore and Rotterdam academy certification. |
| Geographic Expansion | India's PLI scheme drives VR equipment familiarization demand across automotive assembly lines in Karnataka. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with flight training center operators, defense procurement officers, medical residency program directors, and simulator OEM engineering leads alongside secondary validation through FAA regulatory filings, EASA certification databases, EU AI Act implementation guidance, and MIIT GB standard publications. Bottom-up segment sizing triangulates against top-down defense budget allocation and commercial aviation training spend estimates.
Rate-of-change decomposition separates volume drivers from price mix effects across the analysis window. Segmentation dimensions include technology tier, application vertical, end-user industry concentration, and deployment mode complexity. CAGRs derive from fitted growth curves against historical procurement cycle patterns and regulatory mandate implementation timelines. Physics-based modeling advancement rates and cloud-rendering adoption curves constitute simulator-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for Mixed Reality hardware cost reduction would alter the outlook. Forecasts reflect assumptions regarding FAA mandate enforcement consistency and ITAR regulation stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Professional Development and Training
Europe Leadership Development Program Market
Professional Development and Training
Coding Bootcamp Market
Professional Development and Training
Equipment Maintenance Training Services Market
Professional Development and Training
United States Executive Education Program Market
Professional Development and Training
Personal Development Market
Professional Development and Training
Firefighter Simulator Training Services Market
Professional Development and Training
Technical and Vocational Education Market
Professional Development and Training
Executive Education Program Market
Professional Development and Training
United States Soft Skills Training Market
Professional Development and Training
Europe Soft Skills Training Market
Professional Development and Training
Business Coaching Service Market
Professional Development and Training
GCC Soft Skills Training Market
Professional Development and Training
Canada Executive Education Program Market
Professional Development and Training
Executive Coaching and Leadership Development Market
Professional Development and Training
North America IT Training Market
Professional Development and Training
HR Professional Services Market